
 Spain Location-Based Services Market | 2026-2036
Spain Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Location-Based Services Market Insights
Tourism and retail applications are expanding within Spain's location-based services ecosystem, drawing investment toward real-time visitor analytics and personalized engagement platforms. HERE Technologies leverages its mapping heritage to dominate automotive and logistics segments across Iberian transport corridors. Google sustains competitive pressure through its Android location stack and Google Maps Platform services embedded in Spanish consumer applications. Esri specializes in geographic information system analytics, serving public sector smart city initiatives in Barcelona and Valencia.
Location-based services encompass software and hardware systems that determine device or object position through satellite triangulation, wireless signal mapping, or proximity sensing, then deliver contextual information or trigger automated actions based on that spatial data. GPS technology maintains foundational status for outdoor navigation and fleet coordination, though Wi-Fi positioning and Bluetooth beacons are displacing satellite dependency in dense urban and indoor environments where signal occlusion limits accuracy. Cloud-based deployment leads current infrastructure preferences among Spanish enterprises seeking elastic scaling for seasonal tourism traffic, while edge computing architectures are gaining traction in latency-sensitive autonomous vehicle and industrial safety applications where millisecond response times prove critical.
Spain's national data protection authority, the AEPD, enforces GDPR-mandated consent frameworks that directly constrain how location data is harvested, stored, and monetized by service providers. The EU AI Act adds algorithmic transparency obligations for automated geofencing and predictive location analytics, compelling vendors to document decision logic and risk classifications. Stakeholders must monitor evolving interoperability standards between national digital identity systems and location platforms, as Spain's eIDAS implementation creates both compliance thresholds and integration opportunities for cross-border service authentication.
Market Dynamics
Spain's location-based services sector faces acute pressure from the EU AI Act's algorithmic transparency mandates, which compel vendors to document decision logic for automated geofencing and predictive analytics systems. The AEPD's concurrent enforcement of GDPR consent frameworks for geolocation data processing creates a dual compliance burden that is restructuring vendor operating models.
Growth Catalysts
- Smart city infrastructure:Barcelona and Madrid are deploying beacon networks and Wi-Fi positioning systems for real-time visitor analytics. Municipal procurement is accelerating across urban transport hubs and cultural venues.
- AEPD regulatory clarity:Spain's data protection authority has issued sector-specific guidance on geolocation consent mechanisms. This reduces legal uncertainty for service providers designing compliant data collection architectures.
- Bluetooth Low Energy maturation:Indoor positioning accuracy improvements are displacing GPS dependency in retail environments. Spanish department stores and shopping centers are integrating proximity marketing platforms.
Market Restraints
- Silicon supply concentration:Positioning chipset fabrication concentrates in East Asian foundries. Spanish system integrators face extended lead times and input cost volatility for beacon and sensor hardware.
- EU AI Act compliance costs:Algorithmic documentation and risk classification obligations impose fixed overhead on predictive location analytics vendors. Mid-tier providers lack resources for dedicated regulatory functions.
- Wi-Fi signal occlusion:Dense urban architecture in historic Spanish city centers degrades positioning accuracy. Satellite-independent technologies struggle in environments with thick masonry construction.
Strategic Opportunities
- Andalusian tourism digitization:Seville and Granada lag Barcelona and Madrid in beacon deployment. Regional government smart tourism initiatives are creating procurement channels for visitor engagement platforms.
- eIDAS integration:Spain's digital identity infrastructure convergence with location authentication creates cross-border service verification opportunities. Vendors can bundle spatial verification with identity assurance for financial services.
- Edge computing convergence:Millisecond-latency requirements in autonomous vehicle testing zones around Barcelona are driving hybrid cloud-edge architectures. Industrial safety applications follow similar deployment patterns.
Industry Challenges
- Embedded systems engineering scarcity:Spanish universities produce insufficient firmware developers with radio-frequency optimization skills. Vendors compete for talent capable of tuning Wi-Fi and Bluetooth positioning algorithms.
- Legacy municipal IT integration:City council data systems in secondary Spanish urban centers use incompatible protocols. Location platform vendors must build custom middleware for each deployment.
- AEPD audit timelines:Geolocation data processing authorization reviews extend 8-14 months. Product launch schedules compress against regulatory approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Location-Based Services Market |
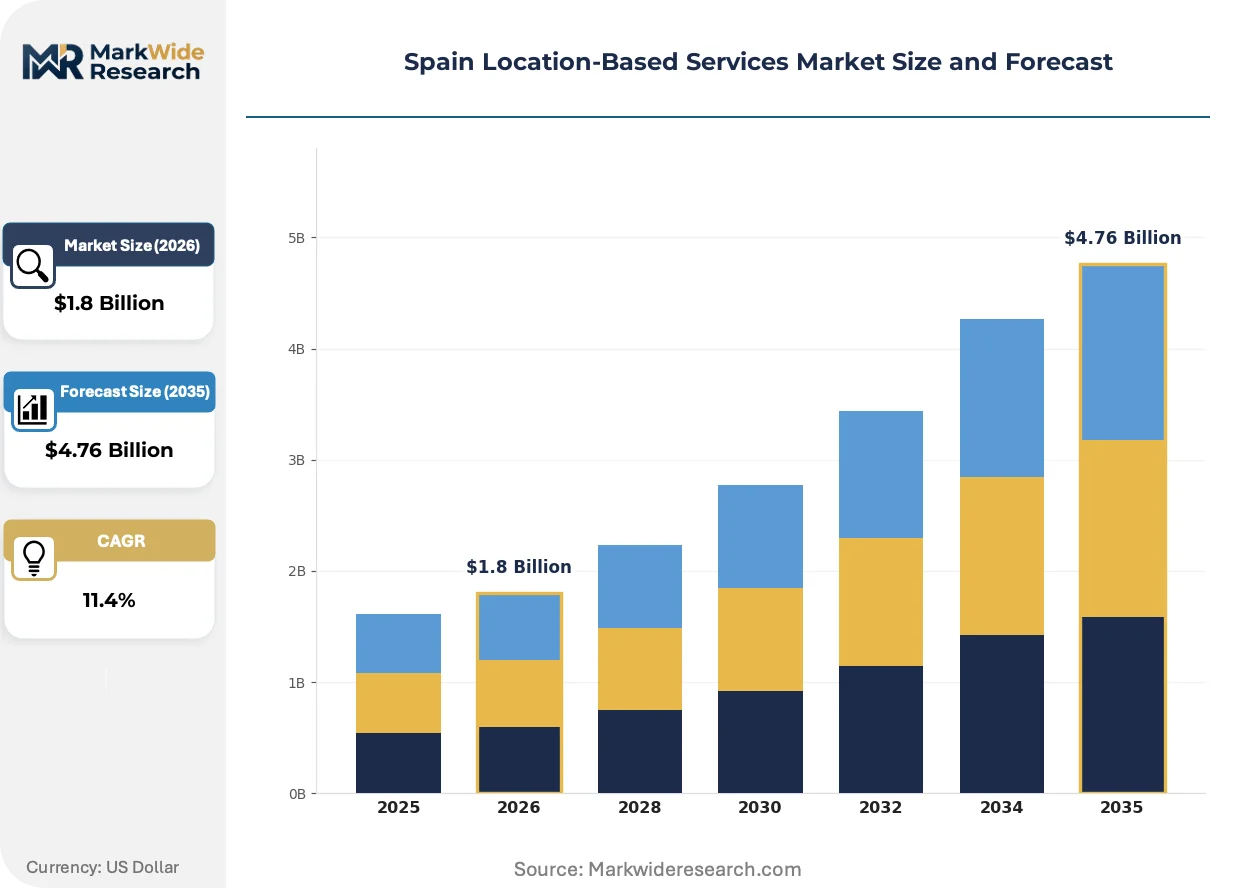
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Navigation, Advertising, Fleet Management, Travel Technology: GPS, Wi-Fi Positioning, Beacons, RFID End User: Retail, Transportation, Healthcare, Tourism Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | ALE International, Cisco Systems, Ericsson, Esri, Aruba Networks, HERE Technologies, Google, IBM, Qualcomm Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Location-Based Services Market Trends and Innovations
Spanish location-based services are undergoing architectural transformation as edge computing and privacy-preserving computation reshape how spatial data is processed. Three interconnected developments are altering competitive positioning and procurement patterns.
Ultra-wideband positioning is modularizing indoor navigation infrastructure across Spanish retail and logistics facilities. The technology delivers centimeter-level accuracy for asset tracking and proximity marketing. Major Spanish supermarket chains are piloting shelf-level customer journey mapping. Modular deployment allows incremental capability expansion without full infrastructure replacement.
The EU AI Act's risk-based classification system is imposing documentation burdens on automated geofencing applications. High-risk systems must maintain technical files and human oversight protocols. Spanish predictive analytics vendors serving insurance and automotive segments are restructuring product architectures to meet conformity assessment requirements. Legal engineering functions are expanding within vendor organizations.
Tourism boards in Valencia and Bilbao are consolidating visitor data procurement through centralized smart destination platforms. Municipal agencies previously bought point solutions from fragmented vendor bases. Aggregated demand is compressing supplier margins while raising performance requirements for real-time analytics throughput. Platform contracts now specify sub-second latency for crowd density alerts.
Spain Location-Based Services Market Segmentation
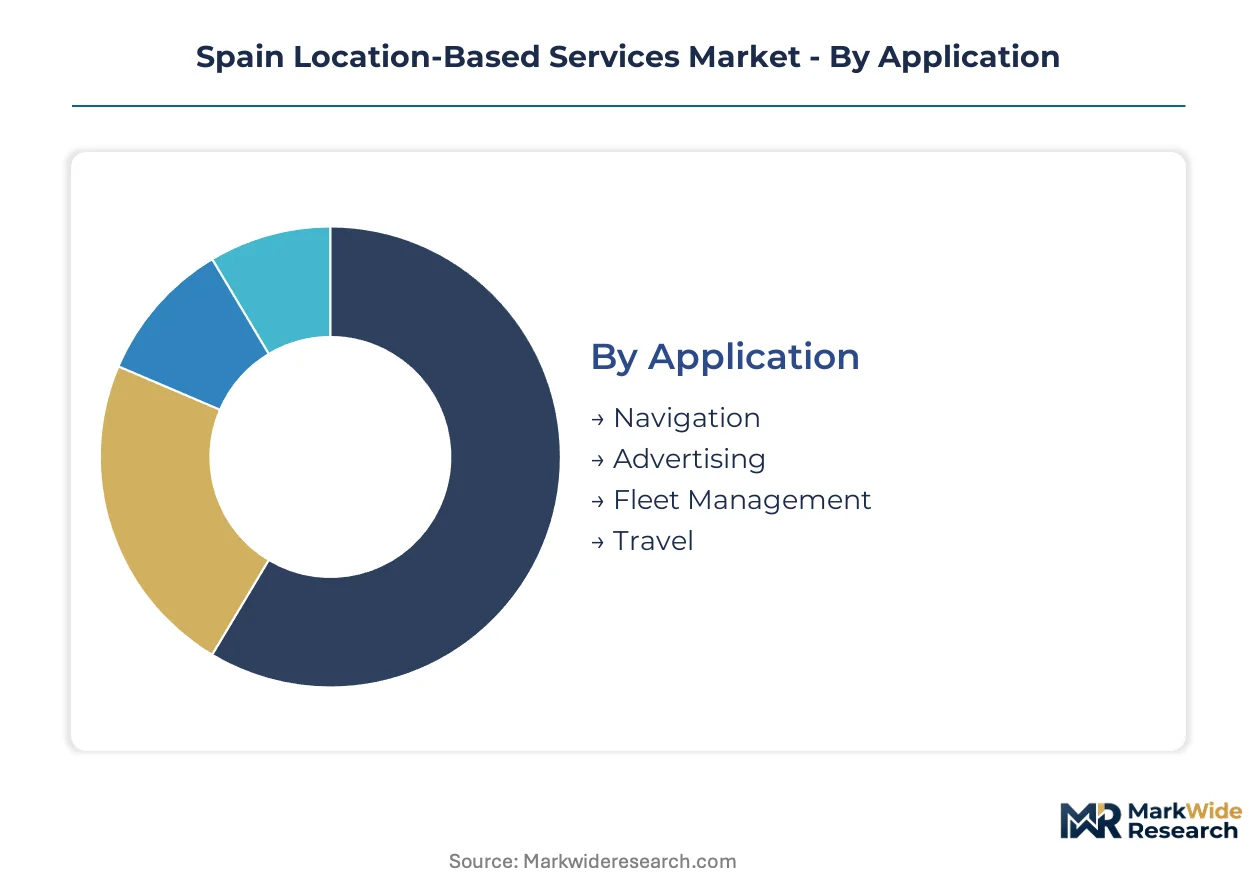
Spain's location-based services market fragments across four structural dimensions that determine procurement patterns and vendor competitive positioning. Application requirements vary sharply between real-time navigation and predictive fleet analytics, while technology choices reflect trade-offs between GPS accuracy and beacon density in urban environments.
Application:
Buyers in this category differentiate by latency tolerance and data granularity requirements, with automotive and logistics procurement demanding sub-second response times while tourism applications prioritize historical pattern analysis.
- Navigation:Satellite-dependent routing systems dominate automotive OEM contracts and logistics fleet coordination across Iberian transport corridors. Barcelona and Madrid municipal procurement is accelerating for multimodal urban navigation integrating public transit with pedestrian wayfinding.
- Advertising:Proximity-triggered engagement platforms leverage beacon networks and geofenced zones for retail customer acquisition. Spanish department store chains are consolidating procurement through centralized martech stacks that bundle location intelligence with loyalty program integration.
- Fleet Management:Real-time vehicle tracking and route optimization for trucking and delivery operations.
- Travel:Visitor experience platforms and destination recommendation engines for tourism boards.
Navigation leads volumes today; Advertising is gaining share fastest.
Technology:
Technology selection in Spanish deployments tracks infrastructure maturity and signal environment characteristics, with dense urban centers favoring terrestrial alternatives to satellite occlusion.
- GPS:Satellite triangulation remains foundational for outdoor navigation and long-haul fleet tracking despite signal degradation in urban canyons. Spanish logistics operators maintain hybrid architectures that fall back to cellular positioning when satellite lock degrades.
- Wi-Fi Positioning:Signal mapping of access point fingerprints enables indoor navigation where GPS fails. Madrid Metro and Barcelona transit authority deployments are driving standardization of Wi-Fi RTT protocols for sub-meter platform positioning.
- Beacons:Bluetooth Low Energy transmitters for proximity detection and micro-location marketing.
- RFID:Passive and active radio-frequency identification for asset tracking and access control.
GPS anchors current infrastructure investment; Wi-Fi Positioning shows the steepest expansion trajectory.
End User:
End user procurement patterns diverge by regulatory exposure and data sensitivity, with healthcare and finance verticals imposing stricter consent architectures than retail or tourism implementations.
- Retail:Proximity marketing and indoor positioning for customer journey analytics. Spanish supermarket chains are piloting shelf-level tracking while navigating AEPD consent requirements for geolocation data collection.
- Transportation:Fleet coordination, multimodal routing, and autonomous vehicle testing infrastructure. Barcelona's autonomous driving zones are driving edge computing procurement for millisecond-latency positioning.
- Healthcare:Patient tracking and medical equipment location systems for hospital operations.
- Tourism:Visitor analytics and personalized destination services for municipal smart tourism platforms.
Transportation commands the largest procurement budgets; Tourism is climbing the fastest as regional governments digitize visitor economies.
Deployment:
Deployment architecture choices reflect data sovereignty requirements and latency constraints, with financial services and public sector buyers favoring on-premises or hybrid models over pure cloud.
- Cloud-Based:Elastic infrastructure for seasonal tourism traffic spikes and retail campaign bursts. Spanish hospitality platforms leverage auto-scaling to handle summer visitor volume without permanent overprovisioning.
- On-Premises:Dedicated hardware for sensitive healthcare patient tracking and defense applications where data residency is non-negotiable.
- Hybrid:Split architectures processing raw positioning at edge nodes while aggregating analytics in central cloud repositories.
- Edge Computing:Millisecond-latency processing for autonomous vehicle testing and industrial safety systems requiring immediate geofence enforcement.
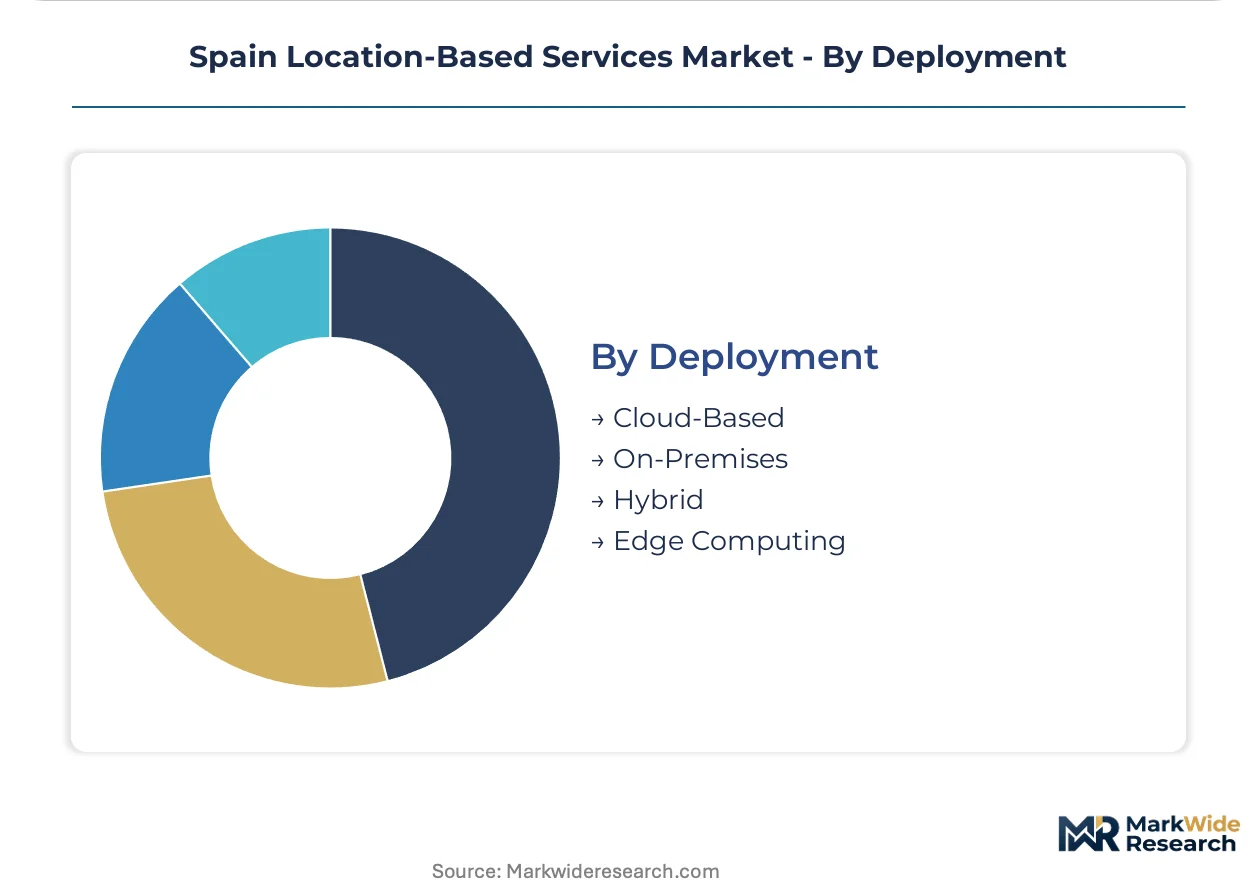
Cloud-Based deployments dominate current vendor revenue; Edge Computing is expanding most quickly around Barcelona's autonomous vehicle corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment patterns across Spain's autonomous communities as the AEPD's geolocation consent frameworks create compliance cost differentials between sub-regions with varying enforcement intensity.
Madrid
Madrid concentrates smart city procurement through its municipal digital services agency, deploying beacon networks across Atocha and Chamartín transport hubs. The regional government's Data Protection Delegation coordinates with AEPD on geolocation consent guidance. Edge computing clusters in the Madrid-Barcelona corridor support autonomous vehicle testing infrastructure with sub-10 millisecond latency requirements.
Catalonia
Barcelona's Superblock urban planning integrates Wi-Fi positioning for pedestrian flow optimization and emergency response routing. The Catalan Data Protection Authority enforces GDPR supplements that exceed national baselines for location data retention. The 22@ innovation district hosts HERE Technologies and Esri development centers serving Iberian logistics corridors.
Basque Country
Bilbao's port authority deploys ultra-wideband asset tracking for container logistics, generating procurement demand for industrial-grade positioning systems. The Basque Cybersecurity Centre audits location data processing under regional critical infrastructure frameworks. San Sebastián's smart tourism platform aggregates visitor analytics from provincial museum networks and coastal attractions.
Andalusia
Seville and Granada municipal tourism boards are consolidating beacon procurement through the Junta de Andalucía's smart destination program. Regional data protection delegations apply AEPD guidance with extended consultation periods for geolocation consent architectures. Málaga's Costa del Sol corridor is piloting proximity marketing platforms in duty-free retail zones.
Valencia
Valencia's port and airport authority coordinates multimodal positioning systems for cruise passenger navigation. The regional government's digital strategy office mandates interoperability standards between municipal location platforms. The Albufera smart tourism cluster deploys environmental sensors with geofenced visitor alerts for protected wetland zones.
Spain Location-Based Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with infrastructure vendors dominating municipal procurement while platform specialists capture recurring SaaS revenue from retail and tourism applications. The vendor base concentrates around three strategic archetypes: mapping heritage players with automotive OEM relationships, cloud-native platform providers leveraging Android ecosystem penetration, and geographic information system specialists serving public sector analytics. Competitive moves center on edge computing partnerships for latency-sensitive deployments and regulatory compliance bundling to address AEPD audit requirements.
Within the mapping and automotive tier, HERE Technologies and Esri occupy anchor positions, with the former exemplifying infrastructure-scale deployment capabilities and the latter representing public sector GIS analytics specialization. Google sits within the consumer platform archetype, leveraging its Android location stack penetration across Spanish mobile applications. Among networking infrastructure providers, Cisco Systems and Ericsson represent the enterprise-grade hardware and connectivity layer that underpins beacon and Wi-Fi positioning deployments in urban environments.
| Leading Market Players |
|---|
| ALE International |
| Cisco Systems |
| Ericsson |
| Esri |
| Aruba Networks |
| HERE Technologies |
| IBM |
| Qualcomm Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive chip sourcing from East Asian foundries anchors vendor cost structures while constraining pricing flexibility for Spanish system integrators. HERE Technologies and Esri leverage in-house mapping data pipelines to command premium positioning in automotive and public sector procurement, whereas mid-tier beacon vendors absorb margin compression from silicon input volatility.
Pricing Analysis
Distributor margins on BLE beacon hardware compress under procurement consolidation by Spanish retail chains. SaaS-tiered subscription models dominate visitor analytics platforms, with pricing stratifying across premium, standard, and economy tiers based on data granularity and AEPD compliance bundling. Municipal buyers exhibit lowest price sensitivity due to budget cycle insulation, while mid-market retail chains drive hardest bargain on per-node beacon costs. Cost compression in hardware tiers is intensifying because foundry allocation prioritizes automotive chip demand.
Supply Chain Analysis
Radio-frequency engineering talent scarcity in Spanish universities extends firmware development timelines for positioning algorithm vendors. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with BLE chipset supply drawing from TSMC and Samsung foundry capacity. UWB module assembly rests on Chinese contract manufacturers. Single-source vulnerability in 5G positioning chipsets exposes Spanish integrators to allocation rationing. Distribution runs through Madrid-based electronics distributors serving Iberian system integrators and municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Catalonia's stricter GDPR supplements and Andalusia's extended AEPD consultation periods creates compliance cost differentials for vendors optimizing geographic deployment sequencing.
For Market Incumbents: Extend edge computing partnerships with Barcelona autonomous vehicle test zones to lock in latency-sensitive procurement before platform standardization solidifies. Acquire firmware development capabilities in Portugal or Eastern Europe to offset Spanish RF engineering scarcity. HERE Technologies faces emerging pressure from Google Maps Platform pricing aggression in retail navigation contracts. For New Entrants and Emerging Players: Enter via Seville and Granada municipal tourism digitization programs, where beacon infrastructure penetration lags Madrid and Barcelona by 3-4 deployment cycles. White-space exists in shelf-level customer journey analytics for mid-size Spanish supermarket cooperatives. Go-to-market through Junta de Andalucía consolidated procurement channels reduces customer acquisition friction. For Investors and Strategic Acquirers: Roll-up economics work for GIS analytics specialists because municipal smart city procurement is consolidating from fragmented point solutions to integrated platform contracts. Target firms with existing AEPD audit clearance and Barcelona or Madrid reference deployments. Watch for EU AI Act conformity assessment completion as inflection signal for predictive analytics vendor viability.| Strategic Initiative | Industry Significance |
|---|---|
| AEPD Compliance Bundling | Packaging audit-ready documentation with platform sales accelerates municipal procurement cycles in Spain. |
| Edge Computing Partnership | Collaboration with Barcelona autonomous zones secures millisecond-latency positioning contracts. |
| Ultra-Wideband Module Launch | Centimeter-accuracy shelf tracking opens Spanish retail pilot budgets currently held by camera analytics. |
| eIDAS Integration Development | Spatial verification bundled with digital identity creates cross-border financial services revenue. |
| Andalusian Geographic Expansion | Seville and Granada smart tourism procurement channels offer first-mover positioning before consolidation. |
Research Methodology
Multiple input streams — municipal procurement databases, AEPD regulatory filings, and vendor technical documentation — were reconciled against primary interviews with smart city project managers, retail IT directors, beacon hardware procurement leads, and geographic information system specialists. Secondary validation drew from EU AI Act implementation guidance, Spanish Data Protection Authority sector bulletins, Barcelona and Madrid municipal digital strategy reports, and hyperscaler location platform disclosures. Bottom-up deployment counts triangulated against top-down market sizing from infrastructure investment flows.
Historical deployment trajectories in Barcelona's 22@ district and Madrid's transport hub beacon networks were cross-referenced against expert panel assessments of Andalusian and Basque Country expansion timelines. Segmentation modeling covered application type, positioning technology, end-user vertical, and deployment architecture across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves incorporating AEPD regulatory lag effects and tourism seasonality patterns.
Inputs from Spanish municipal procurement portals and regional data protection delegations were available through the study window; gaps in real-time beacon deployment counts for secondary urban centers introduce uncertainty bands around mid-market sizing. Forecasts reflect assumptions on EU AI Act enforcement intensity and foundry capacity allocation continuity. Material deviation in AEPD audit timeline compression or East Asian semiconductor export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market