
 Italy Geospatial Analytics Market | 2026-2036
Italy Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Geospatial Analytics Market Insights
The EU Green Deal's digital twin mandates for built-environment monitoring is realigning procurement priorities across Italian infrastructure agencies. Hexagon AB dominates geospatial software licensing through its measurement sensor integration. GEODATA SpA anchors underground mapping services for tunnel and mining clients throughout the Alpine arc. Latitudo 40 S.r.l. specializes in satellite imagery analytics for agricultural compliance reporting.
Geospatial analytics encompasses the computational processing of location-referenced data through coordinate-based algorithms, spectral classification, and spatial statistics to extract patterns from satellite, aerial, and ground-based sensor networks. Its primary commercial purpose is to transform raw positional information into actionable intelligence for asset tracking, risk assessment, and resource optimization. Remote sensing technology leads technology investment as defense and climate adaptation budgets expand spectral resolution requirements. Cloud-based deployment is capturing the fastest expansion as ANAFI-compliant agencies migrate from legacy on-premises systems. Real estate end users represent concentrated margin pools where cadastral modernization drives recurring subscription revenue.
Italy's national geospatial framework operates under EU INSPIRE directives, with ISPRA enforcing metadata standards for public-sector spatial data infrastructure. The EU AI Act introduces algorithmic transparency requirements for automated geospatial classification systems used in sensitive zones. Stakeholders must monitor how CE-marking obligations for geospatial hardware interface with emerging cybersecurity certification schemes.
Market Dynamics
The EU Green Deal's digital twin mandates are forcing Italian infrastructure agencies to replace legacy CAD workflows with real-time geospatial platforms, compressing procurement cycles and reshaping vendor qualification criteria across the peninsula.
Growth Catalysts
- EU AI Act compliance deadlines:Automated geospatial classification systems for sensitive zones now require algorithmic transparency documentation, creating upgrade demand from public-sector spatial data infrastructure operators.
- Alpine tunneling activity:Underground construction projects across the Alpine arc require sub-meter accuracy for geological risk mapping, pulling investment into ground-penetrating radar and LiDAR integration.
- Lombardy smart city integration:Municipal operators in Milan's metropolitan corridor embed satellite-derived analytics into traffic management and utility monitoring, normalizing recurring SaaS procurement.
Market Restraints
- Spectral sensor import dependency:High-resolution imaging components for defense-grade applications concentrate among non-EU suppliers, exposing procurement to tariff volatility and export control friction.
- ANAFI migration costs:Cloud-based deployment requires legacy on-premises system decommissioning, imposing capital intensity on regional agencies with frozen IT budgets.
- Interoperability fragmentation:ISPRA metadata standards interface unevenly with municipal data formats, forcing redundant data transformation layers that inflate project timelines.
Strategic Opportunities
- Sicily agricultural compliance gap:Satellite imagery analytics for CAP subsidy verification remains underdeployed across southern regions, offering first-mover positioning for precision agriculture platforms.
- CE-marking cybersecurity convergence:Emerging hardware certification schemes for geospatial sensors create bundled service opportunities combining physical device compliance with data protection protocols.
- Hybrid edge-cloud architectures:Convergence of on-device processing with centralized analytics enables real-time infrastructure monitoring for high-frequency grid operators without full cloud dependency.
Industry Challenges
- Geomatics talent scarcity:Universities produce insufficient graduates trained in coordinate-based algorithms and spectral classification, forcing employers to poach from adjacent surveying disciplines.
- Legacy system integration complexity:Municipal operators maintain decades-old cadastral databases that resist API-based connectivity, requiring custom middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Geospatial Analytics Market |
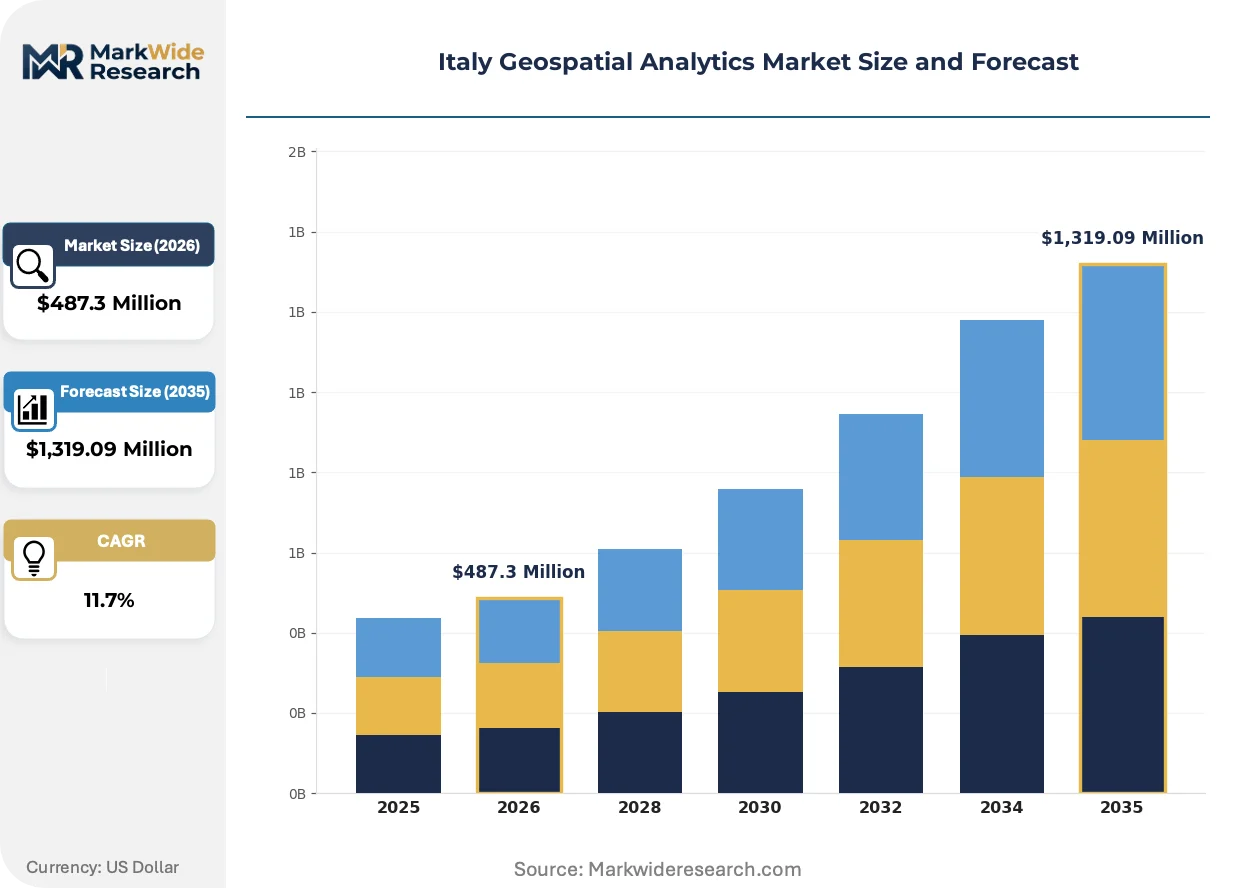
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Transportation Management, Environmental Monitoring, Disaster Response Technology: GIS Software, Database Management, Remote Sensing, Spatial Analysis End User: Government Agencies, Transportation Services, Energy Sector, Real Estate Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Fugro N.V., GEODATA SpA, Hexagon AB, Flypix AI GmbH, Latitudo 40 S.r.l., ESRI Italia S.r.l., e-Geos S.p.A., Telespazio S.p.A., Trimble Italy S.r.l., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Geospatial Analytics Market Trends and Innovations
Italian geospatial markets are pivoting from static mapping deliverables toward continuous monitoring subscriptions, with platform vendors embedding machine learning pipelines directly into sensor hardware to compress insight latency.
AI-powered feature extraction from satellite imagery is automating cadastral boundary detection and informal construction identification. Regional tax authorities in Veneto and Emilia-Romagna deploy these tools at scale, replacing manual photointerpretation. The technology is automating compliance verification workflows that previously required months of field survey, collapsing enforcement cycles to weeks.
EU Green Deal built-environment monitoring mandates now require digital twin coverage for all major infrastructure assets by 2030. Italian agencies must procure platforms capable of fusing aerial, satellite, and ground sensor feeds into unified 4D models. Tunnel operators and port authorities face the steepest compliance cliffs, driving concentrated RFP activity through 2027.
Subscription pricing for geospatial analytics is displacing perpetual license models across municipal procurement. Lombardy regional government standardized SaaS-based terrain monitoring, forcing vendors to absorb infrastructure costs and compete on usage-based tiers. The shift concentrates vendor risk in data storage and compute scaling while transferring capex burden from public budgets to private balance sheets.
Italy Geospatial Analytics Market Segmentation
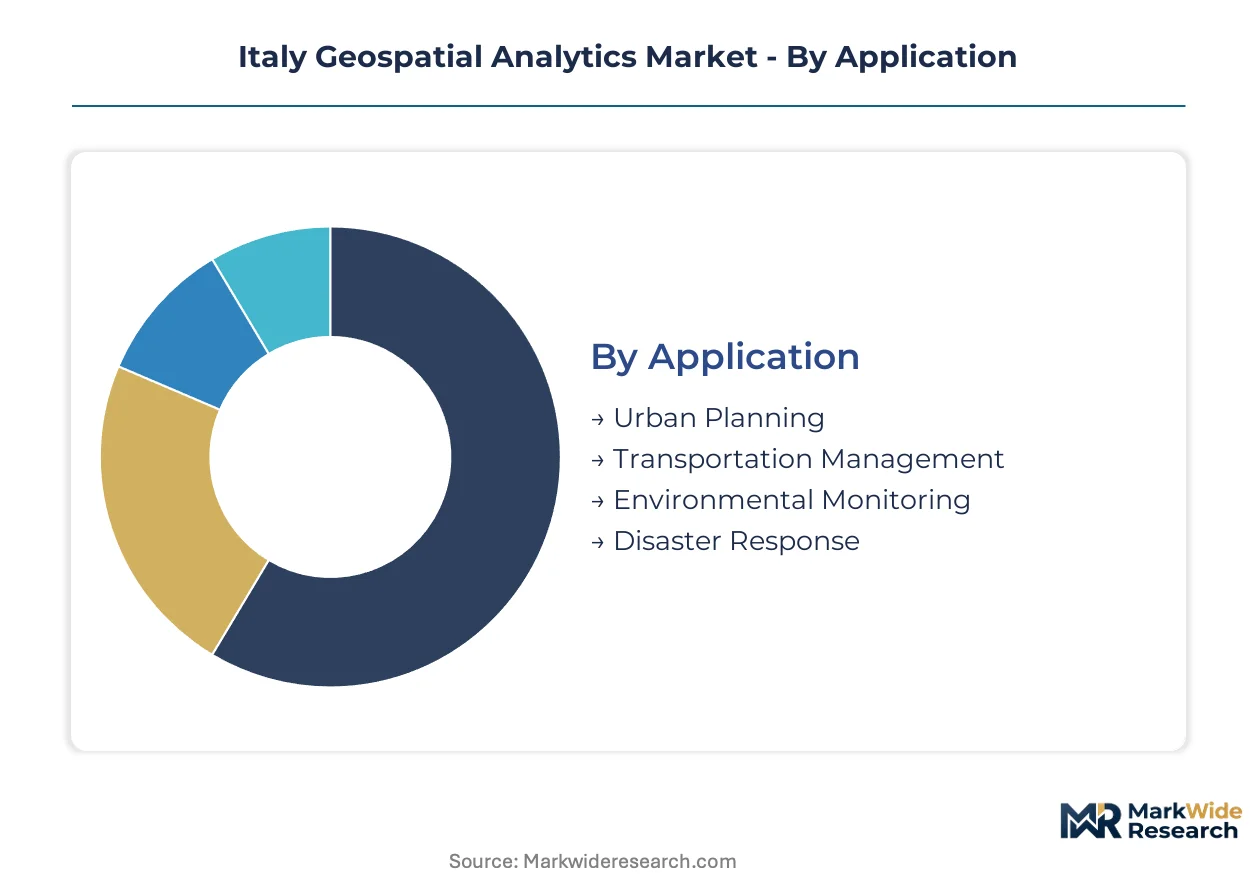
Italian procurement patterns diverge sharply across application contexts, with infrastructure agencies prioritizing compliance-ready platforms while commercial operators seek modular, API-first architectures. Technology selection increasingly hinges on ANAFI migration status and EU AI Act algorithmic transparency requirements.
Application:
Urban operators distinguish themselves by cadastral modernization urgency, while environmental agencies prioritize spectral resolution for regulatory reporting.
- Urban Planning:Municipal digitization of zoning overlays and construction permitting workflows drives concentrated demand in Lombardy and Veneto metropolitan corridors. Milan's metropolitan government embeds satellite-derived analytics into master plan updates, collapsing traditional survey cycles.
- Environmental Monitoring:ISPRA mandates for ecosystem health tracking pull investment into multi-spectral classification systems for wetland and coastal zone assessment. Alpine regional authorities deploy these tools for glacial retreat documentation under EU Green Deal reporting obligations.
- Transportation Management:Traffic flow optimization and infrastructure condition monitoring for Autostrade per l'Italia networks.
- Disaster Response:Post-seismic building damage assessment and landslide early warning systems for Civil Protection Department coordination.
Volume sits with Urban Planning; growth tilts toward Environmental Monitoring.
Technology:
Buyer sophistication separates legacy CAD-dependent agencies from cloud-native operators seeking real-time sensor fusion.
- Remote Sensing:Defense and climate adaptation budgets are expanding spectral resolution requirements for satellite and aerial imaging platforms. Italian utility operators deploy these systems for grid infrastructure thermal monitoring across the Alpine arc.
- GIS Software:Measurement sensor integration platforms dominate licensing revenue as infrastructure agencies replace static mapping with dynamic spatial databases. Hexagon AB's entrenched position in geomatics education creates switching friction for municipal buyers.
- Spatial Analysis:Machine learning pipelines for automated feature extraction and predictive terrain modeling.
- Database Management:Metadata standardization tools for INSPIRE-compliant spatial data infrastructure.
Revenue concentrates in GIS Software; capability investment flows fastest into Remote Sensing.
End User:
Budget autonomy and procurement cycle length separate centralized government tenders from decentralized commercial decisions.
- Government Agencies:ISPRA and regional spatial data infrastructure operators drive standardization-mandated procurement with multi-year framework agreements. EU Green Deal digital twin deadlines compress evaluation timelines for infrastructure asset monitoring platforms.
- Real Estate:Cadastral modernization and informal construction identification generate recurring subscription revenue as Veneto and Emilia-Romagna tax authorities automate compliance verification. AI-powered boundary detection collapses enforcement cycles from months to weeks.
- Energy Sector:Terna and distribution operators integrating geospatial analytics into grid resilience planning.
- Transportation Services:Port authorities and tunnel operators facing steepest EU digital twin compliance cliffs through 2027.
Contract value peaks with Government Agencies; margin expansion favors Real Estate.
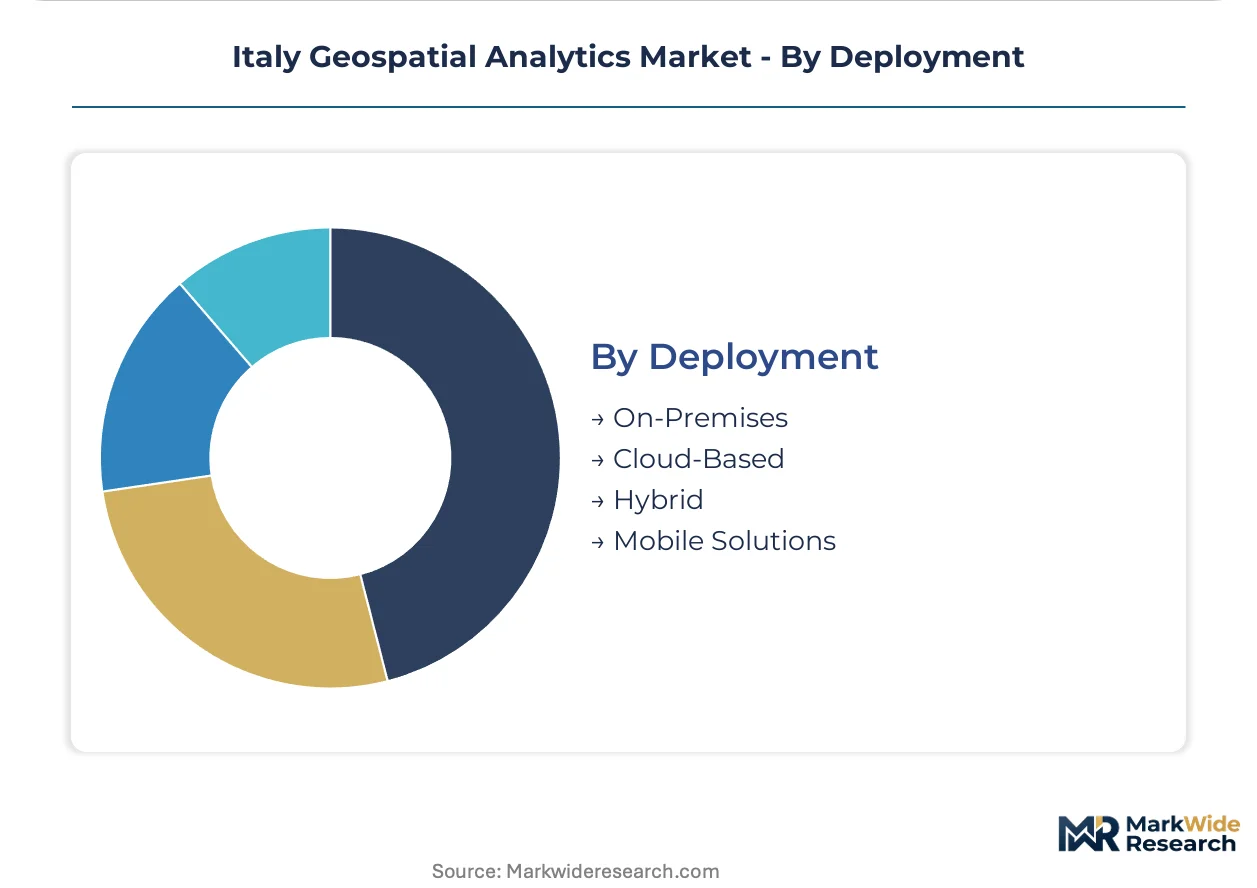
Deployment:
Data sovereignty requirements and legacy system entrenchment determine cloud migration pace across buyer types.
- Cloud-Based:ANAFI-compliant agencies are migrating from on-premises systems, transferring capex burden to vendor balance sheets through usage-based SaaS tiers. Lombardy regional government standardized this model for terrain monitoring procurement.
- Hybrid:Edge-cloud architectures enable real-time infrastructure monitoring for high-frequency grid operators without full dependency on centralized compute. Convergence of on-device processing with cloud analytics addresses latency-sensitive use cases.
- On-Premises:Defense-grade and sensitive zone applications requiring air-gapped security protocols.
- Mobile Solutions:Field survey crews and emergency response teams requiring offline-capable data collection.
Installed base remains On-Premises; subscription momentum concentrates in Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian geospatial production concentrates in northern industrial clusters while consumption spreads across infrastructure agencies nationwide. Lombardy generates disproportionate platform revenue through Milan's smart city procurement. Southern regions present agricultural compliance gaps that satellite analytics vendors now target.
Lombardy
Milan's metropolitan government embeds satellite-derived analytics into traffic management and utility monitoring workflows. EU Green Deal digital twin mandates compress procurement timelines for infrastructure asset monitoring platforms. The metropolitan corridor normalizes recurring SaaS subscriptions for terrain monitoring, transferring capex burden from public budgets to vendor balance sheets.
Piedmont
Alpine tunneling projects across the Susa Valley require sub-meter geological risk mapping accuracy. ISPRA metadata standards enforcement pulls investment into ground-penetrating radar and LiDAR integration for underground construction. Turin anchors specialized geomatics services for mining clients throughout the western Alpine arc.
Veneto
Regional tax authorities deploy AI-powered feature extraction for cadastral boundary detection and informal construction identification. Automated compliance verification collapses enforcement cycles from months to weeks. Padua and Verona clusters concentrate photogrammetry specialists serving the Po Valley agricultural belt.
Emilia-Romagna
Bologna's metropolitan government integrates geospatial platforms into construction permitting workflows. ANAFI-compliant agencies migrate from legacy on-premises systems toward cloud-based deployment models. The Po Delta wetland monitoring programs drive multi-spectral classification system procurement under EU ecosystem health tracking obligations.
Sicily
Satellite imagery analytics for CAP subsidy verification remains underdeployed across southern agricultural zones. Precision agriculture platforms find first-mover positioning opportunities in citrus and vineyard compliance reporting. Catania's emerging tech cluster attracts Earth observation startups targeting Mediterranean crop monitoring gaps.
Italy Geospatial Analytics Market Competitive Landscape
The competitive structure tilts toward measurement sensor integration specialists with entrenched positions in geomatics education. Hexagon AB dominates geospatial software licensing through decades of municipal buyer relationships. Three archetypes occupy distinct positions: European sensor-hardware conglomerates, Italian underground mapping specialists, and satellite imagery analytics boutiques. Consolidation pressure concentrates in cloud-platform capabilities as ANAFI migration forces legacy vendors toward acquisition or partnership.
Within the European conglomerate tier, Hexagon AB anchors measurement sensor integration through its entrenched licensing position. GEODATA SpA exemplifies the Italian underground mapping specialist archetype, serving tunnel and mining clients throughout the Alpine arc. Latitudo 40 S.r.l. occupies the satellite imagery analytics boutique position, focusing on agricultural compliance reporting. These three represent divergent strategic bets: hardware-software bundling versus vertical service specialization versus narrow AI-powered feature extraction.
| Leading Market Players |
|---|
| Fugro N.V. |
| GEODATA SpA |
| Hexagon AB |
| Flypix AI GmbH |
| Latitudo 40 S.r.l. |
| ESRI Italia S.r.l. |
| e-Geos S.p.A. |
| Telespazio S.p.A. |
| Trimble Italy S.r.l. |
| Others |
Pricing and Supply Chain Analysis
Geomatics talent scarcity in Turin's Polytechnic corridor widens pricing-tier spreads between premium sensor-integrated platforms and commodity SaaS offerings, compressing mid-market vendor margins as labor-cost differentials force tier stratification.
Pricing Analysis
Margin tightening in municipal SaaS tiers reflects ANAFI migration capex absorption by vendors competing for Lombardy framework agreements. Three-tier pricing structure across premium sensor-fusion, standard cloud-native, and economy on-premises levels separates buyers by compliance urgency and spectral resolution requirements. Cost-down pressure on hybrid deployments accelerates because edge-hardware vendors bundle compute subsidies to capture recurring analytics revenue. Regional agencies with frozen IT budgets exhibit highest price sensitivity; defense-grade operators with spectral upgrade mandates show lowest.
Supply Chain Analysis
EU Green Deal local-content thresholds for digital twin infrastructure are reshaping sourcing toward CE-marked sensor manufacturers in Germany, France, and domestic Italian producers. High-resolution imaging components for defense applications draw from Israeli, US, and limited European foundries. Single-source vulnerability concentrates in gallium arsenide detector substrates. Distribution runs through Hexagon AB's entrenched geomatics education channels and specialized Alpine surveying equipment dealers serving tunnel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geomatics talent scarcity props platform pricing as vendors compete for finite coordinate-algorithm specialists trained in spectral classification, creating supply-constrained vendor power.
For Market Incumbents: Cement sensor-hardware bundling advantages by acquiring cloud-native analytics boutiques before ANAFI migration peaks, insulating against modular API-first challengers eroding municipal maintenance contracts. Deepen backward integration into LiDAR component sourcing to reduce tariff exposure from non-EU spectral sensor suppliers. For New Entrants and Emerging Players: Municipal tax authorities in southern regions lacking cadastral automation present first-mover positioning for AI-powered boundary detection platforms priced below Hexagon AB's enterprise licensing. Target Sicily's CAP compliance gap with satellite-derived crop verification bundled with regional agronomy advisory services. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid edge-cloud architecture specialists given EU digital twin infrastructure deadlines forcing real-time monitoring procurement. Long-term viability favors vendors combining physical sensor compliance with data protection protocol bundling. Watch Lombardy SaaS procurement standardization as signal for subscription-model validation across Italian municipal markets.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Hardware Bundling | Hexagon AB's measurement integration creates switching friction for municipal buyers seeking seamless LiDAR-to-software workflows. |
| Cloud-Native Platform Acquisition | Legacy vendors acquire API-first boutiques to compress ANAFI migration timelines and absorb SaaS infrastructure costs. |
| Edge-Compute Partnership | Grid operators deploy on-device processing with centralized analytics to address latency-sensitive infrastructure monitoring without full cloud dependency. |
| Alpine Tunneling Specialization | GEODATA SpA anchors sub-meter geological risk mapping services throughout the Susa Valley underground construction corridor. |
| Agricultural Compliance Expansion | Latitudo 40 S.r.l. targets Sicily's underdeployed CAP verification with citrus and vineyard satellite analytics for southern market penetration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with geomatics platform engineers, ISPRA metadata standardization officers, municipal IT procurement managers, and Alpine tunneling project surveyors. Secondary validation drew from EU INSPIRE directive implementation reports, ANAFI compliance disclosure databases, and Lombardy regional government tender archives. Bottom-up segment sizing triangulated against top-down infrastructure spending projections.
Granularity-level modeling deployed application-by-technology matrices across urban planning, environmental monitoring, and disaster response use cases, with deployment-mode splits for cloud, hybrid, and on-premises architectures. CAGRs derived from spline-interpolated year-over-year expenditure patterns across the projection horizon. Industry-specific forecast inputs incorporated EU AI Act algorithmic transparency compliance deadlines and EU Green Deal digital twin coverage mandates for infrastructure assets.
Revisions become necessary when spectral sensor export controls tighten, ANAFI migration timelines accelerate, or ISPRA metadata standards shift. Forecasts reflect documented assumptions on public-sector IT budget trajectories and defense-grade imaging resolution upgrade cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
China Contact Center Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Latin America Location Analytics Market
Analytics
Global Cognitive Analytics Market
Analytics
Global AI Video Analytics Market
Analytics
Global Data Visualization Tools Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Crowd Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Legal Analytics Market
Analytics
Europe Crowd Analytics Market
Analytics
Data Visualization Market
Analytics
Pandemic Analytics Market
Analytics
Global People and HR Analytics Software Market