
 Geographic Information System (GIS) Software Market | 2026-2036
Geographic Information System (GIS) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Geographic Information System (GIS) Software Market Foresight
Geospatial analyst shortages across North America and Western Europe are reorganizing how vendors structure training ecosystems and partner networks. Esri sustains the deepest channel penetration through its certification academy model. Hexagon AB leverages sensor-to-software integration across surveying and metrology workflows. Autodesk, Inc. competes by embedding GIS capabilities directly into BIM design environments, reducing friction for AEC professionals.
Geographic Information System (GIS) software encompasses spatial data capture, storage, manipulation, analysis, and visualization tools that operate on coordinate-referenced information layers, typically supporting raster and vector data formats with sub-meter accuracy requirements. Its primary commercial purpose is to enable location-based decision-making across asset management, emergency response, and environmental compliance workflows. Cloud-based deployment is capturing the fastest expansion as agencies retire legacy server farms and adopt SaaS consumption models. Spatial analytics and location intelligence solutions command premium pricing due to specialized machine-learning integration and real-time streaming architecture requirements. Mapping software remains the volume anchor, though margin pools are shifting toward visualization tools that serve executive dashboards in utility and defense sectors.
EPA mandates on environmental impact documentation, EU INSPIRE directive compliance for cross-border spatial data interoperability, and FERC requirements for utility corridor mapping collectively shape product certification roadmaps and procurement eligibility. EMA and national health regulators in Europe are additionally specifying GIS traceability standards for pharmaceutical supply chain integrity. Stakeholders must weigh sovereign data residency rules against cloud scalability when selecting deployment architecture for multi-jurisdiction operations.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from months to days, forcing legacy on-premise vendors to restructure licensing models and partner ecosystems around consumption-based pricing.
Growth Catalysts
- EU INSPIRE Directive:Cross-border spatial data interoperability mandates across member states are accelerating platform standardization and procurement alignment for utility corridor mapping.
- LiDAR sensor cost curves:Surveying and metrology workflows now integrate sub-centimeter capture at price points accessible to municipal governments and mid-sized engineering firms.
- India:National cadastral digitization programs under the Digital India initiative are generating sustained demand for parcel boundary automation and land-record modernization.
Market Restraints
- Geospatial talent scarcity:North American and Western European universities produce insufficient analysts trained in spatial statistics and remote sensing, constraining implementation velocity.
- Sovereign data residency:Multi-jurisdiction operators face architectural fragmentation as Germany, France, and India impose conflicting localization requirements on cloud-hosted geospatial assets.
- Legacy system entrenchment:Government agencies maintain decades-old shapefile repositories and proprietary coordinate systems that resist API-based integration.
Strategic Opportunities
- Digital twin convergence:Real-time sensor feeds from IoT networks and BIM models are creating unified infrastructure monitoring platforms for smart city operators.
- EMA traceability mandates:Pharmaceutical supply chain integrity requirements are opening specialized GIS modules for batch tracking and cold-chain verification.
- Subscription revenue models:SaaS consumption patterns are displacing perpetual licenses in mid-market AEC firms, improving vendor cash flow predictability.
Industry Challenges
- Certification pipeline delays:EPA environmental impact documentation standards and FERC utility corridor specifications require multi-quarter validation cycles that stall product releases.
- Interoperability tax:Converting between raster formats, vector schemas, and coordinate reference systems consumes 15-25% of implementation budgets according to systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geographic Information System (GIS) Software Market |
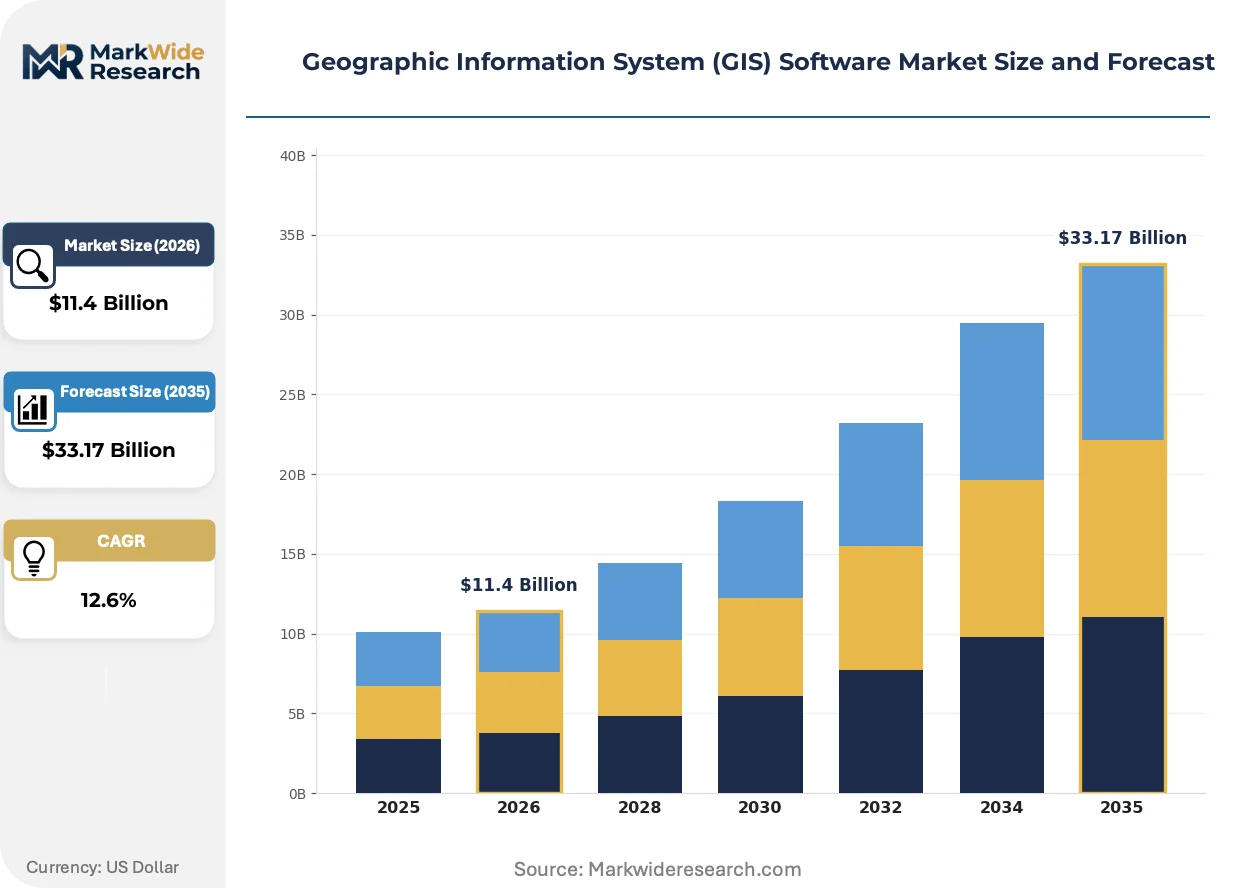
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $33.17 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, SaaS Solution Type: Mapping Software, Spatial Analytics, Data Management, Visualization Tools, Location Intelligence Application: Urban Planning, Environmental Monitoring, Agriculture Management, Infrastructure Development, Defense Surveillance End User: Government Agencies, Utility Providers, Environmental Consultants, Transportation Planners, Educational Institutions |
| Companies Covered | Environmental Systems Research Institute, Inc. (Esri), Hexagon AB, Trimble Inc., Autodesk, Inc., Bentley Systems, Incorporated, Maxar Technologies Inc., Topcon Positioning Systems, Inc., Pitney Bowes, Inc., Caliper Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geographic Information System (GIS) Software Market Shifts & Advancements
Machine learning inference at the edge is compressing analytics latency from batch processing to real-time decision support, restructuring how spatial intelligence layers into operational workflows.
Containerized microservices architectures are decomposing monolithic GIS platforms into modular components. Defense and utility sectors are adopting these disaggregated stacks fastest, enabling selective capability procurement without full-suite licensing. This decomposition is fragmenting vendor lock-in and accelerating API-first integration with enterprise ERP systems.
EPA mandates on environmental impact documentation are tightening data provenance requirements. Industrial consequence includes mandatory audit trails for spatial analysis used in regulatory submissions. Environmental consulting firms serving US infrastructure projects are responding by investing in blockchain-anchored metadata systems.
Buyer concentration among federal agencies and tier-one utilities is compressing sales cycles and demanding outcome-guaranteed implementation contracts. Systems integrators and value-added resellers are displacing direct vendor relationships in the mid-market. Germany and India exhibit this channel shift most visibly, where national procurement frameworks favor certified local partners over direct foreign software sales.
Geographic Information System (GIS) Software Market Segmentation
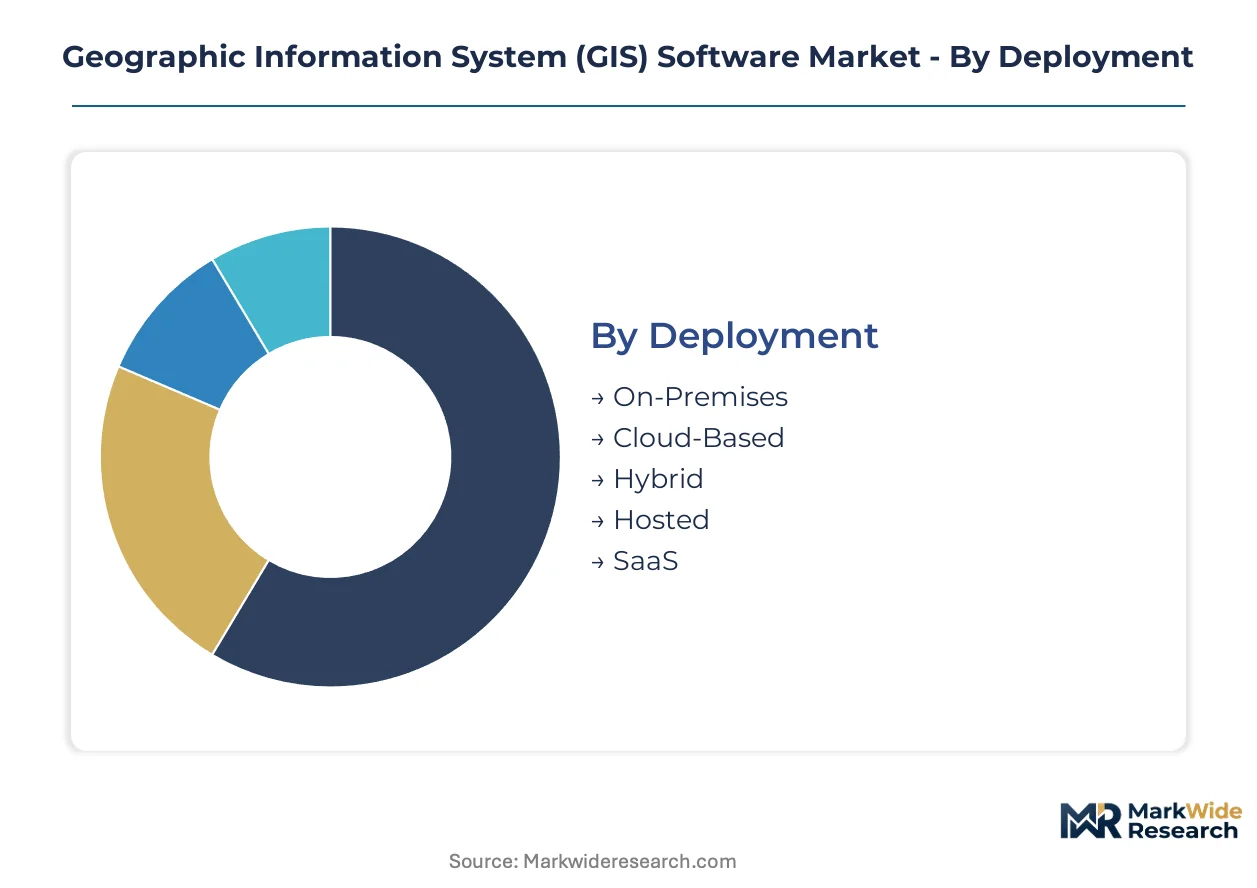
GIS software segmentation reveals how deployment architectures, solution capabilities, and end-user requirements reshape procurement patterns across regulated industries. Understanding these dimensions clarifies where platform investments concentrate and how vendors must align certification roadmaps with customer workflows.
Deployment:
EPA environmental impact documentation and FERC utility corridor specifications impose divergent data residency and audit trail requirements that reshape cloud migration timelines across customer segments.
- On-Premises:Legacy server architectures maintaining shapefile repositories and proprietary coordinate systems within agency data centers. Defense surveillance and classified infrastructure projects in the United States and Germany retain this model due to sovereign data localization mandates and air-gapped security requirements.
- Cloud-Based:SaaS consumption models compressing deployment cycles from months to days through API-first integration with enterprise ERP systems. Municipal governments in India and mid-sized environmental consulting firms in Germany are migrating fastest as legacy server farms retire and open-data mandates accelerate platform modernization.
- Hybrid:Split architectures preserving sensitive cadastral data on-premise while pushing analytics workloads to scalable cloud environments. Utility providers facing FERC corridor mapping requirements use this approach to balance compliance with computational flexibility.
- Hosted:Third-party managed infrastructure reducing capital expenditure for educational institutions and smaller transportation planning departments with limited IT staffing.
- SaaS:Subscription revenue models displacing perpetual licenses in mid-market AEC firms and improving vendor cash flow predictability through consumption-based pricing.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
Solution Type:
Cost tier differentiation separates commodity mapping functions from premium spatial intelligence layers requiring specialized machine-learning integration and real-time streaming architecture.
- Mapping Software:Volume anchor segment encompassing coordinate-referenced raster and vector data visualization with sub-meter accuracy requirements. Government agencies digitizing cadastral networks in India and utility corridor operators in Germany sustain baseline demand despite margin compression.
- Spatial Analytics:Premium-priced solutions integrating machine learning inference at the edge for real-time decision support. Environmental consultants serving EPA-mandated impact documentation and defense surveillance operators command specialized capabilities for predictive modeling and pattern detection.
- Data Management:Centralized repositories handling multi-format ingestion, provenance tracking, and blockchain-anchored metadata systems for regulatory audit trails.
- Visualization Tools:Executive dashboard layers serving utility sector leadership and defense command structures with operational geospatial intelligence.
- Location Intelligence:Cross-functional platforms embedding spatial reasoning into supply chain, risk assessment, and asset lifecycle workflows.
Mapping Software captures current procurement volume; Spatial Analytics exhibits the steepest expansion trajectory as machine learning integration commands premium pricing.
Application:
Customer maturity and implementation complexity determine where implementation budgets concentrate and where systems integrators capture the greatest service attach rates.
- Urban Planning:Smart city operators converging real-time sensor feeds from IoT networks with BIM models for unified infrastructure monitoring platforms.
- Environmental Monitoring:EPA-mandated impact documentation tightening data provenance requirements and driving blockchain-anchored metadata investment among US environmental consulting firms.
- Agriculture Management:Precision farming applications leveraging LiDAR sub-centimeter capture at price points now accessible to municipal governments and mid-sized engineering firms.
- Infrastructure Development:AEC professionals embedding GIS capabilities directly into design environments to reduce workflow friction across transportation and utility projects.
- Defense Surveillance:Containerized microservices architectures enabling selective capability procurement without full-suite licensing among classified program offices.
Infrastructure Development anchors current implementation spending; Environmental Monitoring is gaining share fastest as regulatory documentation requirements tighten.
End User:
Procurement authority and certification requirements fragment the vendor-customer relationship, with national procurement frameworks in Germany and India favoring certified local partners over direct foreign software sales.
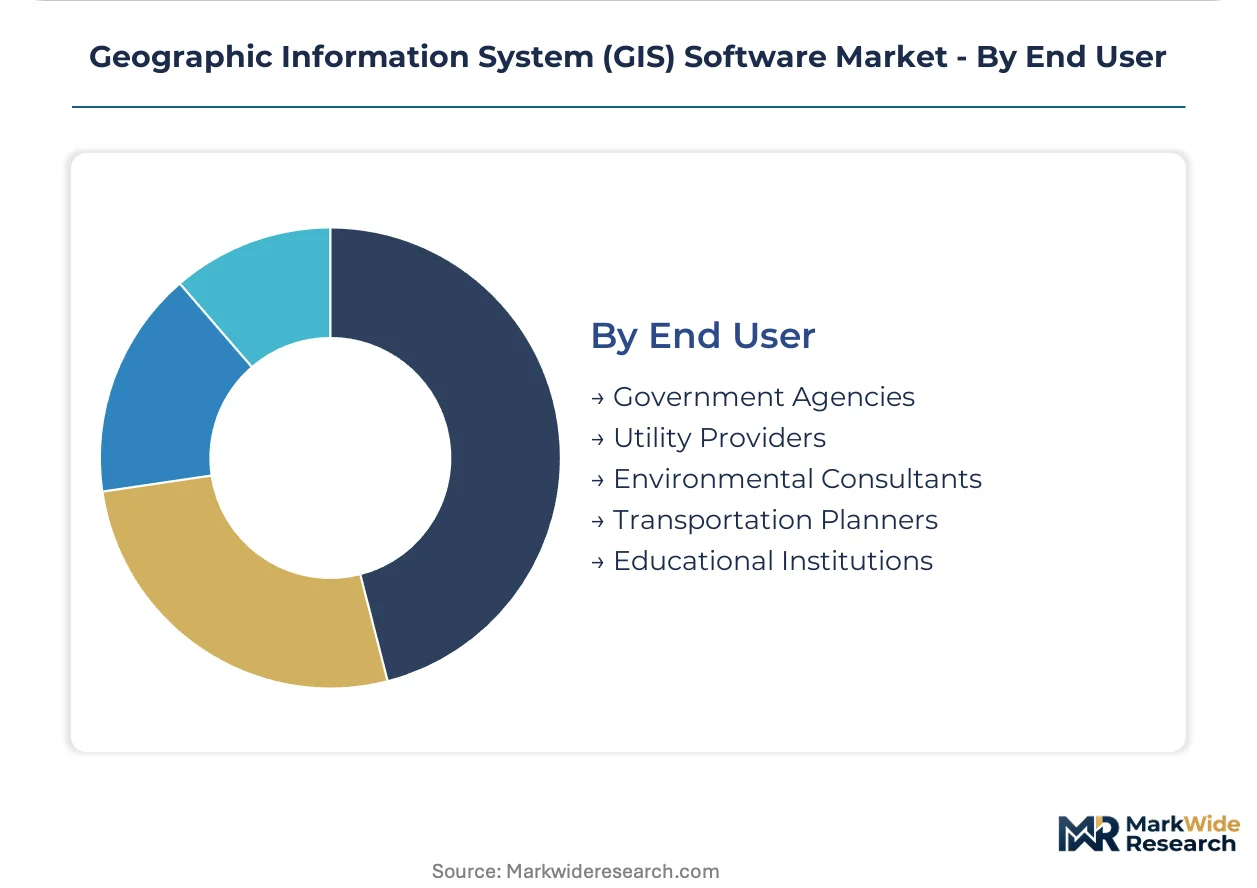
- Government Agencies:Federal buyers compressing sales cycles and demanding outcome-guaranteed implementation contracts for cadastral digitization and land-record modernization programs.
- Utility Providers:FERC-regulated corridor mapping driving API-based integration investments to replace decades-old proprietary coordinate systems.
- Environmental Consultants:Service firms investing in blockchain-anchored metadata systems to satisfy EPA audit trail mandates for spatial analysis used in regulatory submissions.
- Transportation Planners:State and municipal departments modernizing legacy shapefile repositories for multimodal network analysis and congestion modeling.
- Educational Institutions:University GIS programs training analysts in spatial statistics and remote sensing to address North American and Western European talent scarcity.
Government Agencies dominate procurement volume; Environmental Consultants represent the fastest-climbing customer segment as regulatory documentation requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA mandates on environmental impact documentation anchor North American procurement patterns, while EU INSPIRE directive compliance and India's Digital India cadastral programs reshape deployment architectures across their respective markets.
United States
Federal agencies and tier-one utilities compress sales cycles through outcome-guaranteed implementation contracts for infrastructure resilience projects. EPA environmental impact documentation standards and FERC utility corridor specifications drive multi-quarter validation cycles for platform certification. Environmental consulting firms in the Mid-Atlantic and Texas invest in blockchain-anchored metadata systems to satisfy audit trail mandates for regulatory submissions.
Germany
National procurement frameworks favor certified local partners over direct foreign software sales, restructuring channel relationships for platform vendors. EU INSPIRE directive compliance mandates cross-border spatial data interoperability, accelerating standardization for utility corridor mapping across member states. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate surveying and metrology workflows integrating sensor-to-software architectures.
India
National cadastral digitization programs under the Digital India initiative generate sustained demand for parcel boundary automation and land-record modernization. The country's national geospatial regulator imposes data localization requirements that fragment cloud deployment architectures for multi-jurisdiction operators. State-level implementations in Maharashtra and Karnataka lead municipal government migrations from legacy server farms to SaaS consumption models.
United Kingdom
Utility providers and transportation planners modernize decades-old shapefile repositories and proprietary coordinate systems that resist API-based integration. GDPR and post-Brexit data sovereignty rules complicate cloud-hosted geospatial asset strategies for operators spanning European and domestic jurisdictions. Greater London and the Southeast concentrate smart city operators converging real-time IoT sensor feeds with BIM models for unified infrastructure monitoring.
Japan
Defense surveillance and classified infrastructure projects retain on-premise deployment models due to sovereign data localization mandates and air-gapped security requirements. METI industrial digitization programs accelerate containerized microservices adoption for selective capability procurement without full-suite licensing. Industrial corridors in the Kanto region around Tokyo and manufacturing hubs in the Chubu region drive precision surveying demand for infrastructure development workflows.
Geographic Information System (GIS) Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the GIS software market. The vendor ecosystem organizes around three strategic tiers: full-suite platform providers with certification academy models, sensor-integrated specialists leveraging hardware-software convergence, and embedded-capability vendors reducing workflow friction through design environment integration. Dominant competitive moves include restructuring licensing models around consumption-based pricing and building API-first partner ecosystems to displace direct sales relationships in regulated procurement frameworks.
Within the full-suite platform tier, Environmental Systems Research Institute, Inc. (Esri) and Hexagon AB occupy anchor positions representing divergent integration strategies—Esri through channel penetration and certification infrastructure, Hexagon through sensor-to-software vertical control. Autodesk, Inc. sits within the embedded-capability archetype, exemplifying how design-environment integration reduces procurement friction for architecture, engineering, and construction professionals. These three entities collectively illustrate how competitive positioning stratifies across certification depth, hardware convergence, and workflow embedding rather than feature parity alone.
| Leading Market Players |
|---|
| Environmental Systems Research Institute, Inc. (Esri) |
| Hexagon AB |
| Trimble Inc. |
| Autodesk, Inc. |
| Bentley Systems, Incorporated |
| Maxar Technologies Inc. |
| Topcon Positioning Systems, Inc. |
| Pitney Bowes, Inc. |
| Caliper Corporation |
| Others |
Supply & Pricing Matrix
Ninety-day implementation cycles for enterprise GIS deployments concentrate pricing power with vendors possessing certified training ecosystems, while cloud-native alternatives compress these timelines and force legacy providers toward consumption-based licensing restructuring.
Pricing Analysis
Geographic price spreads of 40-60% separate North American federal procurement from Indian state-level municipal contracts, reflecting certification overhead and localization requirements. Three-tier pricing structure across premium analytics, standard mapping, and economy visualization levels dominates, with differentiation anchored in machine-learning integration depth and FERC/EPA certification status. Pricing pressure stems from open-source alternatives and SaaS consumption models displacing perpetual licenses. Mid-market AEC firms exhibit highest price sensitivity; defense and tier-one utilities demonstrate lowest sensitivity due to mandate-driven procurement authority.
Supply Chain Analysis
Inventory concentration in sensor hardware and LiDAR components extends lead times for integrated platform vendors dependent on Hexagon AB and Trimble Inc. manufacturing cycles. Software development concentrates in the United States, Germany, and India, while sensor fabrication rests on Taiwanese semiconductor foundries and German precision optics. Supply chain risk centers on single-source vulnerability for sub-centimeter LiDAR arrays subject to export control classifications. Distribution runs through certified value-added resellers in regulated procurement frameworks, with direct vendor relationships diminishing outside federal agency tier-one contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GIS platform vendors capture expanding service-attach revenue as implementation complexity and certification requirements drive systems integrator dependency, with recurring training and support layers growing faster than perpetual license recognition.
For Market Incumbents: Fortify certification academy infrastructure against emerging cloud-native competitors offering API-first integration without legacy training overhead. Deepen backward integration into sensor hardware partnerships to replicate Hexagon AB's vertical control over surveying workflows. Prioritize consumption-based pricing pilots in Indian state procurement frameworks where national digitization programs favor flexible deployment models. For New Entrants and Emerging Players: Mid-market environmental consulting firms in Germany and the United Kingdom represent an under-served service layer where incumbents lack localized blockchain-anchored metadata expertise. Penetrate through API-first microservices architectures that bypass full-suite licensing friction for containerized defense and utility deployments. Anchor go-to-market motion around EPA audit trail compliance as a wedge against legacy platform entrenchment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because sovereign data residency mandates and multi-jurisdiction compliance requirements create durable moats for certified platform providers. Target acquisition profiles center on sensor-to-software integration specialists with established FERC or EMA validation pipelines. Monitor LiDAR sensor cost curve acceleration as the inflection signal indicating commoditization pressure on hardware-dependent margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | EPA and FERC validation cycles create multi-quarter barriers protecting incumbent positioning. |
| API-First Platform Architecture | Microservices decomposition fragments vendor lock-in and accelerates ERP integration velocity. |
| Sensor Hardware Partnership | LiDAR cost compression demands vertical control over sub-centimeter capture workflows. |
| Consumption-Based Licensing | SaaS models improve cash flow predictability and displace perpetual licenses in mid-market AEC. |
| Blockchain Metadata Integration | EMA and EPA audit trail mandates open specialized modules for pharmaceutical and environmental compliance. |
Research Methodology
A standing panel of geospatial platform engineers, government procurement officers, environmental consulting technical leads, and systems integration specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA environmental impact documentation filings, FERC utility corridor specifications, EU INSPIRE directive implementation reports, and Indian Digital India cadastral program disclosures. Bottom-up deployment modeling and top-down vendor revenue triangulation anchored segmentation outputs.
Consistency checks against hyperscaler geospatial service disclosures and national geospatial regulator procurement databases validated volume assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution capability tier, application vertical, and end-user procurement authority. CAGRs derived from S-curve adoption patterning and regulatory mandate sequencing. Forecast inputs incorporated LiDAR sensor cost trajectories and cloud migration velocity benchmarks from municipal government IT modernization disclosures.
Forecasts assume regulatory continuity in EPA environmental documentation standards, EU INSPIRE interoperability mandates, and Indian data localization requirements; material policy shifts in sovereign data residency rules or open-data mandate acceleration would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Canada Geospatial Analytics Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Location Based Advertising Market