
 IPC Soc Chip Market | 2026-2036
IPC Soc Chip Market Size, Share, and Industry Trends Forecast 2026-2036
IPC Soc Chip Market Insights
Taiwan's foundry capacity expansion is reconfiguring supply dynamics for IPC SoC fabrication. Intel Corporation leverages its IDM model to sustain captive wafer supply for industrial-grade chips. Qualcomm Incorporated anchors its position through AI processing integration at the network edge. MediaTek Inc. competes aggressively on cost-optimized embedded SoC portfolios for factory automation.
An IPC SoC (Industrial PC System-on-Chip) integrates CPU cores, memory controllers, I/O interfaces, and specialized accelerators onto a single die, typically manufactured at 7nm to 28nm process nodes to balance thermal constraints with real-time deterministic performance for harsh-environment computing. Embedded SoCs dominate current shipment volumes due to their prevalence in PLC controllers and HMIs, while AI Processing technology commands premium pricing as manufacturers embed neural inference engines directly onto factory-floor devices. Application Processors are gaining share in vision-guided robotics, though FPGAs retain structural importance in aerospace and defense deployments requiring hardware reconfigurability.
The US FCC governs wireless connectivity modules embedded within IPC SoCs, while China's MIIT enforces GB standards for electromagnetic compatibility in industrial equipment. The EU AI Act is beginning to shape certification requirements for autonomous decision-making chips deployed in European manufacturing environments. Stakeholders must monitor how divergent national semiconductor subsidy regimes reshape cost competitiveness across fabrication geographies.
Market Dynamics
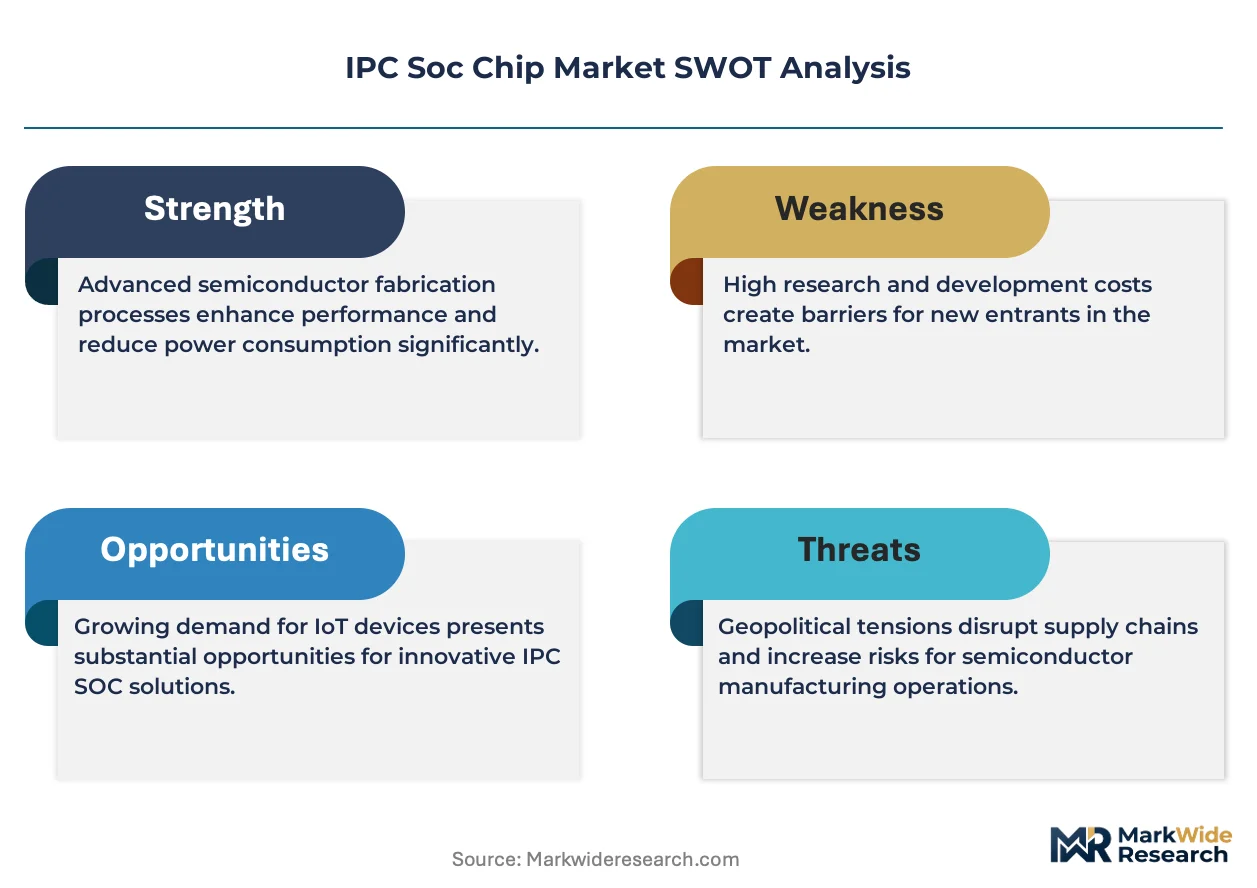
Industrial automation systems are accelerating SoC procurement as manufacturing plants consolidate compute onto single-die architectures, compressing hardware footprints while tightening real-time deterministic requirements for harsh-environment deployment.
Growth Catalysts
- Edge AI Integration:Neural inference engines embedded directly onto factory-floor devices are pulling premium silicon volumes as vision-guided robotics proliferate across automotive assembly lines.
- China's MIIT Certification Tightening:The GB framework for electromagnetic compatibility in industrial equipment is mandating upgraded SoC architectures that integrate hardened I/O controllers.
- East Asian Fabrication Clustering:Taiwan and South Korea foundry capacity expansion is reconfiguring supply availability for 7nm to 28nm process nodes critical to thermal-constrained industrial computing.
Market Restraints
- Advanced Node Cost Structure:Mask set expenses and yield engineering at 7nm nodes impose capital barriers for mid-volume industrial chip programs.
- Geographic Supply Concentration:Taiwan's foundry dominance creates single-point vulnerability for wafers supplying PLC controller and HMI manufacturers.
- FPGA Substitution in Defense:Aerospace deployments retain hardware reconfigurability requirements that ASIC-based SoCs cannot satisfy, capping addressable market in high-reliability segments.
Strategic Opportunities
- EU AI Act Tailwind:Certification requirements for autonomous decision-making chips in European manufacturing environments are creating compliance-driven upgrade cycles.
- AI Processing Convergence:TPU-NPU fusion architectures are opening white space in predictive maintenance and quality inspection applications.
- Direct OEM Channel Expansion:Bypassing traditional distribution, SoC vendors are establishing captive engineering relationships with robotics OEMs in Germany and Japan.
Industry Challenges
- Real-Time Firmware Engineering Gap:Shortage of engineers proficient in deterministic kernel optimization for RTOS environments is delaying product qualification timelines.
- Multi-Standard Certification Complexity:Simultaneous FCC wireless module approval, MIIT electromagnetic compliance, and EU AI Act verification is extending time-to-revenue for new designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IPC Soc Chip Market |
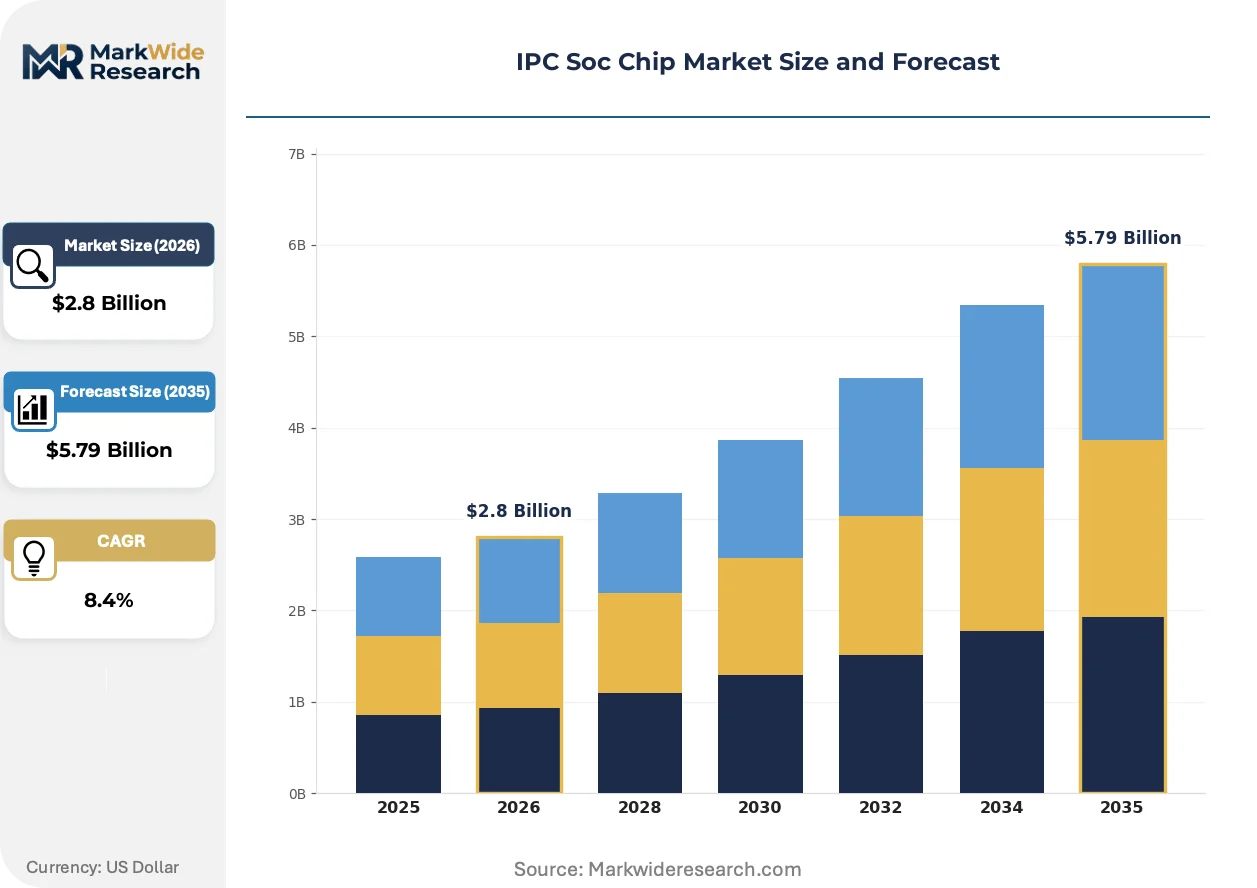
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded SoCs, Application Processors, FPGAs, DSPs Technology: Quantum Computing, 5G, Edge Computing, AI Processing End User: Manufacturing, Aerospace, Automotive, Healthcare Deployment: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | Intel Corporation, Qualcomm Incorporated, Broadcom Inc., Samsung Electronics Co., Ltd., MediaTek Inc., NXP Semiconductors N.V., STMicroelectronics N.V., Texas Instruments Incorporated, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IPC Soc Chip Market Trends and Innovations
Compute architectures are compressing heterogeneous integration timelines as industrial buyers demand consolidated silicon that eliminates discrete component procurement. Three trajectories are reshaping vendor roadmaps and foundry allocation priorities.
Chiplets are migrating from high-performance computing into industrial-grade SoCs, enabling die-level mixing of logic, memory, and analog functions without monolithic process node commitments. Automotive and robotics OEMs in Germany are piloting chiplet-based designs for vision systems. This modularity is compressing non-recurring engineering costs while fragmenting supplier ecosystems around standardized interconnect protocols.
REACH substance restrictions and RoHS recast directives in Europe are forcing material substitutions in solder bump compositions and substrate laminates used for industrial SoC packaging. Semiconductor packaging houses in the Netherlands and Austria are requalifying lead-free alloy formulations. The industrial automation segment is absorbing compliance premiums most acutely, with PLC manufacturers accelerating supply chain audits to preempt enforcement actions.
Factory automation buyers are consolidating vendor relationships around full-stack compute platforms rather than discrete processor procurement, compressing the traditional distribution channel. System integrators in South Korea are displacing component distributors as the primary specification authority for HMI projects. This concentration is most visible in automotive manufacturing clusters where single-source accountability reduces subsystem integration risk.
IPC Soc Chip Market Segmentation

IPC SoC purchasing cycles vary dramatically by segment, with some categories refreshing every 18-24 months while others extend beyond seven years. Understanding these velocity differentials helps suppliers align inventory and R&D roadmaps with actual procurement rhythms.
Product Type:
Embedded SoCs turn inventory fastest through PLC and HMI replacement programs, while FPGAs linger longest in defense qualification pipelines.
- Embedded SoCs:These single-die architectures integrate CPU cores, memory controllers, and hardened I/O for deterministic real-time performance. Factory automation buyers in Germany and Japan are consolidating compute onto these devices to compress hardware footprints in harsh-environment deployments.
- Application Processors:Higher-clock multicore designs with dedicated GPU blocks and vision acceleration engines. Vision-guided robotics OEMs in South Korea are pulling volumes as automotive assembly lines embed quality inspection directly onto production cells.
- FPGAs:Field-programmable gate arrays retain structural importance in aerospace deployments requiring hardware reconfigurability post-deployment. Defense contractors in the US and France specify these for mission profiles where in-flight algorithm updates prove essential.
- DSPs:Digital signal processors optimized for deterministic control loops and motor drive applications. Motion control systems in Japanese machine tool manufacturing represent the primary demand concentration.
Embedded SoCs dominate installed base. Application Processors is where expansion concentrates.
Technology:
Cost tiers separate experimental quantum investments from mass-deployed edge architectures, with AI Processing commanding premium silicon pricing.
- AI Processing:Neural inference engines embedded directly onto factory-floor devices enable real-time defect detection and predictive maintenance. Automotive OEMs in Germany are piloting TPU-NPU fusion architectures for quality inspection applications.
- Edge Computing:Distributed compute nodes processing data locally before cloud transmission, reducing latency for time-critical industrial control. South Korean smart factory deployments are absorbing the highest shipment volumes.
- 5G:Integrated baseband and RF modules supporting ultra-reliable low-latency communication for mobile robotics. Taiwan's industrial automation sector is driving early adoption of 5G-enabled AMR coordination systems.
- Quantum Computing:Experimental cryogenic control electronics and error-correction coprocessors for research-phase industrial optimization. IBM and Google research partnerships with German chemical manufacturers represent the only commercial traction.
Edge Computing dominates installed base. AI Processing is climbing the fastest.
End User:
Volume concentration sits with manufacturing's high-frequency replacement cycles, while aerospace and healthcare stretch procurement timelines through extended certification requirements.
- Manufacturing:PLC controllers, HMIs, and industrial gateways demanding 7nm to 28nm thermal-constrained silicon. China's MIIT GB certification tightening is mandating upgraded SoC architectures with hardened electromagnetic compatibility.
- Automotive:Battery management systems, ADAS sensor fusion, and assembly line robotics requiring AEC-Q100 grade reliability. German automotive clusters are consolidating vendor relationships around full-stack compute platforms.
- Aerospace:Flight control systems and satellite payloads where DO-254 and DO-178C compliance extends design cycles. Hardware reconfigurability requirements favor FPGA-SoC hybrids over fixed-function ASICs.
- Healthcare:Medical imaging equipment and surgical robotics demanding ISO 13485 quality systems and extended field support. Japanese diagnostic equipment manufacturers specify 10-15 year supply guarantees.
Manufacturing dominates installed base. Automotive is where expansion concentrates.
Deployment:
Customer maturity separates on-premise traditionalists from hybrid adopters, with cloud-native architectures still proving viability in industrial latency-sensitive environments.
- On-Premise:Self-contained compute within factory air-gapped networks, mandatory for defense and critical infrastructure. US Department of Defense manufacturing contractors require CMMC-compliant on-premise architectures exclusively.
- Hybrid:Split processing between local real-time control and cloud-based analytics, emerging as the dominant architecture for predictive maintenance. German Mittelstand manufacturers are piloting this model to balance latency with AI model training.
- Cloud-Based:Centralized compute with thin edge gateways, limited to non-time-critical monitoring applications. South Korean smart city industrial zones are testing cloud-based HMI dashboards with 5G backhaul.
- Remote:Satellite-linked or cellular-connected deployments for offshore, mining, and distributed energy applications. Australian mining operations in Western Australia specify these for autonomous haul truck coordination.
On-Premise dominates installed base. Hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication concentrates in East Asian foundry clusters, yet procurement demand disperses across manufacturing belts in Germany, the United States, and Japan. Taiwan and South Korea supply the process nodes; industrial automation in Bavaria and Detroit consumes the silicon.
United States
Defense manufacturing contractors and automotive assembly lines in Michigan and Ohio drive procurement volumes for hardened industrial SoCs. The FCC governs wireless connectivity modules embedded within these chips, mandating pre-market equipment authorization. Austin's semiconductor corridor hosts design centers optimizing SoC architectures for Department of Defense CMMC-compliant deployments.
Germany
Automotive OEMs and Mittelstand machine tool manufacturers in Bavaria and Baden-Württemberg absorb premium AI-processing silicon for vision-guided robotics. The EU AI Act shapes certification requirements for autonomous decision-making chips deployed in European manufacturing environments. Stuttgart's industrial automation cluster consolidates vendor relationships around full-stack compute platforms rather than discrete component procurement.
China
Smart factory deployments and PLC controller replacement programs accelerate SoC procurement across the Yangtze River Delta manufacturing belt. MIIT tightens integrated circuit certification standards under its GB framework for electromagnetic compatibility in industrial equipment. Shenzhen's electronics ecosystem is reconfiguring supply dynamics as domestic foundry capacity expands to reduce import dependency.
Japan
Motion control systems and diagnostic equipment manufacturers in Nagoya and Osaka specify extended supply guarantees for industrial-grade SoCs. METI oversees industrial technology standards while JIS certification governs embedded component reliability. The Chubu region's machine tool manufacturing corridor represents concentrated demand for DSP-optimized silicon in deterministic control loops.
South Korea
Smart factory deployments and 5G-enabled AMR coordination systems pull volumes from Seoul's industrial automation sector. The national semiconductor support framework reinforces domestic foundry allocation priorities for 7nm to 28nm process nodes. Busan's manufacturing belt is displacing traditional component distributors as system integrators consolidate specification authority for HMI projects.
IPC Soc Chip Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three strategic archetypes: IDM operators sustaining captive wafer supply, fabless designers anchoring AI processing integration, and diversified semiconductor conglomerates competing on cost-optimized portfolios. Consolidation pressures favor scale-driven players with direct OEM channel access, while mid-volume industrial programs face capital barriers at advanced nodes. Competitive moves center on foundry capacity reservation and strategic partnerships with robotics OEMs in Germany and Japan.
Among IDM operators, Intel Corporation exemplifies the captive supply archetype through in-house fabrication for industrial-grade chips. Qualcomm Incorporated occupies a position within the fabless tier, representing AI processing integration at the network edge. MediaTek Inc. anchors the cost-optimized portfolio segment, sitting within the competitive set targeting factory automation through embedded SoC offerings. These three entities collectively illustrate the strategic positioning spectrum without exhausting the competitive field.
| Leading Market Players |
|---|
| Intel Corporation |
| Qualcomm Incorporated |
| Broadcom Inc. |
| Samsung Electronics Co., Ltd. |
| MediaTek Inc. |
| NXP Semiconductors N.V. |
| STMicroelectronics N.V. |
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwan's foundry dominance creates single-source vulnerability that compresses pricing tier spreads between premium AI-processing silicon and cost-optimized embedded SoCs while simultaneously forcing supply chain consolidation around TSMC and Samsung capacity allocation decisions.
Pricing Analysis
China's MIIT GB electromagnetic compatibility certification dictates the pricing tier structure across the IPC SoC market. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-grade silicon from industrial-temperature embedded controllers and commercial-temperature economy variants. Cost compression in the economy tier is intensifying because domestic Chinese foundries are expanding 28nm capacity. Automotive OEMs in Germany exhibit the lowest price sensitivity due to long qualification timelines, while PLC manufacturers in Southeast Asia face acute margin pressure.
Supply Chain Analysis
TSMC, Samsung Foundry, and SMIC hold the dominant contract-manufacturing capacity for industrial-grade SoC fabrication. Wafer supply concentrates in Taiwan, South Korea, and mainland China for 7nm to 28nm process nodes critical to thermal-constrained deployments. Raw material dependencies include silicon wafers, advanced photoresists, and high-purity specialty gases sourced predominantly from Japanese and US chemical suppliers. Single-source vulnerability in EUV lithography equipment creates structural risk for advanced node migration. Distribution runs through direct OEM channels in Germany and Japan, displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IPC SoC procurement exhibits defensive moat characteristics rooted in regulatory entrenchment—MIIT GB certification and EU AI Act compliance create switching costs that lock buyers into qualified vendor relationships for 7-10 year product lifecycles.
For Market Incumbents: Entrench position through captive foundry capacity reservation at TSMC and Samsung for 7nm-28nm nodes, insulating against supply disruption while competitors face allocation rationing. Deepen backward integration into substrate packaging by acquiring Netherlands-based advanced packaging houses, securing lead-free alloy supply chains ahead of REACH enforcement. The emerging threat of Chinese domestic foundry expansion demands preemptive certification investment in MIIT GB electromagnetic compatibility to maintain market access. For New Entrants and Emerging Players: Mid-market PLC controllers in India's manufacturing belt represent the most penetrable entry point, bypassing entrenched German and Japanese OEM relationships. AI inference acceleration for predictive maintenance in Southeast Asian smart factories offers white-space expansion with lower qualification barriers than automotive or aerospace segments. A direct system integrator channel strategy in South Korea bypasses traditional distribution, mirroring successful incumbent approaches. For Investors and Strategic Acquirers: The EU AI Act certification requirements reshape the acquisition landscape by elevating compliance infrastructure to strategic asset status. Long-term viability over the 5-10 year window favors targets with existing CE marking and functional safety certification depth rather than pure technology plays. Acquisition target archetype: mid-cap fabless designers with MIIT GB pre-qualification and established robotics OEM relationships in Germany or Japan. The signal to watch is foundry capacity allocation priority shifts at TSMC toward automotive and AI silicon, squeezing industrial-grade allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | TSMC long-term allocation agreements secure wafer supply for 7nm-28nm industrial nodes against automotive and AI competition. |
| AI Processing Integration | TPU-NPU fusion architectures embedded directly onto factory-floor devices enable premium pricing in German automotive robotics. |
| MIIT GB Certification Pre-Investment | Early electromagnetic compliance qualification preserves China market access as domestic foundry capacity expands. |
| Direct OEM Channel Establishment | Captive engineering relationships with robotics manufacturers in Stuttgart and Nagoya displace traditional distribution. |
| Advanced Packaging Backward Integration | In-house substrate and lead-free bump capacity insulates against REACH substance restriction enforcement in Europe. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor procurement managers at German automotive OEMs, Taiwanese foundry planning executives, Japanese machine tool control system engineers, and South Korean smart factory system integrators. Secondary validation drew from MIIT GB standard filings, EU AI Act regulatory drafts, TSMC and Samsung capacity expansion disclosures, and customs data for industrial semiconductor trade flows. Bottom-up shipment estimates by product type and technology tier were triangulated against top-down wafer allocation forecasts.
Calibration against historical foundry utilization rates and industrial automation capex cycles anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, process node tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from regression analysis of procurement velocity differentials between PLC replacement cycles and defense qualification timelines. Industry-specific inputs incorporated MIIT certification timeline assumptions and EU AI Act implementation phasing.
Practitioners should monitor foundry capacity allocation shifts, REACH substance restriction enforcement actions, and robotics OEM vendor consolidation for early signals of forecast revision. Quarterly review of TSMC industrial-grade wafer pricing, MIIT GB certification queue depths, and German Mittelstand automation capex intentions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
5G CPE Chip Market