
 Smart Home Switches Market | 2026-2036
Smart Home Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Switches Market Analysis
Multi-family residential development is restructuring the addressable base for smart home switches, outpacing single-family installations in several metro corridors. Schneider Electric leverages its building automation heritage to anchor large-scale developer contracts across European and Asian markets. Lutron sustains premium positioning through proprietary wireless protocols and shading integration, while TP-LINK competes aggressively on Wi-Fi-native cost structures for retrofit consumers.
Smart home switches are electromechanical or solid-state devices that replace conventional wall switches to enable remote, scheduled, or sensor-driven control of lighting and outlet circuits, typically operating at 120-240V AC with wireless transceivers in the 2.4 GHz or sub-GHz spectrum. Their primary commercial purpose centers on energy reduction, occupancy responsiveness, and integration with broader building management platforms. Smart dimmer units command margin pools in residential premium tiers where aesthetic finish and voice compatibility drive replacement cycles. Zigbee technology leads in whole-home deployments through mesh reliability and hub-centric architectures, while Bluetooth segments expand in rental and hospitality settings where tenant turnover demands simplified onboarding without permanent infrastructure.
FCC Part 15 governs unlicensed radio emissions for Wi-Fi and Zigbee devices in the United States, shaping antenna design and coexistence testing burdens for manufacturers seeking market access. CE marking under the EU Radio Equipment Directive and REACH substance restrictions compound compliance layers for products sold across European distribution channels. Stakeholders must monitor evolving interoperability mandates from national energy regulators and utility commission rebate qualifications that increasingly require open protocol support rather than proprietary ecosystems.
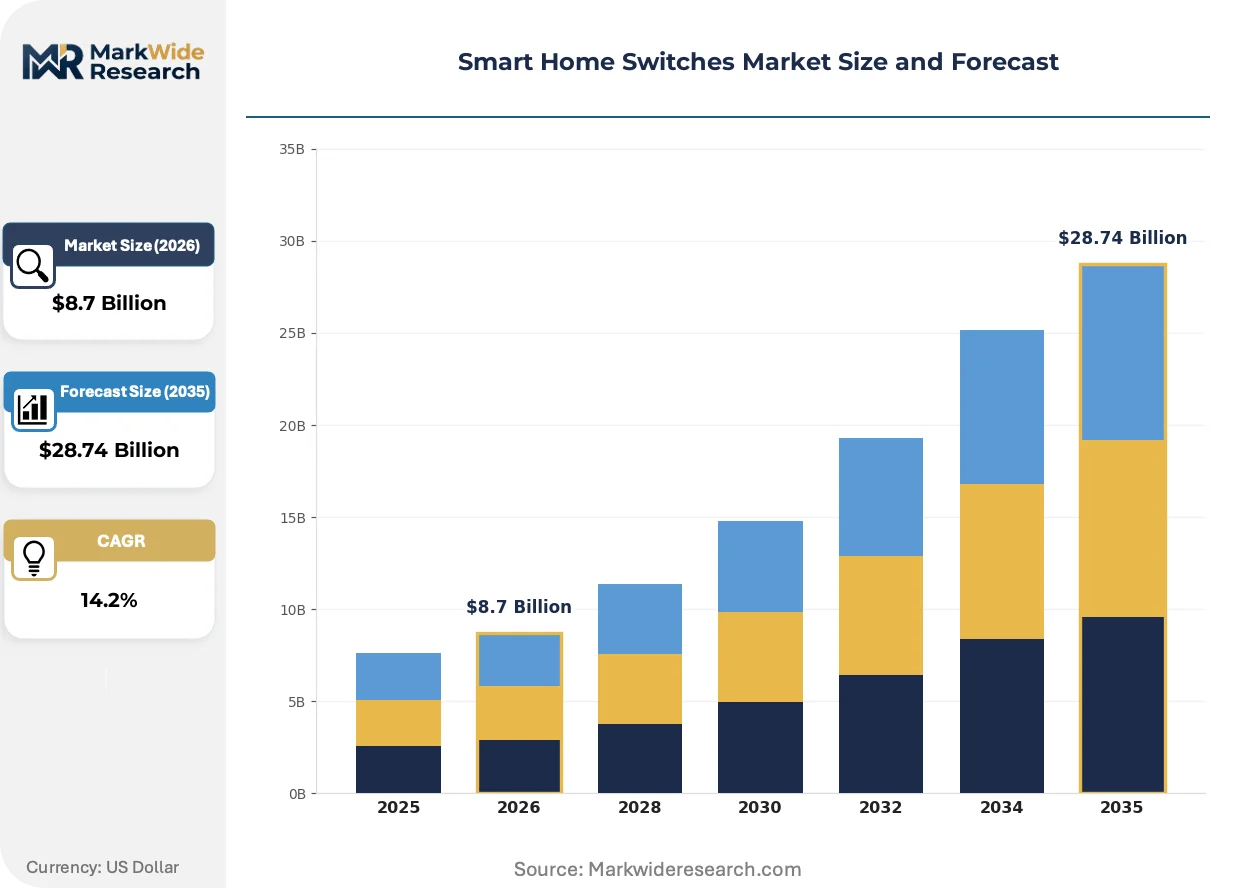
Market Dynamics
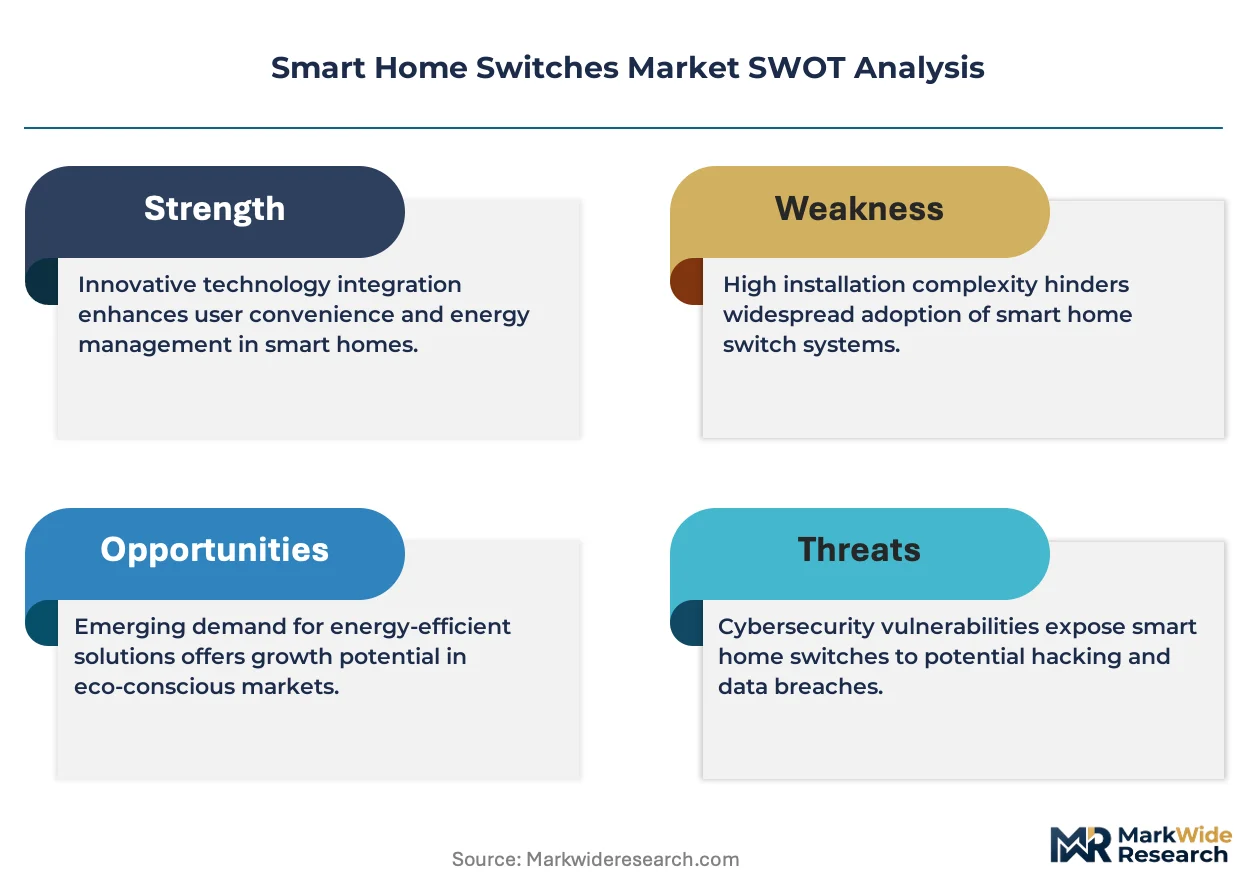
Residential retrofit waves are compressing replacement cycles for conventional wiring infrastructure as homeowners prioritize wireless retrofit solutions over full electrical overhauls. Utility rebate programs in multiple jurisdictions now mandate open protocol compatibility, forcing manufacturers to abandon proprietary ecosystems.
Growth Catalysts
- EU Green Deal building mandates:Interoperable energy management interfaces are now compulsory in German and French efficiency codes, accelerating Zigbee and Z-Wave certification demand across new construction and renovation projects.
- Utility rebate program expansion:Electricity providers in the United States, China, and India subsidize connected switch installations, lowering consumer acquisition costs and expanding addressable households in metropolitan corridors.
- Mesh network reliability:Whole-home deployments favor Zigbee's hub-centric architecture over Wi-Fi for stability in multi-device environments, particularly in multi-family residential developments.
Market Restraints
- Copper and semiconductor input volatility:Electromechanical switch production depends on copper pricing and 2.4 GHz transceiver chip availability, squeezing margin pools for cost-optimized manufacturers.
- Hub infrastructure concentration:Mesh protocol dependence on centralized controllers creates single-point-of-failure risks and vendor lock-in concerns for residential buyers.
- FCC Part 15 coexistence burdens:Unlicensed spectrum congestion in the 2.4 GHz band forces expensive antenna redesign and extended testing timelines for Wi-Fi and Zigbee device certification.
Strategic Opportunities
- Indian smart city infrastructure:National urban renewal investments create bulk procurement channels for connected building controls in affordable housing and municipal retrofits.
- Bluetooth Low Energy convergence:Rental and hospitality settings are adopting BLE-native switches to eliminate permanent hub infrastructure and enable tenant self-onboarding.
- CE marking simplification pathways:Harmonized EU Radio Equipment Directive compliance frameworks reduce redundant testing for manufacturers selling across European distribution channels.
Industry Challenges
- RF engineering talent scarcity:Antenna design and coexistence testing expertise is concentrated among a limited pool of specialists, extending product development timelines.
- Legacy electrical contractor training gaps:Traditional wiring professionals lack certification for wireless commissioning, creating installation bottlenecks in retrofit markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Switches Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Toggle, Smart Dimmer, Smart Plug, Smart Outlet Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Commercial, Industrial, Hospitality Integration Level: Standalone, Home Automation Systems, IoT Ecosystems, Smart Hubs |
| Companies Covered | Legrand, Lutron, Leviton, Schneider Electric, Signify, ABB, Panasonic, GE Lighting, TP-LINK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Switches Market Emerging Trajectories
Smart home switch architecture is fragmenting into protocol-specific ecosystems while converging on voice and sensor integration as baseline expectations. Manufacturers are repositioning around installation simplicity and interoperability rather than proprietary control.
Matter protocol implementation is modularizing device firmware architecture across the installed base. Smart home switch vendors are adopting Matter's application-layer standard to bridge Zigbee, Thread, and Wi-Fi devices under unified control interfaces. This convergence is compressing ecosystem fragmentation and enabling multi-protocol hardware designs that reduce SKU complexity for manufacturers.
REACH substance restrictions under the EU Green Deal are forcing material substitutions in switch housings and contact assemblies. Manufacturers must reformulate flame-retardant plastics and solder compositions to maintain CE marking eligibility. German and French building efficiency inspectors now verify substance compliance during energy performance certification audits.
Tenant turnover patterns in rental housing are compressing device onboarding expectations. Property managers now demand switch solutions that transfer between occupants without hub reconfiguration or account migration. This behavioral shift favors Bluetooth-native and Thread-based products in hospitality and multi-family residential channels, particularly in urban Chinese and Indian rental markets where device portability drives procurement decisions.
Smart Home Switches Market Segmentation
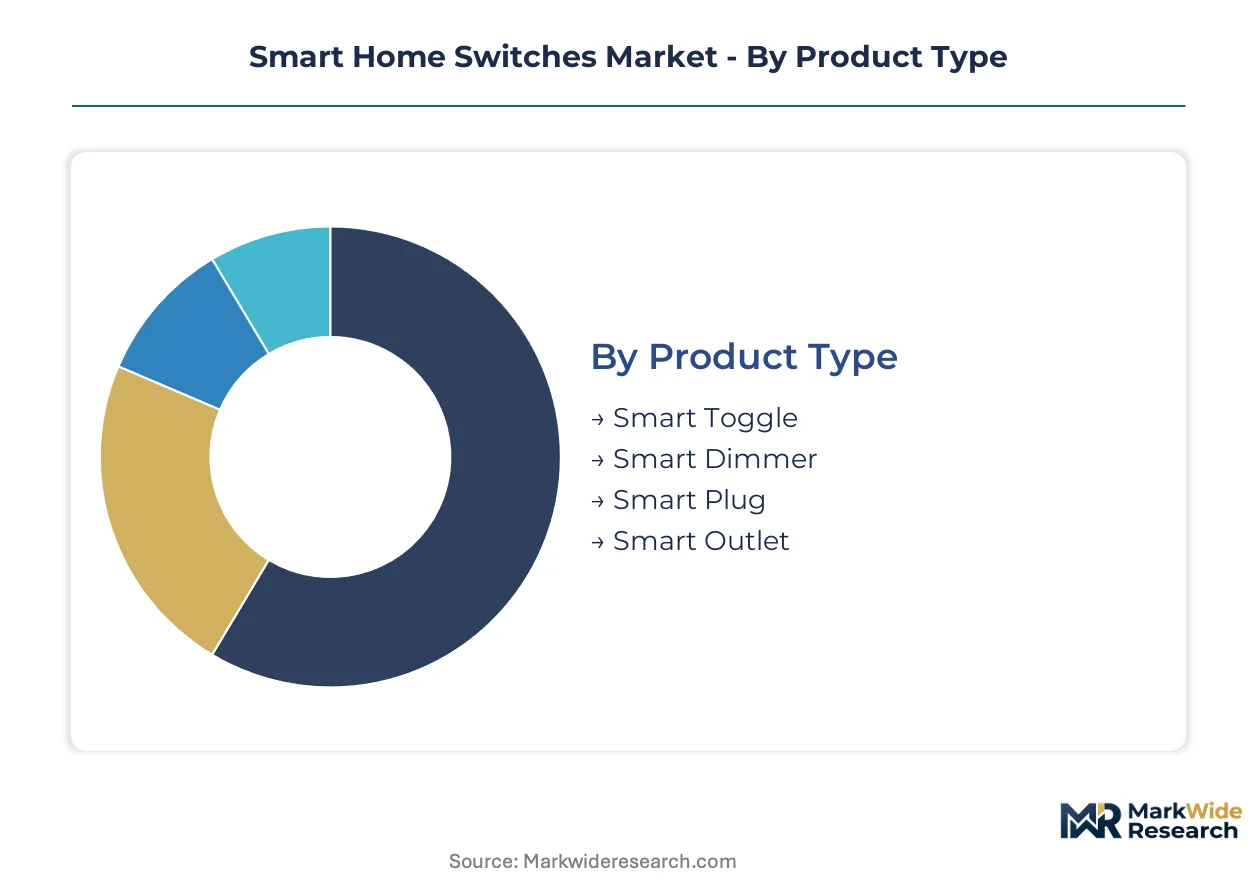
Smart home switch procurement splits across four dimensions that determine pricing power and replacement frequency. Product type governs margin structure, while technology choice locks in ecosystem compatibility for the installation lifespan.
Product Type:
Retrofit cycles concentrate demand in categories that minimize electrical contractor involvement.
- Smart Toggle:Binary on/off electromechanical units with 120-240V AC contact ratings. Demand clusters in United States single-family retrofits where homeowners seek direct replacement of legacy toggle switches without rewiring. FCC Part 15 certification burdens favor established suppliers with testing economies of scale.
- Smart Dimmer:TRIAC-based or 0-10V dimming modules with aesthetic finish options. German and French premium residential tiers drive replacement cycles through EU Green Deal efficiency mandates and energy performance certification requirements.
- Smart Plug:Portable 15A outlet adapters with integrated transceivers. Indian smart city affordable housing programs and Chinese rental markets favor plug-and-play deployment without permanent installation.
- Smart Outlet:In-wall receptacle replacements with USB-C and load monitoring. Hospitality procurement in United States metro corridors specifies tamper-resistant designs with centralized energy management integration.
Smart Toggle sits at the top of the volume ranking, with Smart Dimmer climbing the fastest.
Technology:
Protocol selection determines hub infrastructure requirements and installation complexity for end users.
- Wi-Fi:Native 2.4 GHz transceivers requiring no dedicated controller. TP-LINK and cost-optimized Chinese manufacturers dominate United States mass-market retail through direct-to-consumer channels and utility rebate program eligibility.
- Zigbee:Mesh networking at 2.4 GHz with sub-GHz regional variants. Whole-home deployments in German multi-family developments favor Zigbee's self-healing topology and interoperability certification under EU Radio Equipment Directive.
- Z-Wave:Sub-GHz proprietary mesh with regional frequency allocation. United States security-focused installations value Z-Wave's spectrum separation from Wi-Fi congestion, though hub vendor concentration creates lock-in risks.
- Bluetooth:BLE 5.0 and Mesh implementations for tenant-facing applications. Indian and Chinese rental markets adopt Bluetooth-native switches to eliminate permanent infrastructure and enable occupant self-onboarding.
Wi-Fi holds the broadest installed base, though Bluetooth is gaining share fastest in hospitality and rental channels.
End User:
Customer type dictates procurement scale, specification stringency, and replacement cycle length.
- Residential:Single-family and multi-family homeowners purchasing through retail or contractor channels. United States utility rebate programs and EU building efficiency codes accelerate replacement of conventional wiring in owner-occupied housing.
- Commercial:Office and retail facilities integrating with building management platforms. German commercial efficiency audits now mandate interoperable energy management interfaces, expanding Zigbee and Z-Wave specification requirements.
- Industrial:Manufacturing and warehouse environments requiring ruggedized specifications. Limited penetration due to hardwired industrial control standards and electrician certification requirements for hazardous locations.
- Hospitality:Hotels and serviced apartments prioritizing guest-facing simplicity and backend energy oversight. Chinese and Indian urban hotel chains specify Bluetooth-native products to streamline turnover between guest stays.
Residential commands the deepest volume pool, with Hospitality expanding most quickly in Asian metro corridors.
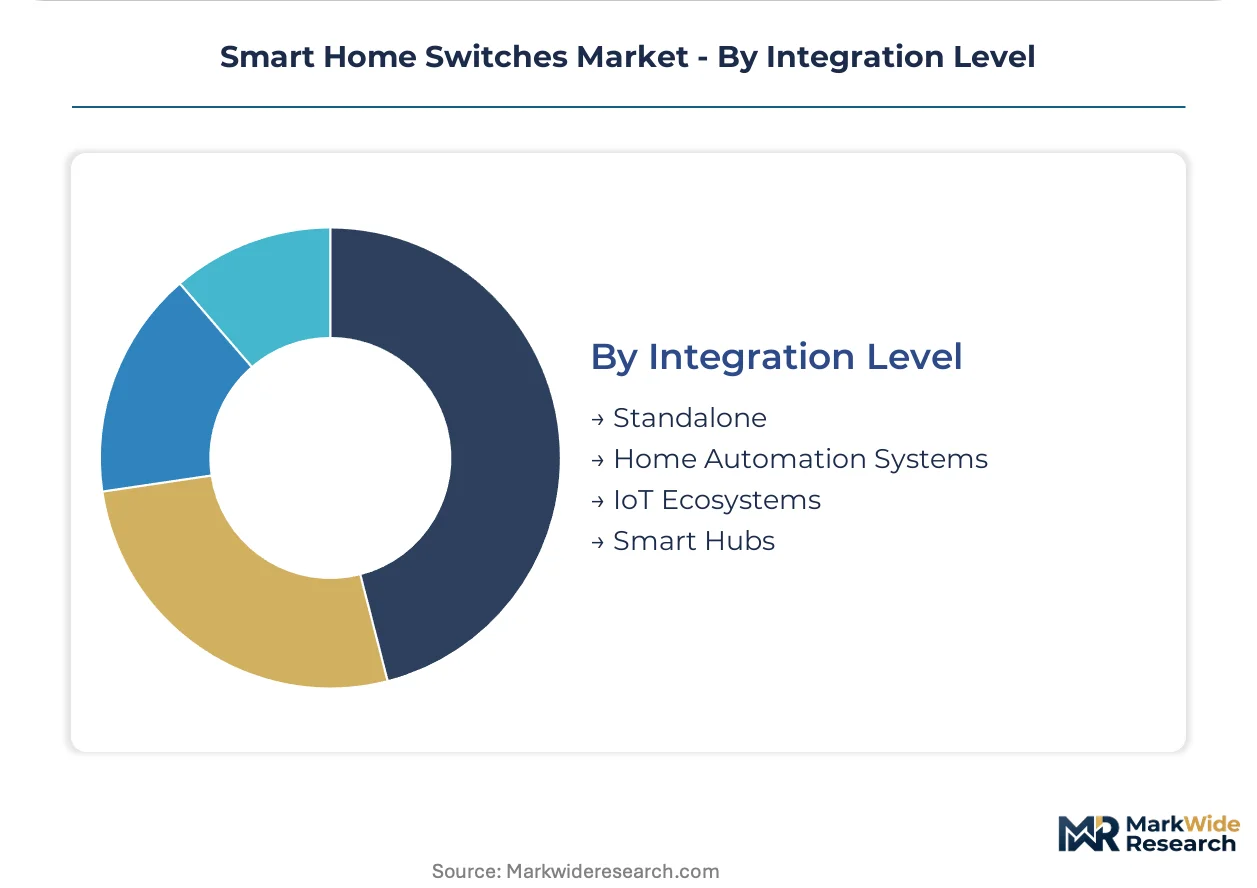
Integration Level:
System architecture determines upfront hardware costs and ongoing subscription or maintenance obligations.
- Standalone:Single-device app control without ecosystem binding. Entry-tier Wi-Fi switches in United States big-box retail target price-sensitive retrofit consumers avoiding hub investments.
- Home Automation Systems:Proprietary platforms with centralized scheduling and scene programming. Lutron's RadioRA and similar systems anchor premium residential positioning through shading and lighting integration.
- IoT Ecosystems:Cloud-connected platforms from technology vendors with voice assistant integration. Matter protocol implementation is modularizing this segment to bridge previously isolated device fleets.
- Smart Hubs:Local controller hardware aggregating multiple protocols. German and French building codes increasingly mandate open hub architectures rather than vendor-locked installations.
Standalone products lead in unit shipments, while IoT Ecosystems show the steepest expansion trajectory as Matter adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are migrating assembly operations toward jurisdictions with streamlined RF certification pathways, exploiting cost-of-compliance gaps between FCC Part 15 testing burdens and CE marking harmonization under the EU Radio Equipment Directive.
United States
Utility rebate programs in California, Texas, and New York subsidize connected switch installations, lowering consumer acquisition costs. FCC Part 15 governs unlicensed 2.4 GHz emissions, shaping antenna design requirements. The Pacific Northwest corridor concentrates Wi-Fi-native manufacturers targeting mass-market retail through direct-to-consumer channels.
Germany
EU Green Deal building efficiency codes mandate interoperable energy management interfaces in new construction and renovation projects. REACH substance restrictions force material substitutions in switch housings and contact assemblies. The Rhine-Ruhr metropolitan region anchors Zigbee certification demand through multi-family residential developments.
China
Smart city infrastructure investments in Shenzhen, Shanghai, and Beijing expand addressable households for connected building controls. MIIT governs radio equipment type approval for 2.4 GHz and sub-GHz devices. The Pearl River Delta concentrates cost-optimized manufacturers competing on Wi-Fi-native architectures for export markets.
India
National urban renewal programs create bulk procurement channels for affordable housing and municipal retrofits. BIS certification requirements for electrical equipment compound compliance layers for imported products. The Delhi-Mumbai Industrial Corridor drives hospitality procurement of Bluetooth-native switches for tenant turnover optimization.
France
Energy performance certification audits now verify REACH substance compliance during building inspections. ANSM and national energy regulators mandate open protocol support for utility rebate qualifications. The Île-de-France region concentrates premium residential demand for aesthetic dimmer finishes with voice compatibility.
Smart Home Switches Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers bridge protocol fragmentation through cross-licensing arrangements. The vendor base organizes into three tiers: diversified electrical conglomerates with building automation heritage, specialized lighting control firms with proprietary wireless ecosystems, and cost-optimized consumer electronics suppliers. Two archetypes prevail: hub-centric mesh specialists and Wi-Fi-native direct-to-consumer players. M&A activity and Matter protocol certification drives separate winners from legacy proprietary stack holders.
Among diversified electrical conglomerates, Schneider Electric and Legrand exemplify the building automation heritage archetype, anchoring large-scale developer contracts through integrated energy management platforms. Lutron occupies the premium-tier specialist position, while TP-LINK represents the cost-optimized Wi-Fi-native vector competing on direct-to-consumer accessibility. These three anchors illustrate the strategic divergence between hub-dependent mesh architectures and standalone cloud-connected alternatives.
| Leading Market Players |
|---|
| Legrand |
| Lutron |
| Leviton |
| Schneider Electric |
| Signify |
| ABB |
| Panasonic |
| GE Lighting |
| TP-LINK |
| Others |
Supply Flow & Price Mechanics
Matter protocol modularization is compressing firmware development costs while fragmenting manufacturing concentration across multiple assembly hubs. This dual effect squeezes margin pools for proprietary stack holders and rewards multi-protocol hardware designs that reduce SKU complexity.
Pricing Analysis
Distributor margin layering stratifies across three tiers: premium mesh-certified products command 35-45 point markups through electrical wholesale channels, Wi-Fi-native units flow through mass retail at compressed 15-20 point spreads, and direct-to-consumer bypass captures full margin but absorbs customer acquisition costs. Price differentiation rests on certification grade—FCC Part 15 and CE marking under EU Radio Equipment Directive tier access to rebate-eligible procurement—and volume scale for developer contracts. Pricing pressure stems from copper and 2.4 GHz transceiver chip volatility squeezing electromechanical switch production. Mass-market retail buyers exhibit highest price sensitivity, while German multi-family developers prioritize interoperability certification over unit cost.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and China's MIIT local-content rules for radio equipment type approval are reshaping sourcing patterns for 2.4 GHz and sub-GHz transceiver assembly. Component production concentrates in China, Vietnam, and Mexico, drawing from copper contact suppliers in Chile and semiconductor foundries in Taiwan and South Korea. Raw material dependencies include flame-retardant plastics subject to REACH restrictions, copper wiring, and RF transceiver chips. Single-source vulnerability in sub-GHz regional frequency allocation creates regulatory lock-in risks. Distribution runs through electrical wholesale networks in Germany and France, direct-to-consumer e-commerce in the United States, and municipal procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Home Switches Market functions as a stable compounder anchored by EU Green Deal building mandates that institutionalize replacement cycles across European new construction and renovation projects.
For Market Incumbents: Deepen backward integration into RF transceiver chip sourcing to insulate margin pools from semiconductor availability volatility. Expand Zigbee and Z-Wave certification capacity in Rhine-Ruhr metropolitan region facilities to capture German multi-family developer contract flow. Matter protocol certification investment represents the critical defensive lever against proprietary ecosystem erosion. For New Entrants and Emerging Players: Begin with Bluetooth-native switch designs targeting Indian and Chinese rental markets where tenant turnover patterns eliminate hub infrastructure requirements. Hospitality procurement in Delhi-Mumbai Industrial Corridor offers the most penetrable white-space target. Direct-to-property-manager sales channels bypass established electrical wholesale incumbent relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among cost-optimized Wi-Fi-native manufacturers with utility rebate program eligibility but limited protocol diversification. Five-to-ten year viability hinges on Matter protocol implementation timelines and open hub architecture mandate expansion. Watch German and French building code inspector enforcement patterns as inflection indicator for interoperability premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Bridges Zigbee, Thread, and Wi-Fi devices under unified control interfaces for multi-protocol hardware. |
| Backward Integration into RF Components | Captive supply of 2.4 GHz transceivers insulates margin pools from semiconductor availability constraints. |
| Utility Rebate Program Enrollment | FERC-influenced state commission qualifications expand addressable households in California, Texas, and New York. |
| Bluetooth-Native Product Line Launch | Eliminates permanent hub infrastructure for Indian and Chinese rental market tenant self-onboarding. |
| CE Marking Harmonization Investment | REACH substance compliance and EU Radio Equipment Directive testing reduces redundant certification for European distribution. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrical contractor network managers, smart home platform engineering leads, utility demand-side management officers, and multi-family property development procurement directors with secondary validation. Regulatory filings from FCC Part 15 equipment authorization databases, EU Radio Equipment Directive notified body certificates, MIIT radio type approval records, and BIS electrical equipment registrations anchored supply-side assessment. Bottom-up channel shipment estimates and top-down construction permit analysis provided triangulation checks.
Historical reference periods spanning pre-pandemic baseline through post-supply-shock recovery established anchor points for the projection horizon. The analytical framework modeled segmentation across product type, protocol technology, end-user category, and integration architecture, with regional regulatory cluster as an additional dimension. CAGRs derived from installed base replacement cycle analysis, new construction permit trajectories, and rebate program budget allocations. Forecast inputs included copper price futures curves and 2.4 GHz spectrum congestion indices.
Caveats apply where semiconductor availability shocks or REACH substance restriction expansion could materially shift the outlook. Forecasts reflect assumptions about Matter protocol adoption velocity and national building code amendment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Pad-Mounted Switchgear Market
Switches
Residual Current Circuit Breaker Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Global Safety Switches Market
Switches
Timer Switch Socket Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Smart Circuit Breaker Market
Switches
Digital Crosspoint Switches Market
Switches
Rocker Switch Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Global Float Level Switches Market
Switches
Optical Switches Market
Switches
Touchpad Market
Switches
Mexico Rocker Switch Market
Switches
Analog Switches Market