
 Audio Signaling Devices Market | 2026-2036
Audio Signaling Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Signaling Devices Market Analytics
Wireless mesh networking is reshaping how audio signaling systems integrate with building management platforms, enabling zone-specific alerts and remote diagnostics. Siemens AG leverages its building technologies division to anchor European demand for networked fire and evacuation sounders. Patlite Corporation specializes in stack light and audible alarm combinations for lean manufacturing environments. Federal Signal Corporation dominates municipal and industrial siren segments through its long-standing channel relationships with public safety agencies.
Audio signaling devices are electromechanical or solid-state apparatus engineered to emit tonal, pulsed, or voice-based alerts within specified frequency ranges and sound pressure levels. These devices serve critical notification functions across safety, security, and operational workflows where visual cues prove inadequate. The sirens category leads unit volume in emergency services and industrial applications where long-range audibility and harsh-environment durability command premium positioning. Digital technology represents the fastest-expanding segment as facilities replace legacy analog horns with addressable, software-configurable units that support multi-language voice messaging and event logging. Hybrid systems that combine wired backbone infrastructure with wireless endpoint flexibility are capturing margin pools in retrofit-heavy commercial building verticals.
FCC Part 15 governs radio-frequency emissions for wireless signaling equipment in the United States, while NFPA 72 dictates installation and performance standards for fire alarm and emergency communication systems. EMEA markets face additional compliance layers from CE marking under the EU Construction Products Regulation and country-specific workplace safety directives. IEC 60268-16 provides the speech intelligibility measurement framework that increasingly shapes product development roadmaps. Stakeholders must monitor evolving harmonization between regional certification regimes as manufacturers pursue platform consolidation across North American and European specifications.
Market Dynamics
Wireless mesh protocols are compressing installation timelines for multi-zone audio alerting systems, forcing incumbents to re-architect product roadmaps around software-configurable endpoints rather than fixed-tone hardware.
Growth Catalysts
- NFPA 72 intelligibility mandates:US commercial buildings face retrofits of legacy horn-strobe combinations, creating pull-through demand for voice-capable emergency communication systems that exceed 0.5 STI ratings.
- Factory automation intensity in Germany:Automotive and chemical plants specify IP66-rated audible alarms with integrated stack lights to satisfy DGUV workplace safety inspections and minimize unplanned downtime.
- Edge computing integration:On-device audio processing enables localized decision-making for evacuation routing, reducing latency versus centralized control panel architectures.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing dominance by Chinese state-controlled entities creates input cost volatility for electromechanical siren manufacturers.
- IEC 60268-16 certification friction:Speech transmission index testing requires specialized anechoic facilities, extending product launch timelines by 4-8 months for voice messaging units.
- LED visual alert substitution:High-intensity strobe arrays displace audible-only devices in noise-restricted zones such as hospital recovery wards and recording studios.
Strategic Opportunities
- India industrial corridor buildout:PLI scheme incentives for semiconductor and pharmaceutical manufacturing create greenfield demand for integrated safety notification systems in Gujarat and Tamil Nadu.
- EU CSRD reporting alignment:Corporate sustainability disclosure requirements favor suppliers offering lifecycle carbon data for audio signaling hardware, advantaging modular repairable designs.
- 5G private network convergence:Ultra-reliable low-latency communication enables mission-critical voice evacuation over cellular infrastructure, opening retrofit paths for aging copper-wired commercial buildings.
Industry Challenges
- Embedded firmware security hardening:IEC 62443 cybersecurity standards for operational technology impose development overhead on traditionally hardware-focused siren manufacturers.
- Multi-protocol integration complexity:Facilities managers struggle to synchronize BACnet fire alarm panels with proprietary wireless mesh endpoints from competing vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Signaling Devices Market |
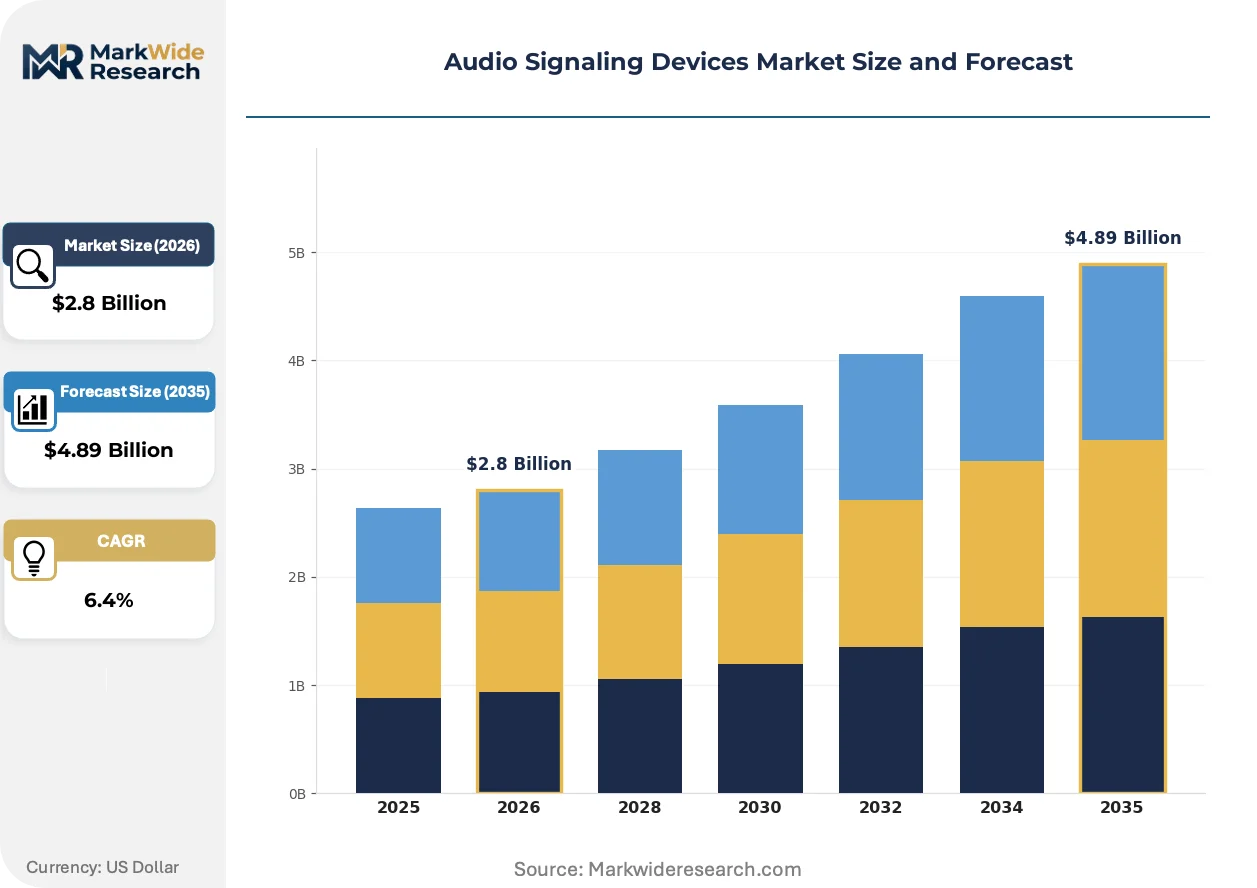
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buzzers, Alarms, Sirens, Horns Technology: Analog, Digital, Wireless, Hybrid Application: Home Security, Industrial Safety, Automotive Alerts, Emergency Services End User: Manufacturers, Contractors, Residential, Retailers |
| Companies Covered | Honeywell International Inc., Siemens AG, Eaton Corporation, Federal Signal Corporation, Schneider Electric SE, ABB Ltd., Rockwell Automation Inc., Emerson Electric Co., Patlite Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Signaling Devices Market Evolving Landscape
Audio signaling hardware is shedding fixed-function limitations as solid-state architectures and cloud-connected diagnostics redefine what constitutes a "finished" product at shipment.
Software-defined sirens are virtualizing the traditional boundary between device and system. These programmable units store multiple tone patterns and voice messages locally, enabling facility managers to reconfigure alerts without hardware swaps. Large distribution centers and automated warehouses in the US Midwest are deploying them aggressively. The technology is virtualizing spare parts inventory, as one SKU replaces dozens of fixed-tone variants.
EU Construction Products Regulation harmonization is tightening CE marking requirements for fire safety equipment, including mandatory third-party testing of acoustic performance claims. Manufacturers must now submit sound pressure level data from accredited laboratories before placing products on the market. German and French certification bodies are processing backlogs of 12-18 months, compressing competitive windows for new entrants.
Buyers are unbundling installation from hardware procurement, treating audio signaling systems as IT infrastructure rather than electrical commodities. Systems integrators and managed service providers are capturing margin that distributors previously held. This pattern is most visible in Nordic commercial real estate, where property owners prioritize OpEx-based service agreements over capital equipment purchases.
Audio Signaling Devices Market Segmentation
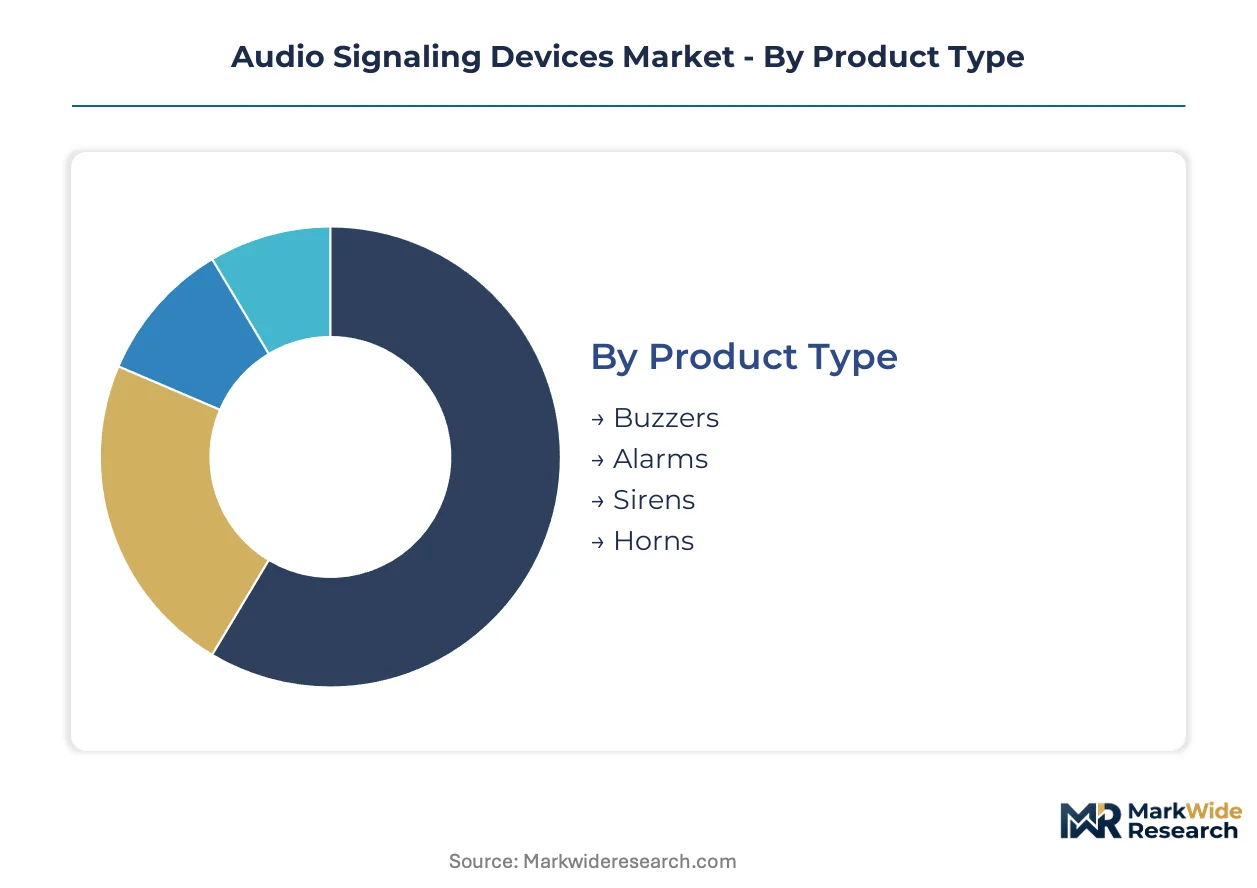
Audio signaling devices fragment across four distinct dimensions that shape procurement patterns and margin structures. Product type and technology choices determine hardware specifications, while application context and end-user category dictate channel strategy and service bundling requirements.
Product Type:
Sound output mechanism and environmental durability separate these hardware categories across cost tiers and deployment contexts.
- Sirens:Electromechanical or solid-state units engineered for long-range audibility above 100 dB. Municipal emergency services and heavy industrial facilities in Germany specify these for outdoor hazard notification where NFPA 72 intelligibility mandates apply.
- Alarms:Programmable tonal or voice-capable devices deployed in building fire evacuation systems. US commercial real estate retrofits are pulling addressable alarm units that exceed 0.5 STI ratings under tightening code enforcement.
- Buzzers:Compact piezoelectric or electromagnetic indicators for localized status signaling. Lean manufacturing lines in automotive plants integrate these with stack lights for andon notification.
- Horns:Directional acoustic projectors for high-ambient-noise environments. Marine and mining operations specify corrosion-resistant horn variants for extreme duty cycles.
Sirens command the established base. The steepest expansion runs through alarms as voice-messaging retrofits accelerate.
Technology:
Signal processing architecture determines integration flexibility, maintenance overhead, and compliance trajectory across installation types.
- Digital:Software-configurable units with onboard storage for multi-language voice messaging and event logging. Distribution centers across the US Midwest are deploying these to virtualize spare parts inventory through programmable tone libraries.
- Wireless:Mesh-networked endpoints enabling zone-specific alerts and remote diagnostics without copper infrastructure. Nordic commercial real estate operators favor these for retrofit-heavy building modernization projects.
- Hybrid:Wired backbone infrastructure paired with wireless endpoint flexibility. Margin capture concentrates in legacy building upgrades where ripping out existing conduit proves cost-prohibitive.
- Analog:Fixed-tone electromechanical devices with minimal configuration capability. Replacement demand dominates as facilities phase out legacy horn-strobe combinations.
Analog retains residual volume in price-sensitive retrofits. Digital and wireless are climbing the fastest as facilities prioritize addressable infrastructure.
Application:
Environmental conditions and regulatory exposure shape specification requirements across vertical markets.
- Industrial Safety:IP-rated audible alarms integrated with machine safety systems. German chemical and automotive plants specify these for DGUV workplace compliance and unplanned downtime minimization.
- Emergency Services:Long-range notification systems for municipal fire, police, and civil defense. FCC Part 15 governs radio-frequency emissions for wireless equipment in US deployments.
- Home Security:Compact battery-powered or hardwired intrusion deterrents. Residential construction cycles and smart home integration trends influence specification.
- Automotive Alerts:Pedestrian warning systems and reverse alarms for electric and hybrid vehicles. Regulatory mandates for acoustic vehicle alerting systems drive specification in multiple jurisdictions.
Industrial safety commands the established base. Emergency services represent the steepest expansion trajectory as municipal agencies modernize aging siren networks.
End User:
Procurement authority and technical capability determine channel structure and service bundling economics.
- Contractors:Systems integrators and electrical contractors specifying audio signaling as part of bundled fire alarm or building automation installations. Margin capture is shifting toward these intermediaries as buyers unbundle hardware from installation.
- Manufacturers:Original equipment manufacturers integrating signaling components into machinery, vehicles, or finished goods. Automotive tier-1 suppliers and industrial automation OEMs dominate this procurement category.
- Residential:Individual homeowners and property managers acquiring through retail or contractor channels. Price sensitivity and DIY installation capability segment this demand.
- Retailers:Distributors and resellers holding inventory for spot purchase and replacement demand. This channel faces compression as direct procurement and managed service agreements expand.
Contractors command the established base. Manufacturers represent the steepest expansion trajectory as embedded signaling integration deepens across industrial and automotive platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial safety managers and building automation contractors concentrate procurement authority across three distinct buyer archetypes: German automotive OEMs specifying integrated machine safety systems, US commercial real estate operators retrofitting legacy fire alarm infrastructure, and Indian manufacturing project developers sourcing greenfield notification networks.
Germany
Automotive and chemical plants in Stuttgart and Leverkusen drive specification of IP66-rated audible alarms with stack light integration. DGUV workplace safety inspections enforce strict decibel and intelligibility thresholds. The Ruhr industrial corridor hosts concentrated demand from BASF and ThyssenKrupp facilities modernizing hazard notification systems.
United States
Commercial real estate portfolios in Chicago and Dallas face mandatory NFPA 72 intelligibility retrofits for voice-capable emergency communication systems. FCC Part 15 governs wireless mesh deployment in multi-tenant buildings. Distribution centers across Ohio and Indiana adopt software-configurable alarms to virtualize spare parts inventory.
India
PLI scheme incentives for semiconductor and pharmaceutical manufacturing create greenfield demand in Gujarat and Tamil Nadu. The national electrical regulator mandates BIS certification for fire safety equipment in industrial zones. The Delhi-Mumbai Industrial Corridor anchors concentrated procurement from Foxconn and Tata Electronics facilities.
Japan
Automotive tier-1 suppliers in Toyota City and Yokohama integrate pedestrian warning systems for hybrid and electric vehicle platforms. METI regulations drive acoustic vehicle alerting system mandates. The Nagoya industrial cluster concentrates stack light and audible alarm demand from lean manufacturing lines.
China
State-backed semiconductor fabrication investments in Shanghai and Hefei require integrated safety notification systems. GB standards and MIIT regulations govern electromagnetic compatibility for industrial signaling equipment. The Yangtze River Delta anchors procurement from SMIC and Hua Hong Semiconductor facilities.
Audio Signaling Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Building technology conglomerates leverage fire alarm panel integration to capture specification authority, while electromechanical specialists defend position through hazardous-environment durability certifications. Three archetypes dominate: diversified industrial automation conglomerates, dedicated audible-visual signaling specialists, and municipal emergency systems incumbents. Competitive moves concentrate on wireless protocol licensing partnerships and cybersecurity certification acceleration under IEC 62443 standards.
Among diversified industrial conglomerates, Honeywell International Inc. and Siemens AG occupy positions anchoring building automation integration. Federal Signal Corporation exemplifies the municipal and industrial siren specialist archetype with deep channel relationships in public safety procurement. Patlite Corporation represents the dedicated audible-visual combination specialist tier serving lean manufacturing environments. These three named entities illustrate how competitive positioning fragments across integration depth, application specialization, and geographic channel control rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Eaton Corporation |
| Federal Signal Corporation |
| Schneider Electric SE |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Emerson Electric Co. |
| Patlite Corporation |
| Others |
Value Network & Pricing Analysis
Neodymium magnet supply concentration in Chinese state-controlled processing facilities determines both tiered pricing spreads across electromechanical siren categories and the geographic shape of component sourcing networks. Buyers face volatile input cost pass-throughs that compress margins on economy-grade units while premium voice-messaging systems absorb volatility through software-value bundling.
Pricing Analysis
Cost-plus contracts indexed to rare earth oxide benchmarks dominate procurement between electromechanical siren manufacturers and automotive OEMs. Pricing stratifies across IEC 60268-16 certified premium tiers, standard addressable units, and economy-grade fixed-tone devices. Cost compression in economy tiers is intensifying because of magnet price volatility and substitution pressure from LED visual alerts. Residential contractors exhibit highest price sensitivity, while German chemical plants prioritize certification-grade premiums over unit cost.
Supply Chain Analysis
Export-control restrictions on rare earth processing technology limit alternative supplier qualification for neodymium-dependent electromechanical components. Manufacturing concentrates in China for magnet processing, Germany for precision acoustic engineering, and Japan for piezoelectric ceramics. Magnet supply draws from concentrated Chinese state entities, voice-processing chipsets from Taiwanese foundries, and corrosion-resistant enclosures from German metalworking specialists. Single-source vulnerability in rare earth separation creates procurement risk. Distribution runs through authorized systems integrators holding NFPA 72 and CE marking compliance credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs deep as wireless mesh protocols unbundle hardware from installation, creating specialist niches for cybersecurity-certified firmware developers and managed service operators.
For Market Incumbents: Build certification moats around IEC 62443 cybersecurity standards for operational technology. Siemens AG and Honeywell International Inc. should accelerate firmware hardening investments to defend against software-defined siren entrants. Backward integration into voice-processing chipset supply reduces exposure to Taiwanese foundry lead times. Channel control through systems integrator certification programs limits margin capture by emerging managed service providers. For New Entrants and Emerging Players: Pursue white-space targeting in 5G private network voice evacuation retrofit for aging US commercial real estate. The most penetrable segment combines wireless mesh endpoints with existing BACnet fire alarm panels in Chicago and Dallas multi-tenant buildings. Go-to-market leverage rests on OpEx-based service agreements that unbundle hardware procurement from installation, mirroring Nordic commercial real estate patterns. For Investors and Strategic Acquirers: EU CSRD reporting alignment reshapes the acquisition landscape toward modular repairable design specialists with lifecycle carbon data capabilities. Long-term viability favors targets combining software-configurable alarm platforms with established IEC 60268-16 testing relationships. Watch for BIS certification acceleration in Indian industrial corridors as the inflection signal for greenfield demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Protocol Licensing Partnership | Enables Siemens AG to extend BACnet integration into competing fire alarm panel ecosystems. |
| Cybersecurity Certification Acceleration | Positions Federal Signal Corporation for IEC 62443 compliance ahead of municipal procurement mandates. |
| Voice Messaging Localization Investment | Allows Patlite Corporation to capture Japanese automotive tier-1 supplier specification authority. |
| Rare Earth Magnet Supply Diversification | Reduces Eaton Corporation exposure to Chinese state-controlled processing concentration. |
| Managed Service Agreement Expansion | Captures recurring revenue streams from Nordic commercial real estate operator preferences. |
Research Methodology
Desk research of regulatory filing databases, trade association technical standards, and customs shipment records preceded structured interviews with fire alarm systems integrators, industrial safety procurement managers, building automation contractors, and voice-messaging firmware developers. Primary fieldwork combined with secondary validation against NFPA 72 enforcement bulletins, IEC committee draft releases, and BIS certification registries. Bottom-up unit shipment estimates triangulated against top-down facility modernization spending data.
Assumptions held fixed include NFPA 72 intelligibility mandate enforcement timelines, neodymium magnet supply concentration, and wireless mesh protocol adoption curves across the projection horizon. The analytical framework modeled technology substitution rates, application vertical spending cycles, and end-user procurement authority shifts. CAGRs derived from segment-level unit economics and value-per-unit trajectories. Voice-messaging retrofit penetration and 5G private network deployment pace served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or rare earth trade policy would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in EU Construction Products Regulation harmonization timelines or Chinese export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market