
 Ethernet Phys Market | 2026-2036
Ethernet Phys Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Phys Market Analysis
Automotive OEM demand for multi-gigabit Ethernet PHYs is collapsing toward data center and AI infrastructure buyers as the dominant volume archetype. Broadcom Inc. leverages its merchant silicon position across 400G and 800G PAM4 PHYs to sustain design wins at hyperscale switch vendors. Marvell Technology anchors the high-speed interconnect segment with DSP-based retimers and active electrical cables. Texas Instruments competes in the industrial temperature-grade niche where extended reliability specifications command premium positioning.
Ethernet physical layer transceivers encode, transmit, and receive data streams across copper or optical media, with modern implementations operating at 56 Gbaud PAM4 signaling to achieve 112 Gbps per lane. These devices translate digital MAC-layer frames into analog waveforms compliant with IEEE 802.3 electrical specifications, enabling interoperability across switch ports, NICs, and backplane traces. The technology dimension shows twisted pair PHYs dominating unit volume in enterprise access layers while fiber optic implementations capture the majority of value in data center spine fabrics. By application, data center networking generates the fastest growth trajectory as AI clusters demand low-latency, high-bandwidth interconnects, whereas industrial automation represents a mature, slower-expansion segment with long product lifecycles.
IEEE 802.3 standards development, FCC equipment authorization requirements, and EU RoHS substance restrictions collectively shape PHY design roadmaps and market access conditions. The IEEE 802.3dj task force is defining 800 GbE and 1.6 TbE electrical interfaces, forcing vendors to rearchitect SerDes architectures ahead of interoperability testing deadlines. FCC Part 15 emissions compliance adds validation cost and cycle time for copper PHYs operating above 10 GHz. Stakeholders must monitor standards ratification schedules against foundry process node availability to time tape-outs and avoid stranded R&D investment.
Market Dynamics
The migration from NRZ to PAM4 modulation schemes is compressing power budgets per lane while multiplying lane counts, forcing PHY vendors to rearchitect SerDes architectures around 112 Gbps electrical interfaces before IEEE 802.3dj ratification deadlines.
Growth Catalysts
- AI cluster buildouts:Hyperscalers in the United States are deploying 400G and 800G PHYs in training fabrics, creating concentrated demand for retimers and active electrical cables.
- Energy Efficient Ethernet mandates:IEEE 802.3az compliance requirements in European data centers are accelerating replacement cycles for legacy 10G and 25G ports.
- Automotive zonal architectures:Multi-gigabit Ethernet PHY specifications for in-vehicle networks in Germany and Japan are opening design win opportunities at Tier-1 suppliers.
Market Restraints
- Advanced packaging costs:2.5D interposer and CoWoS processes from Taiwan-based foundries are inflating die costs for 800G PHY implementations.
- Copper reach limitations:Signal integrity degradation beyond 3 meters at 112 Gbps PAM4 is restricting twisted-pair PHY deployment in large-scale data halls.
- FCC Part 15 friction:Electromagnetic emissions testing for copper PHYs above 10 GHz adds validation cycle time and non-recurring engineering expense.
Strategic Opportunities
- Linear pluggable optics integration:Convergence of DSP-based retimers with silicon photonics is enabling lower-power 800G optical modules for cloud AI fabrics.
- India data center expansion:Domestic cloud region buildouts by global hyperscalers are creating demand for 100G and 400G PHYs in Mumbai and Hyderabad clusters.
- EU Green Deal alignment:Power consumption disclosure requirements under CSRD are favoring vendors with watt-per-gigabit documentation and circular design roadmaps.
Industry Challenges
- SerDes analog design talent scarcity:Expertise in 56 Gbaud PAM4 equalization and clock recovery is concentrated among a small pool of engineers in Silicon Valley and Israel.
- Interoperability testing bottlenecks:IEEE 802.3ck and 802.3dj compliance verification at third-party labs is creating tape-out delays for 800G PHY products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Phys Market |
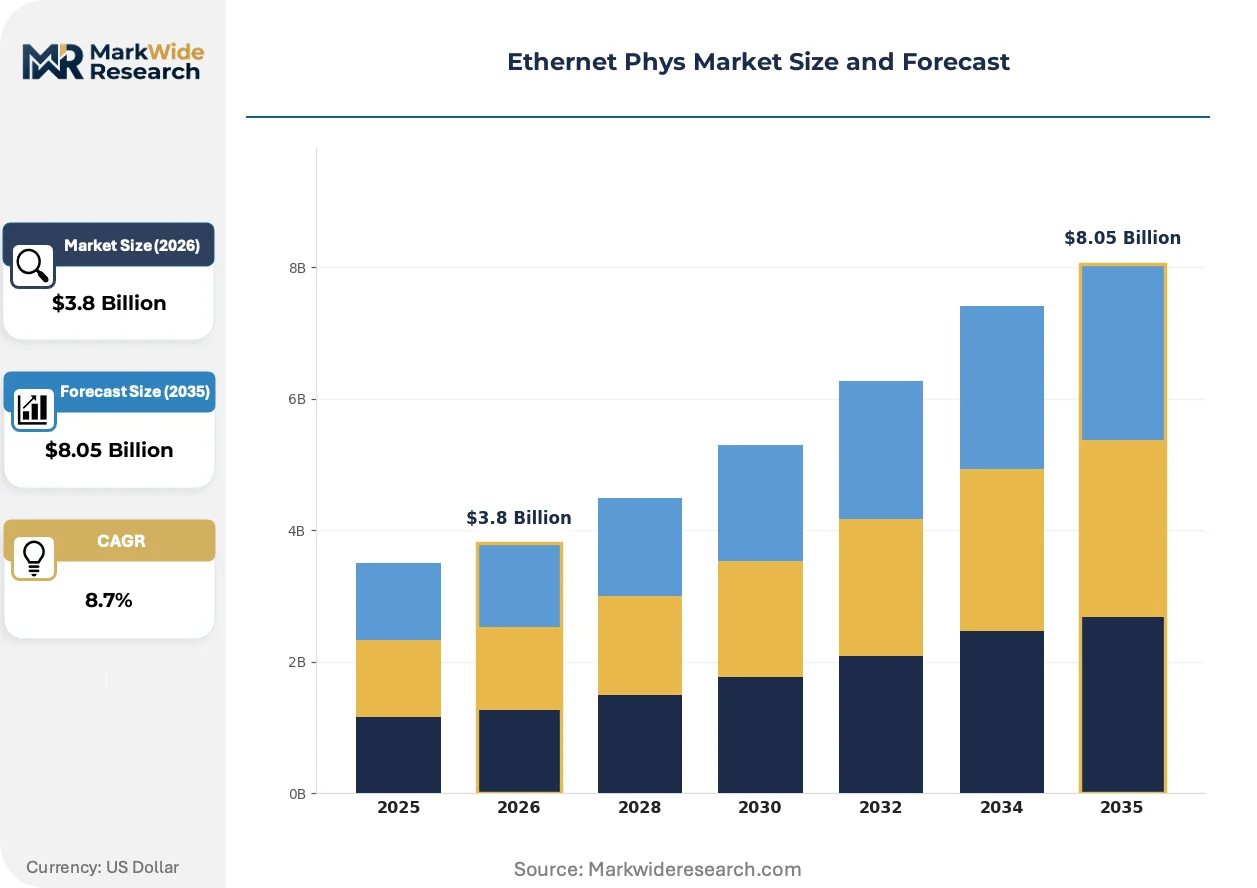
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 10Base-T, 100Base-TX, 1000Base-T, 10GBase-T Technology: Twisted Pair, Fiber Optics, Coaxial, Power over Ethernet Application: Data Center Networking, Industrial Automation, Telecommunications, Home Networking End User: Enterprises, Service Providers, Educational Institutions, Healthcare |
| Companies Covered | Broadcom Inc., Marvell Technology, Realtek Semiconductor, Texas Instruments, Microchip Technology, NXP Semiconductors, Analog Devices, Intel Corporation, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Phys Market Emerging Trajectories
PAM4 signaling architectures are decomposing traditional PHY design assumptions, while regulatory pressure on energy consumption and hyperscaler procurement consolidation are restructuring competitive positioning.
Linear drive optics is decomposing the conventional DSP-heavy transceiver architecture. Cloud operators in the United States are piloting LPO modules for 800G links to reduce power and latency in AI training clusters. This technology is decomposing the incumbent retimer-based supply chain by eliminating power-hungry digital signal processors from the optical path.
EU RoHS substance restrictions are tightening permissible thresholds for lead and cadmium in semiconductor packaging. PHY vendors serving European data center operators must reformulate solder alloys and substrate materials to maintain market access. German industrial automation buyers are now requiring full material disclosure documentation as a procurement gate.
Hyperscale direct sourcing is consolidating procurement authority away from traditional distributor channels. Large cloud operators in the United States and China are negotiating long-term supply agreements directly with PHY vendors for 400G and 800G volumes. This pattern is most visible in switch ASIC co-development programs where PHY specifications are locked years ahead of production ramp.
Ethernet Phys Market Segmentation
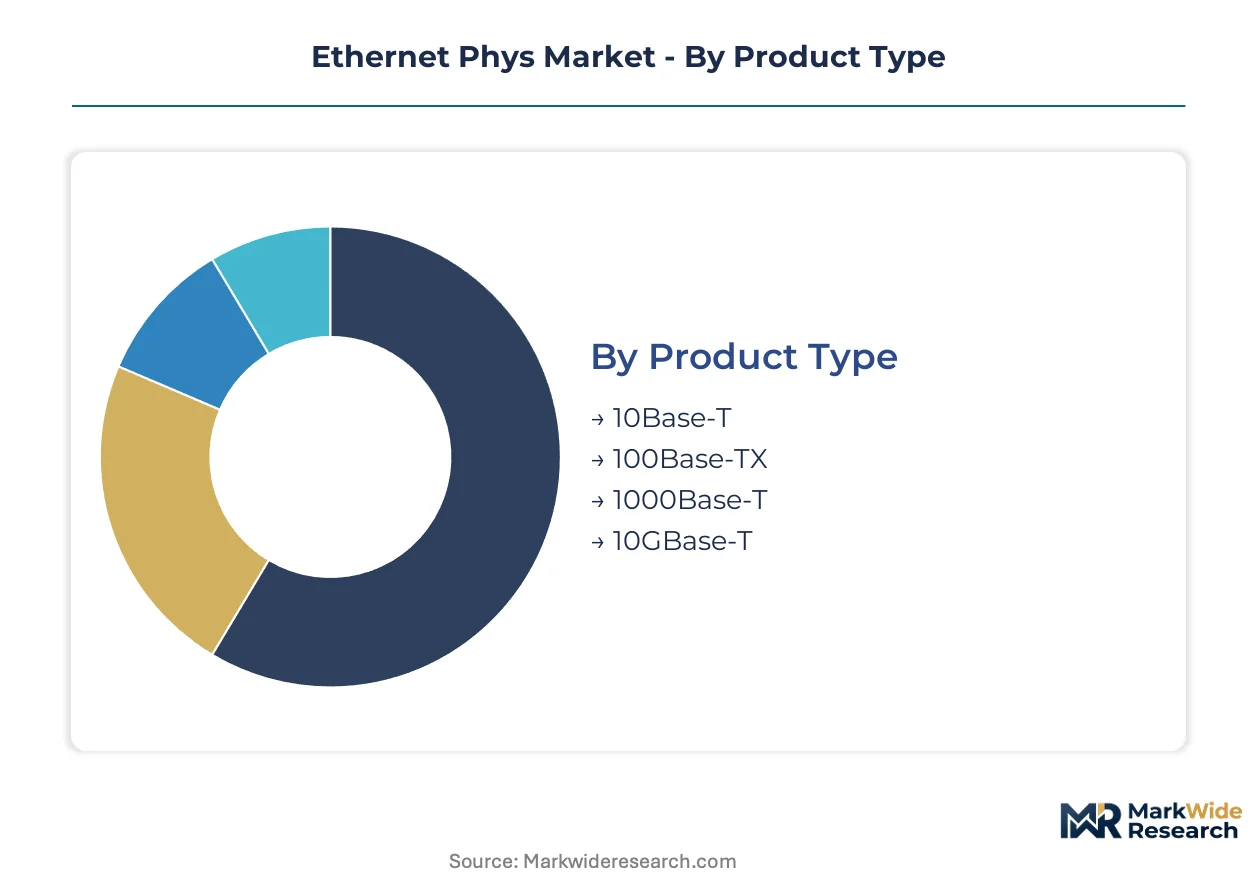
Ethernet PHY segmentation reveals distinct procurement channels and technical requirements across speed grades and media types. Each category channels through different buyer profiles, from hyperscale direct sourcing for high-speed fiber implementations to distributor-mediated enterprise purchasing for copper-based access layers.
Product Type:
Channel mix varies sharply by speed tier, with 10GBase-T and 1000Base-T flowing through broadline distributors while legacy 10Base-T concentrates in industrial surplus channels.
- 10GBase-T:Copper PHYs operating at 10 Gbps over Cat6a cabling with extended reach capabilities. Hyperscale data centers in the United States are standardizing on this speed for server access layers to avoid optical transceiver costs. Signal integrity challenges at 100-meter distances are driving demand for retimer-equipped implementations.
- 1000Base-T:Gigabit Ethernet PHYs dominating enterprise access switch deployments through twisted-pair infrastructure. Educational institutions in Germany and Japan are refreshing campus networks with this speed tier to support hybrid learning bandwidth requirements. Volume concentration here reflects the technology's maturity and broad switch vendor support.
- 10Base-T:Legacy 10 Mbps implementations persisting in industrial control systems and building automation networks.
- 100Base-TX:Fast Ethernet PHYs maintained for compatibility with embedded systems and legacy medical devices.
By volume, 1000Base-T leads. By growth pace, 10GBase-T is expanding most quickly.
Technology:
Cost tier separation is pronounced, with fiber optic implementations commanding 8-12x premiums over twisted pair while Power over Ethernet bridges power delivery and data transmission.
- Fiber Optics:Optical PHYs using laser or LED transmitters across single-mode and multimode fiber for spine and core network applications. Data center operators in the United States are deploying 400G and 800G optical PHYs in AI training clusters to minimize latency between GPU nodes. IEEE 802.3ck electrical specifications are forcing SerDes architecture redesigns ahead of interoperability testing.
- Twisted Pair:Copper PHYs leveraging differential signaling across unshielded or shielded twisted-pair cabling for cost-sensitive access applications. Enterprise IT departments in India favor this technology for office connectivity due to existing Cat5e/Cat6 infrastructure. FCC Part 15 emissions compliance adds validation overhead for implementations above 10 GHz.
- Power over Ethernet:Integrated PHY and power sourcing equipment delivering DC power alongside data for IP cameras and access points.
- Coaxial:Legacy PHY implementations for cable modem and DOCSIS infrastructure in residential broadband networks.
By volume, twisted pair dominates. By margin contribution, fiber optics is ahead.
Application:
Customer maturity profiles diverge, with data center networking demanding 18-24 month product cycles while industrial automation tolerates decade-long lifecycles.
- Data Center Networking:High-speed interconnects for cloud compute and storage fabrics requiring 112 Gbps PAM4 electrical interfaces. Hyperscalers in the United States and China are commissioning custom PHY specifications through switch ASIC co-development programs. Linear pluggable optics pilots are displacing traditional DSP-heavy architectures in 800G links.
- Industrial Automation:Temperature-hardened PHYs for factory floor networks with -40°C to +85°C operating ranges. German automotive manufacturers are requiring full material disclosure documentation under EU RoHS substance restrictions. Long qualification cycles favor incumbent vendors with proven field reliability records.
- Telecommunications:Carrier-grade PHYs for central office and cell site backhaul with synchronization capabilities.
- Home Networking:Consumer-grade PHYs integrated into residential gateways and mesh Wi-Fi systems.
By volume, home networking leads. By technology refresh rate, data center networking is gaining share fastest.
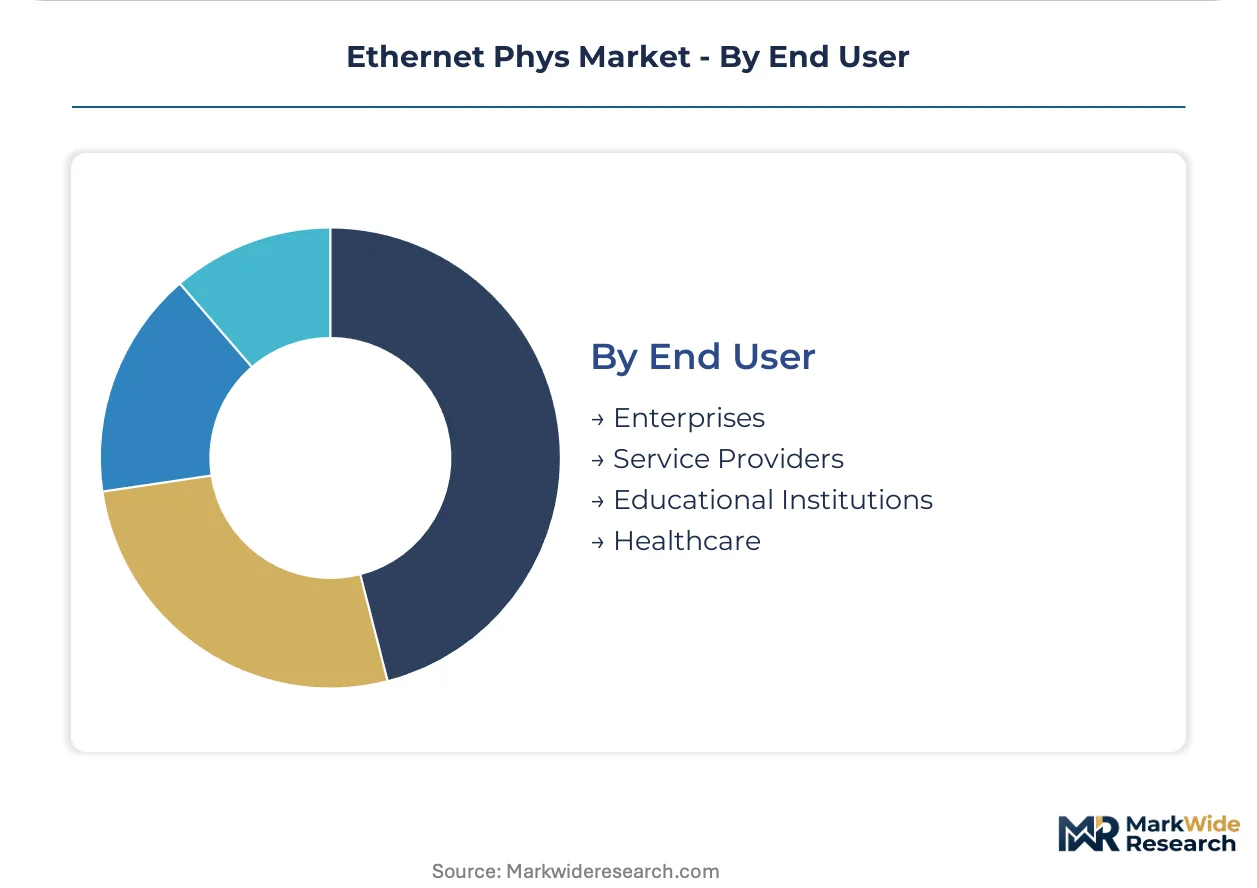
End User:
Procurement authority concentration varies, with service providers consolidating purchasing through direct vendor negotiations while enterprises fragment across IT reseller channels.
- Service Providers:Telecommunications carriers and cloud operators with centralized procurement of high-speed PHYs in 100,000+ unit volumes. Domestic cloud region buildouts by global hyperscalers in India are creating concentrated demand for 100G and 400G implementations. Long-term supply agreements lock specifications years ahead of production ramp.
- Enterprises:Corporate IT departments purchasing through value-added resellers and distributor channels. Healthcare systems in the United States are refreshing network infrastructure to support HIPAA-compliant data segregation. Budget cycles and capital approval processes extend procurement timelines versus service provider direct sourcing.
- Educational Institutions:University and K-12 networks with E-rate funding dependencies in the United States.
- Healthcare:Hospital networks requiring galvanic isolation and electromagnetic immunity certifications.
By volume, enterprises lead. By contract value concentration, service providers are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The subsea cable landing stations at Hillsboro, Oregon and Virginia Beach anchor United States data center interconnect demand for 400G and 800G PHYs. These fiber optic corridors channel transoceanic traffic into hyperscale campuses that commission custom PHY specifications through direct vendor negotiations.
United States
Hyperscaler capex cycles in Northern Virginia and Dallas-Fort Worth drive concentrated bulk purchasing of high-speed transceivers and retimers. FCC Part 15 emissions compliance adds validation overhead for copper PHYs above 10 GHz. The Hillsboro-Oregon fiber corridor channels subsea cable capacity into AI training clusters requiring low-latency interconnects.
China
Domestic cloud operators in Beijing and Shanghai are expanding 400G spine fabric deployments to support AI inference infrastructure. MIIT equipment certification requirements and GB standards compliance shape PHY design roadmaps for local market access. The Yangtze River Delta concentration of switch ASIC vendors enables co-development programs locking specifications years ahead of production.
Germany
Automotive OEMs in Munich and Stuttgart require multi-gigabit Ethernet PHYs for zonal E/E architectures transitioning to centralized compute. EU RoHS substance restrictions and REACH chemical compliance mandate material disclosure documentation from semiconductor suppliers. The Baden-Württemberg industrial automation cluster favors temperature-hardened PHYs with decade-long qualification cycles.
India
Domestic cloud region buildouts by global hyperscalers in Mumbai and Hyderabad are creating demand for 100G and 400G PHYs in greenfield data centers. BIS equipment certification and TRAI infrastructure guidelines influence procurement specifications for telecommunications carriers. The Maharashtra data center corridor channels foreign direct investment into carrier-neutral facilities requiring high-speed interconnects.
Japan
Telecommunications carriers in Tokyo and Osaka are refreshing core networks with 400G coherent optics for 5G backhaul and fronthaul aggregation. METI energy efficiency guidelines and JIS standards compliance shape procurement criteria for enterprise networking equipment. The Kanto region concentration of electronics manufacturers sustains long-term supply agreements for industrial-grade PHY implementations.
Ethernet Phys Market Vendor Landscape
Listed leaders compete with private specialists across merchant silicon and captive supply dimensions. The vendor base stratifies into three tiers: diversified semiconductor conglomerates with broad PHY portfolios, fabless specialists concentrating on high-speed SerDes architectures, and industrial-grade niche suppliers with extended temperature specifications. Strategic moves center on switch ASIC co-development programs and silicon photonics integration partnerships that lock specifications years ahead of volume ramps.
Within the diversified semiconductor tier, Broadcom Inc. and Marvell Technology occupy positions defined by merchant silicon scale across PAM4 PHY implementations. Texas Instruments exemplifies the industrial-grade niche archetype where extended reliability specifications command premium positioning. Realtek Semiconductor anchors the high-volume gigabit Ethernet segment serving enterprise access layer refresh cycles.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Marvell Technology |
| Realtek Semiconductor |
| Texas Instruments |
| Microchip Technology |
| NXP Semiconductors |
| Analog Devices |
| Intel Corporation |
| Qualcomm |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between hyperscalers and PHY vendors lock in both wafer capacity allocation and price visibility across 400G and 800G product generations. These multi-year contracts insulate buyers from spot-market volatility in advanced packaging while securing foundry slots for PAM4 SerDes tape-outs ahead of IEEE 802.3dj ratification deadlines.
Pricing Analysis
Volume-discount tiering structures separate hyperscale direct purchasers from enterprise distributor channels, with the former capturing 30-40% unit cost advantages at 100,000+ port commitments. Certification-grade differentiation separates automotive temperature-hardened PHYs from commercial-temperature implementations, while FCC Part 15 pre-compliance testing adds non-recurring engineering overhead that concentrates in sub-10,000 unit orders. Cost compression in 800G optical modules intensifies as linear pluggable optics pilots displace DSP-heavy retimer architectures. Enterprise IT departments exhibit highest price sensitivity, whereas AI training cluster operators prioritize latency specifications over per-port expenditure.
Supply Chain Analysis
Strait of Malacca transit lanes anchor substrate and advanced packaging material flows from Taiwan-based foundries to assembly and test facilities across Southeast Asia. 2.5D interposer manufacturing concentrates in Taiwan and South Korea, while silicon photonics integration capacity expands in the United States and China. Gallium arsenide laser sources and silicon germanium modulator wafers constitute critical input dependencies. Single-source vulnerability in CoWoS capacity creates allocation risk during hyperscaler capex surges. Distribution runs through direct vendor negotiations for high-speed tiers and broadline electronics distributors for gigabit access products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margin compression across 400G and 800G PHY generations elevates firmware customization and field application engineering as the fastest-expanding recurring-revenue layer. Service-attach contracts for SerDes tuning and interoperability validation now outpace silicon ASP growth in contract value per port.
For Market Incumbents: Fortify switch ASIC co-development relationships by embedding PHY specification teams within hyperscaler platform engineering organizations. Deepen backward integration into silicon photonics foundry partnerships to secure linear drive optics capacity ahead of 1.6 TbE demand inflection. Marvell Technology and Broadcom Inc. already anchor this pattern; challengers must match foundry reservation scale or cede 800G+ design wins. For New Entrants and Emerging Players: Lead with industrial temperature-grade PHY specifications for German automotive zonal architectures, where decade-long qualification cycles and material disclosure requirements create incumbent stickiness that rewards early design win accumulation. Target Tier-1 supplier procurement committees in Stuttgart and Munich with REACH-compliant documentation packages. License SerDes IP from Israel-based analog specialists to bypass talent scarcity in 56 Gbaud PAM4 equalization. For Investors and Strategic Acquirers: Fabless PHY specialists with locked foundry capacity and active optical cable integration capabilities represent the most defensible acquisition archetype as linear pluggable optics displaces retimer-based supply chains. Monitor IEEE 802.3dj interoperability testing bottlenecks at third-party labs as an inflection indicator—tape-out delays signal R&D investment risk for vendors without pre-qualified SerDes architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Switch ASIC Co-Development Program | Locks PHY specifications years ahead of hyperscaler production ramps in Northern Virginia campuses. |
| Silicon Photonics Integration Partnership | Enables lower-power 800G optical modules for AI training clusters in Hillsboro-Oregon fiber corridors. |
| Automotive Temperature-Grade Certification | Opens design wins at Munich OEMs transitioning to zonal E/E architectures under EU RoHS mandates. |
| Linear Pluggable Optics Pilot Deployment | Displaces DSP-heavy retimers in United States cloud operator 800G links to reduce power and latency. |
| India Data Center Supply Agreement | Captures 100G and 400G demand from Mumbai and Hyderabad greenfield buildouts under BIS certification. |
Methodological Framework
The analysis maps PAM4 SerDes architectures, copper versus fiber optic media implementations, and temperature-grade specifications, each validated through semiconductor design executives, hyperscale network procurement officers, and Tier-1 automotive supplier engineering leads. Primary fieldwork combined with secondary validation against IEEE 802.3 standards documentation, FCC Part 15 equipment authorization databases, and SEC 10-K hyperscaler capex disclosures. Bottom-up unit demand modeling from switch port shipments and top-down value triangulation from foundry revenue disclosures cross-checked segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled speed tier migration curves, media type substitution elasticities, and geographic demand concentration by cloud region buildout schedules. CAGRs derived from segment-level unit ramp assumptions and ASP decay functions tied to process node transitions. Forecast inputs incorporated foundry capacity expansion timelines and IEEE standards ratification schedules without specific year anchoring.
Forecasts assume regulatory continuity in FCC emissions testing regimes and EU RoHS substance restriction thresholds; material policy shifts would require re-modeling. Technology transition risk from NRZ to PAM4 modulation and linear drive optics displacement of DSP architectures may accelerate or delay segment trajectories. Practitioners should keep alternative scenarios live as hyperscaler capex cycles and foundry allocation priority shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market