
 4D Radar Chip Market | 2026-2036
4D Radar Chip Market Size, Share, and Industry Trends Forecast 2026-2036
4D Radar Chip Market Insights
Software-defined radar feature licensing is realigning how chip vendors monetize hardware platforms. NXP Semiconductors leverages its S32R processor family to anchor long-term service contracts with European Tier-1 suppliers. Texas Instruments competes through integrated mmWave AWR device portfolios that sustain design-win momentum across North American and Asian automotive programs.
A 4D radar chip integrates multiple transmit-receive channels on a single die to detect range, velocity, azimuth, and elevation simultaneously, typically operating at 76-81 GHz with sub-degree angular resolution for real-time object discrimination. Automotive radar dominates volume demand as collision avoidance mandates harden across major vehicle markets, while defense radar commands premium pricing for target tracking applications requiring hardened GaN front-ends. Microwave technology retains installed-base dominance, though solid-state architectures are displacing legacy pulsed systems in next-generation autonomous driving platforms where fast chirp modulation enables simultaneous long-range detection and high-resolution mapping.
FCC spectrum allocations in the United States govern 76-81 GHz operation and directly determine chipset architecture roadmaps for domestic suppliers. ECE R79 in Europe and NHTSA FMVSS in the United States create divergent test-protocol requirements that force dual-validation investments. Stakeholders must monitor whether China's MIIT extends domestic frequency harmonization to match WRC-23 allocations, as this would reshape foundry priorities and export qualification burdens for non-Chinese vendors.
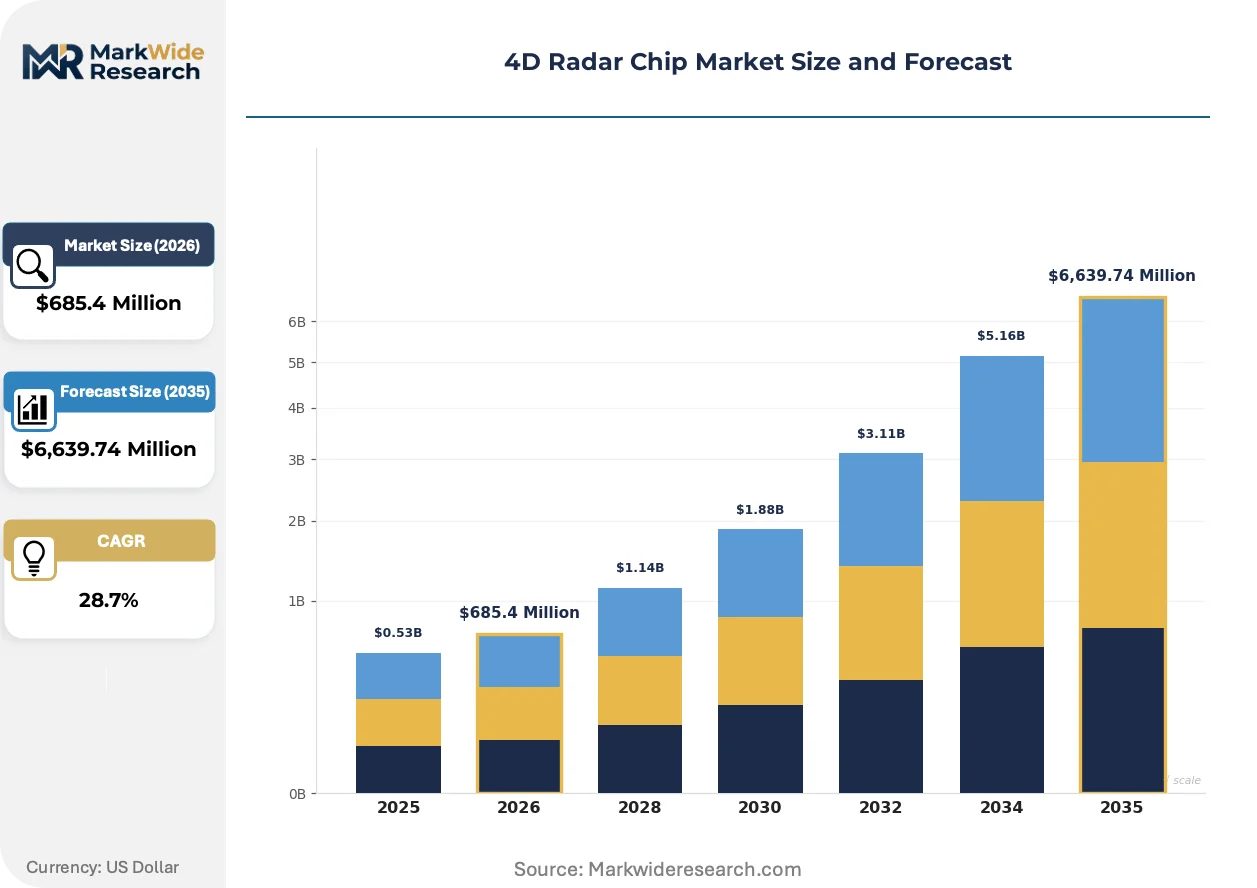
Market Dynamics
Solid-state architectures are compressing design cycles for 77-81 GHz automotive radar, as GaN-on-SiC wafer availability from Yangtze River Delta foundries reconfigures procurement economics for Tier-1 suppliers.
Growth Catalysts
- NHTSA FMVSS pedestrian-detection mandates:United States crash-avoidance standards now require validated 4D imaging radar, compelling Tier-1 suppliers to accelerate chipset qualification timelines for domestic OEM platforms.
- GaN-on-SiC wafer scaling:MIIT-backed fabrication facilities in China's Yangtze River Delta are ramping 77-81 GHz production, creating captive supply for domestic EV supply chains and export-qualified capacity.
- Level 3 autonomous driving procurement:Automotive OEMs in Germany and Japan are scaling solid-state radar chipset orders, embedding 4D capability into highway-automation platforms ahead of 2025 model-year launches.
Market Restraints
- Dual-validation cost burden:ECE R79 European test protocols diverge from NHTSA FMVSS requirements, forcing chipset vendors to maintain parallel certification tracks for transatlantic automotive programs.
- Frontend material concentration:Hardened GaN power amplifiers for defense-grade target tracking depend on limited North American and European substrate suppliers, creating single-source vulnerability for premium radar segments.
- Millimeter-wave thermal constraints:76-81 GHz operation at sub-degree angular resolution generates die-level heat dissipation challenges that constrain packaging density and long-term reliability metrics.
Strategic Opportunities
- WRC-23 frequency harmonization:China's MIIT may extend domestic 76-81 GHz allocations to match international standards, enabling simplified export qualification for non-Chinese chipset vendors and reshaping foundry prioritization.
- Software-defined feature licensing:Processor-anchored service contracts allow chip vendors to monetize hardware platforms through recurring revenue streams rather than one-time silicon sales.
- Defense target-tracking premiumization:Hardened GaN front-ends for military applications command pricing multiples above automotive volumes, attracting specialized foundry investment from European and North American suppliers.
Industry Challenges
- Millimeter-wave RF engineering scarcity:Design of 76-81 GHz transmit-receive channels with sub-degree angular resolution requires specialized simulation expertise that concentrates in German and Japanese engineering centers.
- Automotive-grade qualification timelines:AEC-Q100 stress testing and ISO 26262 functional safety certification for 4D radar SoCs extend development cycles beyond 36 months, compressing return-on-investment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4D Radar Chip Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $6,639.74 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Radar, Aerospace Radar, Industrial Radar, Defense Radar Technology: Microwave, Solid-State, Frequency Modulated, Pulsed End User: OEMs, Tier-1 Suppliers, Military, Aviation Application: Collision Avoidance, Autonomous Driving, Target Tracking, Weather Monitoring |
| Companies Covered | NXP Semiconductors, Robert Bosch GmbH, Infineon Technologies AG, Texas Instruments, Continental AG, Renesas Electronics Corporation, ZF Friedrichshafen AG, Arbe Robotics, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4D Radar Chip Market Trends and Innovations
Fast chirp modulation techniques are collapsing the traditional trade-off between long-range detection and high-resolution mapping, enabling simultaneous object discrimination across multiple automotive use cases.
Silicon-germanium BiCMOS front-end integration is absorbing discrete gallium arsenide components in cost-sensitive automotive radar modules. Mid-range ADAS suppliers in South Korea and Taiwan are adopting these consolidated designs to reduce bill-of-materials complexity. The technology is absorbing market share from legacy multi-chip configurations by delivering comparable range performance at wafer-scale economics.
ECE R79 lane-keeping and blind-spot monitoring mandates in Europe are hardening technical specifications for angular resolution and velocity precision. Tier-1 suppliers must now validate elevation-detection capability that exceeds prior planar radar generations. German automotive programs are responding by specifying 4D imaging radar as baseline equipment for premium vehicle platforms launching in 2025.
Automotive OEMs are consolidating radar chipset procurement around processor-integrated platforms that bundle signal processing with RF front-ends. Long-term service contracts tied to software-defined feature activation are displacing discrete hardware purchasing for North American and European vehicle programs. This contractual evolution is most visible in Germany, where NXP Semiconductors anchors multi-year supply agreements with established Tier-1 radar module manufacturers.
4D Radar Chip Market Segmentation
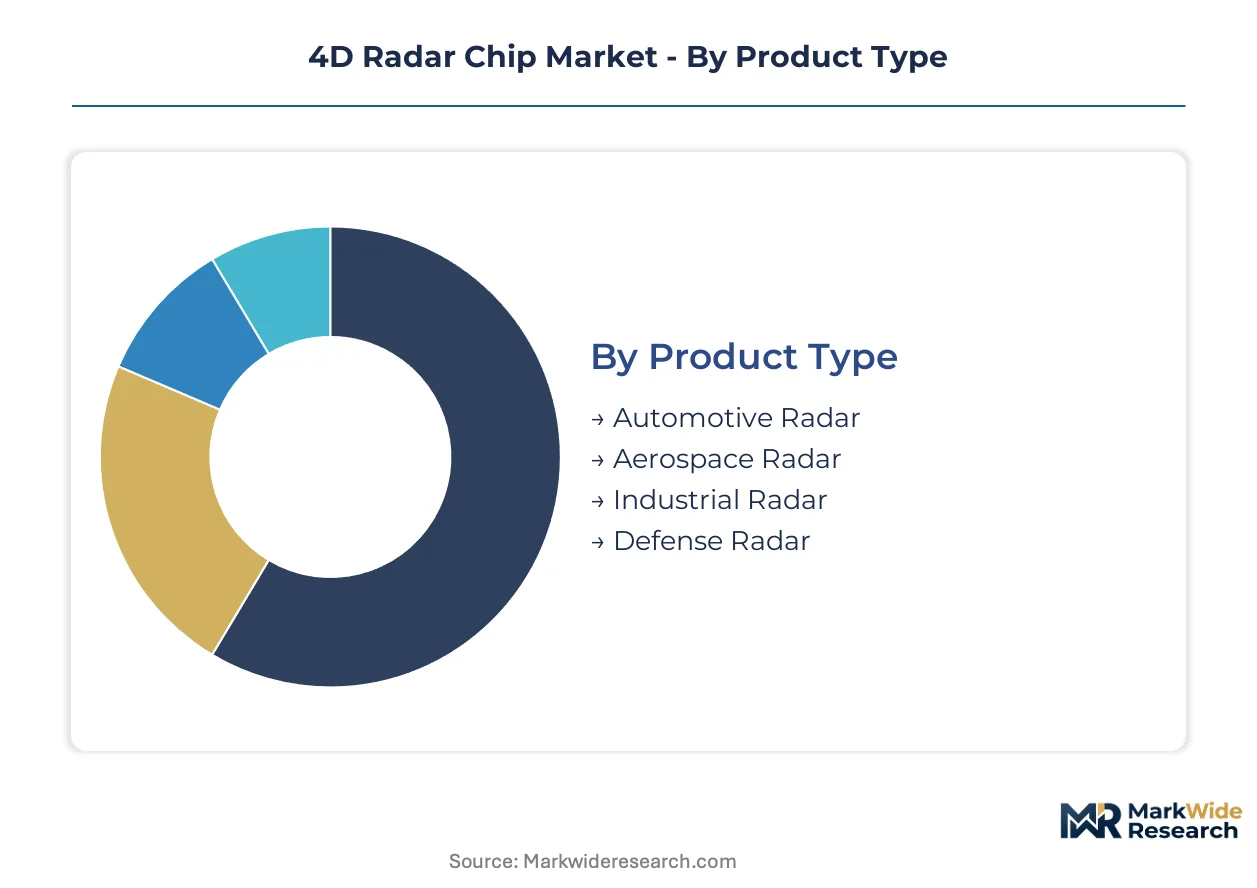
4D radar chip procurement splits across fundamentally different capital requirements, from automotive volume plays demanding wafer-scale economies to defense programs tolerating premium GaN front-end costs. Understanding these investment profiles clarifies why foundry capacity allocates unevenly across segments.
Product Type:
Capital intensity peaks in defense-grade GaN-on-SiC fabrication, where hardened substrates and military qualification layers compound upfront spend.
- Automotive Radar:Silicon-germanium BiCMOS integration dominates this segment, absorbing discrete GaAs components to hit cost targets for mid-range ADAS modules. German and Japanese OEMs are scaling solid-state radar chipset orders for Level 3 highway-automation platforms, embedding 4D capability as baseline equipment ahead of model-year launches.
- Defense Radar:Hardened GaN power amplifiers command pricing multiples above automotive volumes, with target-tracking applications requiring specialized North American and European substrate suppliers. Limited foundry access and extended military qualification timelines create single-source vulnerability and premium procurement economics.
- Aerospace Radar:Weather-monitoring and navigation systems in commercial aviation demand reliability certifications that extend development cycles.
- Industrial Radar:Factory automation and perimeter security applications operate at lower volumes with reduced spectral performance requirements.
Automotive radar absorbs the bulk of installed capacity; defense radar is expanding most quickly on a revenue-per-wafer basis.
Technology:
Process maturity varies sharply, with legacy microwave retaining installed-base dominance while solid-state architectures capture autonomous driving design wins.
- Solid-State:Fast chirp modulation enables simultaneous long-range detection and high-resolution mapping, collapsing traditional performance trade-offs. MIIT-backed fabs in China's Yangtze River Delta are ramping 77-81 GHz GaN-on-SiC production specifically for this architecture, reconfiguring procurement economics for Tier-1 suppliers.
- Microwave:Legacy pulsed systems retain dominance in weather-monitoring and certain aerospace applications where proven reliability outweighs modulation flexibility. Installed base concentration in North American and European defense programs sustains procurement, though design-win momentum shifts toward solid-state alternatives.
- Frequency Modulated:Continuous-wave variants serve cost-sensitive industrial and short-range automotive applications.
- Pulsed:Traditional architectures persist in long-range target-tracking systems requiring peak power handling.
Solid-state platforms command the steepest expansion trajectory; microwave retains the largest installed base.
End User:
Customer concentration patterns determine contract structure, from OEM direct procurement to military specification-driven programs.
- Tier-1 Suppliers:Radar module manufacturers in Germany and North America anchor long-term service contracts with processor-integrated platforms. NHTSA FMVSS pedestrian-detection mandates now compel accelerated chipset qualification timelines, compressing vendor selection windows.
- OEMs:Automotive manufacturers in Germany and Japan are consolidating procurement around software-defined radar feature licensing, displacing discrete hardware purchasing for premium vehicle programs.
- Military:Defense agencies specify hardened GaN front-ends with extended qualification protocols and captive supply requirements.
- Aviation:Commercial airframers and regional operators source weather and navigation radar through specialized aerospace Tier-1 channels.
Tier-1 suppliers manage the majority of design-in activity; OEM direct procurement is climbing fastest.
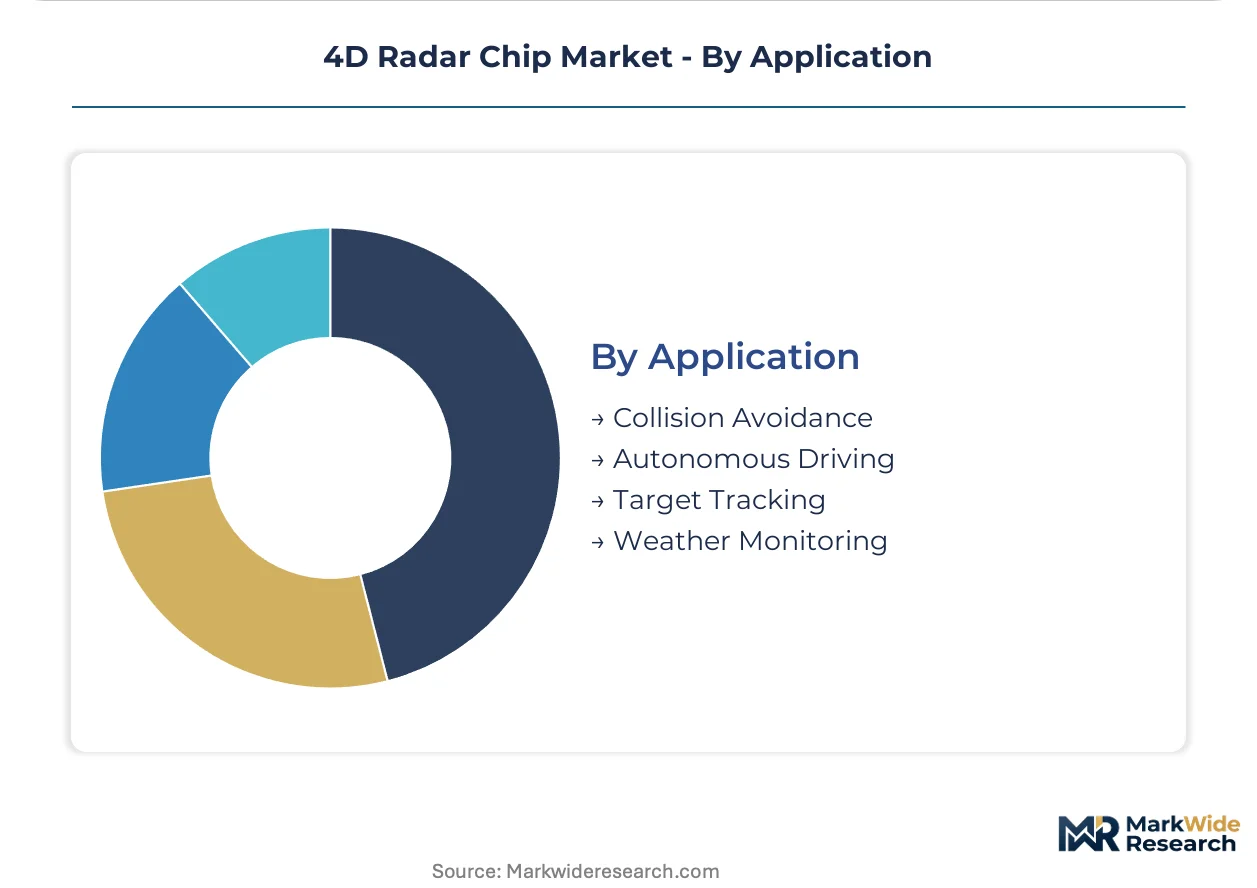
Application:
Functional requirements diverge on angular resolution, with autonomous driving demanding sub-degree precision across four dimensions.
- Autonomous Driving:Level 3 platforms require validated 4D imaging radar with elevation detection exceeding prior planar generations. ECE R79 lane-keeping and blind-spot monitoring mandates in Europe are hardening these specifications, with German automotive programs responding by specifying 4D capability as standard equipment.
- Collision Avoidance:ADAS penetration across vehicle price tiers drives volume demand, with NHTSA FMVSS updates in the United States compelling Tier-1 suppliers to validate pedestrian-detection capability. Silicon-germanium BiCMOS consolidation reduces bill-of-materials complexity for mid-range suppliers in South Korea and Taiwan.
- Target Tracking:Defense applications prioritize range precision and electronic counter-countermeasures resilience over cost minimization.
- Weather Monitoring:Aviation and meteorological agencies require proven reliability in severe environmental conditions.
Collision avoidance commands the largest volume footprint; autonomous driving exhibits the steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity concentrates in East Asia while design validation and Tier-1 integration cluster in Western Europe and North America. This geographic split shapes procurement patterns and regulatory compliance burdens across the value chain.
United States
NHTSA FMVSS pedestrian-detection mandates compel Tier-1 suppliers to accelerate 4D imaging radar qualification for domestic OEM platforms. FCC spectrum allocations at 76-81 GHz directly determine chipset architecture roadmaps for suppliers serving the North American market. Engineering talent for millimeter-wave RF design clusters in Austin and Boston metro areas, anchoring simulation expertise for sub-degree angular resolution development.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are scaling solid-state radar chipset procurement for Level 3 highway-automation platforms launching ahead of 2025 model years. ECE R79 lane-keeping and blind-spot monitoring mandates harden technical specifications for elevation detection beyond prior planar radar generations. Stuttgart and Ingolstadt industrial corridors anchor long-term service contracts between processor-integrated platform vendors and established radar module manufacturers.
China
MIIT-backed fabrication facilities in the Yangtze River Delta are ramping 77-81 GHz GaN-on-SiC wafer production specifically for domestic EV supply chains. The Ministry of Industry and Information Technology governs frequency allocations that may extend to match WRC-23 international standards, reshaping export qualification burdens. Shanghai and Suzhou foundry clusters are reconfiguring procurement economics for Tier-1 suppliers globally through scaled capacity deployment.
Japan
Automotive OEMs in the Kanto and Chubu regions are embedding 4D radar capability as baseline equipment for premium vehicle platforms responding to ECE R79-equivalent domestic safety mandates. METI industrial policy supports semiconductor supply chain resilience investments targeting 76-81 GHz device production. Nagoya engineering centers concentrate specialized simulation expertise for fast chirp modulation architectures that enable simultaneous long-range detection and high-resolution mapping.
South Korea
Mid-range ADAS suppliers in Gyeonggi-do and Busan-Ulsan industrial belts are adopting silicon-germanium BiCMOS front-end integration to reduce bill-of-materials complexity. MFDS-equivalent automotive safety regulations align with international crash-avoidance standards, validating pedestrian-detection capability requirements. Seoul Capital Area design houses are consolidating radar chipset procurement around processor-integrated platforms that bundle signal processing with RF front-ends.
4D Radar Chip Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent investment profiles in the 4D radar chip ecosystem. The vendor base segments into three strategic tiers: integrated semiconductor conglomerates with captive foundry access, fabless radar specialists relying on external fabrication, and Tier-1 module manufacturers backward-integrating into chipset design. Competitive moves concentrate on long-term service contract anchoring with automotive OEMs and foundry capacity reservation agreements for GaN-on-SiC wafer supply.
Among European-integrated semiconductor suppliers, NXP Semiconductors, Infineon Technologies AG, and Robert Bosch GmbH exemplify the processor-integrated platform archetype. These entities occupy positions that leverage automotive-grade qualification heritage and established Tier-1 relationships. Texas Instruments represents the North American mmWave device portfolio approach, while Arbe Robotics and Huawei Technologies sit within the fabless specialist tier pursuing software-defined feature differentiation. The competitive dynamic pivots on whether service-contract monetization or discrete hardware scale economics proves more durable across autonomous driving procurement cycles.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| Texas Instruments |
| Continental AG |
| Renesas Electronics Corporation |
| ZF Friedrichshafen AG |
| Arbe Robotics |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
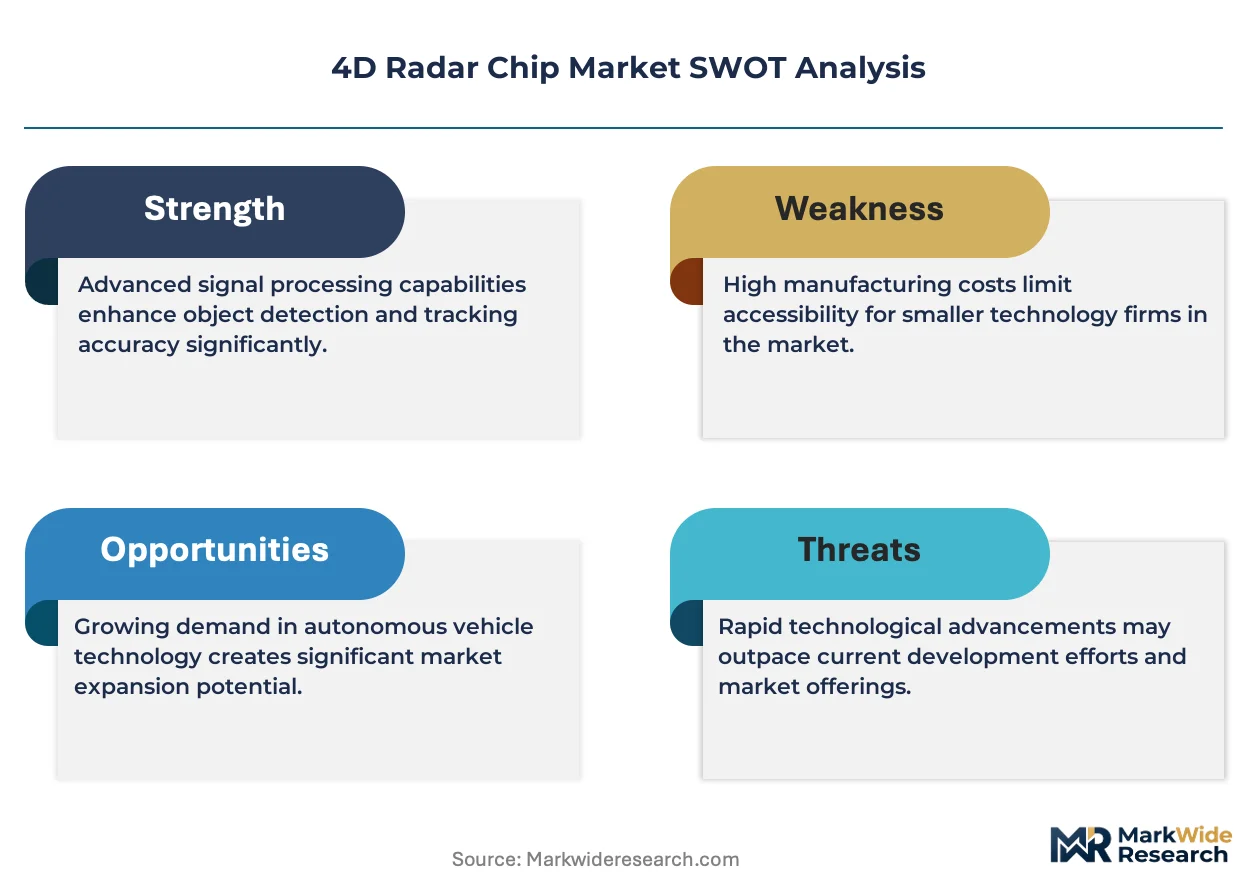
Captive GaN-on-SiC wafer production in China's Yangtze River Delta anchors both supply security and pricing power for domestic EV supply chains, while forcing non-Chinese vendors into dual-source qualification investments that compress margins.
Pricing Analysis
Cost-down pressure on mid-range ADAS modules accelerates as silicon-germanium BiCMOS integration absorbs discrete GaAs components, collapsing bill-of-materials complexity for South Korean and Taiwanese suppliers. Three-tier pricing structure across premium defense-grade GaN front-ends, standard automotive radar SoCs, and economy industrial modules reflects certification grade and volume scale divergence. Pricing pressure stems from MIIT-backed foundry scaling in China, which reconfigures procurement economics globally. Tier-1 suppliers in Germany exhibit lowest price sensitivity due to long-term service contract anchoring, while mid-range module manufacturers in South Korea face acute margin compression.
Supply Chain Analysis
Dual-sourcing mandates from German and Japanese OEMs compel Tier-1 suppliers to qualify GaN-on-SiC wafers from both Yangtze River Delta foundries and North American substrate vendors, extending lead times for defense-grade target-tracking applications. Raw material dependencies center on silicon carbide substrates, gallium nitride epitaxy services, and 77-81 GHz RF packaging materials. Single-source vulnerability concentrates in hardened GaN power amplifiers for military applications, where limited North American and European substrate suppliers create procurement bottlenecks. Distribution runs through processor-integrated platform vendors anchoring multi-year service contracts with established radar module manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA FMVSS pedestrian-detection mandates erect a cost-of-compliance barrier that rewards chipset vendors with validated AEC-Q100 and ISO 26262 certification heritage, while disqualifying unqualified entrants from Tier-1 supplier qualification windows.
For Market Incumbents: To counter margin erosion from MIIT-backed Chinese foundry scaling, deepen backward integration into GaN-on-SiC substrate supply through captive North American wafer agreements, and anchor processor-integrated platform stickiness via software-defined feature licensing contracts that displace discrete hardware purchasing. For New Entrants and Emerging Players: Capture white-space in industrial radar perimeter security applications where spectral performance requirements lag automotive specifications, and pursue fabless specialization in fast chirp modulation IP licensing to Tier-1 suppliers seeking to bypass NRE-heavy in-house development. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-grade radar SoC specialists with validated ECE R79 and NHTSA FMVSS dual-certification tracks; the signal to watch is MIIT frequency harmonization alignment with WRC-23, which would trigger foundry prioritization shifts and acquisition premium repricing for export-qualified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Wafer Supply Agreement | Captive substrate access insulates Tier-1 suppliers from Yangtze River Delta capacity competition. |
| Software-Defined Feature Licensing | Processor-anchored service contracts transform NXP Semiconductors' S32R platforms into recurring revenue engines. |
| ECE R79 Dual-Validation Investment | Parallel certification tracks with NHTSA FMVSS unlock transatlantic automotive program access for chipset vendors. |
| Defense-Grade GaN Front-End Qualification | Hardened target-tracking applications command pricing multiples that attract specialized European foundry investment. |
| Fast Chirp Modulation IP Development | Sub-degree angular resolution expertise concentrates in Nagoya and Stuttgart engineering centers, creating talent moats. |
Research Methodology
SEC 10-K filings, ECE R79 regulatory submissions, and MIIT production statistics formed the secondary backbone, cross-referenced with primary interviews involving Tier-1 radar module procurement directors, OEM platform engineers, GaN foundry operations managers, and NHTSA regulatory affairs specialists. Bottom-up and top-down triangulation validated shipment estimates against wafer capacity announcements and vehicle production databases.
Bottom-up modeling segmented the market by product type, technology architecture, end-user procurement pattern, and application functional requirement across the projection horizon. CAGRs derived from regression analysis of historical qualification timelines, foundry capacity ramps, and regulatory mandate enforcement schedules. Industry-specific inputs included AEC-Q100 stress testing duration assumptions and ISO 26262 ASIL-D certification completion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT frequency harmonization decisions, GaN substrate supply expansion, and Level 3 autonomous driving platform launch delays. Deviation in WRC-23 allocation adoption timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Ethernet Access Device Market