
 Intelligent Cockpit Chip Market | 2026-2036
Intelligent Cockpit Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Cockpit Chip Market Insights
Software-defined cockpit features delivered through over-the-air subscription tiers is consolidating what automakers monetize beyond hardware sales. Qualcomm leverages its Snapdragon Digital Chassis platform to anchor premium infotainment contracts with luxury vehicle programs across North America and Europe. NVIDIA competes through its Drive Thor architecture, specializing in unified AI compute for both autonomous and cockpit workloads. NXP Semiconductors sustains broad Tier-1 supplier relationships with microcontrollers that dominate instrument cluster and body domain controller sockets.
An intelligent cockpit chip is a heterogeneous system-on-chip or discrete semiconductor component engineered to process multimodal sensor inputs, graphics rendering, and neural inference within thermal envelopes typically below 15 watts for passenger vehicle dashboards. These devices integrate CPU clusters, GPU cores, and dedicated AI accelerators on advanced process nodes to enable real-time driver monitoring, augmented reality navigation, and natural language command processing. Processors command the dominant share of value within product type segmentation due to their central role in consolidating multiple cockpit domains onto single compute platforms. Artificial Intelligence within technology segmentation represents the fastest-expanding capability layer, as automakers deploy transformer-based voice models and gaze-tracking algorithms that require dedicated neural processing units. OEM direct procurement within end user segmentation is displacing traditional Tier-1 mediated chip sourcing, as Volkswagen, Mercedes-Benz, and BYD establish their own semiconductor architecture teams and negotiate silicon supply agreements directly with foundries and chip designers.
NHTSA in the United States and ECE R79 in Europe mandate driver availability monitoring for partial automation systems, forcing chip architectures to embed dedicated computer vision accelerators and functional safety cores certified to ISO 26262 ASIL-B or higher. China's MIIT enforces GB standards for intelligent connected vehicles that require domestic certification of cockpit processors handling location data and biometric information, creating market access conditions favoring local designers like SiEngine Technology. Stakeholders must monitor how regional data sovereignty rules fragment chip certification requirements and whether automakers will accept silicon supply diversification into country-specific architectures or insist on globally portable cockpit compute platforms.
Market Dynamics
Consolidation of cockpit compute domains onto single heterogeneous system-on-chips is forcing chip architects to reconfigure thermal budgets and functional safety certifications around unified AI inference and graphics rendering pipelines.
Growth Catalysts
- NHTSA Driver Monitoring Mandates:United States regulations requiring driver availability verification for partial automation systems are embedding computer vision accelerators and ISO 26262 ASIL-B cores into cockpit processor designs.
- GB Standards in China:MIIT certification requirements for intelligent connected vehicles handling biometric and location data are accelerating domestic co-development between foundries and automotive OEMs.
- Transformer-Based Voice Models:Natural language processing architectures requiring dedicated neural processing units are pulling AI accelerator allocation upward within cockpit chip floorplans.
Market Restraints
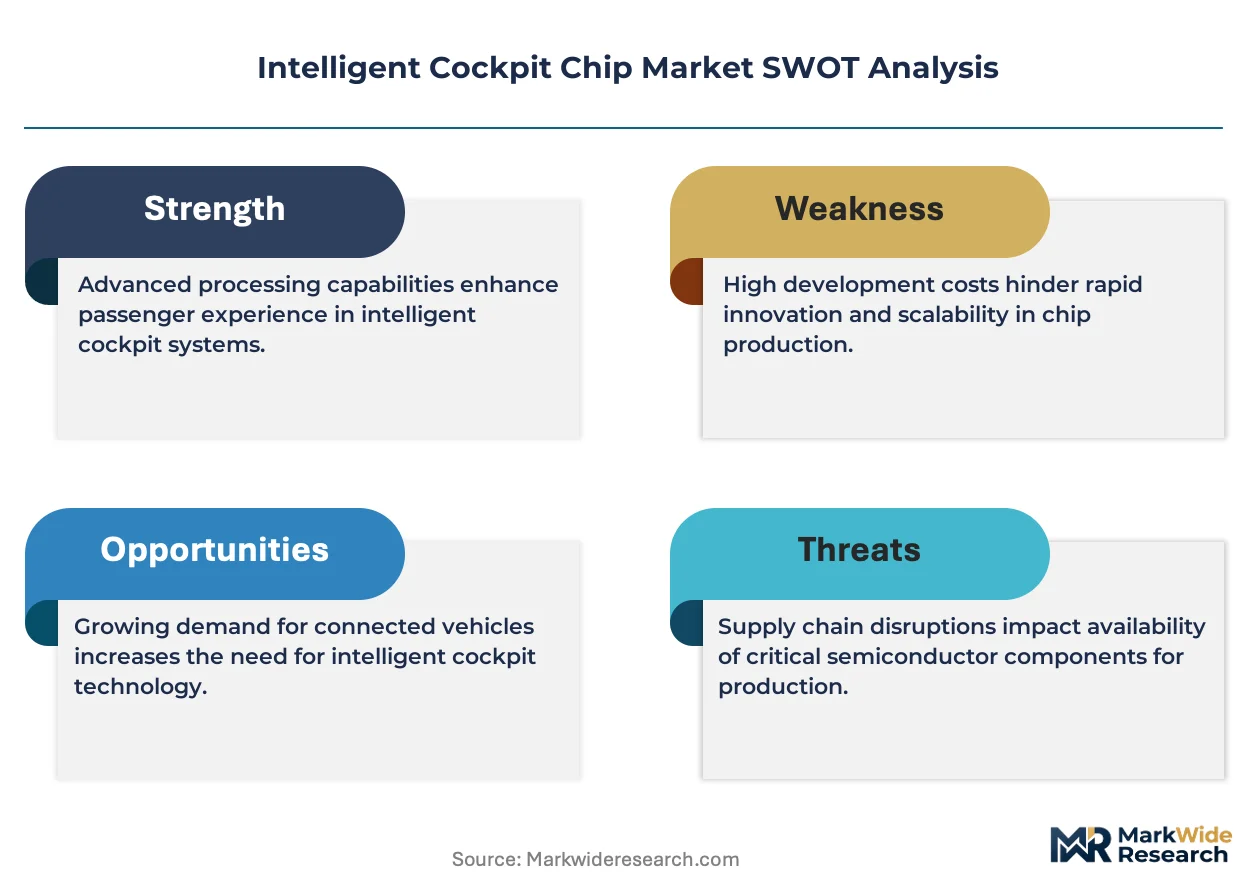
- Advanced Node Concentration:Leading-edge logic production for heterogeneous cockpit SoCs clusters at Taiwan and South Korea foundries, exposing supply continuity to geopolitical friction.
- Functional Safety Certification Burden:ISO 26262 ASIL-D qualification timelines for instrument cluster integration extend 18-24 months, compressing design windows for new vehicle programs.
- Legacy Architecture Lock-In:Existing body domain controller and instrument cluster microcontroller sockets at Tier-1 suppliers resist rapid migration to consolidated cockpit compute platforms.
Strategic Opportunities
- Software-Defined Subscription Tiers:Over-the-air feature activation for augmented reality navigation and personalized HMI profiles is creating recurring revenue streams detached from hardware shipment cycles.
- India Production Linked Incentive:PLI scheme disbursements for semiconductor and automotive component manufacturing are attracting assembly and test capacity for cockpit chips serving domestic vehicle programs.
- Unified Autonomous-Cockpit Convergence:AI compute architectures spanning both driver assistance and cabin intelligence are collapsing separate controller categories into single silicon footprints.
Industry Challenges
- Cross-Domain Talent Scarcity:Functional safety engineering expertise combined with neural network optimization skills concentrates at a handful of design houses and automotive electronics divisions.
- Legacy Fleet Integration Complexity:Backward compatibility requirements for CAN and LIN bus architectures in existing vehicle parcs constrain cockpit processor I/O configuration flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Cockpit Chip Market |
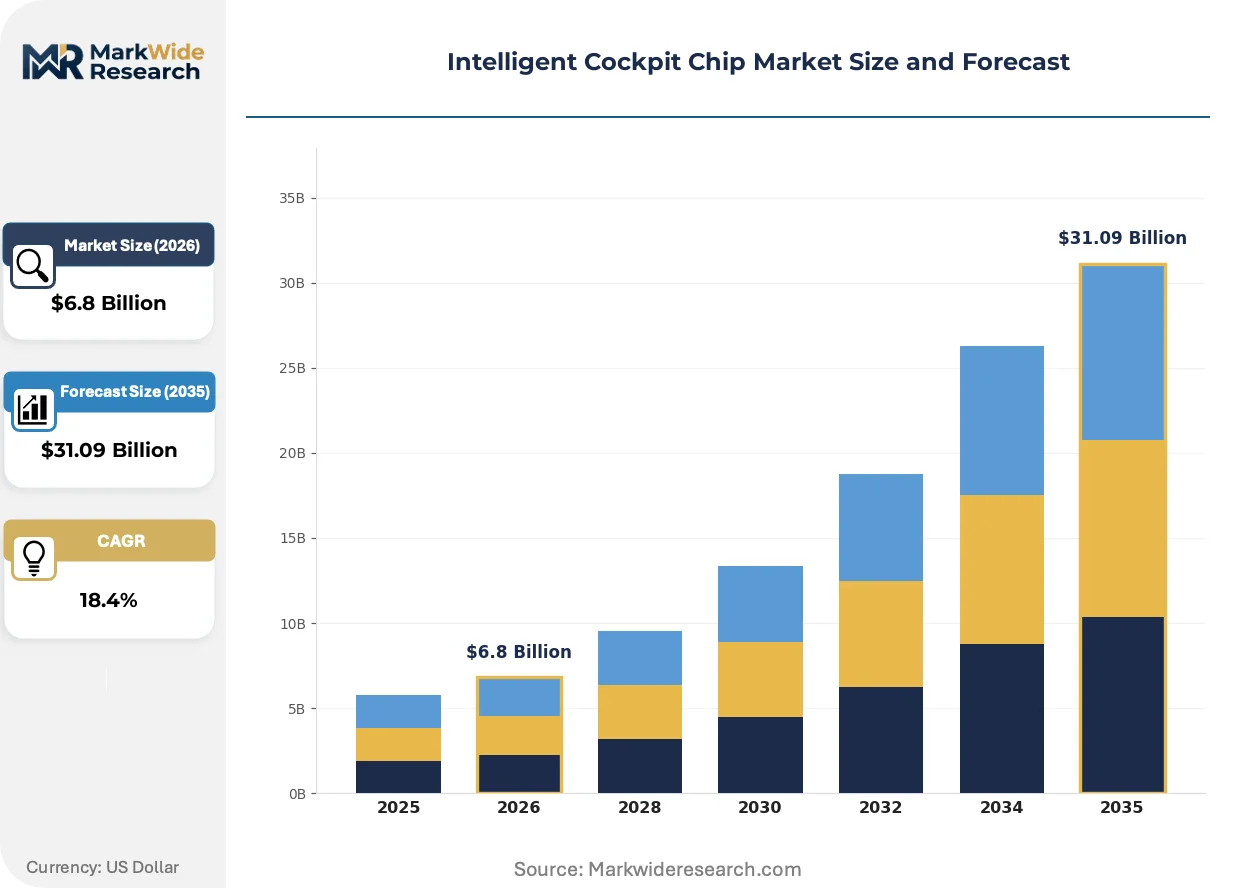
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Processors, FPGA, ASIC Technology: Artificial Intelligence, Machine Learning, Natural Language Processing, Computer Vision End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Application: Navigation Systems, Infotainment, Driver Assistance, Telematics |
| Companies Covered | Qualcomm, NXP Semiconductors, Renesas Electronics, Infineon, Huawei Technologies, SiEngine Technology, Intel, NVIDIA, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Cockpit Chip Market Trends and Innovations
Multimodal sensor fusion and generative AI interfaces are compressing the boundary between autonomous driving compute and cabin intelligence, reshaping how silicon architects partition thermal and safety budgets.
Heterogeneous system-on-chips with dedicated neural processing units are expanding into premium and mass-market vehicle segments simultaneously. Mercedes-Benz and BYD procurement teams are specifying unified AI inference engines for both gaze-tracking and voice command processing. This convergence is expanding into territory previously served by discrete microcontroller and DSP combinations, collapsing multiple socket categories.
ECE R79 regulations in Europe mandate hands-free control system availability for partial automation, compelling chip designers to embed redundant functional safety cores alongside primary application processors. German KBA type-approval processes now require documented failure mode coverage for driver monitoring camera pipelines. Premium OEMs in Stuttgart and Munich are responding by qualifying dual-core lockstep architectures for instrument cluster graphics rendering.
Direct silicon sourcing by automotive OEM architecture teams is displacing traditional Tier-1 mediated procurement for cockpit compute. Volkswagen and domestic Chinese manufacturers now negotiate foundry capacity and IP licensing independently, compressing margin capture by established electronics suppliers. This pattern is most visible in China, where BYD and NIO semiconductor divisions co-define process node requirements with local foundries.
Intelligent Cockpit Chip Market Segmentation
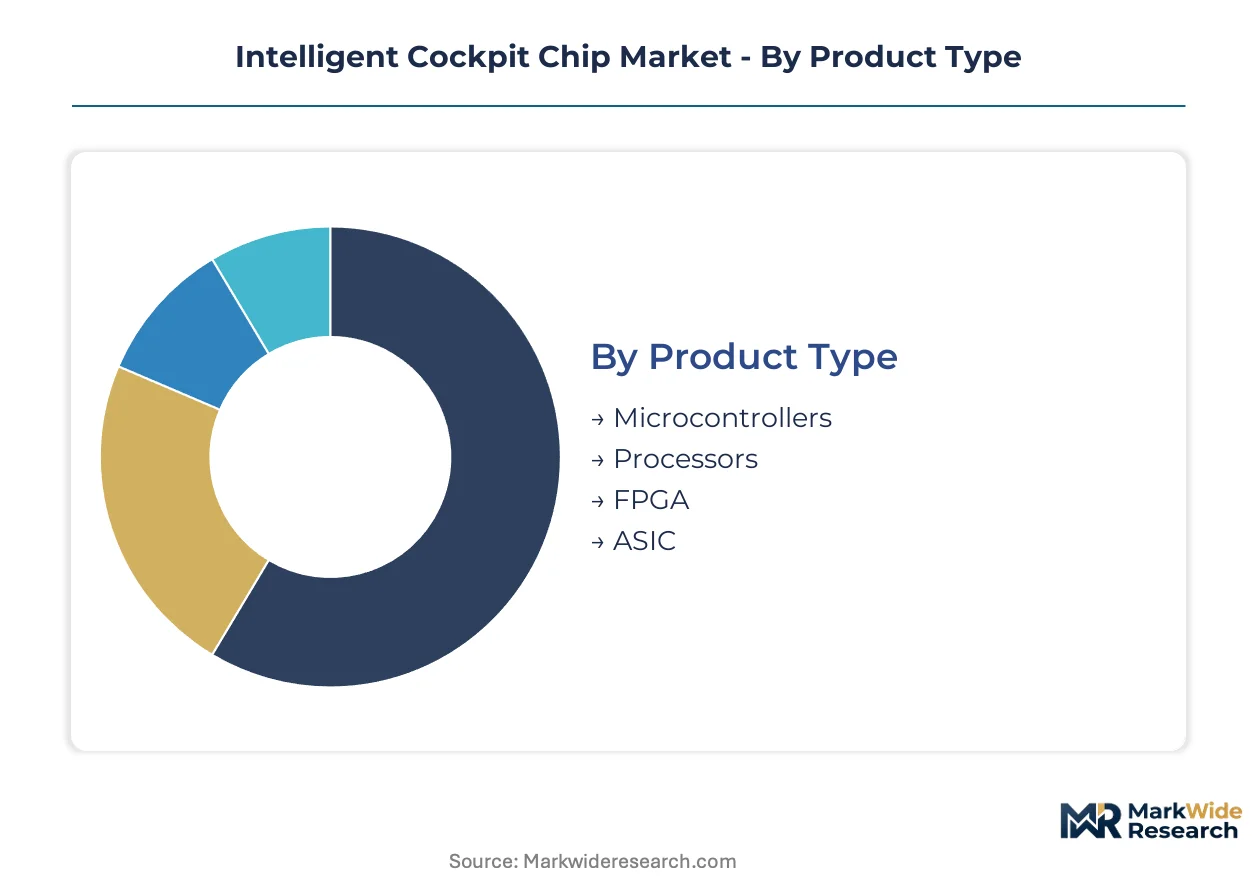
Intelligent cockpit chip segmentation reveals how heterogeneous compute requirements split across thermal envelopes, functional safety tiers, and procurement channels. Each dimension carries distinct margin profiles and certification burdens that reshape supplier competitive positioning.
Product Type:
Capital intensity concentrates in the most advanced process nodes, where mask costs and design verification cycles demand billion-dollar commitments before volume production.
- Processors:Heterogeneous SoCs integrating CPU clusters, GPU cores, and AI accelerators on advanced nodes consolidate multiple cockpit domains onto single die footprints. Premium automakers in Germany and China specify these for multimodal human-machine interfaces, absorbing the bulk of foundry capacity allocation for cockpit silicon.
- Microcontrollers:Lower-complexity devices dominate instrument cluster and body domain controller sockets with proven ISO 26262 ASIL-B qualification paths. Tier-1 supplier relationships with NXP and Renesas sustain incumbent positions here, though migration pressure toward consolidated compute platforms is intensifying.
- FPGA:Reconfigurable logic serves prototype validation and low-volume premium programs requiring post-deployment algorithm updates.
- ASIC:Custom silicon targets specific OEM-defined workloads with optimized power-performance characteristics for dedicated neural inference pipelines.
Processors absorb the bulk of installed capacity; ASIC is expanding most quickly as OEM architecture teams commission custom silicon for differentiated cabin experiences.
Technology:
Neural accelerator allocation within chip floorplans varies sharply by which algorithm class dominates the target vehicle program's feature set.
- Artificial Intelligence:Dedicated neural processing units execute transformer-based voice models and gaze-tracking inference within sub-15-watt thermal envelopes. MIIT GB standards in China mandate domestic certification for biometric data handling, accelerating co-development between local foundries and automotive OEMs for AI-enabled cockpit processors.
- Computer Vision:Dedicated accelerators process driver monitoring camera feeds to satisfy NHTSA availability verification mandates and ECE R79 hands-free control requirements. German KBA type-approval processes now require documented failure mode coverage for these pipelines.
- Natural Language Processing:Specialized cores handle multilingual command recognition with accent adaptation for regional vehicle programs.
- Machine Learning:Broader algorithmic frameworks support predictive maintenance and personalized HMI adaptation through continuous model refinement.
Artificial Intelligence commands the steepest expansion trajectory; Computer Vision maintains the largest installed base due to regulatory compulsion.
End User:
Procurement channel structure determines margin capture distribution between semiconductor designers, foundries, and intermediate electronics suppliers.
- OEMs:Direct silicon sourcing by Volkswagen, Mercedes-Benz, and BYD architecture teams bypasses traditional Tier-1 mediation. These organizations negotiate foundry capacity and IP licensing independently, compressing established supplier margins while accelerating design iteration cycles.
- Tier-1 Suppliers:Incumbent electronics specialists retain microcontroller-centric instrument cluster and body domain sockets where legacy qualification assets create switching costs.
- Aftermarket Providers:Retrofit infotainment and telematics modules serve vehicle parcs outside warranty coverage with reduced functional safety requirements.
- Dealerships:Regional distribution channels bundle chip-enabled feature activations with vehicle delivery configurations.
OEMs capture the dominant share of strategic procurement volume; Aftermarket Providers are gaining traction fastest in extended-vehicle-life monetization.
Application:
Software-defined feature delivery through over-the-air updates is collapsing traditional hardware-software bundling across cockpit domains.
- Infotainment:Graphics-intensive workloads for augmented reality navigation and multi-display synchronization demand highest GPU allocation within heterogeneous SoCs. Qualcomm Snapdragon Digital Chassis contracts anchor premium programs across North America and Europe.
- Driver Assistance:Unified AI compute architectures span both cabin intelligence and partial automation, with NVIDIA Drive Thor targeting this convergence.
- Navigation Systems:Location data processing with real-time traffic fusion requires secure enclaves for GB-standard compliance in China.
- Telematics:Cellular connectivity modules with edge computing capability support fleet management and usage-based insurance data pipelines.
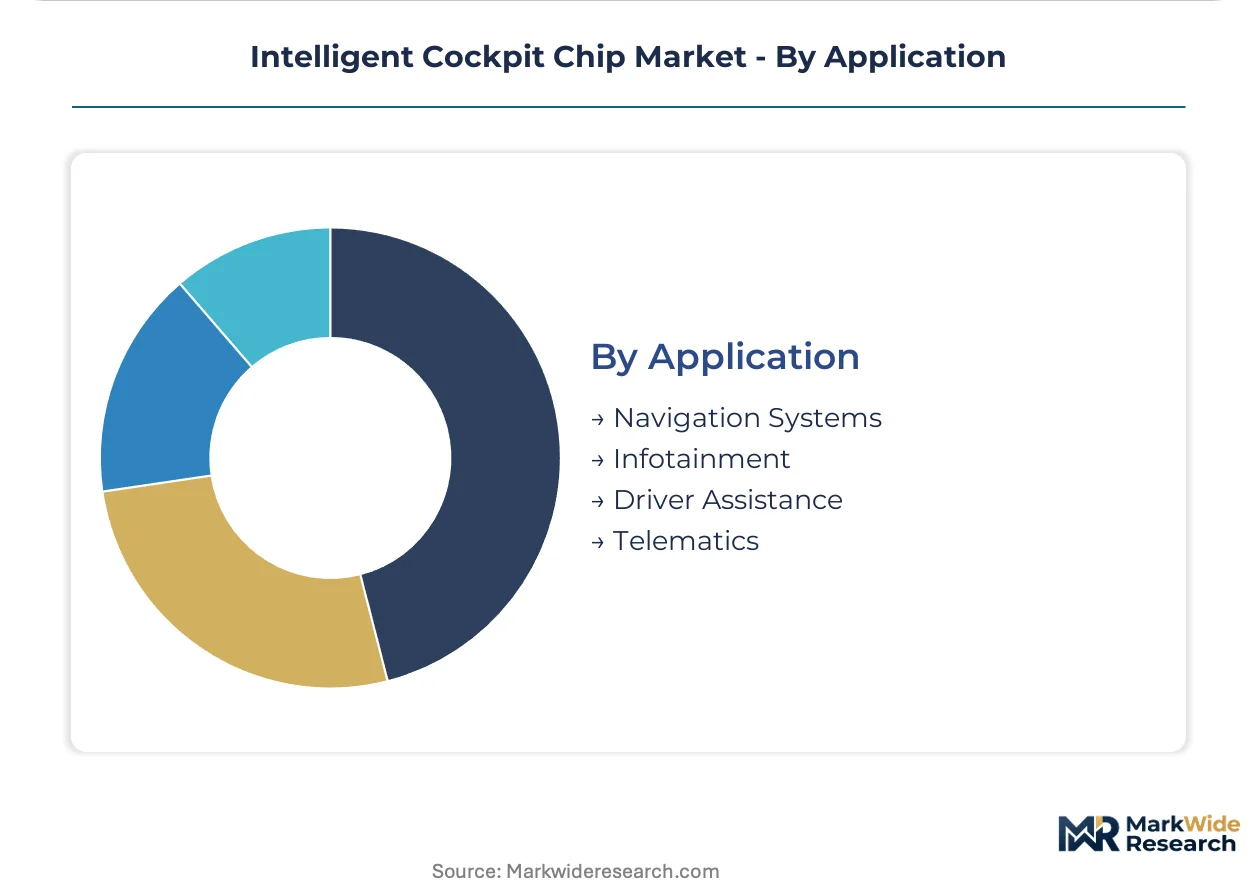
Infotainment commands the largest current silicon allocation; Driver Assistance exhibits the steepest growth curve as autonomy-cockpit convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the dominant share of intelligent cockpit silicon while Taiwan and South Korea foundries manufacture the advanced-node wafers. This geographic split between design validation clusters and high-volume production shapes supply continuity planning for automakers.
China
Domestic OEMs like BYD and NIO are co-developing localized cockpit processors with foundries to satisfy MIIT GB standards for biometric data handling. The MIIT certification regime mandates domestic silicon for connected vehicles processing location and driver monitoring information. Shanghai and Shenzhen house the primary architecture teams negotiating directly with SMIC and Hua Hong for capacity allocation.
Germany
Premium automakers in Stuttgart and Munich specify unified AI inference engines for multimodal human-machine interfaces across Mercedes-Benz and BMW vehicle programs. The KBA type-approval process requires documented failure mode coverage for driver monitoring camera pipelines under ECE R79. Bavaria's automotive electronics corridor concentrates Tier-1 supplier R&D centers adapting to direct OEM silicon sourcing.
United States
NHTSA driver availability monitoring mandates are embedding computer vision accelerators into cockpit processor designs for partial automation systems. The ISO 26262 ASIL-B certification requirement extends qualification timelines for instrument cluster integration. Michigan and California host competing architecture teams at Ford and Tesla negotiating Snapdragon Digital Chassis contracts.
South Korea
Foundry capacity at Samsung anchors leading-edge production for heterogeneous cockpit SoCs integrating GPU and AI accelerator cores. The national industrial policy prioritizes automotive semiconductor self-sufficiency amid geopolitical supply concerns. Seoul's design houses are expanding into cockpit-specific neural processing unit IP licensing.
Japan
Renesas Electronics sustains microcontroller dominance in instrument cluster sockets through established Tier-1 supplier relationships. METI semiconductor revitalization programs are channeling investment toward automotive AI accelerator development. Nagoya's automotive manufacturing belt maintains conservative migration timelines toward consolidated cockpit compute platforms.
Intelligent Cockpit Chip Market Competitive Landscape
Capital-heavy foundry operators compete with asset-light chip designers for margin capture in cockpit silicon. The vendor base concentrates around three tiers: integrated device manufacturers with captive fabrication, fabless specialists licensing ARM architecture, and automotive Tier-1 suppliers defending microcontroller sockets. Strategic differentiation runs through direct OEM engagement versus Tier-1 mediation, and through unified autonomous-cockpit convergence versus domain-specific specialization.
Among fabless designers anchoring premium infotainment contracts, Qualcomm and NVIDIA exemplify divergent convergence strategies. Qualcomm occupies a position centered on Snapdragon Digital Chassis platform consolidation across North American and European luxury programs. NVIDIA represents the unified AI compute archetype with Drive Thor architecture spanning both autonomous and cockpit workloads. NXP Semiconductors sits within the established supplier tier, sustaining broad Tier-1 relationships through microcontroller dominance in legacy instrument cluster sockets.
| Leading Market Players |
|---|
| Qualcomm |
| NXP Semiconductors |
| Renesas Electronics |
| Infineon |
| Huawei Technologies |
| SiEngine Technology |
| Intel |
| NVIDIA |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
Functional safety engineering expertise concentrated in Bavaria and Michigan creates labor-cost differentials that widen pricing-tier spreads between ASIL-D certified processors and standard-grade alternatives. Tier-1 suppliers absorb margin compression as OEM architecture teams negotiate directly with foundries, bypassing traditional electronics procurement channels.
Pricing Analysis
Margin tightening in ASIL-D qualified processors reflects eighteen-month certification timelines that extend design verification cycles and concentrate premium pricing power with incumbent suppliers. Three-tier pricing structure across premium infotainment, standard instrument cluster, and economy body domain tiers differentiates by certification grade and GPU allocation. Cost-down pressure on microcontroller sockets accelerates because consolidated cockpit SoCs displace discrete component bill-of-materials. Aftermarket providers exhibit highest price sensitivity; Mercedes-Benz and BYD architecture teams demonstrate lowest sensitivity due to direct foundry negotiation leverage.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Detroit coordinate hub-and-spoke patterns for finished cockpit processors serving adjacent assembly plants. Wafer fabrication concentrates in Taiwan, South Korea, and China; advanced-node EUV capacity at TSMC and Samsung anchors heterogeneous SoC production. Silicon feedstock, photoresist chemicals, and advanced packaging substrates constitute critical input dependencies. Single-source vulnerability at Taiwan foundries exposes supply continuity to geopolitical friction. Distribution runs through Tier-1 electronics suppliers for legacy microcontroller sockets and direct OEM channels for premium heterogeneous SoCs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heterogeneous system-on-chips are displacing discrete microcontroller combinations across instrument cluster and body domain sockets, compressing the technology-transition window for legacy architecture defenders.
For Market Incumbents: Hedge against direct OEM silicon sourcing by deepening foundry partnership commitments in Taiwan and South Korea while accelerating ASIL-D qualification assets for instrument cluster consolidation. Renesas and NXP must defend microcontroller socket positions against Qualcomm Snapdragon Digital Chassis encroachment through legacy bus architecture compatibility investments. For New Entrants and Emerging Players: MIIT GB standards in China open a window for domestic neural processing unit designers to capture biometric data handling mandates that exclude non-certified foreign silicon. Target co-development partnerships with BYD and NIO semiconductor divisions; pursue white-space in transformer-based voice model acceleration for sub-15-watt thermal envelopes. For Investors and Strategic Acquirers: Re-rating potential sits with fabless AI accelerator specialists given unified autonomous-cockpit convergence collapsing separate controller categories. Long-term viability favors designers with functional safety certification pipelines and direct OEM engagement capabilities. Watch for inflection where Tier-1 suppliers surrender instrument cluster socket share to direct OEM procurement models.| Strategic Initiative | Industry Significance |
|---|---|
| Unified AI Compute Platform Development | NVIDIA Drive Thor architecture spans both autonomous and cockpit workloads for Mercedes-Benz programs. |
| Direct Foundry Capacity Negotiation | Volkswagen and BYD bypass Tier-1 mediation to secure advanced-node wafer allocation at TSMC and SMIC. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D qualification timelines extend eighteen months, creating incumbent defender advantages. |
| Domestic Silicon Co-Development | MIIT GB standards mandate local certification for biometric data handling, favoring SiEngine Technology partnerships. |
| Software-Defined Feature Subscription | Over-the-air activation for augmented reality navigation creates recurring revenue detached from hardware cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, foundry capacity planners, and automotive semiconductor architects provided qualitative validation. NHTSA guidance documents, ECE R79 regulatory texts, and MIIT GB standard publications supplied compliance framework inputs. Bottom-up vehicle production forecasts triangulated against top-down semiconductor consumption models derived from customs trade flows and foundry utilization disclosures.
Reconciliation of wafer shipment data, vehicle program launch schedules, and content-per-vehicle estimates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology capability tier, procurement channel structure, application domain, and regional production cluster. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate timing and technology substitution elasticity. Neural accelerator allocation trends and thermal envelope constraints provided industry-specific forecast inputs.
Caveats apply where geopolitical disruption to Taiwan foundry operations or accelerated migration timelines for consolidated cockpit compute could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM architecture team hiring trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Smart TV Chip Market