
 Power Line Communication System-On-Chip Market | 2026-2036
Power Line Communication System-On-Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Power Line Communication System-On-Chip Market Analysis
Embedded firmware engineering talent is rotating toward powerline communication architectures as utilities modernize grid infrastructure. STMicroelectronics leverages its mixed-signal design heritage to dominate European smart meter sockets. Texas Instruments sustains R&D intensity in narrowband OFDM variants for industrial automation. NXP Semiconductors anchors automotive-qualified PLC portfolios that bridge vehicle-to-grid communication.
Power Line Communication System-On-Chip denotes an integrated circuit embedding analog front-end, digital signal processor, and protocol stack controller onto silicon die, typically fabricated at 40nm to 90nm nodes with operating frequencies spanning 2 MHz to 30 MHz for broadband and 3 kHz to 500 kHz for narrowband carrier modulation. These devices modulate data onto existing AC or DC power conductors, eliminating dedicated communication wiring in smart grid, building automation, and in-vehicle networking deployments. PLC ICs command the dominant revenue share due to direct OEM supply relationships and silicon margin structures, while embedded deployment models are gaining traction as appliance manufacturers integrate communication subsystems at board level rather than purchasing external modules. Automated metering applications lead volume shipments, though home networking represents the fastest-expanding margin pool as retail service providers bundle PLC extenders with fiber subscriptions.
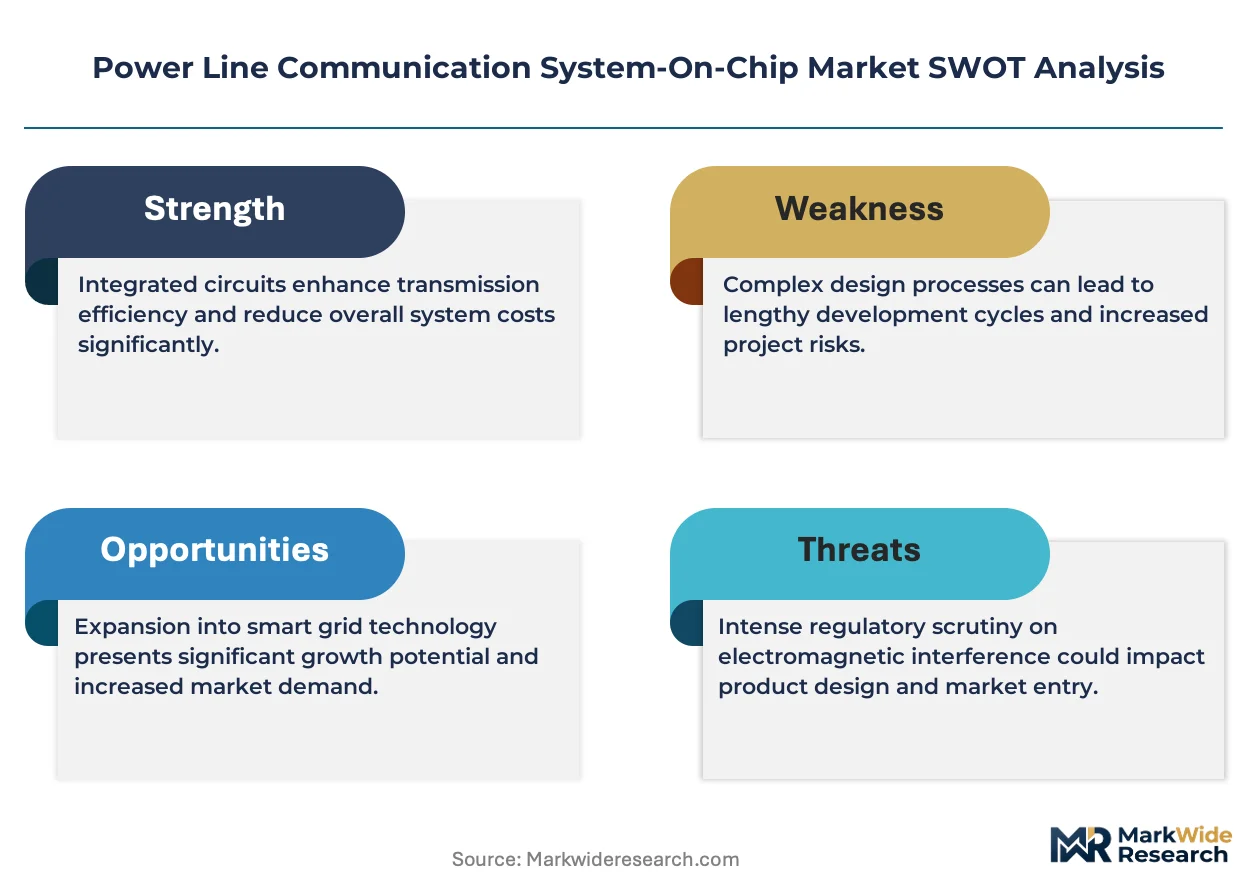
FCC Part 15 emissions limits constrain transmit power spectral density in US deployments, forcing adaptive notch-filter designs that suppress amateur radio bands. ETSI EN 50561 and CENELEC EN 50065 define European access protocols and frequency bands, with France's ANSM-equivalent spectrum authority coordinating coexistence between electricity distributors and broadband over powerline operators. China's MIIT enforces GB/T national standards that prioritize domestic semiconductor procurement in grid tenders. Stakeholders must monitor whether IEEE 1901.1 revisions will mandate AES-256 encryption across all new deployments, a specification shift that would obsolete legacy silicon without hardware security modules.
Market Dynamics
Convergence between IEEE 1901 and ITU-T G.hn standards is compressing silicon design cycles as manufacturers must support dual-protocol implementations to maintain utility procurement eligibility.
Growth Catalysts
- AMI Rollouts:State Grid Corporation's advanced metering infrastructure tenders in China mandate domestic PLC SoC procurement, creating sustained volume anchors for regional foundries.
- FCC Part 15 Adaptive Notching:US emissions limits force dynamic spectrum management features that differentiate premium silicon tiers from commodity alternatives.
- Vehicle-to-Grid Integration:Automotive OEMs embed PLC controllers for bidirectional charging communication, extending addressable silicon demand beyond traditional utility channels.
Market Restraints
- Foundry Concentration:Mature-node capacity at 40nm-90nm concentrates among Taiwan and South Korea facilities, exposing supply continuity to geopolitical friction.
- Copper and Epoxy Resin Volatility:Substrate material costs swing with commodity markets, compressing module-level margins for mid-tier suppliers.
- Wireless Substitution:LoRaWAN and cellular LPWAN alternatives capture last-mile connectivity in rural deployments where powerline noise floors prove prohibitive.
Strategic Opportunities
- India Smart Metering:CEA-mandated 250 million meter deployments by 2026 create first-mover advantages for PLC vendors qualifying under BIS certification.
- Industrial Automation:Narrowband OFDM variants penetrate factory floor power distribution networks for predictive maintenance sensor backhaul.
- EU Green Deal Subsidies:Building renovation incentives accelerate PLC-enabled energy management system retrofits across German and French commercial real estate.
Industry Challenges
- Mixed-Signal Engineering Scarcity:Analog front-end design expertise pools concentrate among legacy semiconductor veterans approaching retirement.
- Multi-Standard Certification Timelines:Simultaneous CENELEC EN 50065, FCC Part 15, and GB/T validation extends product qualification by 8-14 months.
- Legacy Meter Integration:DLMS/COSEM protocol translation layers add firmware complexity when bridging 15-20 year installed base assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Line Communication System-On-Chip Market |
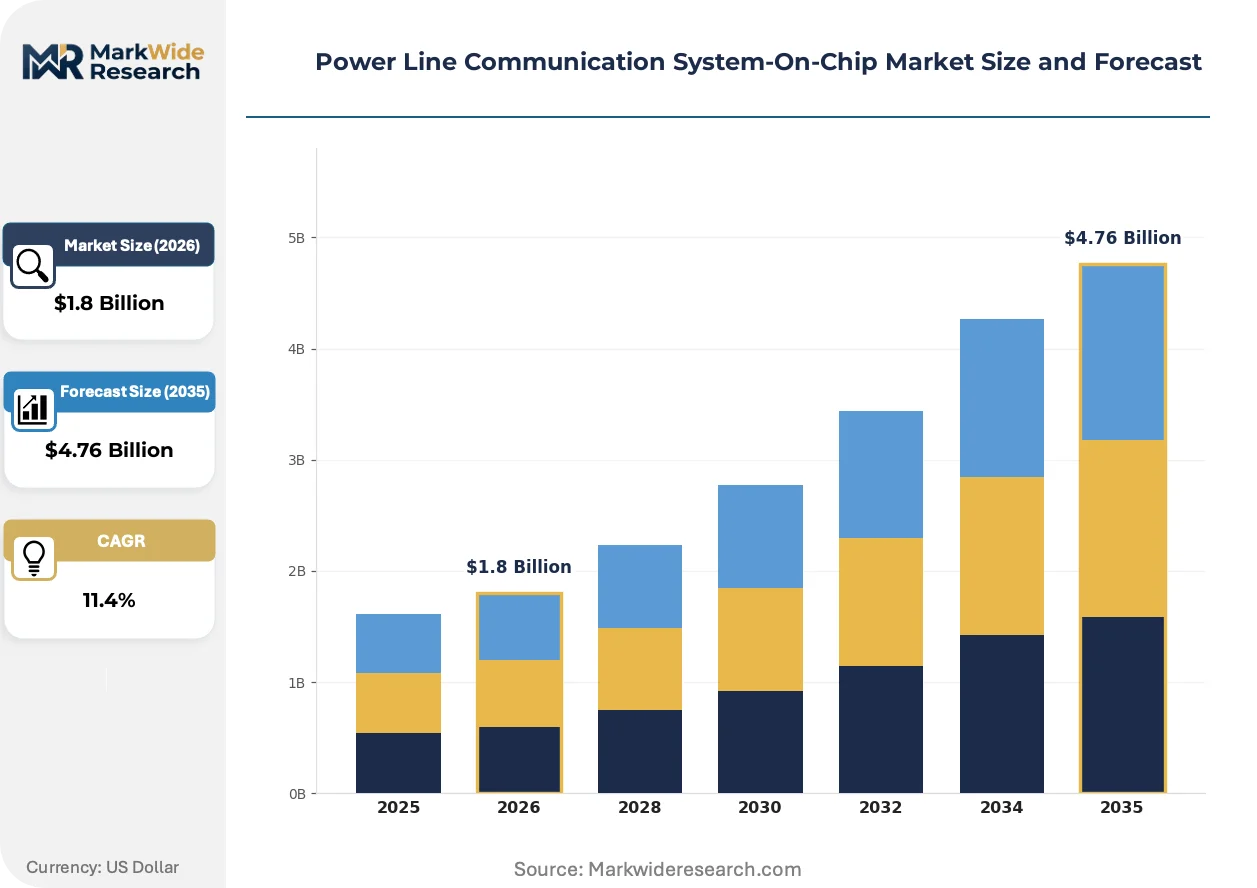
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC ICs, PLC Modules, Adapters, Gateways End User: Energy Utilities, Smart Home Devices, Industrial Automation, Telecommunications Deployment Model: On-Premises, Cloud-Based, Hybrid, Embedded Application: Smart Grid, Home Networking, Remote Monitoring, Automated Metering |
| Companies Covered | Siemens AG, Schneider Electric, General Electric, STMicroelectronics, NXP Semiconductors, Renesas Electronics Corporation, Texas Instruments, Broadcom Inc., AMETEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Line Communication System-On-Chip Market Emerging Trajectories
Silicon architectures are bifurcating between ultra-integrated SoCs for cost-sensitive metering and modular chipsets enabling field-upgradable protocol stacks.
Orthogonal frequency-division multiplexing is fragmenting into specialized variants optimized for specific noise environments. Narrowband OFDM dominates European CENELEC-A band deployments for its robustness against impulsive interference. Broadband OFDM carriers capture home networking applications where 30 MHz spectrum availability supports video backhaul. Each variant demands distinct analog front-end calibration, forcing semiconductor houses to maintain parallel design teams rather than converging on unified platforms.
ETSI EN 50561-1 access protocol harmonization is eliminating coexistence arbitrage between electricity distributors and broadband over powerline operators. France's spectrum authority now coordinates priority access windows, preventing service degradation when multiple operators share medium-voltage segments. German utilities have responded by consolidating procurement specifications around single-vendor PLC ecosystems to guarantee deterministic latency for protection relaying.
Appliance manufacturers are absorbing communication subsystems at board level rather than sourcing external modules. White goods OEMs in Italy and Turkey embed PLC die directly onto motor control PCBs, bypassing module vendor margins. This captive integration compresses addressable module revenue pools while expanding royalty-bearing silicon licensing opportunities for core IP holders.
Power Line Communication System-On-Chip Market Segmentation
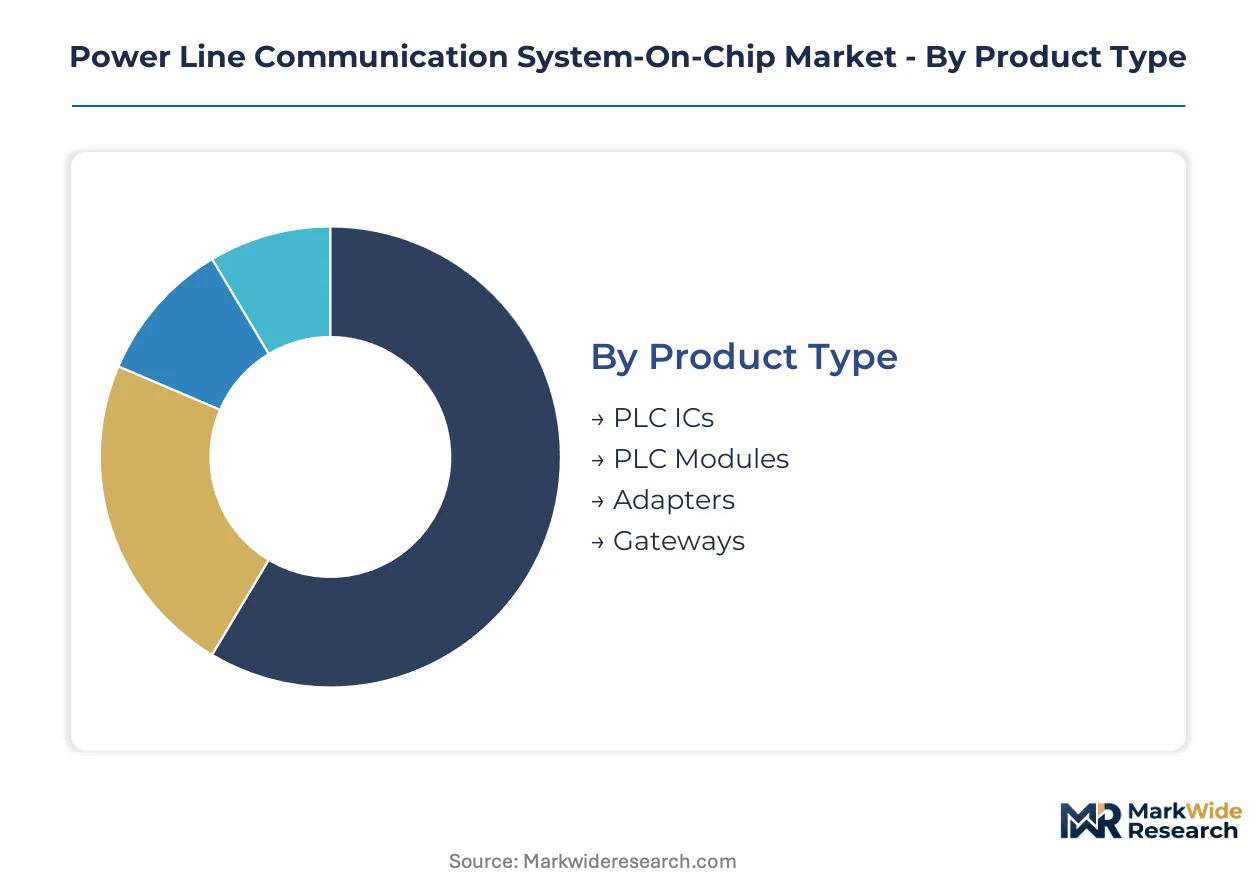
Segmentation in the Power Line Communication System-On-Chip market reflects divergent certification requirements across regulatory jurisdictions. Semiconductor vendors must architect product portfolios that address distinct frequency bands, emission limits, and protocol mandates imposed by national spectrum authorities.
Product Type:
FCC Part 15 adaptive notching requirements in the United States and ETSI EN 50561 access protocols in Europe create divergent silicon specifications that shape product category differentiation.
- PLC ICs:Integrated circuits embed analog front-end, digital signal processor, and protocol stack controller onto single silicon die fabricated at 40nm to 90nm nodes. State Grid Corporation's domestic procurement mandates in China concentrate demand for these devices, with operating frequencies spanning 2 MHz to 30 MHz for broadband and 3 kHz to 500 kHz for narrowband carrier modulation. The integrated architecture eliminates dedicated communication wiring in smart grid deployments.
- PLC Modules:Pre-certified subsystems combine baseband processor with line coupling circuitry and EMC filtering in shielded enclosures. European smart meter sockets favor module form factors to accelerate utility certification timelines under CENELEC EN 50065, particularly in France where ANSM-equivalent spectrum authorities coordinate coexistence between electricity distributors and broadband over powerline operators.
- Adapters:Retail plug-in devices extend network coverage over existing AC wiring. These consumer-facing products face FCC Part 15 emissions constraints that suppress amateur radio bands through dynamic spectrum management.
- Gateways:Aggregation nodes bridge powerline segments to IP backhaul networks. Home networking applications in Germany and France drive demand for these boundary devices under EU Green Deal building renovation incentives.
PLC ICs handle the majority of throughput; PLC Modules are expanding most quickly on share as appliance manufacturers absorb communication subsystems at board level.
End User:
Customer procurement patterns stratify by volume scale and certification burden, with energy utilities commanding longest qualification cycles.
- Energy Utilities:Grid operators deploy PLC SoCs for advanced metering infrastructure and distribution automation. China's MIIT enforces GB/T national standards that prioritize domestic semiconductor procurement in State Grid Corporation tenders, creating sustained volume anchors for regional foundries.
- Smart Home Devices:Consumer electronics OEMs embed narrowband OFDM controllers for appliance connectivity. Italian and Turkish white goods manufacturers integrate PLC die directly onto motor control PCBs, bypassing module vendor margins.
- Industrial Automation:Factory operators leverage narrowband OFDM variants for predictive maintenance sensor backhaul across power distribution networks. CENELEC-A band deployments dominate European industrial settings for robustness against impulsive interference.
- Telecommunications:Service providers bundle PLC extenders with fiber subscriptions to solve last-mile connectivity. Retail service providers in broadband markets favor these solutions where powerline noise floors remain manageable.
Energy Utilities dominate procurement volume; Smart Home Devices are gaining share fastest as captive integration compresses addressable module revenue pools.
Deployment Model:
Architecture choices reflect trade-offs between firmware control and operational overhead, with hybrid configurations emerging as utilities modernize legacy assets.
- On-Premises:Local protocol processing within substation or meter concentrator enclosures. German utilities consolidate procurement specifications around single-vendor PLC ecosystems to guarantee deterministic latency for protection relaying.
- Cloud-Based:Centralized data aggregation and analytics platforms. These architectures face scrutiny under GDPR in European deployments where meter data crosses national boundaries.
- Hybrid:Edge processing with cloud synchronization for AMI command-and-control. DLMS/COSEM protocol translation layers add firmware complexity when bridging 15-20 year installed base assets.
- Embedded:Communication subsystems integrated at board level during appliance manufacturing. This deployment model expands royalty-bearing silicon licensing opportunities for core IP holders.
Embedded deployments are climbing the fastest on share; On-Premises retains the dominant installed base among conservative utility procurement.
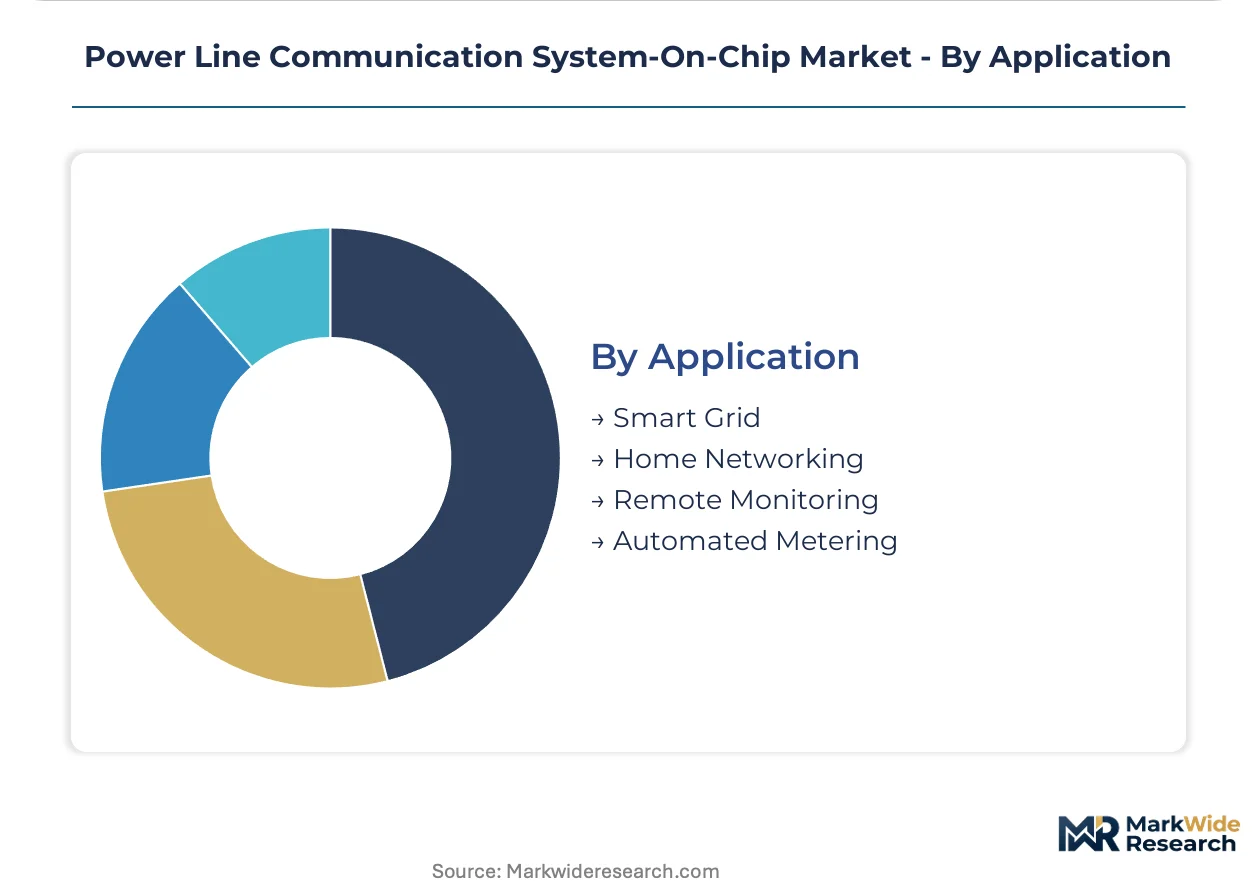
Application:
Use case requirements fragment silicon specifications across noise tolerance, data rate, and latency dimensions.
- Smart Grid:Distribution automation and demand response systems. IEEE 1901 and ITU-T G.hn standards convergence compresses silicon design cycles as manufacturers must support dual-protocol implementations to maintain utility procurement eligibility.
- Home Networking:Residential broadband extension and multimedia distribution. Broadband OFDM carriers capture these applications where 30 MHz spectrum availability supports video backhaul.
- Remote Monitoring:Industrial sensor networks and environmental telemetry. LoRaWAN and cellular LPWAN alternatives capture rural deployments where powerline noise floors prove prohibitive.
- Automated Metering:AMI endpoints for electricity, gas, and water consumption tracking. India's CEA-mandated 250 million meter deployments create first-mover advantages for vendors qualifying under BIS certification.
Automated Metering leads volume shipments; Home Networking shows the steepest expansion trajectory as retail service providers bundle PLC extenders with fiber subscriptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes PLC SoCs primarily for utility-scale metering infrastructure, while Germany and the United States deploy these devices across industrial automation and home networking applications with divergent regulatory constraints.
China
State Grid Corporation's advanced metering infrastructure tenders mandate domestic PLC SoC procurement, creating sustained volume anchors for regional foundries. MIIT enforces GB/T national standards that prioritize local semiconductor content in grid tenders. Yangtze River Delta fabrication clusters near Shanghai concentrate mature-node production for narrowband OFDM variants.
United States
Industrial automation and vehicle-to-grid integration drive differentiated demand beyond utility metering channels. FCC Part 15 emissions limits constrain transmit power spectral density, forcing adaptive notch-filter designs that suppress amateur radio bands. Silicon Valley and Austin technology corridors host fabless design houses specializing in broadband OFDM controllers for home networking.
Germany
EU Green Deal building renovation incentives accelerate PLC-enabled energy management system retrofits across commercial real estate. ETSI EN 50561 and CENELEC EN 50065 define access protocols and frequency bands for European deployments. Bavarian industrial clusters around Munich consolidate procurement specifications around single-vendor PLC ecosystems for deterministic protection relaying latency.
India
CEA-mandated 250 million smart meter deployments by 2026 create first-mover advantages for vendors qualifying under BIS certification. Central Electricity Authority regulations prioritize domestic manufacturing content in public procurement tenders. Gujarat and Maharashtra industrial corridors attract module assembly investments targeting utility-scale AMI rollouts.
France
ANSM-equivalent spectrum authorities coordinate coexistence between electricity distributors and broadband over powerline operators on shared medium-voltage segments. ETSI EN 50561-1 access protocol harmonization eliminates arbitrage opportunities between service providers. Île-de-France utility headquarters drive standardization around unified PLC ecosystems for grid modernization.
Power Line Communication System-On-Chip Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding direct OEM supply relationships and silicon margin structures. European mixed-signal heritage houses and American broad-line semiconductor manufacturers anchor the premium segment through protocol stack integration. Strategic differentiation concentrates on dual-protocol IEEE 1901 and ITU-T G.hn implementations, while competitive moves emphasize technology licensing partnerships and geographic qualification expansion.
Among European-based semiconductor specialists, STMicroelectronics and NXP Semiconductors exemplify the integrated archetype through automotive-qualified and industrial-automation portfolios. Texas Instruments represents the American broad-line model with sustained R&D positioning in narrowband OFDM variants. These three anchors occupy positions spanning premium silicon tiers to field-upgradable modular chipsets.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric |
| General Electric |
| STMicroelectronics |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Texas Instruments |
| Broadcom Inc. |
| AMETEK Inc. |
| Others |
Supply Flow & Price Mechanics
Mature-node fab utilization at 40nm-90nm nodes concentrates pricing power among Taiwan and South Korea foundries, compressing margin structures for fabless PLC SoC vendors while elevating price floors for utility procurement contracts.
Pricing Analysis
Long-term offtake agreements dominate utility-scale procurement, with State Grid Corporation tenders locking volume commitments across 3-5 year horizons. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—CENELEC EN 50065 and FCC Part 15 dual-qualified silicon commands 15-20% premia over single-standard variants. Cost compression in economy-tier narrowband OFDM controllers is intensifying because Chinese foundries are absorbing substrate volatility. Municipal utilities exhibit highest price sensitivity due to budget-constrained AMI rollouts, while automotive OEMs prioritize deterministic latency over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for PLC SoC production, with Yangtze River Delta packaging houses completing backend assembly. Silicon wafers, epoxy resin substrates, and copper lead frames constitute critical input dependencies. Single-source vulnerability concentrates in mature-node photolithography equipment held by Dutch and Japanese vendors. Distribution runs through direct OEM supply contracts for ICs, while module vendors serve European utility channels via certified system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware-as-a-service attach rates are expanding faster than hardware shipments as utilities demand over-the-air protocol updates and cybersecurity patch management for 15-20 year meter deployments.
For Market Incumbents: Consolidate mixed-signal engineering talent pools through targeted acquisition of analog front-end design houses in Europe and Japan. Wireless substitution threats from LoRaWAN and cellular LPWAN in rural deployments demand defensive certification investment in dual-protocol IEEE 1901 and ITU-T G.hn silicon to maintain utility procurement eligibility. Channel control through exclusive distribution partnerships with German and French system integrators protects premium-tier positioning. For New Entrants and Emerging Players: Lead with BIS-certified narrowband OFDM solutions targeting India's CEA-mandated smart meter deployments, where first-mover advantages remain available for qualified vendors. India's 250 million meter installation target represents the most penetrable geography for new qualification. Project-based engagement with Gujarat and Maharashtra industrial corridor assemblers offers lower barrier-to-entry than direct State Grid Corporation competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firmware-licensing specialists with utility software update contracts—this archetype generates 40-50% service attach rates versus 10-15% for pure-play silicon vendors. Long-term viability over the next decade hinges on AES-256 hardware security module integration as IEEE 1901.1 revisions progress. Watch for MIIT procurement guideline amendments mandating domestic IP content as the inflection signal for Chinese market access.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Protocol Silicon Development | IEEE 1901 and ITU-T G.hn convergence compresses design cycles and expands utility procurement eligibility across CENELEC and FCC jurisdictions. |
| Hardware Security Module Integration | AES-256 encryption mandates in pending IEEE 1901.1 revisions would obsolete legacy silicon without cryptographic acceleration blocks. |
| India BIS Certification Investment | CEA-mandated smart meter deployments create volume anchors for qualified vendors ahead of 250 million unit installation targets. |
| Automotive-Qualified Portfolio Expansion | Vehicle-to-grid bidirectional charging communication extends addressable demand beyond traditional utility channels into OEM supply chains. |
| Firmware-as-a-Service Platform Launch | Over-the-air protocol updates and cybersecurity patch management generate recurring revenue streams attached to 15-20 year meter lifecycles. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, semiconductor product managers, smart meter procurement leads, and industrial automation system integrators. Secondary validation drew from SEC semiconductor filings, MIIT GB/T standard publications, CENELEC regulatory bulletins, and customs trade data for PLC component flows. Bottom-up unit shipment estimates triangulated against top-down utility capex projections.
Across the analysis window, volume and value outputs reflect segmentation by product type, end user, deployment model, and application with regional regulatory cluster overlays. CAGRs were derived from logistic adoption curves fitted to AMI rollout schedules and industrial automation upgrade cycles. Forecast inputs incorporated foundry capacity utilization rates, copper and epoxy resin commodity price indices, and wireless substitution elasticity parameters.
The analysis sits within stated boundaries; outcomes outside sustained State Grid Corporation tender volumes, stable Taiwan-South Korea foundry relations, or unamended IEEE 1901.1 encryption timelines would require recalibration. Forecasts reflect documented assumptions regarding standard convergence, regulatory procurement mandates, and raw material cost trajectories. Recalibration cycles align with material shifts in utility tender awards, spectrum authority rulings, and foundry capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market