
 Wi-Fi Semiconductor Chipset Market | 2026-2036
Wi-Fi Semiconductor Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Semiconductor Chipset Market Outlook
South Korea is narrowing its process-technology gap with leading-edge foundries through government-backed semiconductor clusters in Pyeongtaek and Yongin. Qualcomm Technologies, Inc. leverages its modem-RF system integration to dominate premium smartphone sockets. Broadcom Inc. anchors enterprise access-point supply through merchant silicon programs. MediaTek Inc. competes aggressively in mid-tier consumer electronics with integrated connectivity platforms.
Wi-Fi semiconductor chipsets are integrated circuits that implement baseband processing, RF transceiver functions, and MAC-layer protocols to enable wireless local-area networking under IEEE 802.11 standards, typically fabricated on 12-inch wafers using FinFET or planar CMOS nodes depending on performance tier. These devices serve as the core connectivity engine for consumer electronics, enterprise infrastructure, and industrial IoT endpoints requiring reliable high-throughput wireless data transmission. Wi-Fi 6 and Wi-Fi 6E technology segments are capturing disproportionate engineering investment as OEMs prioritize OFDMA and 6 GHz spectrum support for latency-sensitive applications. Smart home devices and industrial automation application categories are exhibiting the steepest demand slopes as mesh networking and deterministic wireless replace legacy wired connectivity in residential and factory environments.
The FCC in the United States governs 6 GHz spectrum licensing and device certification, directly conditioning which technology generations achieve commercial scale. ETSI and national regulators across Europe enforce RED compliance and cybersecurity baseline requirements that filter market access for non-compliant suppliers. China's MIIT and GB standards mandate domestic testing protocols that shape product localization strategies for foreign chipset vendors. Stakeholders must monitor spectrum auction timelines and harmonization talks between major economies to anticipate which Wi-Fi technology generation achieves cross-border deployment momentum.
Market Dynamics
The transition from Wi-Fi 6 to Wi-Fi 7 is compressing product lifecycles and forcing simultaneous investment in 6 GHz RF front-ends, baseband IP, and advanced packaging across the entire supplier base.
Growth Catalysts
- 6 GHz Spectrum Liberalization:The FCC's 2020 decision to open 1,200 MHz of unlicensed spectrum in the United States created immediate design-win opportunities for tri-band chipsets. This regulatory unlock is now propagating through ETSI harmonization talks across European Union member states.
- Industrial Automation Retrofit Cycles:Factory floors in Germany and Japan are replacing wired Ethernet with deterministic wireless for mobile robotics and AGV fleets. This end-use vertical demands sub-10 millisecond latency that only Wi-Fi 6E and Wi-Fi 7 architectures can reliably deliver.
- Captive Semiconductor Programs:Chinese OEMs are expanding in-house chipset design teams in Shanghai and Shenzhen, reducing reliance on merchant silicon and creating parallel demand for domestic foundry capacity at SMIC and Hua Hong.
Market Restraints
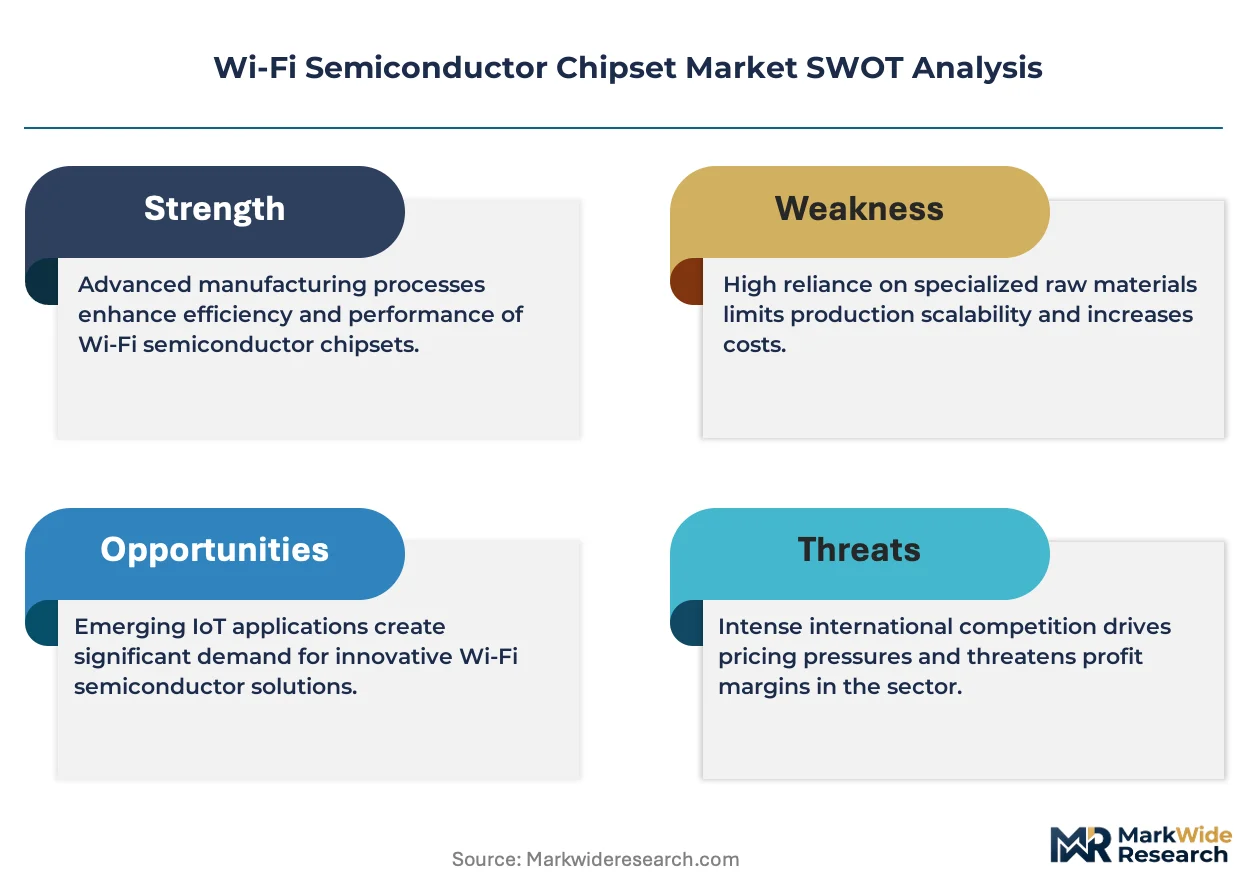
- Advanced Node Cost Escalation:FinFET tape-outs at 5nm and below require $50-80 million per design iteration, concentrating development among cash-rich integrated device manufacturers and freezing out fabless mid-tier competitors.
- RF Front-End Supply Concentration:Bulk acoustic wave filter manufacturing concentrates in Murata, Qorvo, and Broadcom facilities, creating single-source vulnerability for 6 GHz and ultra-wideband coexistence architectures.
- Power Amplifier Efficiency Ceiling:CMOS power amplifiers at 6 GHz exhibit 15-20% drain efficiency versus 35-45% for GaAs alternatives, forcing unacceptable thermal budgets in compact smartphone and tablet form factors.
Strategic Opportunities
- Rural Broadband Infrastructure:India's BharatNet initiative and similar programs in Indonesia and Brazil create demand for low-cost outdoor CPE chipsets with extended temperature ranges and integrated high-gain antenna drivers.
- Wi-Fi and 5G Convergence:Dual-connectivity platforms that simultaneously anchor to licensed cellular and unlicensed Wi-Fi spectrum are enabling private network deployments for mining operations in Australia and Canada.
- Software-Defined Radio Architectures:Programmable baseband implementations allow single-silicon SKUs to serve multiple regional regulatory domains through firmware updates, reducing inventory fragmentation for router OEMs.
Industry Challenges
- RFIC-BBIC Co-Design Talent Scarcity:The intersection of millimeter-wave electromagnetic simulation and digital signal processing algorithm optimization requires specialists that command premium compensation in Taiwan and South Korea labor markets.
- Regulatory Certification Parallelism:Chipset vendors must maintain simultaneous FCC, ETSI, MIIT, and TELEC test campaigns for each product generation, extending time-to-revenue by 6-9 months relative to single-market launches.
- Legacy 2.4 GHz Support Burden:Backward compatibility requirements for IEEE 802.11b/g/n force continued die area allocation to obsolete modulation schemes, constraining power-performance-area optimization for greenfield Wi-Fi 6E and Wi-Fi 7 designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Semiconductor Chipset Market |
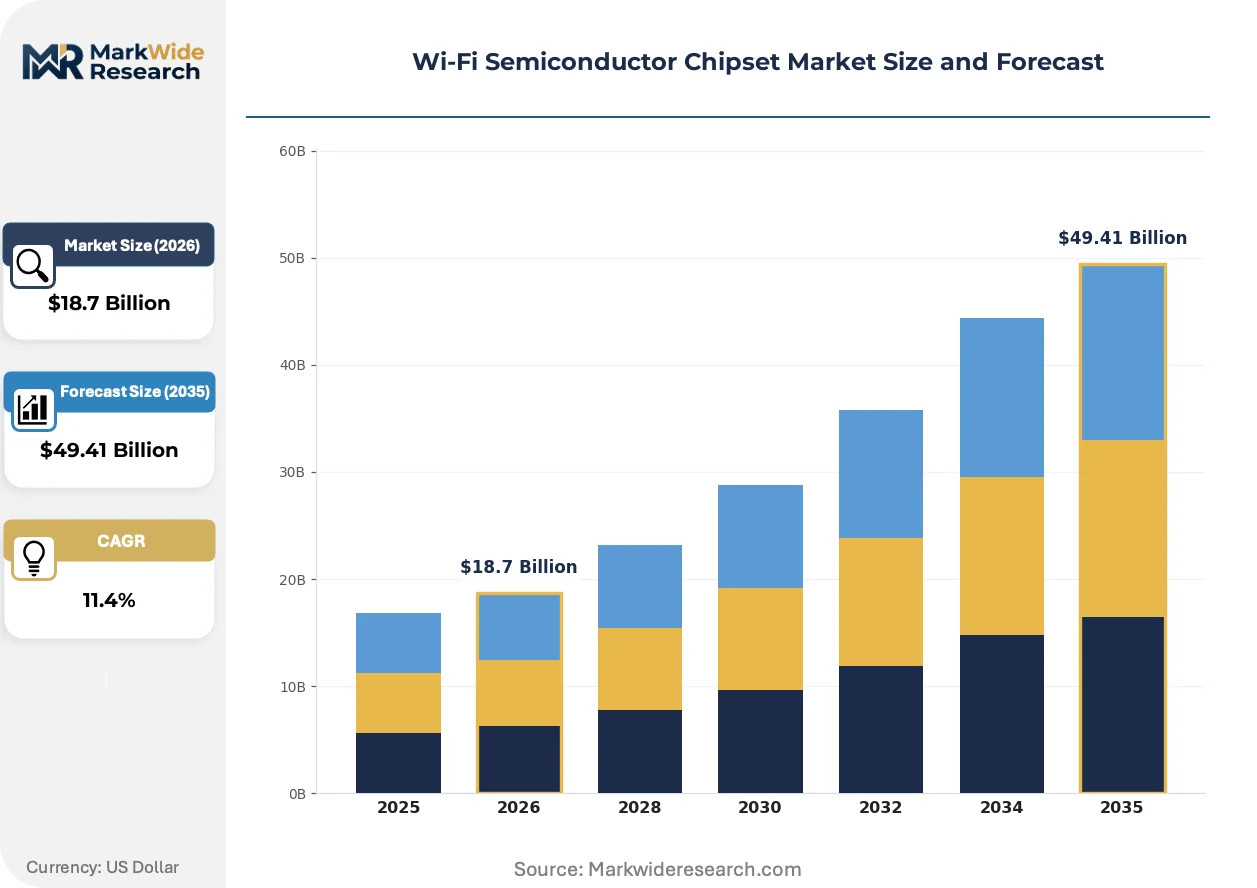
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chipsets, Modules, Integrated Circuits, Adaptive Antennas Technology: Wi-Fi 6, Wi-Fi 6E, Legacy Wi-Fi, FD-MIMO Application: Smart Home Devices, Wearable Technology, Industrial Automation, Consumer Electronics End User: OEMs, Retail Consumers, Commercial Enterprises, Telecommunications Providers |
| Companies Covered | Qualcomm Technologies, Inc., Broadcom Inc., MediaTek Inc., Intel Corporation, Realtek Semiconductor Corp., NXP Semiconductors, Infineon Technologies AG, Texas Instruments Incorporated, Marvell Technology Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Semiconductor Chipset Market Strategic Shifts
Wi-Fi semiconductor architectures are bifurcating between ultra-integrated mobile platforms and disaggregated enterprise access-point solutions, with packaging technology and software stacks becoming the primary differentiation vectors.
Multi-link operation is digitizing how chipset vendors architect channel bonding and spatial stream allocation across 2.4 GHz, 5 GHz, and 6 GHz radios simultaneously. Enterprise infrastructure OEMs in the United States and Germany are piloting 320 MHz channel configurations that aggregate contiguous and non-contiguous spectrum blocks. This capability is digitizing the traditional trade-off between coverage range and peak throughput, allowing single AP deployments to serve high-density conference rooms and adjacent corridors without hardware swaps.
The European Commission's Radio Equipment Directive cybersecurity baseline, effective 2025, mandates secure boot and software update mechanisms for all Wi-Fi devices marketed in EU member states. This regulatory overlay forces chipset vendors to embed hardware root-of-trust and encrypted firmware storage, adding $0.30-0.50 in bill-of-materials cost per unit. Router and mesh system manufacturers serving European distribution channels are now prioritizing silicon with pre-integrated secure enclaves over pure performance benchmarks.
Enterprise IT procurement teams are consolidating vendor relationships around platforms that unify Wi-Fi, Bluetooth, and 802.15.4/Zigbee connectivity on single chipsets. This consolidation pattern displaces discrete component sourcing for smart building and healthcare facility deployments in Singapore and the United Arab Emirates. System integrators now specify "tri-radio" silicon as a baseline requirement, compressing addressable market opportunity for standalone Wi-Fi-only suppliers.
Wi-Fi Semiconductor Chipset Market Segmentation
Wi-Fi semiconductor chipsets exhibit divergent replacement cycles across product forms and technology generations, with integrated solutions turning over every 18-24 months while discrete modules persist for 5-7 years in industrial installations. Understanding these temporal patterns enables suppliers to align R&D cadence with revenue predictability across customer portfolios.
Product Type:
Chipsets and modules compress design cycles to 12-18 months as OEMs chase spectrum certifications, while adaptive antennas and integrated circuits stretch refresh intervals to 36-48 months in infrastructure deployments.
- Chipsets:These monolithic solutions integrate baseband processors, MAC-layer engines, and RF transceivers onto single die, typically fabricated at 7nm or 5nm FinFET nodes for premium tiers. Demand concentrates in South Korean and Chinese smartphone OEMs seeking modem-RF system integration for flagship launches. Qualcomm and MediaTek dominate this socket through aggressive tape-out schedules that match annual device refresh cycles.
- Modules:Pre-certified radio modules combine chipsets with front-end components and antenna matching networks, accelerating time-to-market for mid-tier consumer electronics manufacturers. German industrial automation OEMs favor these solutions for AGV fleet deployments where regulatory pre-approval reduces certification risk and compresses deployment timelines.
- Integrated Circuits:Discrete RF and baseband ICs serve router OEMs pursuing custom board-level optimization for enterprise access points. These components appeal to Taiwanese networking equipment manufacturers seeking differentiation through proprietary thermal and power management implementations.
- Adaptive Antennas:Beamforming antenna arrays with integrated phase shifters and power amplifiers enable spatial multiplexing gains in high-density venues. Deployment concentrates in Singaporean smart building projects and UAE healthcare facilities where spectrum efficiency justifies premium hardware costs.
Chipsets anchor the volume base while adaptive antennas gain share at the steepest rate as mesh networking and enterprise infrastructure deployments accelerate.
Technology:
Cost tiers stratify sharply across Wi-Fi generations, with legacy silicon commanding sub-dollar unit economics and Wi-Fi 7 development programs absorbing $50-80 million per tape-out.
- Wi-Fi 6:OFDMA and 1024-QAM modulation schemes deliver 9.6 Gbps theoretical peak rates across 2.4 GHz and 5 GHz bands. Chinese OEMs in Shenzhen and Shanghai have concentrated procurement around Wi-Fi 6 platforms as baseline specifications for domestic consumer electronics exports.
- Wi-Fi 6E:Tri-band architectures add 6 GHz spectrum access with 160 MHz channel bonding, reducing congestion in dense residential environments. FCC spectrum liberalization in the United States unlocked immediate design-win opportunities, with ETSI harmonization talks now propagating equivalent certifications across EU member states.
- Legacy Wi-Fi:IEEE 802.11a/b/g/n implementations persist in cost-constrained IoT endpoints and sensor networks where throughput requirements remain modest. Indian BharatNet rural broadband initiatives specify these chipsets for outdoor CPE deployments where extended temperature tolerance outweighs peak performance.
- FD-MIMO:Full-dimension multiple-input multiple-output leverages 3D beamforming and massive antenna arrays for stadium and convention center deployments. South Korean telecommunications providers pilot these architectures for K-pop venue connectivity and smart factory deterministic wireless applications.
Legacy Wi-Fi retains the largest installed base though Wi-Fi 6E demonstrates the steepest expansion trajectory among active design programs.
Application:
Volume concentration varies dramatically by deployment environment, with consumer electronics absorbing nine-figure annual unit shipments and industrial automation commanding 10-15x per-unit premiums.
- Smart Home Devices:Mesh networking nodes, security cameras, and voice assistants require always-on connectivity with aggressive standby power budgets. Amazon and Google specification programs drive merchant silicon selection for these sockets, with tri-radio Wi-Fi-Bluetooth-Zigbee integration now mandatory for ecosystem certification.
- Industrial Automation:Deterministic wireless for mobile robotics and programmable logic controllers demands sub-10 millisecond latency with 99.999% reliability guarantees. German automotive manufacturers in Bavaria and Baden-Württemberg specify Wi-Fi 6E and Wi-Fi 7 platforms for factory floor retrofits replacing wired Ethernet.
- Wearable Technology:Smartwatches and fitness trackers prioritize die miniaturization and ultra-low power states over peak throughput. Apple and Samsung captive semiconductor programs dominate this segment, squeezing addressable opportunity for merchant Wi-Fi suppliers.
- Consumer Electronics:Televisions, gaming consoles, and streaming devices represent the highest-volume application category with annual refresh cycles and aggressive cost targets. Japanese and South Korean electronics conglomerates maintain dual-sourcing strategies across Qualcomm, MediaTek, and Broadcom to mitigate supply concentration risk.
Consumer Electronics anchors the volume base while Industrial Automation gains share at the steepest rate as manufacturing digitization accelerates across OECD economies.
End User:
Procurement sophistication diverges sharply, with telecommunications providers demanding roadmap visibility and retail consumers purchasing through opaque OEM bundling arrangements.
- OEMs:Device manufacturers specify chipsets 18-24 months ahead of commercial launch, requiring suppliers to commit to die shrinks and packaging roadmaps. Chinese smartphone OEMs have expanded captive semiconductor teams in Shanghai and Shenzhen, reducing merchant silicon dependence.
- Telecommunications Providers:Carriers bundle CPE and mesh systems with subscription services, prioritizing firmware update mechanisms and remote diagnostics. Verizon and AT&T certification programs in the United States impose 6-9 month qualification timelines that filter supplier participation.
- Commercial Enterprises:IT procurement teams consolidate around unified connectivity platforms, specifying tri-radio silicon for smart building and healthcare facility deployments. Singaporean and UAE system integrators now mandate single-chip Wi-Fi-Bluetooth-Zigbee solutions as baseline requirements.
- Retail Consumers:End-user purchasing decisions are intermediated by router and mesh system OEMs, with chipset branding rarely visible at point of sale. Amazon and Best Buy retail channels concentrate demand around sub-$200 price points that constrain bill-of-materials allocations for connectivity silicon.
OEMs anchor the volume base while Telecommunications Providers gain share at the steepest rate as managed Wi-Fi services expand across North American and European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex and Yangtze River Delta manufacturing corridors anchor Asia-Pacific semiconductor logistics, while the Rotterdam-Antwerp corridor handles European distribution. These infrastructure assets condition regional chipset availability and inventory velocity.
United States
Enterprise Wi-Fi 6E deployments in Dallas and Austin data centers drive merchant silicon procurement. FCC spectrum liberalization for 6 GHz unlicensed access governs certification timelines. The Silicon Valley-San Jose corridor hosts RF front-end design centers where Qualcomm and Broadcom maintain advanced packaging partnerships.
China
Domestic OEM captive semiconductor programs in Shanghai and Shenzhen reduce import dependence for baseband processors. MIIT GB standards mandate domestic testing protocols that filter market access. The Zhangjiang Hi-Tech Park cluster concentrates fabless design teams pursuing tri-band architectures for smart home exports.
Germany
Industrial automation retrofits in Bavaria and Baden-Württemberg specify deterministic wireless for mobile robotics fleets. ETSI RED compliance and cybersecurity baselines condition product localization. The Munich-Ingolstadt corridor hosts automotive OEM procurement teams consolidating connectivity platform specifications.
South Korea
Smartphone OEM flagship cycles in Seoul and Suwon drive annual chipset refresh demand. Government-backed semiconductor clusters in Pyeongtaek and Yongin narrow process-technology gaps with leading-edge foundries. The Pangyo Techno Valley concentrates RFIC-BBIC co-design talent commanding premium compensation.
India
BharatNet rural broadband initiatives specify low-cost outdoor CPE chipsets with extended temperature tolerance. TRAI infrastructure mandates accelerate domestic manufacturing localization. The Bengaluru-Hyderabad corridor hosts system integrators piloting mesh networking for smart city deployments.
Wi-Fi Semiconductor Chipset Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower socket exposure. The supplier base concentrates around three cash-rich integrated device manufacturers and a fragmented tier of fabless connectivity specialists. Strategic archetypes span modem-RF system integrators, merchant silicon providers, and captive semiconductor programs. Competitive moves center on advanced node tape-out acceleration and RF front-end supply consolidation.
Within the platform integrator tier, Qualcomm Technologies, Inc. and Broadcom Inc. occupy positions defined by modem-RF system integration and enterprise access-point merchant silicon respectively. MediaTek Inc. anchors the mid-tier consumer electronics vector with integrated connectivity platforms. These three entities exemplify the strategic divergence between premium smartphone socket capture and cost-optimized volume deployment.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Broadcom Inc. |
| MediaTek Inc. |
| Intel Corporation |
| Realtek Semiconductor Corp. |
| NXP Semiconductors |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Marvell Technology Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Taiwanese foundry concentration at 5nm and 7nm FinFET nodes concentrates margin capture upstream, forcing fabless chipset vendors to absorb $50-80 million tape-out costs while downstream router OEMs face commoditization at sub-$200 retail price points. This structural asymmetry splits profitability between integrated device manufacturers with captive capacity and merchant silicon suppliers locked into annual price-down cycles with smartphone OEMs.
Pricing Analysis
FCC Part 15 rules for 6 GHz unlicensed spectrum dictate the pricing tier structure for Wi-Fi semiconductor chipsets, with tri-band Wi-Fi 6E platforms commanding premium positioning against legacy dual-band alternatives. Pricing stratifies across premium smartphone sockets, standard enterprise access points, and economy-tier IoT modules, with certification grade and volume scale as primary differentiation levers. Cost compression in the mid-tier consumer electronics segment is intensifying because Chinese OEM captive programs are displacing merchant silicon with in-house designs. Retail consumers purchasing through Amazon and Best Buy channels exhibit highest price sensitivity, while telecommunications providers bundling managed Wi-Fi services demonstrate lowest sensitivity due to subscription revenue offsets.
Supply Chain Analysis
12-inch silicon wafer feedstock draws from Taiwan, South Korea, and the United States, with advanced node logic fabrication concentrating at TSMC and Samsung Foundry facilities. Bulk acoustic wave filters, GaAs power amplifiers, and advanced substrate materials rest on Murata, Qorvo, and Broadcom as critical component dependencies. Single-source vulnerability in 6 GHz RF front-end manufacturing creates structural risk for tri-band chipset availability. Distribution runs through Shenzhen port logistics for Asia-Pacific manufacturing, Rotterdam-Antwerp corridors for European markets, and direct enterprise procurement channels for North American telecommunications providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wi-Fi semiconductor architectures are approaching a platform-economics inflection where tri-radio integration of Wi-Fi, Bluetooth, and Zigbee is becoming mandatory for ecosystem certification by Amazon and Google, collapsing addressable market opportunity for standalone connectivity suppliers.
For Market Incumbents: Pre-empt displacement by Chinese captive semiconductor programs through accelerated Wi-Fi 7 tape-out schedules that match annual smartphone refresh cycles. Defend enterprise access-point margins by deepening backward integration into RF front-end components to offset Murata and Qorvo supply concentration. Prioritize certification investment for FCC, ETSI, and MIIT parallel approval to compress 6-9 month qualification timelines that filter supplier participation at Verizon and AT&T. For New Entrants and Emerging Players: Build out software-defined radio architectures that allow single-silicon SKUs to serve multiple regional regulatory domains through firmware updates, reducing inventory fragmentation for router OEMs. Target India's BharatNet rural broadband initiative and Indonesia's similar programs as the most penetrable geography, where low-cost outdoor CPE chipsets with extended temperature tolerance face limited incumbent competition. Pursue system integrator partnerships in Singapore and UAE smart building deployments as the primary go-to-market angle for tri-radio platform adoption. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed RF front-end specialists holding bulk acoustic wave filter patents and GaAs power amplifier capabilities. Long-term viability hinges on 5-10 year positioning for Wi-Fi and 5G convergence in private network deployments for mining operations in Australia and Canada. Watch spectrum harmonization talks between FCC and ETSI as the critical signal for which Wi-Fi technology generation achieves cross-border deployment momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Tape-Out Acceleration | Qualcomm and MediaTek match annual smartphone refresh cycles with 5nm FinFET deployments. |
| RF Front-End Supply Consolidation | Broadcom deepens captive BAW filter production to secure 6 GHz chipset supply chains. |
| Tri-Radio Platform Integration | Single-chip Wi-Fi-Bluetooth-Zigbee solutions displace discrete component sourcing for smart buildings. |
| Software-Defined Radio Architecture | Programmable baseband implementations reduce SKU fragmentation for multi-regional router OEMs. |
| Regional Certification Parallelism | Simultaneous FCC, ETSI, MIIT campaigns compress time-to-revenue for new chipset generations. |
Study Parameters
Initial hypotheses were tested against primary input from RFIC design engineers, enterprise IT procurement managers, telecommunications carrier certification leads, and fabless semiconductor executives and refined through secondary validation against SEC 10-K filings, FCC equipment authorization databases, ETSI harmonization documents, and MIIT GB standard releases. Bottom-up triangulation across smartphone OEM bill-of-materials estimates and top-down reconciliation with foundry capacity utilization data anchored volume and value projections.
Demand-supply balance modeling across the projection horizon incorporated technology generation transitions, spectrum certification timelines, and captive semiconductor program expansion as core analytical framework elements. Segmentation dimensions spanned product type, Wi-Fi standard generation, application vertical, and end-user procurement sophistication. CAGRs were derived from installed base replacement cycle analysis and greenfield deployment velocity across consumer electronics, enterprise infrastructure, and industrial automation end markets. Foundry wafer pricing trajectories and RF front-end component supply constraints fed directly into cost curve and margin projection modules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese captive design teams or accelerated ETSI 6 GHz harmonization would shift outcomes substantially. Quarterly review of spectrum auction timelines, foundry capacity allocation announcements, and OEM vertical integration disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Ethernet Access Device Market