
 Semiconductor Device in Communication Industry Market | 2026-2036
Semiconductor Device in Communication Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Device in Communication Industry Market Insights
REACH compliance is pivoting the cost-of-entry calculus for European-bound RF modules and baseband processors. TSMC leverages advanced packaging co-development with communication chip designers to sustain process leadership at sub-5nm nodes. Samsung Electronics anchors memory supply for 5G infrastructure through its Pyeongtaek fabrication complex. Intel competes aggressively in base station silicon with its foundry services division.
Semiconductor devices in communication encompass transistors, diodes, integrated circuits, and resistors engineered for signal processing, power management, and frequency modulation in networked systems. These components operate across silicon, gallium nitride, and silicon carbide substrates to achieve switching speeds exceeding 100 GHz for millimeter-wave transmission. Gallium nitride technology leads in base station power amplifiers due to superior thermal efficiency and breakdown voltage. Mobile devices and networking equipment represent the dominant application segments where margin pools concentrate in RF front-end modules and high-speed SerDes interfaces.
FCC spectrum allocation rules, EU REACH substance restrictions, and China's GB standards for telecommunications equipment collectively shape product certification timelines and material selection across supply chains. ECHA enforcement of SVHC declarations is forcing component distributors to requalify passive component metallurgy. Stakeholders must monitor divergence between US CHIPS Act domestic content incentives and EU CSRD supply chain disclosure mandates to anticipate sourcing cost trajectories.
Market Dynamics
Gallium nitride power amplifiers are displacing silicon LDMOS in 5G base stations, compressing design cycles and forcing foundry capacity reallocation toward wide-bandgap substrates.
Growth Catalysts
- 5G millimeter-wave deployment:Telecommunication providers in South Korea and Japan are accelerating base station buildouts, pulling demand for RF front-end modules operating above 24 GHz.
- EU AI Act compliance:Hardware certification requirements for AI-enabled network equipment are creating premium tier demand for traceable semiconductor provenance.
- REACH SVHC declarations:ECHA enforcement is mandating metallurgical requalification of passive components, filtering out non-compliant distributors and consolidating qualified supplier pools.
Market Restraints
- Sub-5nm foundry concentration:Advanced node capacity clusters in Taiwan, creating single-point vulnerability for baseband processor supply.
- Silicon carbide substrate shortage:Limited boule growth capacity constrains power device expansion for high-frequency transmission systems.
- Dual-use export controls:US Bureau of Industry and Security restrictions on gallium nitride epitaxy equipment are lengthening lead times for non-domestic RF amplifier manufacturers.
Strategic Opportunities
- India PLI scheme for telecom:Domestic manufacturing incentives for 5G equipment are attracting component packaging investments away from traditional ASEAN hubs.
- Open RAN disaggregation:Interface standardization is expanding the addressable market for merchant silicon suppliers previously locked out of integrated base station architectures.
- Silicon photonics convergence:Co-packaged optics in data center interconnects are creating new demand for III-V compound semiconductor lasers on silicon substrates.
Industry Challenges
- Compound semiconductor process engineering:Gallium nitride HEMT fabrication requires specialized MOCVD expertise scarce outside established wide-bandgap foundries.
- Multi-jurisdiction certification stacking:FCC, CE marking, and GB standard testing sequences for RF modules extend product launch timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Device in Communication Industry Market |
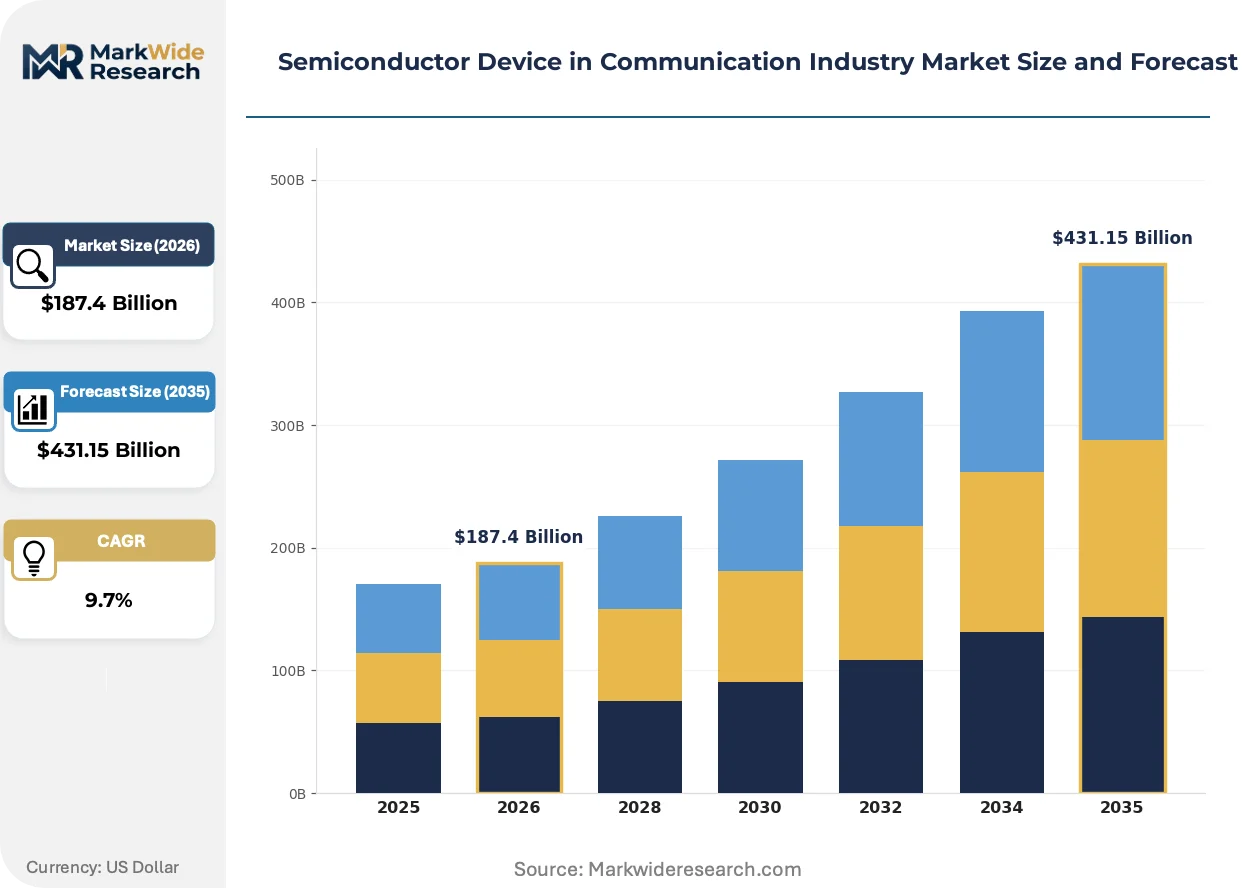
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transistors, Diodes, ICs, Resistors Technology: Silicon, Gallium Nitride, Silicon Carbide, OLED Application: Mobile Devices, Networking Equipment, Base Stations, Optical Communication End User: Telecommunication Providers, Electronics Manufacturers, Research Institutions, Component Distributors |
| Companies Covered | SK hynix, AMD, NVIDIA, Infineon Technologies, NXP Semiconductors, TSMC, Intel, Analog Devices, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Device in Communication Industry Market Trends and Innovations
Signal processing architectures are bifurcating between power-optimized mobile handsets and thermal-constrained base station infrastructure, driving divergent substrate and packaging roadmaps.
Gallium nitride-on-silicon technology enables higher breakdown voltage and thermal conductivity for power amplifiers in massive MIMO arrays. Network equipment manufacturers in South Korea and China are transitioning production lines from silicon LDMOS within eighteen-month windows. This substrate shift is expanding into sub-6 GHz small cell deployments previously reserved for lower-cost silicon solutions.
EU REACH substance restrictions now cover fourteen additional candidate SVHCs in semiconductor metallurgy and molding compounds. Component distributors must maintain dual inventory streams for European-bound versus other-destination shipments. RF module suppliers serving automotive and telecom verticals simultaneously face the steepest compliance cost escalation.
Original equipment manufacturers are consolidating RF front-end procurement through direct foundry relationships, bypassing traditional distributor channels for high-volume 5G modem programs. Tier-one smartphone brands in China and South Korea now negotiate die-level pricing directly with compound semiconductor foundries. This channel compression is most visible in premium flagship device segments where bill-of-materials transparency has become a competitive weapon.
Semiconductor Device in Communication Industry Market Segmentation
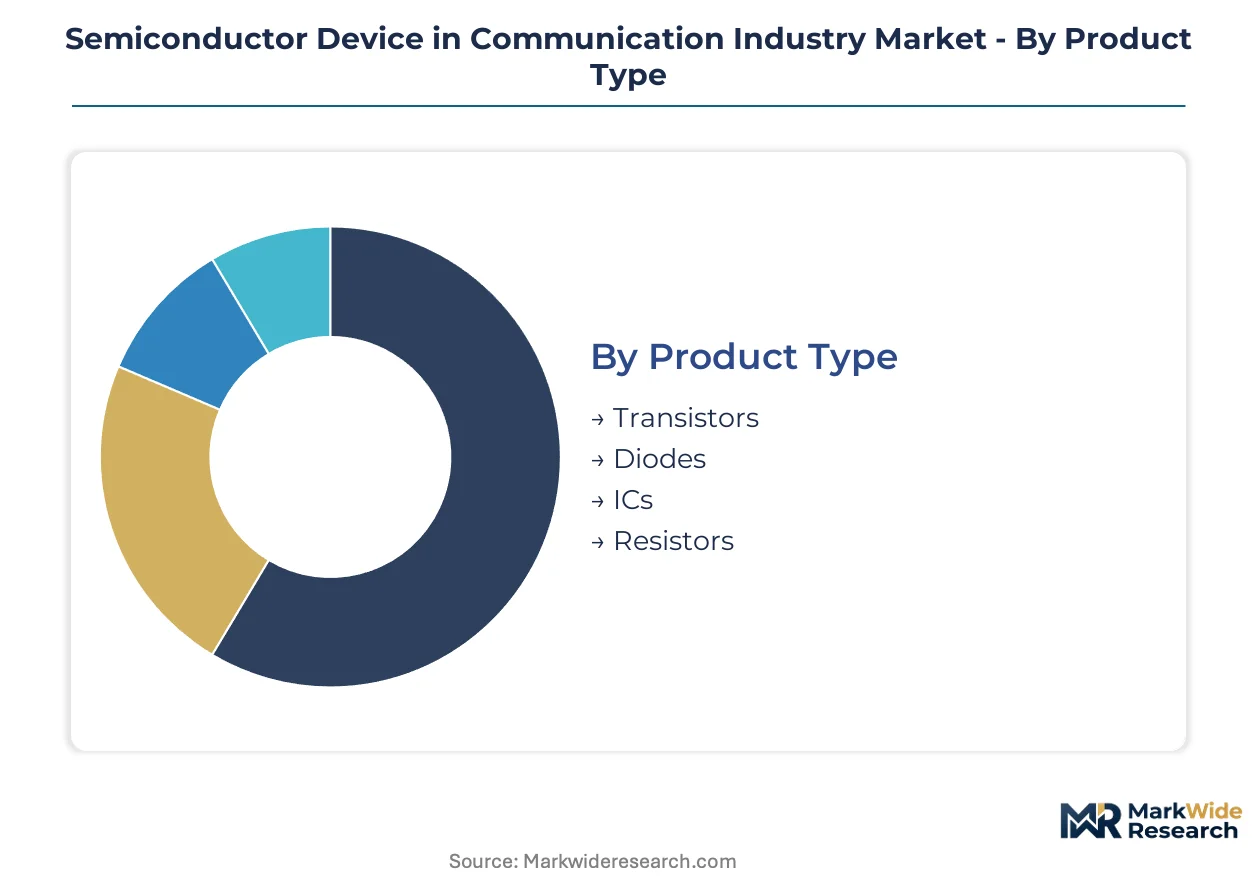
Segmentation in semiconductor devices for communication reveals how certification burdens, thermal requirements, and frequency specifications concentrate margin pools across disparate technology tiers. Each dimension exposes different vulnerability points to REACH compliance, export controls, and foundry capacity allocation.
Product Type:
FCC Part 15 emissions testing applies universally across all product types, while EU RoHS substance restrictions hit passive components hardest and CE marking complexity escalates with integrated functionality.
- Transistors:Bipolar and field-effect architectures handle switching and amplification in RF front-end modules. Demand clusters in South Korea for 5G smartphone power amplifiers, with GaN HEMT variants requiring Bureau of Industry and Security licensing scrutiny.
- ICs:System-on-chip designs integrate baseband processing, RF transceivers, and power management. Pyeongtaek-area foundries anchor supply for flagship mobile modems, though sub-5nm capacity constraints lengthen procurement cycles.
- Diodes:Rectifier and protection devices manage voltage regulation across communication systems.
- Resistors:Passive components face ECHA SVHC requalification mandates for termination metallurgy.
ICs sit at the top of the volume ranking, with transistors climbing the fastest.
Technology:
Substrate selection determines thermal ceiling, breakdown voltage, and which foundry ecosystems a design can access.
- Gallium Nitride:Wide-bandgap properties enable power amplifiers above 100 GHz with superior thermal efficiency. South Korean base station manufacturers are displacing silicon LDMOS within compressed eighteen-month transition windows.
- Silicon:Mature CMOS processes dominate cost-sensitive mobile handsets and legacy networking gear. Yongin-cluster foundries maintain cost leadership through scale economies at 28nm and above nodes.
- Silicon Carbide:Limited boule growth capacity constrains supply for high-frequency transmission power devices.
- OLED:Display driver integration creates specialized demand in premium mobile handsets.
Silicon retains volume leadership, though Gallium Nitride is gaining share fastest in infrastructure applications.
Application:
Deployment environment dictates reliability grade, temperature range certification, and whether GB standards or FCC rules govern final acceptance testing.
- Base Stations:Massive MIMO arrays require GaN power amplifiers with CE marking for European deployments and extended thermal cycling validation. South Korean and Japanese telecommunication providers are accelerating millimeter-wave buildouts above 24 GHz.
- Mobile Devices:Handset RF front-end modules integrate filters, switches, and power amplifiers under severe space constraints. Direct foundry relationships now bypass traditional distribution for high-volume 5G modem programs.
- Networking Equipment:Enterprise and data center switches demand high-speed SerDes interfaces.
- Optical Communication:Co-packaged optics in data center interconnects create demand for III-V compound semiconductor lasers.
Mobile Devices command the highest shipment volumes, with Base Stations expanding most quickly.
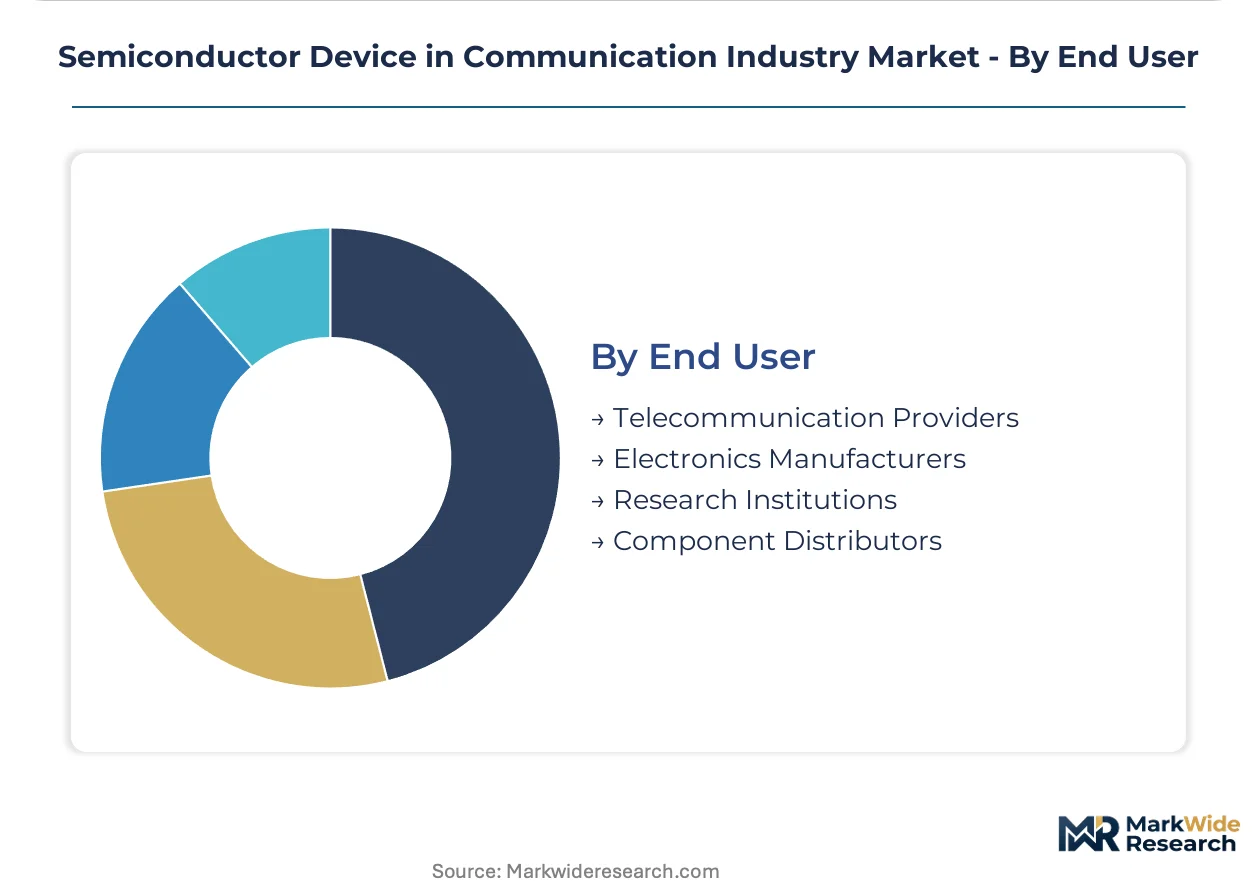
End User:
Procurement sophistication varies sharply, from traceability mandates for AI Act compliance to price-sensitive spot buying.
- Telecommunication Providers:Carriers specify die-level provenance and impose REACH documentation requirements on RF module suppliers. Open RAN disaggregation is expanding merchant silicon qualification opportunities previously locked behind integrated vendor architectures.
- Component Distributors:Middle-tier distributors face ECHA enforcement pressure to maintain dual inventory streams for European-bound versus other-destination shipments.
- Electronics Manufacturers:OEMs consolidate procurement through direct foundry negotiations.
- Research Institutions:Academic and government labs drive early-stage compound semiconductor process development.
Telecommunication Providers anchor procurement volume, with Electronics Manufacturers deepening direct sourcing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized MOCVD engineers and compound semiconductor physicists concentrate in Taiwan, South Korea, and Germany, anchoring the three dominant manufacturing ecosystems for RF and baseband components.
United States
FCC spectrum auctions for millimeter-wave bands drive base station silicon procurement from domestic fabless designers. Bureau of Industry and Security export controls on GaN epitaxy equipment lengthen lead times for non-domestic RF amplifier manufacturers. Greater Phoenix hosts Intel's foundry services expansion targeting base station processors.
South Korea
Telecommunication providers accelerate 5G millimeter-wave buildouts above 24 GHz, pulling demand for RF front-end modules. MFDS hardware certification requirements for network equipment create premium tier demand for traceable semiconductor provenance. Pyeongtaek and Yongin foundry clusters anchor memory supply for 5G infrastructure through Samsung Electronics fabrication complexes.
China
MIIT GB standards for telecommunications equipment govern acceptance testing for domestic 5G deployments. SAMR oversight of semiconductor pricing and supply agreements shapes procurement negotiations for state-owned carriers. Yangtze River Delta packaging houses consolidate RF module assembly for both domestic consumption and re-export.
Germany
ECHA enforcement of REACH SVHC declarations mandates metallurgical requalification of passive components for European-bound shipments. CE marking complexity for integrated RF modules extends product launch timelines. Bavaria-based automotive suppliers simultaneously face compliance cost escalation for telecom-grade components serving connected vehicle programs.
Japan
METI industrial policy directs funding toward compound semiconductor substrate development to reduce import dependence for wide-bandgap materials. JIS standards for telecommunications equipment create parallel certification tracks for domestic versus export-bound production. Kyushu foundries specialize in silicon carbide boule growth for high-frequency transmission power devices.
Semiconductor Device in Communication Industry Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate technologies and packaging tiers. The vendor base separates into three strategic archetypes: integrated device manufacturers controlling epitaxy through test, fabless designers outsourcing to captive foundry capacity, and compound semiconductor foundries serving merchant markets. Consolidation pressures concentrate around advanced packaging capabilities and wide-bandgap substrate access. Competitive moves center on foundry capacity reservations and co-development partnerships with telecommunication equipment vendors.
Among South Korea-based memory conglomerates, SK hynix and Samsung Electronics exemplify the integrated-device-manufacturer archetype with captive fabrication complexes. TSMC represents the pure-play foundry model, occupying a position as the dominant advanced-node supplier for fabless baseband designers. These three entities anchor the supply-side structure through their control of sub-5nm logic and high-bandwidth memory capacity.
| Leading Market Players |
|---|
| SK hynix |
| AMD |
| NVIDIA |
| Infineon Technologies |
| NXP Semiconductors |
| TSMC |
| Intel |
| Analog Devices |
| Samsung Electronics |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride-on-silicon substrate transitions simultaneously compress power amplifier cost curves and concentrate procurement leverage among South Korean and Taiwanese foundries with captive MOCVD capacity. This technology migration reshapes both component economics and supplier power dynamics across 5G infrastructure supply chains.
Pricing Analysis
Component bundling versus die-level unbundling now defines pricing architecture across RF front-end modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in economy-tier silicon LDMOS amplifiers is intensifying because gallium nitride displacement accelerates capacity reallocation. Telecommunication providers exhibit lowest price sensitivity due to traceability mandates, while component distributors face margin tightening from dual inventory maintenance for REACH compliance.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Greater Phoenix, and Bavaria anchor hub-and-spoke fulfillment patterns for RF modules and baseband processors. Supply concentration in Taiwan, South Korea, and the United States creates single-point vulnerability for sub-5nm logic and wide-bandgap substrates. Raw material dependencies span gallium nitride epitaxy equipment, silicon carbide boules, and high-purity semiconductor gases. Tariff exposure on compound semiconductor process tools lengthens lead times for non-domestic manufacturers. Distribution runs through direct foundry relationships that bypass traditional channel intermediaries for high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Semiconductor Device in Communication Industry Market functions as a stable compounder where 5G infrastructure refresh cycles and millimeter-wave spectrum allocation generate sustained component demand across decade-long deployment horizons.
For Market Incumbents: Hedge against gallium nitride substrate supply disruption by securing long-term MOCVD equipment reservations and qualifying secondary wide-bandgap foundry sources outside Taiwan. Deepen backward integration into advanced packaging capabilities at Pyeongtaek-area facilities to defend process leadership against merchant foundry competition. Prioritize REACH documentation systems that automate SVHC traceability for European-bound shipments. For New Entrants and Emerging Players: Begin with Open RAN disaggregation opportunities in India PLI-supported manufacturing zones where interface standardization lowers architectural barriers to merchant silicon qualification. Target base station power amplifier segments below 6 GHz where silicon-to-gallium nitride transition windows create supplier requalification openings. Pursue co-development partnerships with domestic telecom equipment vendors rather than direct foundry competition. For Investors and Strategic Acquirers: Roll-up economics work for compound semiconductor packaging specialists because foundry capacity scarcity and certification stacking burdens favor scaled operators with established regulatory compliance infrastructure. Focus acquisition screening on targets with CE marking expertise and automotive-telecom cross-vertical capabilities. Monitor Bureau of Industry and Security export control expansion as the primary inflection signal for non-domestic equipment valuation discounts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Agreements | TSMC and Samsung Electronics leverage long-term contracts to lock in sub-5nm allocation for baseband processor programs. |
| Advanced Packaging Co-Development | Foundry partnerships with telecommunication equipment vendors accelerate thermal management solutions for massive MIMO arrays. |
| REACH Compliance Automation | ECHA enforcement mandates drive investment in metallurgical traceability systems for European-bound RF component shipments. |
| Open RAN Interface Certification | Standardization expands merchant silicon qualification opportunities previously locked behind integrated base station architectures. |
| Wide-Bandgap Substrate Sourcing | Gallium nitride and silicon carbide supply agreements determine power amplifier cost competitiveness in millimeter-wave deployments. |
Research Methodology
Bottom-up telecommunication equipment deployment modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with RF front-end procurement managers, compound semiconductor process engineers, network equipment regulatory affairs leads, and carrier technology planning officers combine with secondary validation from FCC spectrum auction records, ECHA SVHC candidate list updates, MIIT GB standard filings, and SEC semiconductor capital expenditure disclosures. Triangulation across supply-side capacity announcements and demand-side deployment schedules ensures dimensional consistency.
Historical trendline analysis of substrate technology transitions and certification timeline patterns informs projection methodology across the analysis window. Segmentation dimensions span product type, substrate technology, deployment application, and procurement sophistication tier. CAGRs derive from fitted adoption curves for gallium nitride penetration rates and millimeter-wave base station buildout trajectories. Forecast inputs incorporate foundry yield learning curves and regulatory enforcement intensity indices.
Caveats apply where Bureau of Industry and Security export control expansion, ECHA SVHC list revision, or spectrum auction delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Transceiver Chip Market