
 Global Semiconductor Lead Frame Market | 2026-2036
Global Semiconductor Lead Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Lead Frame Market Outlook
Advanced packaging migration toward multi-chip modules and fan-out wafer-level packaging is reshaping lead frame specifications across the semiconductor supply chain. Mitsui High-tec leverages ultra-precision etching capabilities to dominate high-density QFN applications. Samsung Electronics anchors captive demand through in-house packaging operations spanning memory and logic devices. Chang Wah Technology competes on cost-optimized stamping processes for mid-tier consumer ICs.
A semiconductor lead frame is a thin metal structure that mechanically supports an integrated circuit die while providing electrical connectivity to external circuitry, typically manufactured from copper alloys or iron-nickel alloys via stamping or chemical etching processes with tolerances reaching ±10 micrometers. Plastic lead frames sustain the largest volume position due to cost efficiency in high-pin-count consumer packages, while metal lead frames capture premium margin pools in automotive-grade reliability applications. Wire-bonding technology occupies the mature installed base, though flip-chip technology is displacing conventional interconnects in advanced node packaging where pitch shrink demands alternative metallization.
China's MEE enforces GB standards restricting hazardous substances in electronic components, directly affecting alloy composition and surface plating chemistries for lead frames sold into the Chinese market. Japan's METI coordinates JIS standards with PMDA quality frameworks to ensure medical and automotive semiconductor reliability, creating certification barriers for non-compliant suppliers. Korea's MFDS aligns with ISO 10993 for biocompatible device packaging, extending regulatory scope into emerging healthcare IC applications. Stakeholders must monitor evolving alloy substitution timelines as copper price volatility and sustainability mandates force material strategy recalibration.
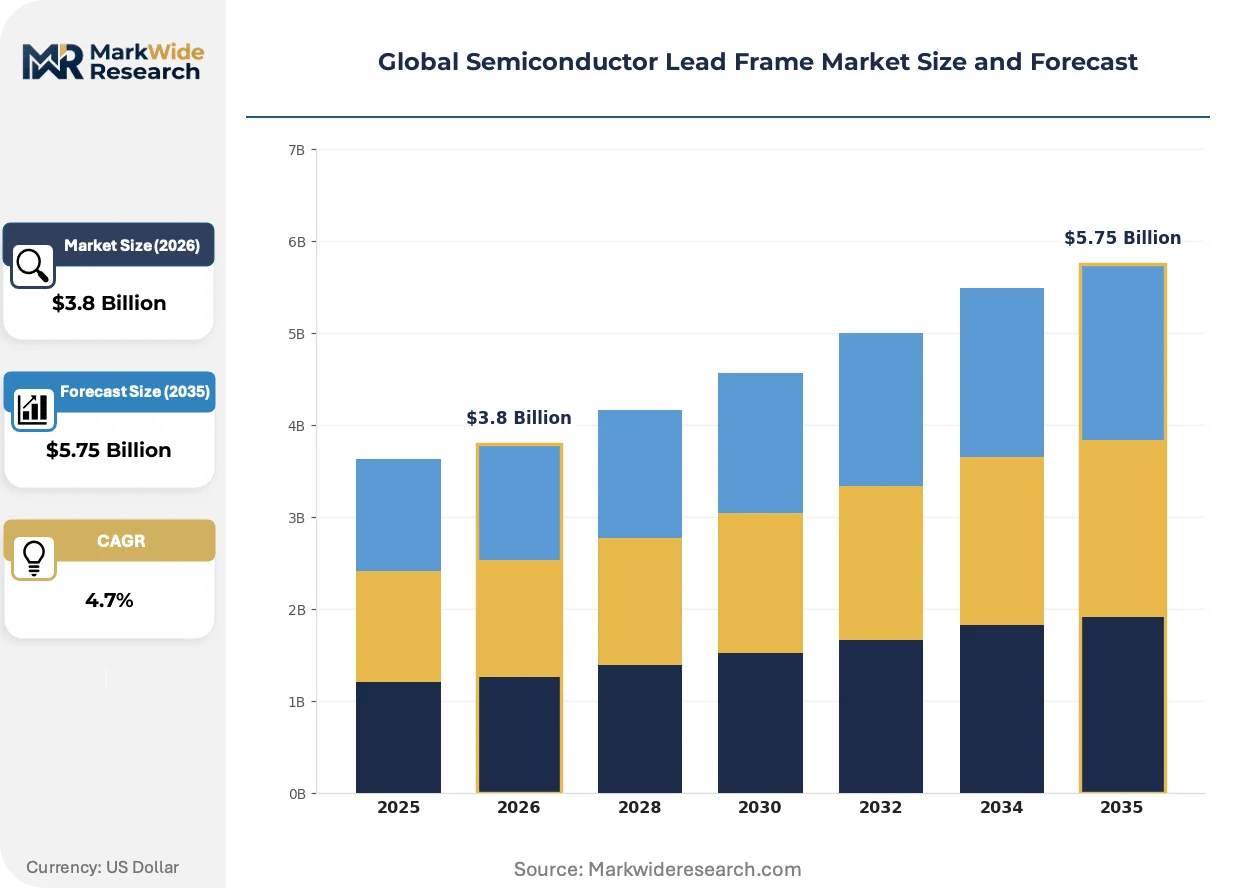
Market Dynamics
Advanced packaging migration toward multi-chip modules and fan-out wafer-level packaging is compressing lead frame specifications while automotive electrification mandates expand high-reliability alloy demand. Copper price volatility and China's dual carbon enforcement are forcing simultaneous material recalibration across East Asian manufacturing clusters.
Growth Catalysts
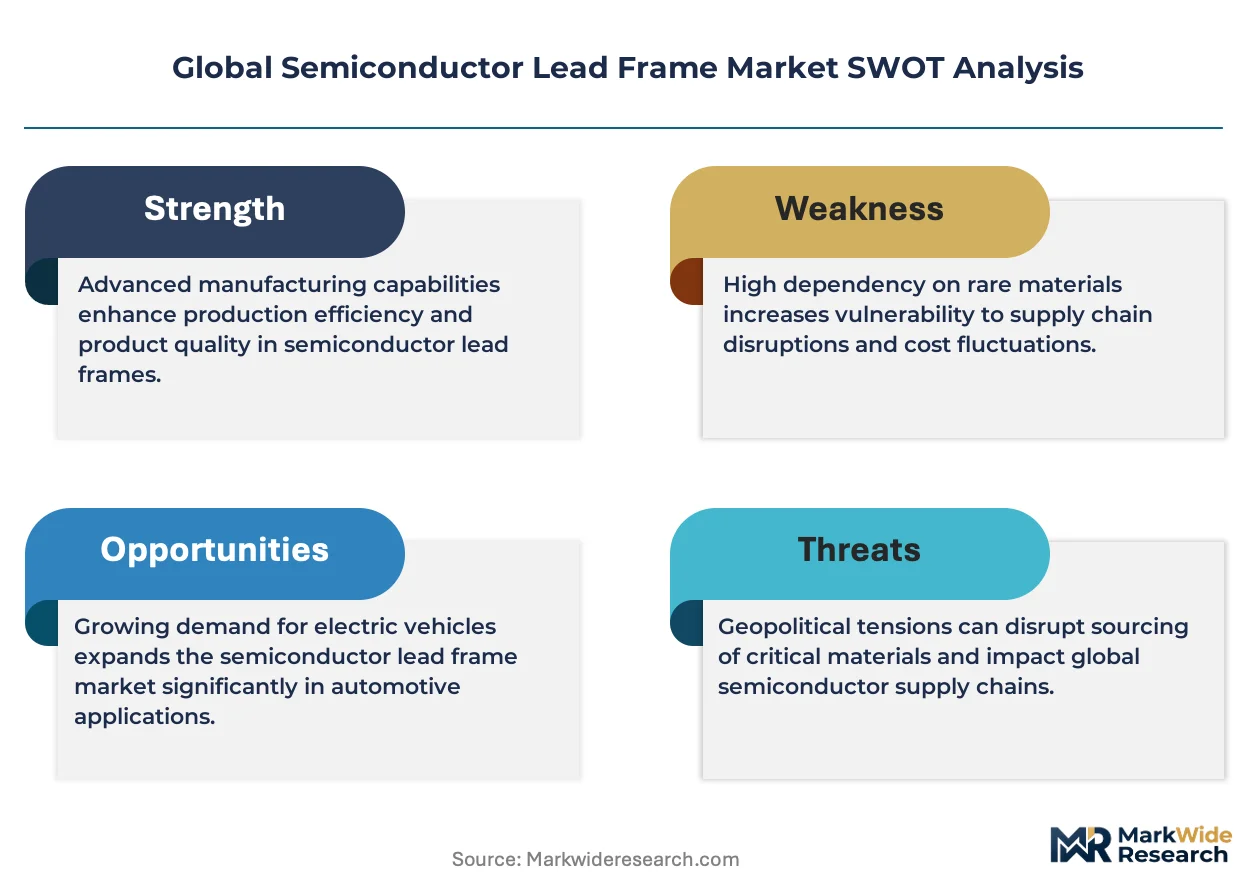
- Automotive electronics penetration:Electric powertrain architectures and ADAS sensor proliferation are expanding high-pin-count QFN demand for motor control and battery management ICs.
- China's GB standards enforcement:MEE restrictions on hazardous substances in electronic components are accelerating compliant alloy substitution timelines for suppliers accessing Chinese packaging facilities.
- Etching precision advances:Sub-20-micron tolerance chemical etching processes are enabling thinner lead frames for mobile and wearable device miniaturization.
Market Restraints
- Copper alloy cost volatility:LME copper price swings exceeding 30% annually are compressing stamping-process margins for mid-tier consumer IC suppliers.
- East Asian supply concentration:Over 70% of high-volume lead frame manufacturing concentrates in China's Pearl River Delta and Japan's Chubu region, creating single-point vulnerability.
- Flip-chip substitution ceiling:Organic substrate-based flip-chip interconnects are capturing advanced node packaging above 7nm, capping lead frame addressable market in leading-edge logic.
Strategic Opportunities
- India packaging infrastructure buildout:PLI scheme incentives for semiconductor assembly and test facilities are creating captive demand for cost-optimized stamped lead frames.
- Biocompatible device packaging:Korea's MFDS alignment with ISO 10993 is extending lead frame specifications into implantable medical IC applications with premium surface plating requirements.
- Copper-iron-nickel alloy hybridization:Convergence of thermal expansion matching with cost efficiency is opening mid-tier automotive sensor packaging previously reserved for pure copper alloys.
Industry Challenges
- Ultra-precision etching talent scarcity:Chemical process engineering expertise for sub-15-micron tolerance production concentrates in Japan's Nagoya and South Korea's Gyeonggi-do clusters.
- Multi-jurisdiction certification timelines:Simultaneous compliance with China's GB standards, Japan's JIS frameworks, and EU REACH registration is extending new product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Lead Frame Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Lead Frames, Metal Lead Frames, Hybrid Lead Frames, Glass Lead Frames Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Equipment Technology: Die-Bonding Technology, Wire-Bonding Technology, Flip-Chip Technology, Hybrid Technology End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Semiconductor Manufacturers |
| Companies Covered | Infineon Technologies, ASM Pacific Technology, Samsung Electronics, Shinko Electric Industries, Amkor Technology, Texas Instruments, Mitsui High-tec, Chang Wah Technology, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Lead Frame Market Strategic Shifts
Etching-based manufacturing is overtaking mechanical stamping as the dominant precision pathway, while regulatory chemistry restrictions and automotive reliability mandates are rewriting alloy composition roadmaps across supplier bases.
Fan-out wafer-level packaging (FOWLP) redistribution layer technology is rendering obsolete conventional wire-bond lead frames in high-performance computing and 5G baseband processors. Samsung Electronics and TSMC packaging subsidiaries are adopting FOWLP at scale for AI accelerator and networking silicon. This displacement is compressing demand for traditional QFP and QFN formats above 0.4mm pitch in advanced logic segments.
REACH Annex XVII restrictions on nickel release and EU RoHS recast directives are forcing palladium-silver plating substitution for conventional tin-lead surface finishes. European automotive Tier-1 suppliers are demanding full material disclosure documentation extending to smelter-level provenance. Medical device packaging for EU MDR Class III implantables is most affected, with German and Swiss contract manufacturers accelerating XRF verification protocols.
Consolidated procurement through captive packaging operations is displacing merchant lead frame spot purchasing across memory and logic device manufacturers. Samsung's in-house AT facilities and Intel's packaging expansion are internalizing specification control and compressing third-party supplier negotiation leverage. This concentration is most visible in South Korea's Pyeongtaek and China's Suzhou manufacturing corridors where integrated device manufacturers dominate volume allocation.
Global Semiconductor Lead Frame Market Segmentation
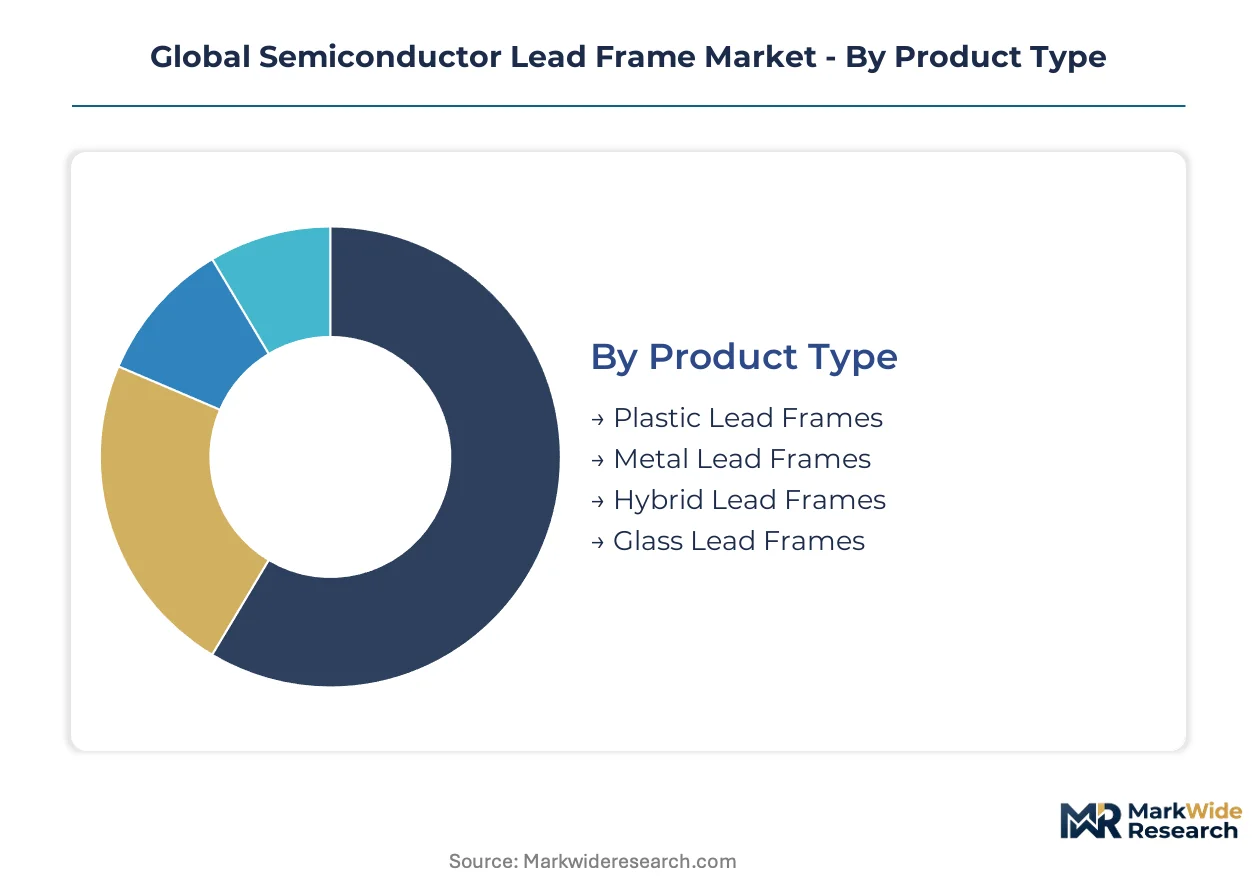
Lead frame segmentation reveals divergent investment cycles across material systems and interconnect technologies. Cycle time variations between consumer-grade plastic formats and automotive-qualified metal variants dictate working capital intensity and supplier margin structures.
Product Type:
Plastic lead frames turn inventory fastest at 4-6 weeks, while glass variants for hermetic packaging stretch to 20-week cycles due to ceramic sealing processes.
- Plastic Lead Frames:Copper alloy substrates with epoxy molding compound encapsulation dominate high-volume consumer IC packaging. Demand concentrates in China's Pearl River Delta smartphone assembly corridors where Dongguan-based packaging houses optimize for cost-per-pin metrics in TWS earbud and wearable controllers.
- Metal Lead Frames:Iron-nickel alloy construction with gold or palladium-silver plating serves automotive underhood applications requiring -40°C to 150°C thermal cycling resilience. German automotive Tier-1 suppliers in Baden-Württemberg specify these for powertrain control modules under ECHA REACH nickel release restrictions.
- Hybrid Lead Frames:Composite copper-iron-nickel structures balance thermal expansion matching with stamping cost efficiency for mid-tier industrial sensors.
- Glass Lead Frames:Ceramic-sealed hermetic formats for aerospace and implantable medical devices requiring moisture ingress protection below 5,000 ppm.
Plastic lead frames anchor the volume base while hybrid formats gain share at the steepest rate from automotive sensor packaging substitution.
Application:
Margin tiering separates automotive qualification premiums from consumer electronics spot pricing volatility.
- Consumer Electronics:Smartphones, tablets, and wearables drive QFN and QFP demand in 0.4mm-0.65mm pitch ranges. South Korea's Gyeonggi-do packaging cluster serves Samsung Electronics captive requirements for Exynos mobile processors.
- Automotive Electronics:Battery management systems and inverter power modules require high-pin-count formats with AEC-Q100 reliability certification. Japanese suppliers in Aichi Prefecture dominate motor control IC lead frame supply to Toyota and Honda Tier-1 networks.
- Telecommunications:Base station power amplifiers and optical transceivers specify low-thermal-resistance copper alloys for 5G infrastructure deployment.
- Industrial Equipment:Factory automation controllers and motor drives prioritize long-term supply continuity over cost optimization in PLC and servo driver packaging.
Consumer electronics generates the highest unit volumes while automotive electronics commands the steepest pricing premiums per lead frame.
Technology:
Process maturity gradients separate legacy wire-bonding installed base from flip-chip displacement in advanced nodes.
- Wire-Bonding Technology:Gold or copper wire interconnects from die pads to lead frame fingers remain dominant in mature node analog and power ICs. Taiwan's Tainan packaging corridor maintains the largest installed wire-bonding capacity for legacy microcontroller formats.
- Flip-Chip Technology:Solder bump direct die attachment to organic substrates or lead frame-based laminate packages serves high-I/O processors and networking silicon. TSMC's CoWoS packaging expansion in Taichung is displacing conventional lead frames in AI accelerator applications above 500W thermal design power.
- Die-Bonding Technology:Epoxy adhesive die attach for low-pin-count discrete devices and simple analog ICs in cost-constrained consumer applications.
- Hybrid Technology:Combined wire-bond and flip-chip in multi-chip modules for heterogeneous integration in automotive radar and lidar sensor fusion processors.
Wire-bonding technology anchors installed capacity while flip-chip formats expand most quickly in high-performance computing segments.
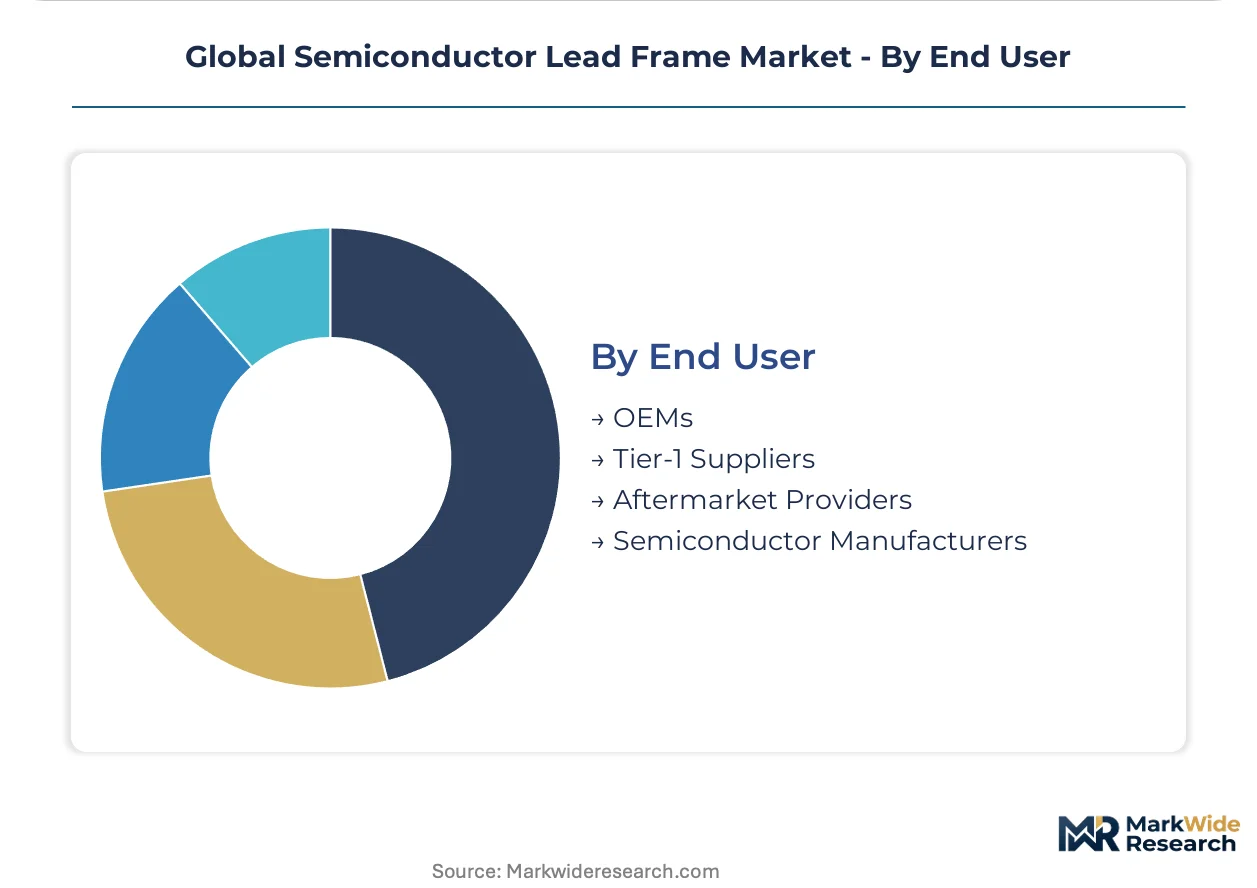
End User:
Customer concentration patterns range from captive IDM integration to fragmented merchant procurement.
- Semiconductor Manufacturers:Integrated device manufacturers with in-house packaging operations specify proprietary lead frame geometries. Intel's Arizona and Oregon packaging facilities internalize high-volume CPU substrate requirements, compressing third-party supplier access.
- Tier-1 Suppliers:Automotive electronics module assemblers in Germany, Japan, and South Korea procure qualified lead frames under long-term agreements with audit rights extending to smelter provenance.
- OEMs:Original equipment manufacturers in industrial automation and medical devices with limited packaging capabilities rely on contract manufacturer specification compliance.
- Aftermarket Providers:Replacement component distributors serving legacy automotive and industrial equipment with extended lifecycle support requirements.
Semiconductor manufacturers concentrate procurement volume while Tier-1 suppliers impose the most stringent qualification protocols on supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated device manufacturers in South Korea, China, and Japan concentrate procurement leverage, while automotive Tier-1 suppliers in Germany and the United States impose qualification barriers that fragment supplier access by geography.
China
Electric vehicle battery management IC demand and smartphone assembly expansion drive lead frame consumption in the Pearl River Delta. MEE enforcement of GB standards restricts hazardous substances in electronic components, forcing alloy composition changes for packaging materials. Dongguan-based packaging houses optimize cost-per-pin metrics for TWS earbud and wearable controllers.
South Korea
Memory and logic device captive packaging operations anchor lead frame specification control through Samsung Electronics in-house AT facilities. MFDS alignment with ISO 10993 extends regulatory scope into biocompatible device packaging for emerging healthcare IC applications. Gyeonggi-do packaging clusters serve Exynos mobile processor requirements with concentrated volume allocation.
Japan
Motor control IC demand from Toyota and Honda Tier-1 networks sustains high-reliability alloy consumption in Aichi Prefecture. METI coordinates JIS standards with PMDA quality frameworks, creating certification barriers for non-compliant suppliers. Nagoya chemical process engineering expertise concentrates sub-15-micron tolerance etching capability.
Germany
Automotive powertrain control module demand from Baden-Württemberg Tier-1 suppliers drives iron-nickel alloy lead frame specifications. ECHA REACH nickel release restrictions mandate palladium-silver plating substitution for conventional surface finishes. Stuttgart-area contract manufacturers accelerate XRF verification protocols for full material disclosure documentation.
United States
AI accelerator and high-performance computing packaging expansion at Intel Arizona and Oregon facilities internalizes substrate requirements, compressing third-party supplier access. NHTSA automotive electronics reliability mandates filter through domestic Tier-1 procurement specifications. Greater Phoenix semiconductor manufacturing corridors concentrate advanced packaging infrastructure investment.
Global Semiconductor Lead Frame Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. Integrated device manufacturers with captive packaging operations concentrate volume leverage, while merchant suppliers fragment across stamping and etching process capabilities. Three archetypes dominate: precision-etching specialists serving high-density QFN formats, cost-optimized stamping houses for consumer ICs, and automotive-qualified alloy processors. Competitive moves center on backward integration into alloy smelting and multi-jurisdiction certification pre-positioning.
Among East Asian fabricators, Mitsui High-tec, Chang Wah Technology, and Shinko Electric Industries occupy distinct tier positions. Mitsui High-tec exemplifies the precision-etching archetype with ultra-precision tolerance capabilities. Chang Wah Technology represents cost-optimized stamping specialization for mid-tier consumer applications. Shinko Electric Industries anchors automotive-grade reliability positioning through iron-nickel alloy expertise. Samsung Electronics and Infineon Technologies function as channel-controlling buyers rather than merchant market participants.
| Leading Market Players |
|---|
| Infineon Technologies |
| ASM Pacific Technology |
| Samsung Electronics |
| Shinko Electric Industries |
| Amkor Technology |
| Texas Instruments |
| Mitsui High-tec |
| Chang Wah Technology |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Pearl River Delta stamping corridors is compressing spot pricing for mid-tier consumer IC lead frames while simultaneously forcing precision-etching specialists in Japan's Nagoya cluster to maintain premium positioning through automotive qualification barriers. This utilization divergence creates a bifurcated supplier landscape where cost-optimized and reliability-certified tiers operate with minimal price overlap.
Pricing Analysis
Cost-plus contracts indexed to LME copper price movements dominate procurement agreements for high-volume stamped lead frames serving Dongguan-based packaging houses. Price differentiation separates AEC-Q100 automotive-certified iron-nickel alloys from consumer-grade copper formats, with certification tier and volume scale as primary drivers. Pricing pressure stems from copper alloy cost volatility exceeding annual swings of 30%, eroding margins for stamping-process suppliers. Consumer electronics module assemblers exhibit highest price sensitivity, while German automotive Tier-1 suppliers under ECHA REACH mandates demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for lead frame distributors serving North American automotive module assemblers. Manufacturing concentrates in China, Japan, and South Korea, with raw material dependencies on Chilean copper cathode and Indonesian nickel feedstock. Single-source vulnerability concentrates in sub-15-micron chemical etching capability tethered to Japan's Nagoya and South Korea's Gyeonggi-do engineering clusters. Distribution runs through captive packaging operations at Samsung Electronics and Intel facilities, compressing third-party merchant supplier access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as automotive electrification penetration accelerates demand for high-reliability lead frame formats previously reserved for premium industrial applications.
For Market Incumbents: Insulate automotive qualification premiums by accelerating backward integration into copper-iron-nickel alloy smelting, reducing exposure to LME price volatility. Secure multi-jurisdiction certification pre-positioning across China's GB standards, Japan's JIS frameworks, and EU REACH registration before flip-chip substitution captures additional advanced node packaging share.
For New Entrants and Emerging Players: India's packaging infrastructure under PLI scheme incentives offers the most penetrable geographic entry point for cost-optimized stamped lead frames serving emerging semiconductor assembly and test facilities. Target biocompatible device packaging specifications aligned with Korea's MFDS and ISO 10993 frameworks, where premium surface plating requirements sustain higher margin pools than commoditized consumer formats.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-etching specialists serving automotive-qualified QFN applications with multi-year supply agreements. Long-term viability favors acquisition targets with demonstrated sub-20-micron tolerance capability and established smelter-level provenance documentation. Monitor copper price stabilization as the primary inflection signal for margin recovery in stamping-process supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Smelting | Mitsui High-tec and Shinko Electric Industries reduce raw material cost volatility exposure through captive copper-iron-nickel production. |
| Multi-Jurisdiction Certification Pre-Positioning | Suppliers accessing Chinese MEE GB standards, Japanese METI JIS frameworks, and EU ECHA REACH registration compress new product qualification cycles. |
| Sub-15-Micron Etching Capability Expansion | Chemical process engineering talent concentration in Nagoya and Gyeonggi-do clusters limits replication by emerging competitors. |
| Biocompatible Surface Plating Investment | Korea's MFDS alignment with ISO 10993 extends lead frame specifications into implantable medical IC applications with premium pricing. |
| India Packaging Corridor Partnership | PLI scheme incentives for semiconductor assembly and test facilities create captive demand for cost-optimized stamped lead frames. |
Study Parameters
Operator-level perspectives from packaging procurement managers, chemical process engineers, automotive Tier-1 supplier quality directors, and semiconductor device packaging architects anchored the qualitative base. Primary interview insights combined with secondary validation from SEC 10-K filings, Japan METI industrial statistics, China customs trade data, and EU ECHA substance registration databases. Bottom-up unit demand modeling across stamping and etching process tiers triangulated against top-down semiconductor packaging equipment capex disclosures.
Scenario-bracketing framed optimistic and conservative demand trajectories across the projection horizon, with segmentation dimensions spanning material system, interconnect technology, end-use application, and regional manufacturing cluster. CAGRs derived from regression analysis of historical packaging substrate demand against semiconductor unit shipment trends, incorporating automotive electrification penetration curves and advanced packaging migration rates as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported fabricators or accelerated flip-chip adoption by TSMC and Samsung Electronics packaging subsidiaries would shift outcomes. Macroeconomic copper price collapse, regulatory relaxation of China's dual carbon enforcement, or breakthrough substrate-based interconnect technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Precision Link Carrier Market