
 Power Line Communication (PLC) Market | 2026-2036
Power Line Communication (PLC) Market Size, Share, and Industry Trends Forecast 2026-2036
Power Line Communication (PLC) Market Analysis
Broadband-grade chip certification is reorganizing competitive tiers in PLC hardware. STMicroelectronics N.V. leverages its foundry partnerships to secure cost positions in G3-PLC silicon. Siemens AG anchors European utility contracts through its integrated substation-to-meter portfolio. Broadcom Inc. specializes in HomePlug AV derivatives for residential networking, competing against utility-focused architectures.
Power Line Communication transmits data over existing electrical wiring using carrier frequencies between 3 kHz and 500 MHz, modulating analog signals onto power conductors to avoid dedicated data cabling. The technology serves industrial automation, grid telemetry, and in-home device networking where running fiber or Ethernet proves impractical. Chipset segments command the deepest margin pools as OEMs seek single-source modem-plus-PHY solutions. Smart grid applications lead volume uptake, while EV charging infrastructure represents the fastest-expanding addressable demand. G3-PLC dominates utility deployments for its robustness across low-voltage transformers, whereas HomePlug AV retains consumer electronics traction.
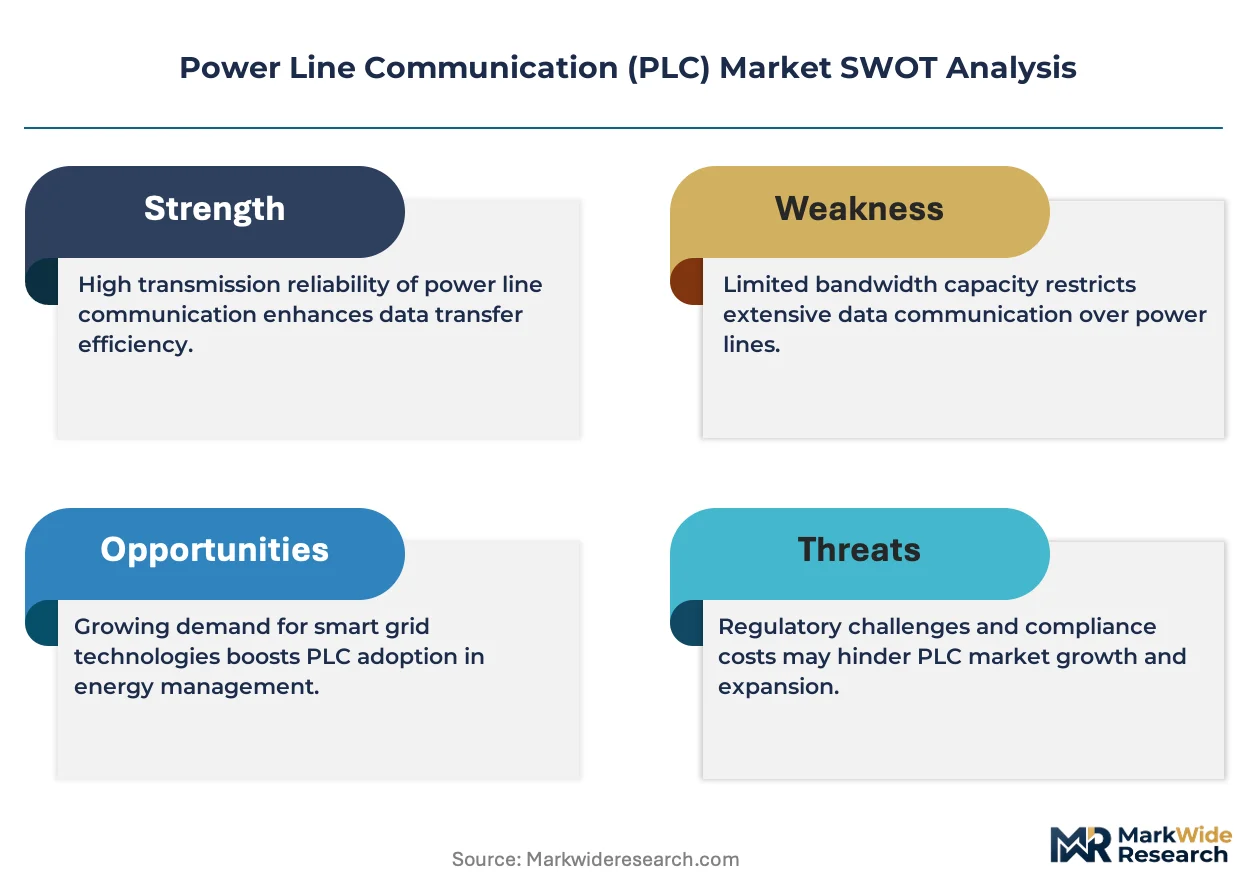
FCC Part 15 rules govern unlicensed PLC emissions in the United States, forcing chipset designers to limit spectral power density and adopt notching for amateur radio bands. Europe's CENELEC EN 50065 standard allocates dedicated frequency bands for narrowband PLC, creating a regulated channel structure that favors standardized protocols over proprietary schemes. IEEE 1901 compliance is becoming a de facto market access requirement for broadband PLC equipment sold across multiple jurisdictions. Stakeholders must monitor how national cybersecurity mandates for critical infrastructure reshape authentication and encryption requirements in next-generation PLC stacks.
Market Dynamics
Utility mandates for smart meter interoperability are compressing proprietary PLC protocols into standardized IEEE 1901 and G3-PLC stacks, forcing chipset vendors to recertify silicon across multiple regulatory domains simultaneously.
Growth Catalysts
- FCC Part 15 Emission Rules:Unlicensed spectrum access in the United States lowers deployment barriers for residential broadband PLC networks. Equipment makers bypass spectrum auction costs.
- EV Charging Telemetry:Electric vehicle infrastructure operators embed PLC modems for real-time load balancing and payment authentication. This application segment expands faster than traditional grid metering.
- Germany's Broadband PLC Mandate:Grid operators require certified chipsets for advanced metering infrastructure rollouts. This regulatory pressure concentrates procurement volume among qualified vendors.
Market Restraints
- Copper and Silicon Input Volatility:Foundry capacity constraints for mixed-signal PLC PHY chips create order backlog cycles. Wafer pricing fluctuations compress hardware margins unpredictably.
- Amateur Radio Band Notching:FCC and CEPT regulations force spectral power density reductions in 3-30 MHz ranges. Chipset designers sacrifice throughput to meet electromagnetic compatibility limits.
- Wireless Mesh Substitution:LoRaWAN and Wi-SUN networks compete for last-mile smart grid connectivity. Utilities in rural topographies favor radio links where power line noise degrades signal integrity.
Strategic Opportunities
- India's Smart Meter National Program:State electricity boards tender millions of PLC-enabled meters under standardization directives. Vendors with localized certification laboratories capture early procurement cycles.
- IEC 61334 Convergence with Wireless:Hybrid PLC-RF chipsets integrate narrowband power line with sub-GHz radio fallback. This dual-phy architecture penetrates noisy transformer environments.
- Direct Utility Channel Bypass:PLC module makers sell through meter OEMs rather than system integrators. Shorter sales cycles accelerate design-win velocity for certified silicon.
Industry Challenges
- G3-PLC Certification Timelines:Utility-grade interoperability testing spans 12-18 months per silicon revision. Delayed certification windows miss annual procurement tenders.
- Legacy SCADA Integration Friction:Decades-old substation automation protocols require protocol translation gateways. Engineering teams face commissioning complexity at brownfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Line Communication (PLC) Market |
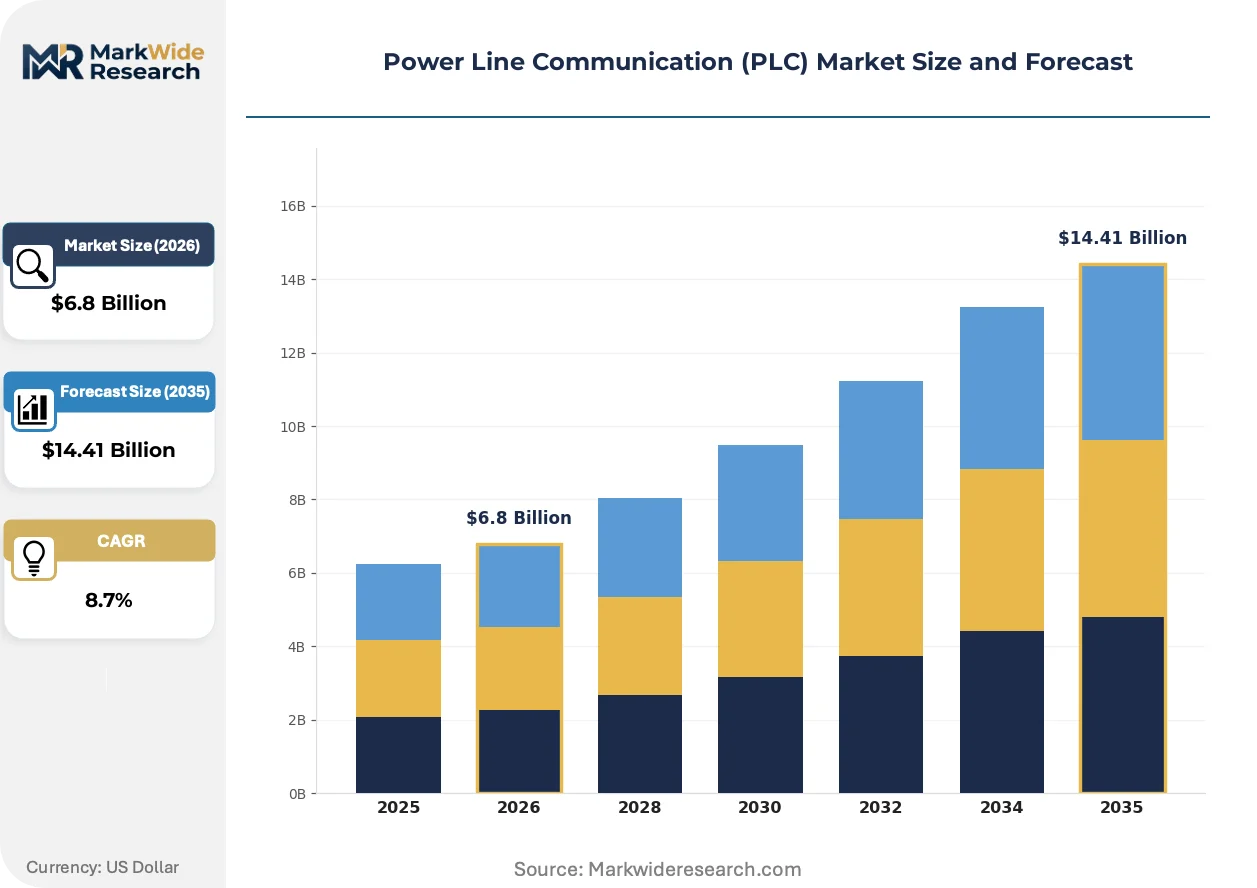
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adapters, Modems, Chipsets, Repeaters Application: Smart Grid, Home Automation, Industrial Controls, EV Charging Technology: G3-PLC, PRIME, HomePlug AV, IEEE 1901 End User: Residential, Commercial, Industrial, Utilities |
| Companies Covered | ABB Ltd., STMicroelectronics N.V., Siemens AG, NXP Semiconductors, Broadcom Inc., General Electric Company, Hitachi Energy Ltd., Landis+Gyr AG, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Line Communication (PLC) Market Emerging Trajectories
Silicon integration and regulatory harmonization are compressing PLC hardware into single-chip solutions while cybersecurity mandates reshape stack architectures.
Multi-protocol system-on-chip designs now combine G3-PLC, PRIME, and IEEE 1901 modems onto unified die geometries. European meter manufacturers consolidate supplier lists around these flexible platforms. Die shrinks below 40nm nodes are miniaturizing analog front-end components without sacrificing signal-to-noise ratios.
EU Cybersecurity Certification Framework mandates for critical infrastructure are extending authentication requirements to PLC transport layers. Chipset vendors embed hardware security modules alongside PHY circuits. German and French utilities now reject silicon lacking ETSI TS 102 687 compliance.
State-level renewable portfolio standards are accelerating time-of-use metering deployments that depend on PLC backhaul. California and Texas utilities compress meter refresh cycles from fifteen to ten years. Procurement teams prioritize chipsets with firmware-over-the-air capabilities to avoid truck rolls.
Power Line Communication (PLC) Market Segmentation
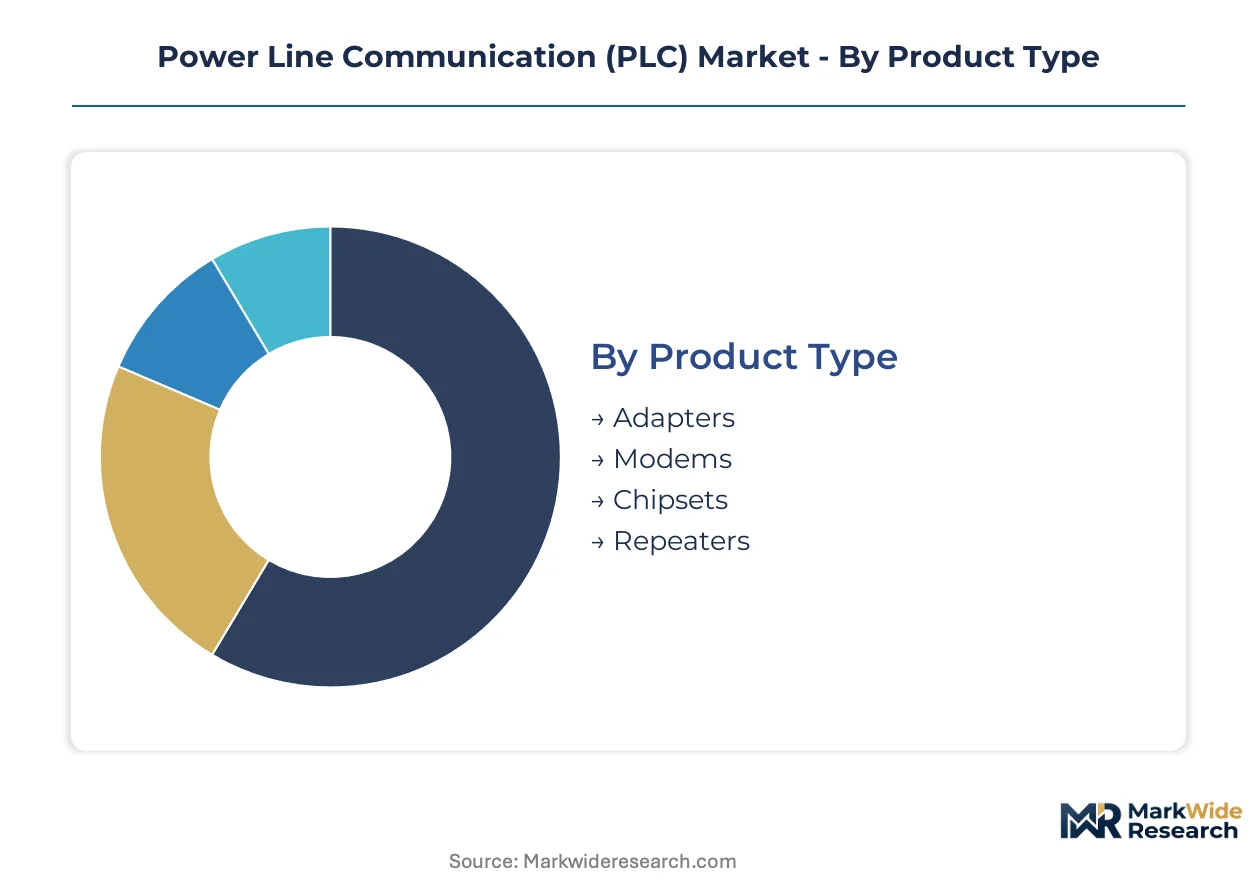
Power Line Communication hardware segments diverge sharply between utility-grade certification requirements and consumer electronics cost targets. Procurement patterns across product types, applications, technologies, and end users reveal distinct margin pools and geographic concentration points that reshape vendor strategies.
Product Type:
Chipsets and modems flow predominantly into export markets bound by IEEE 1901 and G3-PLC certification regimes, while adapters and repeaters serve fragmented domestic retail channels with lower compliance barriers.
- Adapters:Plug-in devices convert existing power outlets into network ports using HomePlug AV or IEEE 1901 PHY layers. Residential networking in Germany and France absorbs volume as consumers bypass Wi-Fi dead zones in older building stock.
- Modems:Standalone transceiver units integrate analog front-end circuits with digital baseband processors for utility AMI backhaul. Grid operators in India and Brazil specify modems with −1 dBm transmit power to penetrate noisy low-voltage transformers.
- Chipsets:Silicon solutions combining MAC, PHY, and power amplifier functions dominate OEM procurement for meter integration. Mixed-signal foundry partnerships in Taiwan and South Korea constrain supply availability during wafer allocation cycles.
- Repeaters:Signal regeneration devices extend PLC range across distribution transformers and long cable runs. Japanese utilities deploy repeaters in mountainous prefectures where subscriber density falls below economic thresholds for fiber overlay.
Chipsets hold the largest share; momentum sits with modems as AMI tender volumes accelerate.
Application:
Cost tier stratification separates capital-intensive smart grid deployments from price-sensitive home automation rollouts, with industrial controls commanding premium pricing for deterministic latency specifications.
- Smart Grid:Advanced metering infrastructure and distribution automation systems constitute the dominant revenue pool. State electricity boards in India and regional utilities in Spain mandate G3-PLC for standardized interoperability across multi-vendor environments.
- Home Automation:Lighting control, security systems, and HVAC integration leverage existing residential wiring. Italian and French consumers drive adoption through energy management mandates tied to building efficiency certificates.
- Industrial Controls:Factory automation networks prioritize real-time determinism over raw throughput. German automotive manufacturers specify PROFINET-over-Powerline hybrids for welding robot cell communication.
- EV Charging:Charging station operators embed PLC for authentication and load management protocols. California and Texas utilities expand fastest here as renewable portfolio standards compress time-of-use metering deployment timelines.
Smart Grid commands the deepest revenue base; EV Charging climbs the fastest as infrastructure buildouts multiply connection points.
Technology:
Volume concentration favors standardized protocols over proprietary schemes as regulatory harmonization eliminates single-vendor lock-in risks across procurement jurisdictions.
- G3-PLC:OFDM-based narrowband standard optimized for noisy power line channels across low-voltage transformers. European CENELEC EN 50065 compliance and FCC Part 15 certification enable sales into Germany, France, and the United States.
- PRIME:Spanish-originated PHY/MAC specification with strong Iberian utility adoption. Iberdrola and Endesa deployment volumes sustain dedicated silicon production lines at European semiconductor foundries.
- HomePlug AV:Broadband consumer networking standard operating in 2-30 MHz spectrum. Retail channel presence in Japan and South Korea persists despite IEEE 1901 convergence pressure.
- IEEE 1901:Unified broadband PLC standard subsuming HomePlug AV and HD-PLC variants. Multi-protocol certification requirements in Italy and the United Kingdom force chipset vendors to support concurrent G3-PLC and IEEE 1901 operation.
G3-PLC retains dominant deployment volume; IEEE 1901 gains share fastest through regulatory convergence mandates.
End User:
Customer maturity separates utilities with 15-year amortization horizons from industrial buyers demanding 5-year technology refresh cycles and residential price elasticity.
- Residential:Individual consumers purchase adapters and integrated home networking equipment. French and Italian retail channels show highest penetration where energy tariffs incentivize consumption visibility.
- Commercial:Office buildings and retail spaces deploy PLC for lighting and climate control retrofits. German commercial property managers favor wired solutions over wireless where electromagnetic interference from medical equipment disrupts radio links.
- Industrial:Manufacturing facilities require hardened equipment with extended temperature ranges and galvanic isolation. Japanese automotive and electronics factories specify JIS-compliant industrial-grade modems for production line reliability.
- Utilities:Grid operators represent the most concentrated procurement authority with standardized tender processes. State-level mandates in India and national programs in Spain concentrate annual volume into qualified vendor pools.
Utilities hold the largest share; commercial adoption expands most quickly through building efficiency regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry partnerships in Taiwan and South Korea constrain PLC chipset availability, while utility procurement concentrates in jurisdictions with standardized certification regimes. Germany's broadband PLC mandate and India's national smart meter program anchor volume demand. Regulatory fragmentation across CENELEC EN 50065, FCC Part 15, and IEEE 1901 compliance creates multi-domain recertification burdens for silicon vendors.
Germany
Grid operators mandate certified G3-PLC chipsets for advanced metering infrastructure under federal standardization directives. The country's national regulator enforces CENELEC EN 50065 frequency allocations for narrowband deployments. Industrial clusters in Bavaria and North Rhine-Westphalia host substation automation integrators specifying Siemens and ABB equipment for distribution network modernization.
United States
California and Texas utilities compress meter refresh cycles to ten years under state renewable portfolio standards. FCC Part 15 emission rules govern unlicensed PLC spectrum access, forcing amateur radio band notching in 3-30 MHz ranges. Silicon Valley fabless designers collaborate with Broadcom on HomePlug AV derivatives for residential broadband channels.
India
State electricity boards tender millions of PLC-enabled meters under the national smart meter program standardization framework. The Central Electricity Authority mandates interoperability testing for multi-vendor AMI environments. Manufacturing corridors in Gujarat and Maharashtra concentrate meter OEM assembly operations serving utilities in Maharashtra, Karnataka, and Tamil Nadu.
Japan
Electric power companies deploy repeaters in mountainous prefectures where subscriber density falls below fiber overlay thresholds. METI industrial standards guide PLC equipment procurement for building energy management systems. Automotive and electronics factories in Aichi and Kanagawa specify JIS-compliant industrial-grade modems for production line reliability.
Spain
Iberdrola and Endesa sustain dedicated PRIME protocol silicon production through European foundry partnerships. The national grid code requires PLC backhaul for distribution automation in rural Castilla y León and Aragón provinces. Madrid-based system integrators bridge legacy SCADA protocols with next-generation G3-PLC stacks at brownfield substation sites.
Power Line Communication (PLC) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the PLC value chain. The market structures around three tiers: integrated European industrial conglomerates with utility channel depth, Asian mixed-signal foundry partners securing PHY silicon supply, and North American semiconductor specialists targeting consumer broadband segments. Strategic moves concentrate on multi-protocol certification alignment and direct utility channel bypass through meter OEM partnerships.
Within the integrated industrial tier, Siemens AG and ABB Ltd. exemplify European conglomerates anchoring substation-to-meter portfolios through long-cycle utility relationships. STMicroelectronics N.V. occupies a position bridging foundry-scale silicon supply with G3-PLC certification expertise. Broadcom Inc. sits within the consumer-facing archetype, representing North American specialization in residential broadband PHY layers despite IEEE 1901 convergence pressure.
| Leading Market Players |
|---|
| ABB Ltd. |
| STMicroelectronics N.V. |
| Siemens AG |
| NXP Semiconductors |
| Broadcom Inc. |
| General Electric Company |
| Hitachi Energy Ltd. |
| Landis+Gyr AG |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Taiwanese foundries and European chipset vendors lock in wafer allocation for G3-PLC silicon while capping unit cost exposure across multi-year utility tender cycles. These arrangements bind procurement volume to certification timelines, creating price visibility for grid operators in Germany and India who amortize meter deployments over decade-long refresh horizons.
Pricing Analysis
CENELEC EN 50065 dictates the pricing tier structure for narrowband PLC equipment in European markets, separating certified G3-PLC silicon from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects IEEE 1901 compliance grade, foundry partnership depth, and firmware-over-the-air capability bundling. Cost compression in economy-tier residential adapters is intensifying because HomePlug AV derivatives face IEEE 1901 convergence pressure. Commercial building automation buyers exhibit highest price sensitivity, while German utilities with federal mandate backing accept premium positioning for transformer-robust chipsets.
Supply Chain Analysis
Inventory buffers for mixed-signal PHY wafers stretch 16-20 weeks as Taiwanese and South Korean foundries allocate capacity toward automotive and consumer electronics. Raw material dependencies center on 300mm silicon wafers, copper leadframes for power amplifier packaging, and ceramic substrate materials for high-temperature industrial modems. Single-source vulnerability concentrates in G3-PLC certification laboratory access, where only three facilities worldwide conduct utility-grade interoperability testing. Distribution runs through meter OEM direct channels rather than system integrator networks, shortening design-win cycles for qualified silicon vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around IEEE 1901 and G3-PLC certification creates defensive moats for incumbent chipset vendors, as utility procurement mandates lock out unqualified competitors for 12-18 month recertification windows.
For Market Incumbents: Shield certified silicon positions by deepening foundry partnerships in Taiwan to secure wafer allocation during capacity crunches. Prioritize firmware-over-the-air capability development to defend against wireless mesh substitution threats from LoRaWAN and Wi-SUN vendors targeting rural grid topographies. Channel control through direct meter OEM relationships accelerates design-win velocity versus system integrator-dependent rivals. For New Entrants and Emerging Players: Hybrid PLC-RF chipset integration represents the most penetrable white-space where incumbents under-serve noisy transformer environments in India's national smart meter program. Target state electricity boards in Maharashtra and Karnataka with localized certification support bundled into silicon supply agreements. Go-to-market leverage rests on IEC 61334 convergence expertise rather than single-PHY replication. For Investors and Strategic Acquirers: G3-PLC certification-capable fabless designers with existing utility design wins present the most defensible acquisition archetype for medium-term infrastructure exposure. Long-term viability hinges on cybersecurity mandate compliance extending ETSI TS 102 687 authentication requirements into transport layer silicon. Watch for German and French utility tender rejections of non-compliant silicon as the inflection signal for stack architecture consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Integration | Combines G3-PLC, PRIME, and IEEE 1901 modems onto unified die geometries for European meter OEM consolidation. |
| Hybrid PLC-RF Chipset Development | Integrates narrowband power line with sub-GHz radio fallback to penetrate noisy transformer environments in India. |
| Direct Utility Channel Bypass | Sells PLC modules through meter OEMs rather than system integrators to accelerate design-win velocity. |
| Hardware Security Module Embedding | Meets EU Cybersecurity Certification Framework mandates for critical infrastructure authentication requirements. |
| Firmware-Over-the-Air Capability Investment | Enables remote updates for California and Texas utilities compressing meter refresh cycles to ten years. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility procurement officers, meter OEM engineering directors, semiconductor foundry account managers, and certification laboratory technical leads; alongside secondary validation through IEEE standards documentation, CENELEC EN 50065 regulatory filings, SEC 10-K disclosures from listed chipset vendors, and Central Electricity Authority tender records from India. Bottom-up unit economics for G3-PLC silicon and top-down utility capex trajectories were triangulated against foundry wafer allocation data.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, application, technology protocol, and end-user archetype, with additional dimensioning by certification jurisdiction cluster. CAGRs were derived from utility tender pipeline analysis and state-level smart meter mandate progression. Key forecast inputs included transformer penetration rates for narrowband PLC and EV charging infrastructure connection point multiplication.
Forecasts assume regulatory continuity in FCC Part 15, CENELEC EN 50065, and IEEE 1901 regimes; material policy shifts around cybersecurity mandates or spectrum allocation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Satellite Communication Components Market