
 Neurometabolic Disorder Market | 2026-2036
Neurometabolic Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Neurometabolic Disorder Market Foresight
Orphan drug designation status is bifurcating competitive access to neurometabolic indications. Novartis leverages its gene therapy infrastructure to sustain leadership in rare disease portfolios. Amicus Therapeutics specializes in small-molecule chaperone therapies, occupying a differentiated position within enzyme deficiency markets.
Neurometabolic disorders encompass inherited conditions disrupting biochemical pathways in neural tissue, including lysosomal storage diseases, mitochondrial disorders, and peroxisomal biogenesis defects characterized by substrate accumulation, energy failure, or toxic metabolite buildup. These conditions demand precise enzymatic assay panels and metabolic biomarker quantification for definitive diagnosis and longitudinal management. Enzyme replacement therapies command premium positioning due to manufacturing complexity and limited supplier bases, while diagnostic kits expand through decentralized laboratory networks. Specialty clinics anchor the highest-margin application segment, whereas home care settings represent the fastest-growing delivery channel for chronic maintenance regimens.
FDA orphan drug incentives and EMA's priority medicines scheme shape clinical trial investment and accelerated approval pathways for neurometabolic therapies. The EU AI Act and GDPR impose algorithmic transparency requirements on AI-assisted diagnostic platforms processing patient metabolic profiles. Stakeholders must monitor evolving reimbursement frameworks for one-time gene therapies versus chronic enzyme replacement to align portfolio development with payer value thresholds.
Market Dynamics
FDA orphan drug incentives and EMA priority medicines schemes are concentrating clinical trial investment around lysosomal storage diseases, while gene therapy manufacturing bottlenecks create supply-side scarcity that shapes competitive positioning.
Growth Catalysts
- Orphan drug designation pathways:FDA and EMA accelerated approval frameworks reduce time-to-market for enzyme replacement therapies targeting Gaucher disease and Fabry disease.
- Specialty clinic expansion:Academic medical centers in Boston, San Diego, and London are anchoring neurometabolic testing networks that drive diagnostic volume.
- AI-assisted metabolic profiling:Machine learning platforms processing enzymatic assay data are compressing diagnostic timelines from months to weeks.
Market Restraints
- Viral vector manufacturing concentration:AAV production capacity concentrates among three contract manufacturers, creating supply bottlenecks for gene therapy candidates.
- Reimbursement uncertainty for one-time therapies:CMS and NICE value assessment frameworks struggle to price curative interventions against chronic enzyme replacement.
- Biomarker validation gaps:Heterogeneous disease progression in mitochondrial disorders limits surrogate endpoint acceptance by regulators.
Strategic Opportunities
- Home infusion channel development:Subcutaneous enzyme formulations enable nursing-supported administration outside hospital settings.
- EU AI Act compliance services:Algorithmic transparency requirements for diagnostic platforms create advisory revenue streams.
- Peroxisomal disorder expansion:X-linked adrenoleukodystrophy represents an underpenetrated indication with no approved disease-modifying therapy.
Industry Challenges
- Gene therapy talent scarcity:Viral vector process development and analytical characterization expertise concentrates at a handful of biotech clusters.
- Multi-year certification timelines:EMA's ATMP classification and GMP manufacturing inspections delay commercial readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurometabolic Disorder Market |
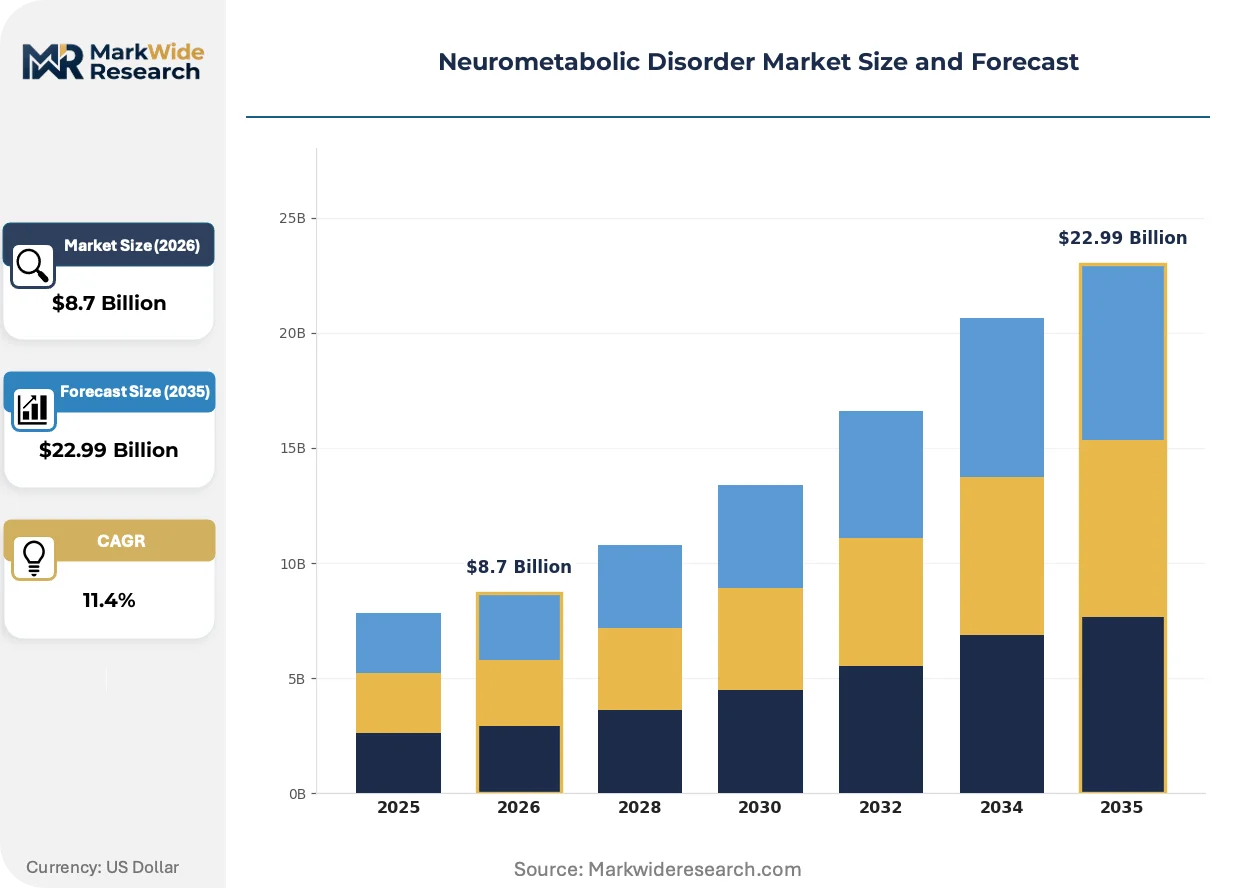
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Metabolic Pathway Modulators, Enzyme Replacement Therapies, Nutritional Supplements Application: Diagnostic Laboratories, Specialty Clinics, Research Institutions, Home Care Settings Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal End User: Healthcare Providers, Patients, Caregivers, Research Scientists |
| Companies Covered | Novartis, Roche, Sanofi, Bristol-Myers Squibb, AbbVie, Merck & Co., Johnson & Johnson, Amicus Therapeutics, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurometabolic Disorder Market Shifts & Advancements
Gene therapy modalities are displacing chronic infusion regimens across neurometabolic indications, while regulatory frameworks adapt to single-administration pricing models and decentralized diagnostic networks expand patient identification.
Base editing platforms are displacing conventional AAV gene addition approaches in preclinical programs targeting methylmalonic acidemia and propionic acidemia. Biotech sponsors in Cambridge and Basel are prioritizing these modalities for liver-directed metabolic correction. The technology is displacing investor capital from incremental enzyme engineering toward permanent genomic repair strategies.
EMA's priority medicines scheme and FDA's rare disease endpoint advancement pilot are compressing clinical development timelines for neurometabolic therapies. These frameworks enable adaptive trial designs that reduce placebo-controlled exposure in pediatric populations. Sponsors targeting neuronopathic Gaucher disease are leveraging these pathways to accelerate biomarker qualification.
Patient advocacy organizations are consolidating procurement influence through managed access programs and expanded access protocols. These groups negotiate pre-approval supply agreements directly with manufacturers, bypassing traditional hospital pharmacy committees. The shift concentrates demand leverage in the United States and Germany where foundation networks maintain regulatory affairs capabilities.
Neurometabolic Disorder Market Segmentation
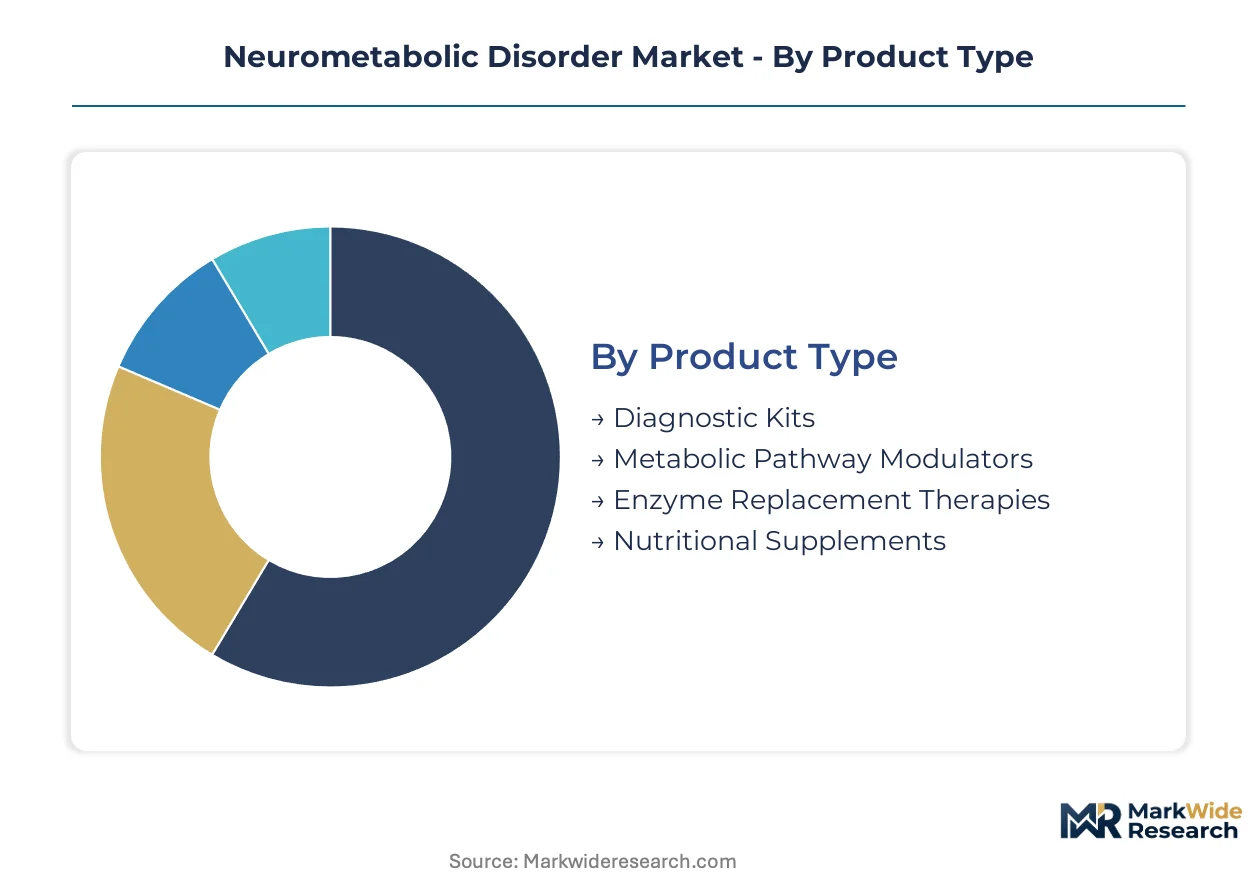
Neurometabolic disorder segmentation reflects divergent commercial models across acute intervention versus chronic maintenance. Channel economics vary sharply between institutional procurement of high-complexity diagnostics and direct-to-patient delivery for metabolic supplements.
Product Type:
Diagnostic kits and enzyme replacement therapies anchor hospital pharmacy budgets, while metabolic modulators and nutritional supplements flow through retail and mail-order channels.
- Enzyme Replacement Therapies:Biologic infusions requiring cold-chain distribution and specialized compounding facilities. Demand concentrates in academic medical centers managing Gaucher and Fabry disease patient cohorts, where FDA orphan drug exclusivity sustains premium positioning.
- Diagnostic Kits:Enzymatic assay panels and metabolic biomarker quantification systems for newborn screening and confirmatory testing. Specialty clinics in Boston and San Diego drive volume for lysosomal storage disease identification, compressing diagnostic timelines through AI-assisted metabolic profiling.
- Metabolic Pathway Modulators:Small-molecule chaperones and substrate reduction compounds. Amicus Therapeutics and comparable developers target mitochondrial disorder subsets through specialty pharmacy networks.
- Nutritional Supplements:Medical foods and cofactor formulations for metabolic maintenance. Home care settings and direct-to-consumer platforms represent the primary volume channel for chronic regimen adherence.
Enzyme replacement therapies dominate installed base. Diagnostic kits are where expansion concentrates.
Application:
Margin structures diverge between high-throughput laboratory networks and decentralized home administration, with reimbursement complexity scaling inversely to site-of-care acuity.
- Specialty Clinics:Dedicated neurometabolic centers at Massachusetts General Hospital, University College London, and University of California San Diego anchor clinical trial recruitment and longitudinal patient management. These sites command premium pricing for complex case coordination.
- Home Care Settings:Nursing-supported subcutaneous enzyme administration and metabolic monitoring outside hospital infrastructure. Subcutaneous formulation development by Novartis and comparable sponsors enables this channel shift.
- Diagnostic Laboratories:Centralized newborn screening and confirmatory testing through state public health laboratories and commercial reference labs. EU AI Act compliance requirements are reshaping algorithmic diagnostic platform procurement.
- Research Institutions:Preclinical and clinical investigation sites for gene therapy and base editing programs. Cambridge and Basel biotech clusters concentrate early-phase metabolic correction trials.
Specialty clinics capture the highest per-patient revenue. Home care settings are climbing the fastest.
Delivery Mode:
Route of administration determines manufacturing complexity, cold-chain requirements, and site-of-care economics across the product portfolio.
- Intravenous:Hospital- or infusion-center-based enzyme replacement requiring specialized nursing and adverse event monitoring. Manufacturing concentrates among three contract viral vector producers, creating supply-side scarcity.
- Subcutaneous:Home-administered formulations reducing hospital dependency. Patient advocacy organizations negotiate direct procurement agreements, bypassing traditional pharmacy committees.
- Oral:Small-molecule chaperones and substrate modulators with standard pharmaceutical distribution. Retail pharmacy networks handle fulfillment for chronic maintenance indications.
- Transdermal:Emerging delivery platforms for metabolic cofactors and nutritional supplementation. Limited commercial penetration relative to established routes.
Intravenous delivery dominates biologic revenue. Subcutaneous administration is gaining share fastest.
End User:
Procurement authority fragments across institutional committees, patient foundations, and individual caregivers depending on therapy modality and reimbursement pathway.
- Healthcare Providers:Academic medical centers and specialty clinics controlling enzyme replacement procurement through pharmacy and therapeutics committees. EMA ATMP classification shapes purchasing timelines.
- Patients:Direct beneficiaries of one-time gene therapies and chronic metabolic maintenance. CMS and NICE value assessment frameworks create pricing uncertainty for curative interventions.
- Caregivers:Family members administering nutritional supplements and subcutaneous regimens in home settings. Training and compliance support represent adjacent service revenue.
- Research Scientists:Principal investigators at Cambridge, Basel, and San Diego sites driving biomarker validation and surrogate endpoint development for regulatory submission.
Healthcare providers control institutional procurement. Patients are emerging as direct demand aggregators through foundation networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and gene therapy clusters concentrate demand across five countries where orphan drug pathways and manufacturing infrastructure shape competitive access. Patient foundation networks in these markets negotiate procurement directly with manufacturers.
United States
Massachusetts General Hospital and University of California San Diego anchor clinical trial networks for lysosomal storage diseases. FDA orphan drug incentives and accelerated approval frameworks compress development timelines for enzyme replacement therapies. The Boston-Cambridge biotech cluster concentrates base editing programs targeting methylmalonic acidemia.
Germany
University College London partnerships and Heidelberg University Hospital drive diagnostic volume for neurometabolic testing. EMA's priority medicines scheme and ATMP classification shape purchasing timelines for gene therapy candidates. The Basel-Zurich corridor anchors viral vector manufacturing capacity serving European trials.
United Kingdom
NICE value assessment frameworks create pricing uncertainty for one-time curative interventions against chronic enzyme replacement. NHS England's specialized commissioning for rare diseases concentrates patient access through designated treatment centers. London's Great Ormond Street Hospital anchors pediatric neurometabolic case coordination.
Switzerland
Swissmedic's alignment with EMA procedures enables rapid market authorization for ATMP-classified therapies. Novartis leverages Basel-based gene therapy infrastructure to sustain rare disease portfolio leadership. The country's contract manufacturing ecosystem supplies AAV vectors to European sponsors.
Japan
PMDA's sakigake designation system accelerates review for neurometabolic therapies addressing unmet pediatric needs. Tokyo and Osaka academic medical centers participate in multinational gene therapy trials for neuronopathic Gaucher disease. METI funding supports domestic viral vector production capacity expansion.
Neurometabolic Disorder Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with gene therapy platforms and mid-cap enzyme engineering specialists. Market structure concentrates around three contract viral vector manufacturers creating supply-side scarcity. Strategic archetypes include platform-integrated rare disease developers, small-molecule chaperone specialists, and diagnostic-therapy paired service providers. Competitive moves center on manufacturing capacity reservations and patient foundation direct procurement agreements.
Within the platform-integrated tier, Novartis exemplifies infrastructure-heavy positioning through its Basel-anchored gene therapy manufacturing network. Amicus Therapeutics occupies the small-molecule specialist archetype with chaperone therapy focus. Roche represents the diagnostic-therapy integration model through metabolic biomarker quantification systems paired with therapeutic development pipelines.
| Leading Market Players |
|---|
| Novartis |
| Roche |
| Sanofi |
| Bristol-Myers Squibb |
| AbbVie |
| Merck & Co. |
| Johnson & Johnson |
| Amicus Therapeutics |
| Pfizer |
| Others |
Supply & Pricing Matrix
EMA's ATMP classification gates both manufacturing qualification and reimbursement tiering, creating a dual-filter where only sponsors with GMP-certified viral vector capacity can command premium gene therapy pricing against chronic enzyme replacement benchmarks.
Pricing Analysis
Cost-plus contracts with producer price indexation anchor enzyme replacement procurement between academic medical centers and contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates orphan-designated biologics from biosimilar entrants and nutritional supplements. Cost compression in the metabolic modulator tier is intensifying because small-molecule chaperone competition is expanding. Patient foundations demonstrate lowest price sensitivity for one-time curative interventions, while retail pharmacy channels for oral maintenance regimens face highest substitution pressure.
Supply Chain Analysis
Switzerland, the United States, and Germany anchor viral vector manufacturing and specialized enzyme production for neurometabolic therapies. AAV plasmid banks, bioreactor-grade growth media, and cryopreservation logistics draw from concentrated biotech clusters. Single-source vulnerability runs through the three contract manufacturers controlling GMP AAV capacity. Distribution runs through cold-chain logistics networks serving hospital pharmacy and direct-to-patient home infusion channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platform economics are inflecting toward winner-take-most structures as base editing interoperability with existing AAV delivery infrastructure consolidates developer ecosystems around manufacturing-accessible modalities.
For Market Incumbents: Compound manufacturing capacity reservations at Basel and Cambridge viral vector facilities to preempt competitor access. Secure direct procurement agreements with patient advocacy foundations in the United States and Germany, bypassing traditional hospital pharmacy committees that face CMS and NICE reimbursement uncertainty for one-time curative interventions. For New Entrants and Emerging Players: Differentiate on peroxisomal disorder indications where no approved disease-modifying therapy exists, particularly X-linked adrenoleukodystrophy. Target home care settings with subcutaneous enzyme formulations that reduce hospital dependency. Pursue EU AI Act compliance advisory services as a go-to-market entry point for diagnostic platform developers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy manufacturing as viral vector process development expertise concentrates at a handful of biotech clusters. Five-to-ten year viability favors platform-integrated rare disease developers with captive supply arrangements. Acquisition target archetype: mid-cap enzyme engineering specialists with orphan drug designation pipelines. Signal to watch: EMA ATMP classification timelines compressing toward Swissmedic-aligned authorization speeds.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Capacity Reservation | Preemptive viral vector GMP slotting at Basel contract facilities locks out competitor sponsors. |
| Patient Foundation Direct Procurement | Bypasses hospital pharmacy committees facing CMS reimbursement framework uncertainty for curative therapies. |
| EU AI Act Compliance Certification | Enables algorithmic diagnostic platform sales into GDPR-regulated European laboratory networks. |
| Subcutaneous Formulation Development | Shifts site-of-care economics toward nursing-supported home administration outside hospital infrastructure. |
| Base Editing Platform Investment | Displaces conventional AAV gene addition approaches in preclinical methylmalonic acidemia programs. |
Research Methodology
A spread of perspectives from regulatory affairs leads at EMA and FDA, formulary directors at academic medical centers, viral vector process development heads, and patient advocacy foundation procurement officers converged on the working assumptions. Primary interview insights combined with secondary validation against ClinicalTrials.gov entries, EMA priority medicines scheme designations, FDA orphan drug exclusivity records, and CMS Medicare reimbursement data. Bottom-up patient cohort sizing and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type across enzyme replacement, diagnostic kits, metabolic modulators, and nutritional supplements; application across specialty clinics, home care, diagnostic laboratories, and research institutions; delivery mode across intravenous, subcutaneous, oral, and transdermal; and end user across healthcare providers, patients, caregivers, and research scientists. CAGRs were derived from trajectory fitting across the projection horizon. Forecast inputs incorporated biomarker validation timelines for mitochondrial disorder surrogate endpoints and viral vector manufacturing capacity expansion schedules.
The analysis sits within stated boundaries; outcomes outside FDA and EMA accelerated approval pathway continuity, viral vector supply chain stability, and gene therapy reimbursement framework resolution would require recalibration. Forecasts reflect documented assumptions regarding orphan drug incentive persistence and AI-assisted diagnostic platform adoption curves. Recalibration cycles align with material shifts in regulatory designation timelines and manufacturing capacity allocation decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market