
 Cellulitis Management Market | 2026-2036
Cellulitis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulitis Management Market Outlook
Hospital procurement channels for cellulitis antibiotics is narrowing as integrated delivery networks consolidate purchasing decisions across regional systems. Pfizer leverages its manufacturing scale to secure multi-year supply agreements with these networks. Sun Pharmaceutical Industries Ltd anchors its position through cost-competitive oral generic portfolios that dominate discharge prescriptions. Teva Pharmaceutical Industries Ltd competes on breadth, sustaining formulary slots across both acute and step-down care settings.
Cellulitis management encompasses the clinical protocols, pharmaceutical interventions, and wound care methodologies used to treat acute bacterial skin infections, primarily involving beta-hemolytic streptococci and Staphylococcus aureus, where antibiotic selection depends on severity grading, comorbidity profiles, and local resistance patterns. The primary purpose is to halt bacterial spread, prevent necrotizing complications, and reduce recurrence rates in vulnerable populations. Antibiotics command the largest value share among product types, while intravenous medications carry premium pricing tied to hospital administration and monitoring requirements. Oral medications represent the fastest expansion pathway as outpatient parenteral-to-oral conversion protocols shorten hospital stays and shift treatment burden to homecare settings.
The FDA oversees anti-infective approval pathways and antimicrobial stewardship guidance that shape prescribing patterns and hospital formulary decisions, while the EMA's evolving resistance surveillance frameworks influence developer R&D priorities in European markets. These regulatory architectures elevate the evidence threshold for new entrants and reward sponsors with robust resistance data packages. Stakeholders must monitor how payer tightening on outpatient antibiotic reimbursement reshapes channel economics between hospitals and homecare providers.
Market Dynamics
Integrated delivery networks in the United States are consolidating antibiotic procurement decisions across multi-hospital systems, compressing vendor access and rewarding manufacturers with vertically integrated supply chains and resistance surveillance capabilities.
Growth Catalysts
- FDA STREAM Pathways:The FDA's streamlined approval mechanisms for anti-infective therapies reduce clinical trial duration and accelerate market entry for novel antibiotics targeting resistant gram-positive pathogens.
- Outpatient Parenteral-to-Oral Conversion:Ambulatory care networks are expanding home infusion services, shifting intravenous antibiotic administration from hospitals to homecare settings and extending treatment duration capture.
- Long-Term Care Facility Volume:Skilled nursing facilities and residential care centers in the United States are experiencing elevated cellulitis admission rates among diabetic and immunocompromised populations.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for key beta-lactam antibiotics concentrates in China and India, exposing formulators to geopolitical disruption and customs delays.
- Antimicrobial Stewardship Mandates:CDC and Joint Commission requirements for hospital antibiotic oversight programs restrict broad-spectrum prescribing and compress empirical therapy windows.
- Oral Generic Substitution:Cost-competitive oral generic portfolios dominate discharge prescriptions, eroding branded oral antibiotic margins and compressing revenue per patient episode.
Strategic Opportunities
- Homecare Infusion Networks:Underpenetrated rural markets in the United States present expansion targets for specialty pharmacy providers capable of delivering outpatient parenteral antibiotic therapy with remote monitoring.
- Combination Wound Care Protocols:Convergence of topical antimicrobial dressings with systemic antibiotic regimens offers integrated treatment bundles for diabetic foot cellulitis in podiatry and wound care centers.
- IRAntibiotic Reimbursement:Medicare's evolving reimbursement frameworks for hospital outpatient antibiotic administration create incentive alignment for shortened length-of-stay protocols.
Industry Challenges
- Microbiology Laboratory Capacity:Hospital and reference laboratories face staffing shortages in clinical microbiology, delaying culture-directed therapy and extending empirical antibiotic exposure.
- EHR Integration Complexity:Antimicrobial stewardship software platforms require costly integration with legacy electronic health record systems, slowing deployment across community hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulitis Management Market |
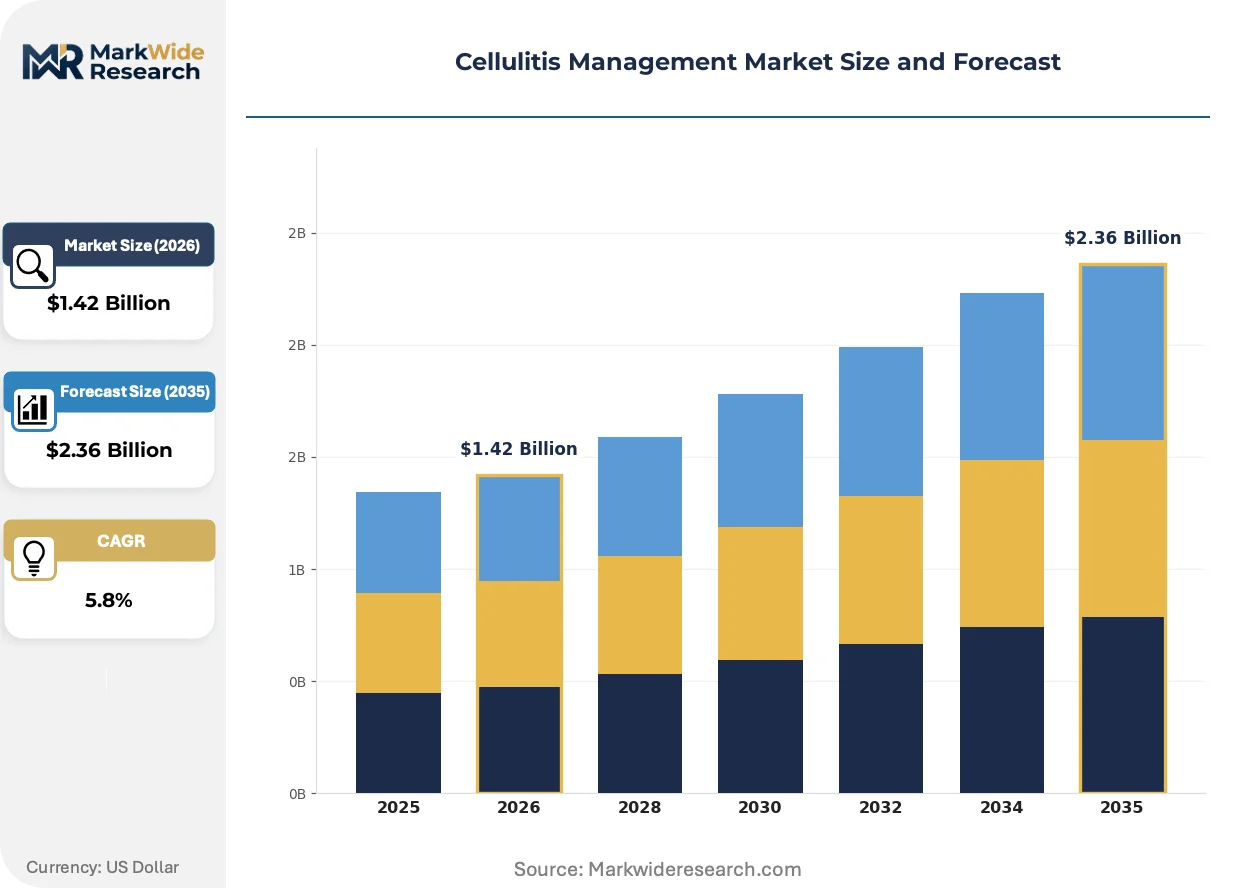
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Topical Treatments, Oral Medications, Intravenous Medications Administration Route: Oral, Intravenous, Topical, Intramuscular End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Treatment Stage: Acute Phase, Recovery Phase, Maintenance Phase, Preventive Care |
| Companies Covered | Pfizer, Sun Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd, Teva Pharmaceutical Industries Ltd, Novartis AG, GlaxoSmithKline, Shionogi & Co., Ltd., Aurobindo Pharma Ltd, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulitis Management Market Strategic Shifts
Diagnostics-guided de-escalation is displacing empirical broad-spectrum prescribing across acute care settings, compressing antibiotic exposure duration and reshaping manufacturer value demonstration requirements.
Rapid molecular diagnostic platforms are rendering obsolete traditional culture-based susceptibility testing for staphylococcal and streptococcal identification. Hospital microbiology laboratories in the United States are adopting PCR-based pathogen detection within 24-48 hours of admission. This compression of diagnostic turnaround is rendering obsolete extended empirical vancomycin coverage and enabling same-day targeted therapy selection.
EMA's evolving resistance surveillance frameworks are elevating post-market pharmacovigilance obligations for systemic antibiotics across European markets. Developers must now submit annual resistance surveillance data packages to maintain marketing authorization, increasing regulatory compliance costs. Hospital formularies in Germany and France are prioritizing agents with robust resistance mitigation data, disadvantaging entrants with limited real-world evidence portfolios.
Specialty pharmacy carve-outs from traditional hospital purchasing are fragmenting antibiotic distribution channels in the United States. Integrated delivery networks are contracting directly with home infusion providers for outpatient parenteral therapy, bypassing wholesale distributors. This channel disintermediation is most visible in Medicare Advantage populations concentrated in Florida and Texas, where risk-bearing entities seek cost containment through shortened inpatient stays.
Cellulitis Management Market Segmentation
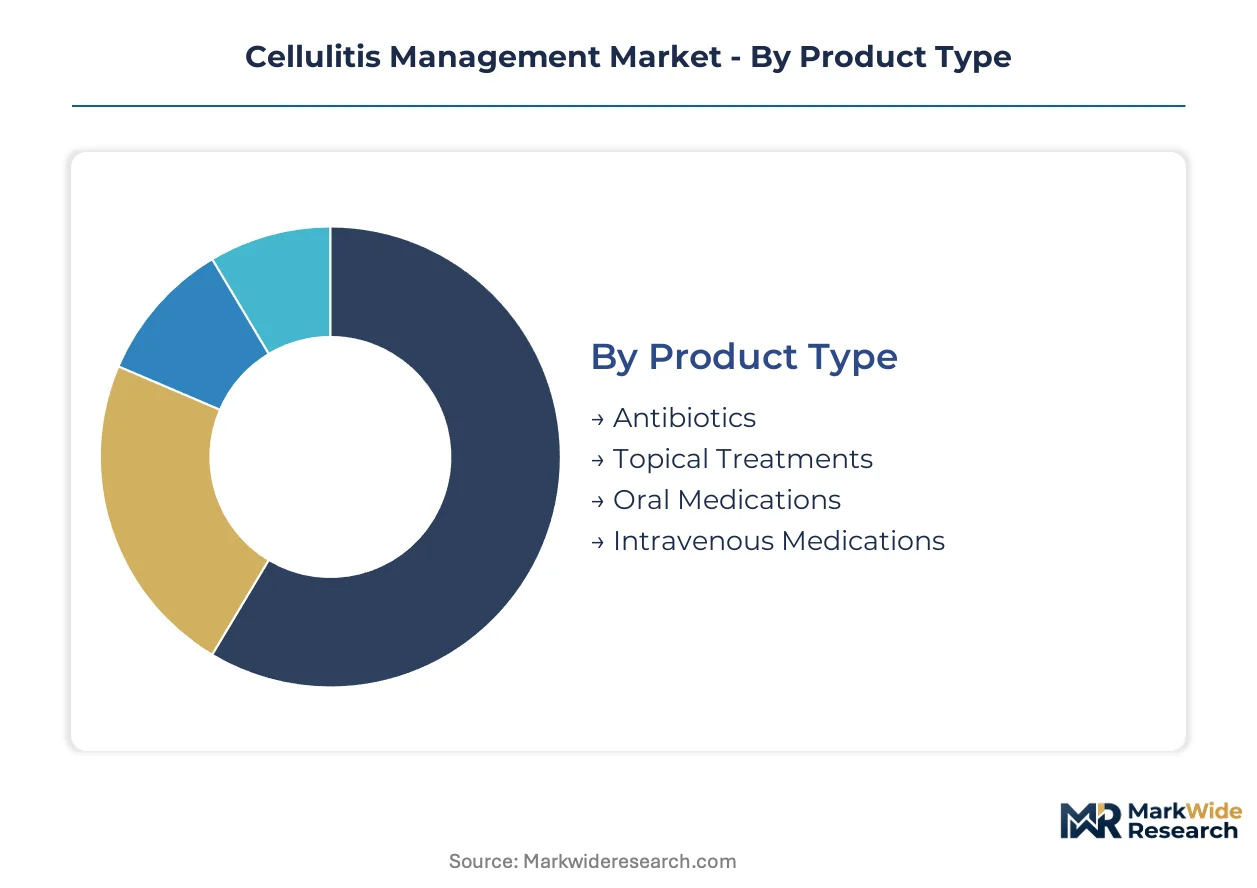
Cellulitis management spans a complex care continuum where product selection, delivery mode, and care setting interlock to determine clinical outcomes and cost structures. Understanding how these dimensions fragment reveals where pharmaceutical and service investments concentrate.
Product Type:
Use-case spectrum ranges from systemic bacterial eradication to localized wound bed preparation, with each tier commanding distinct margin profiles and regulatory pathways.
- Antibiotics:Systemic agents targeting beta-hemolytic streptococci and Staphylococcus aureus form the therapeutic backbone, with selection guided by severity grading and local resistance surveillance. Hospital formularies in the United States prioritize agents with FDA-approved MRSA coverage for empirical therapy initiation.
- Oral Medications:Beta-lactam and macrolide formulations enable discharge from acute care, with step-down protocols shortening length-of-stay metrics that Medicare Advantage plans scrutinize. Florida and Texas networks are expanding home-based oral completion therapy for uncomplicated cases.
- Topical Treatments:Antimicrobial dressings and enzymatic debriders serve adjunctive roles in diabetic foot presentations, often bundled with systemic regimens in wound care centers.
- Intravenous Medications:Vancomycin and daptomycin infusions require hospital or home infusion infrastructure, with reimbursement tied to administration setting.
The dominant share belongs to Antibiotics, while Oral Medications is closing the gap fastest.
Administration Route:
Cost tier stratification separates acute inpatient delivery from ambulatory and self-administered alternatives, reshaping channel economics.
- Oral:Generic cephalexin and amoxicillin-clavulanate dominate discharge prescribing, with pharmacy benefit managers driving substitution to preferred formulary tiers.
- Intravenous:Infusion services capture premium reimbursement when delivered in hospital outpatient departments, though home infusion carve-outs are compressing this margin.
- Topical:Silver sulfadiazine and mupirocin ointments serve localized superficial infections and surgical site prophylaxis in post-acute settings.
- Intramuscular:Depot formulations like ceftriaxone bridge gaps in patient adherence for substance use populations and rural access constraints.
Oral administration commands volume leadership, though Intravenous delivery retains value concentration in Medicare reimbursement frameworks.
End User:
Customer type fragmentation reflects care migration from institutional settings toward lower-acuity environments.
- Hospitals:Emergency departments and observation units manage severe presentations with necrosis risk, where culture-directed de-escalation protocols govern antibiotic stewardship compliance.
- Homecare:Specialty pharmacy networks in the United States are deploying infusion nurses for outpatient parenteral therapy, supported by remote monitoring platforms that track adherence and adverse events.
- Clinics:Urgent care and primary care sites handle uncomplicated presentations, with point-of-care ultrasound increasingly deployed to exclude abscess formation.
- Long-term Care Facilities:Skilled nursing facilities in the United States experience elevated admission rates from diabetic residents, with CMS quality metrics tracking infection-related hospitalization rates.
Hospitals retain the dominant share of severe case value, though Homecare is gaining share fastest as risk-bearing entities shorten inpatient stays.
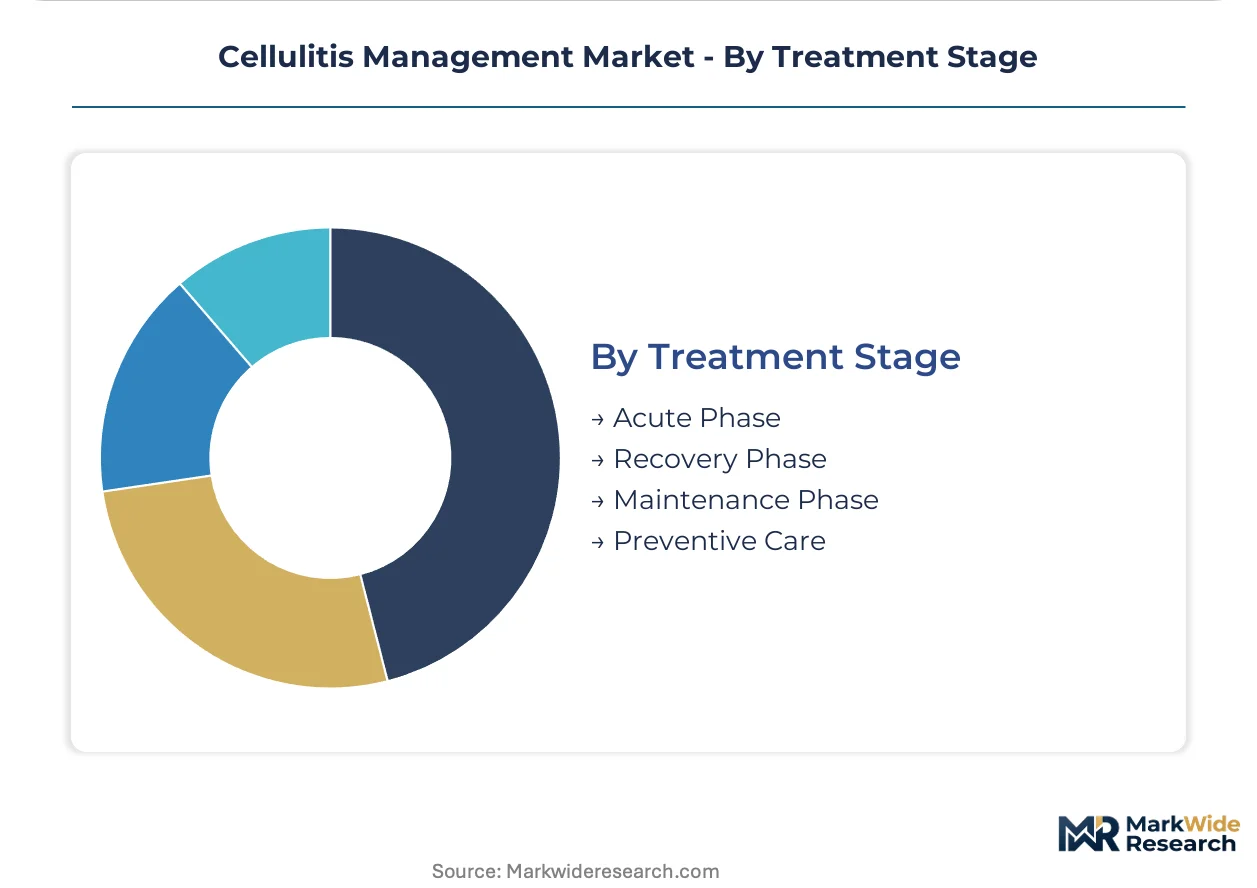
Treatment Stage:
Maturity gradient separates high-intensity acute intervention from lower-margin chronic management and prophylaxis.
- Acute Phase:Empirical broad-spectrum coverage with progression monitoring occupies the highest resource intensity, where rapid molecular diagnostics are compressing time-to-targeted therapy.
- Recovery Phase:Parenteral-to-oral conversion protocols and wound reassessment schedules determine total antibiotic exposure duration.
- Maintenance Phase:Extended suppressive therapy for recurrent cellulitis in lymphedema patients involves prolonged low-dose regimens with tetracyclines or macrolides.
- Preventive Care:Skin hygiene protocols and tinea pedis management in diabetic populations aim to reduce recurrence incidence.
The Acute Phase captures dominant expenditure, while Preventive Care is expanding most quickly as payers invest in readmission reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement frameworks in the United States reward shortened length-of-stay protocols, accelerating outpatient parenteral-to-oral conversion and reshaping regional demand patterns across developed markets.
United States
Integrated delivery networks in Florida and Texas are contracting directly with home infusion providers for outpatient antibiotic therapy. The FDA's STREAM pathways accelerate anti-infective approvals, reducing clinical trial duration for novel agents. Hospital procurement consolidation across multi-hospital systems in the Southeast is compressing vendor access and rewarding manufacturers with vertically integrated supply chains.
Germany
Hospital formularies prioritize agents with robust resistance mitigation data, disadvantaging entrants with limited real-world evidence portfolios. The EMA's evolving resistance surveillance frameworks elevate post-market pharmacovigilance obligations for systemic antibiotics. Manufacturing clusters in Baden-Württemberg concentrate on high-quality beta-lactam production for European distribution.
Japan
PMDA oversight shapes antimicrobial stewardship compliance requirements in acute care settings. Rapid molecular diagnostic adoption in Tokyo and Osaka metropolitan hospitals compresses time-to-targeted therapy. Domestic pharmaceutical manufacturers face pricing pressure from generic substitution policies while maintaining quality leadership in intravenous formulations.
India
Active pharmaceutical ingredient manufacturing for key beta-lactam antibiotics concentrates in Gujarat and Maharashtra, exposing formulators to customs delays and geopolitical disruption. CDSCO regulatory pathways govern anti-infective approvals, with cost-competitive oral generic portfolios dominating discharge prescriptions. Hyderabad-based manufacturers anchor global supply for oral cephalosporins.
United Kingdom
NHS antimicrobial stewardship programs restrict broad-spectrum prescribing and compress empirical therapy windows. London and Southeast England hospital networks deploy point-of-care diagnostics to accelerate culture-directed de-escalation. Post-Brexit regulatory divergence from EMA frameworks creates parallel compliance obligations for sponsors seeking market access.
Cellulitis Management Market Competitive Environment
On the supply side, the industry is consolidating around manufacturers with vertically integrated API-to-formulation capabilities and multi-year supply agreements with integrated delivery networks. Tiered competitive dynamics separate global innovators with novel anti-MRSA agents from cost-competitive generic specialists dominating oral step-down therapy. Three strategic archetypes define positioning: multinational innovators with hospital formulary anchoring, emerging market generic manufacturers with scale advantages, and specialty pharmaceutical firms with home infusion service integration. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and strategic partnerships with specialty pharmacy networks for outpatient parenteral distribution.
Among multinational innovators, Pfizer exemplifies the scale-driven archetype through manufacturing leverage and supply chain breadth. Sun Pharmaceutical Industries Ltd and Teva Pharmaceutical Industries Ltd occupy positions within the cost-competitive generic tier, with the former anchoring oral portfolio dominance and the latter sustaining formulary presence across acute and step-down care settings.
| Leading Market Players |
|---|
| Pfizer |
| Sun Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd |
| Teva Pharmaceutical Industries Ltd |
| Novartis AG |
| GlaxoSmithKline |
| Shionogi & Co., Ltd. |
| Aurobindo Pharma Ltd |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient manufacturing for beta-lactam antibiotics concentrates in Gujarat and Maharashtra, India, and coastal China, anchoring cost structures for downstream formulators and determining where margin pools accumulate in finished dosage production. This upstream concentration grants API suppliers significant leverage over oral generic pricing while exposing formulators to customs volatility and geopolitical friction.
Pricing Analysis
Volume-discount tiering structures separate hospital procurement contracts from retail pharmacy and home infusion channels. Three-tier pricing stratification across innovator intravenous agents, branded oral formulations, and commodity generics reflects FDA approval status and MRSA coverage breadth. Pricing pressure stems from pharmacy benefit manager formulary tightening on oral step-down therapy. Hospital networks exhibit lowest price sensitivity due to bundled reimbursement, while long-term care facilities face acute cost scrutiny under CMS quality metrics.
Supply Chain Analysis
Upstream feedstock dependency on 6-APA and 7-ACA intermediates draws from fermentation-based production in India, China, and select European sites. Key inputs include corn-derived dextrose, specialized enzyme catalysts, and solvent recovery systems. Single-source vulnerability concentrates in penicillin G potassium and cephalosporin C zinc salt precursors. Distribution runs through integrated delivery network direct contracting, bypassing wholesale distributors for outpatient parenteral therapy in Medicare Advantage populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulitis management markets are recovering from antimicrobial stewardship compression cycles as outpatient parenteral-to-oral conversion protocols expand addressable volume. This cyclical recovery hinges on Medicare reimbursement recalibration for shortened length-of-stay incentives.
For Market Incumbents: Insulate formulary positioning through backward integration into active pharmaceutical ingredient production, securing captive supply of beta-lactam intermediates against tariff exposure. Anchor hospital contracts with resistance surveillance data packages that satisfy FDA pharmacovigilance requirements. Deepen integration with specialty pharmacy networks to control outpatient parenteral distribution channels as home infusion carve-outs fragment traditional wholesale routes. For New Entrants and Emerging Players: Rural homecare markets in the United States Southeast present underpenetrated white-space for outpatient antibiotic therapy with remote monitoring capabilities. Target skilled nursing facility networks in Florida and Texas where diabetic foot cellulitis admissions concentrate and risk-bearing entities seek cost containment. Pursue combination wound care protocol partnerships with podiatry centers to bundle topical antimicrobial dressings with systemic regimens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty pharmacy platforms holding home infusion infrastructure and Medicare Advantage contracts. Long-term viability favors vertically integrated manufacturers with API-to-formulation capabilities and multi-year supply agreements with consolidated hospital networks. Watch FDA STREAM pathway approval velocity as inflection indicator for novel anti-MRSA agent commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive supply of beta-lactam intermediates insulates margin from customs delays and tariff volatility. |
| Specialty Pharmacy Network Partnership | Direct contracting with home infusion providers captures outpatient parenteral therapy volume outside hospital channels. |
| Rapid Molecular Diagnostic Co-Development | PCR-based pathogen identification platforms accelerate culture-directed de-escalation and reduce empirical vancomycin exposure. |
| Resistance Surveillance Data Investment | Annual pharmacovigilance packages satisfy EMA post-market obligations and secure hospital formulary priority in Germany and France. |
| Combination Wound Care Protocol Launch | Integrated topical-systemic bundles for diabetic foot cellulitis differentiate offerings in podiatry and wound care centers. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with hospital formulary directors, antimicrobial stewardship officers, specialty pharmacy procurement leads, and CDSCO regulatory consultants; and secondary validation through FDA anti-infective approval databases, EMA resistance surveillance frameworks, CMS Medicare cost reports, and integrated delivery network contract disclosures. Bottom-up patient-flow modeling triangulated against top-down pharmaceutical expenditure tracking.
Forecast inputs considered antibiotic utilization rates across acute, step-down, and homecare settings, segmented by administration route, severity grading, and regional reimbursement cluster. Treatment duration assumptions incorporated parenteral-to-oral conversion protocol adoption curves. CAGR derivation weighted historical antimicrobial expenditure elasticity against projected outpatient shift acceleration over the projection horizon.
Practitioners should monitor FDA STREAM pathway throughput, Medicare Advantage risk adjustment recalibration, and API customs clearance latency for early signals of forecast deviation. Material shifts in antimicrobial stewardship mandate stringency or hospital procurement consolidation velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Pleurodynia Treatment Market