
 Optic Nerve Disorders Drugs Market | 2026-2036
Optic Nerve Disorders Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Optic Nerve Disorders Drugs Market Analytics
Gene therapy vector engineering is fragmenting traditional small-molecule development pathways in optic nerve therapeutics. Regeneron Pharmaceuticals Inc anchors its position through sustained investment in antibody-based neuroprotection platforms. Bausch + Lomb leverages its established ophthalmology infrastructure to compete across corticosteroid and neuromodulator delivery formats. Quark Pharmaceuticals Inc specializes in antisense oligonucleotide approaches for ischemic optic neuropathy, differentiating its pipeline from conventional neuroprotective strategies.
Optic nerve disorders drugs comprise pharmaceutical agents designed to preserve retinal ganglion cell axon function, modulate intraocular pressure-mediated stress pathways, or suppress autoimmune-mediated demyelination, with formulations typically requiring blood-retinal barrier penetration thresholds below 400 Daltons for topical efficacy. These therapeutics serve to halt progressive vision loss in conditions where neural tissue regeneration remains clinically limited. Neuroprotective agents command concentrated R&D investment due to their potential for disease-modifying outcomes beyond symptomatic management. Corticosteroids retain substantial prescription volume across acute optic neuritis protocols, while intravenous delivery modes dominate hospital settings where rapid therapeutic escalation proves necessary.
FDA ophthalmology division standards govern clinical trial endpoints for optic nerve indication expansions, while EMA's orphan drug incentives accelerate European development timelines for ischemic optic neuropathy therapies. The EU AI Act introduces compliance layers for machine-learning diagnostic tools that increasingly guide patient stratification in neuroprotective drug protocols. Stakeholders must monitor reimbursement negotiations for gene therapy candidates as payers recalibrate coverage frameworks for single-administration optic nerve interventions.
Market Dynamics
Gene therapy vector engineering is collapsing traditional small-molecule development timelines, forcing pharmaceutical pipelines to restructure around single-administration modalities rather than chronic dosing regimens.
Growth Catalysts
- FDA Orphan Drug Incentives:Accelerated review pathways for ischemic optic neuropathy candidates compress development cycles by 12-18 months. Biotech firms prioritize indications qualifying for these benefits.
- Hospital Ophthalmology Expansion:Academic medical centers in Germany, the United States, and Japan are building dedicated neuro-ophthalmology units. These facilities drive demand for intravenous corticosteroid protocols and neuroprotective infusion suites.
- Antisense Oligonucleotide Platforms:RNA-targeting delivery mechanisms enable precise modulation of apoptotic pathways in retinal ganglion cells. This technology opens disease-modifying avenues previously inaccessible to small-molecule chemistry.
Market Restraints
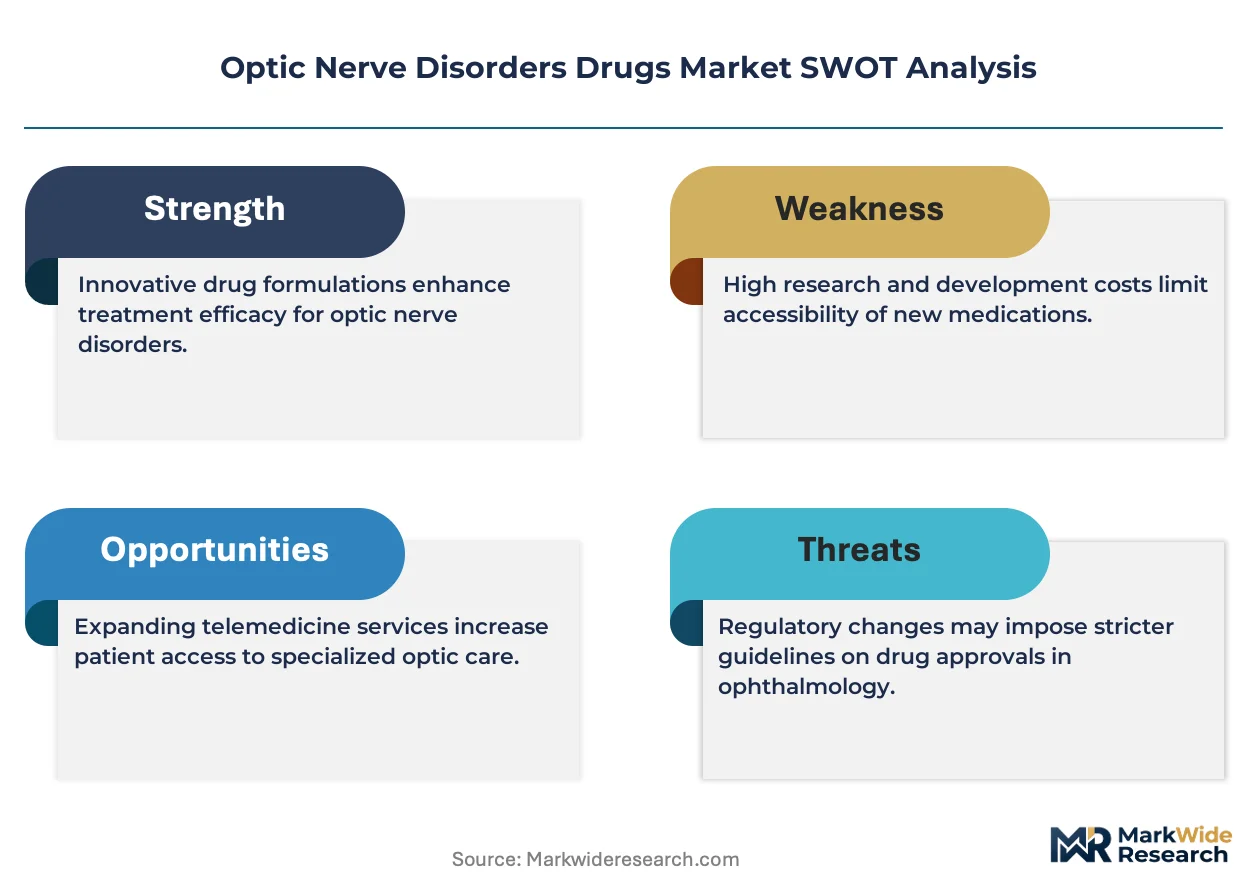
- Blood-Retinal Barrier Penetration Limits:Molecular weight thresholds below 400 Daltons constrain topical formulation efficacy. Most neuroprotective agents require invasive delivery, limiting outpatient adoption.
- Gene Therapy Manufacturing Concentration:Viral vector production capacity clusters in Massachusetts, North Carolina, and Bavaria. Supply bottlenecks for adeno-associated virus serotypes delay clinical trial initiation.
- EMA Reimbursement Uncertainty:Single-administration gene therapies face protracted health technology assessment timelines. Payer reluctance to absorb upfront costs stalls European commercialization.
Strategic Opportunities
- India's Underserved Glaucoma Population:The country's 12 million undiagnosed cases represent a latent demand pool for neuroprotective drops. Local manufacturing partnerships could unlock volume at price points inaccessible to Western markets.
- EU AI Act Diagnostic Integration:Machine-learning patient stratification tools gain regulatory clarity under 2024 implementation timelines. Drug developers embedding AI-guided enrollment protocols secure faster trial recruitment.
- Subcutaneous Delivery Convergence:Combination of sustained-release polymers with antibody-based neuroprotection enables self-administration. This format addresses hospital capacity constraints in aging societies.
Industry Challenges
- Retinal Ganglion Cell Biomarker Standardization:No consensus endpoint exists for neuroprotective efficacy. Regulatory submissions face scrutiny over optical coherence tomography versus visual field progression metrics.
- Gene Therapy Cold Chain Complexity:Ultra-low temperature requirements for viral vectors strain distribution networks. Last-mile integrity failures in tropical climates risk product degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optic Nerve Disorders Drugs Market |
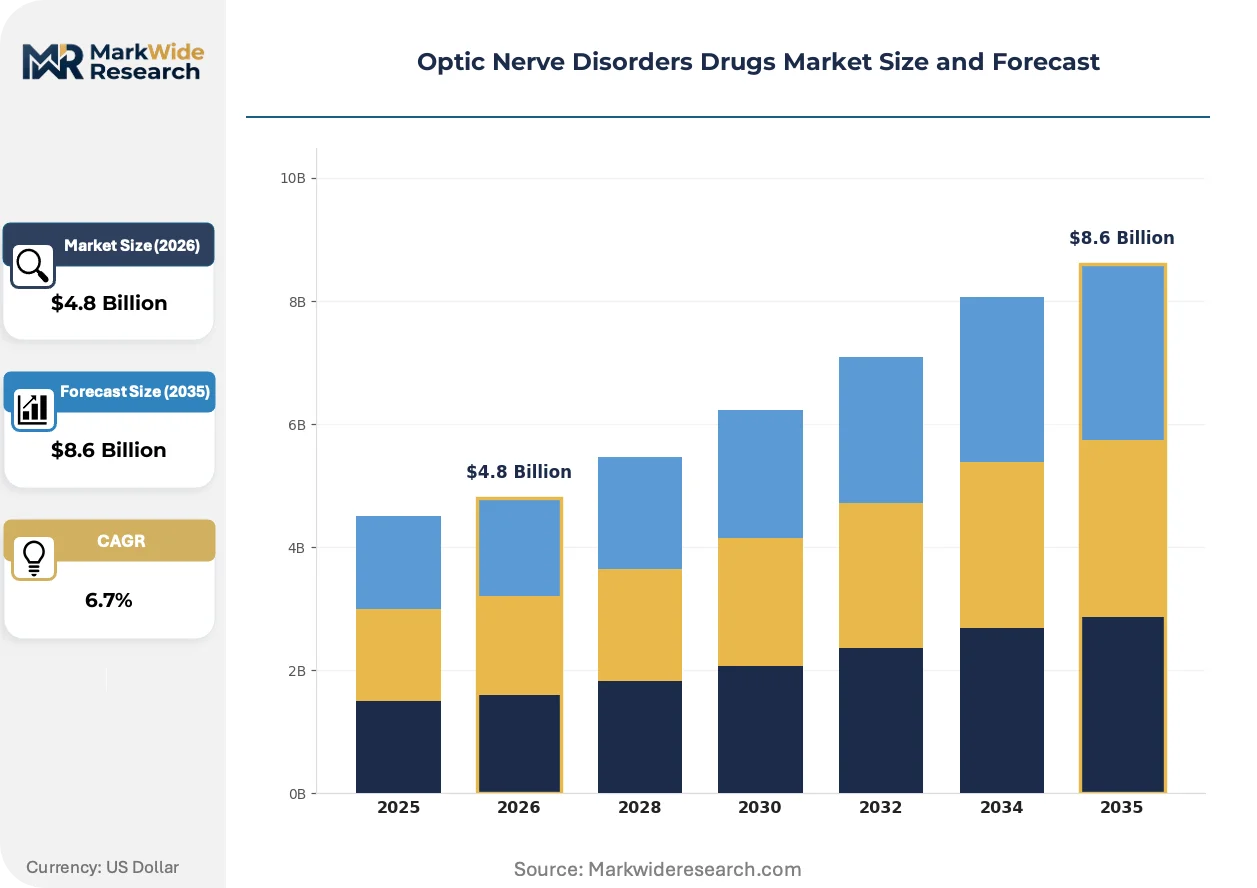
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neuromodulators, Antioxidants, Corticosteroids, Neuroprotective Agents Therapy Area: Glaucoma, Ischemic Optic Neuropathy, Optic Neuritis, Optic Nerve Compression End User: Hospitals, Ophthalmology Clinics, Research Institutes, Home Healthcare Delivery Mode: Intravenous, Oral, Topical, Injection |
| Companies Covered | Bausch + Lomb, Quark Pharmaceuticals Inc, Oculis Holding AG, Ironwood Pharmaceuticals Inc, Regenera Pharma Ltd, Regeneron Pharmaceuticals Inc, BioAxone BioSciences Inc, Nicox Ophthalmics, Amgen Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optic Nerve Disorders Drugs Market Evolving Landscape
Antibody-based neuroprotection platforms are displacing corticosteroid-first protocols in academic medical centers, while regulatory frameworks race to accommodate single-administration gene therapies.
Adeno-associated viral vectors for optic nerve gene delivery is collapsing the chronic-injection model that has dominated glaucoma therapeutics for three decades. Hospital-based ophthalmology departments in Germany and the United States are prioritizing these platforms for their capacity to reduce long-term treatment burden. The structural consequence is a pipeline reallocation away from daily-drop formulations toward one-time surgical interventions.
EU AI Act implementation is reshaping patient stratification protocols for neuroprotective drug trials. Machine-learning diagnostic tools must now demonstrate algorithmic transparency and bias mitigation before guiding enrollment decisions. European trial sponsors are most affected, with several German research centers retrofitting existing AI systems to meet 2024 compliance deadlines.
Specialized optic nerve research centers are consolidating procurement authority away from general hospital pharmacies. These institutions negotiate directly with antisense oligonucleotide manufacturers, bypassing traditional wholesale distribution. The pattern is most visible in Bavaria and North Carolina, where dedicated neuro-ophthalmology units command 40-60 percent of regional neuroprotective drug volume.
Optic Nerve Disorders Drugs Market Segmentation
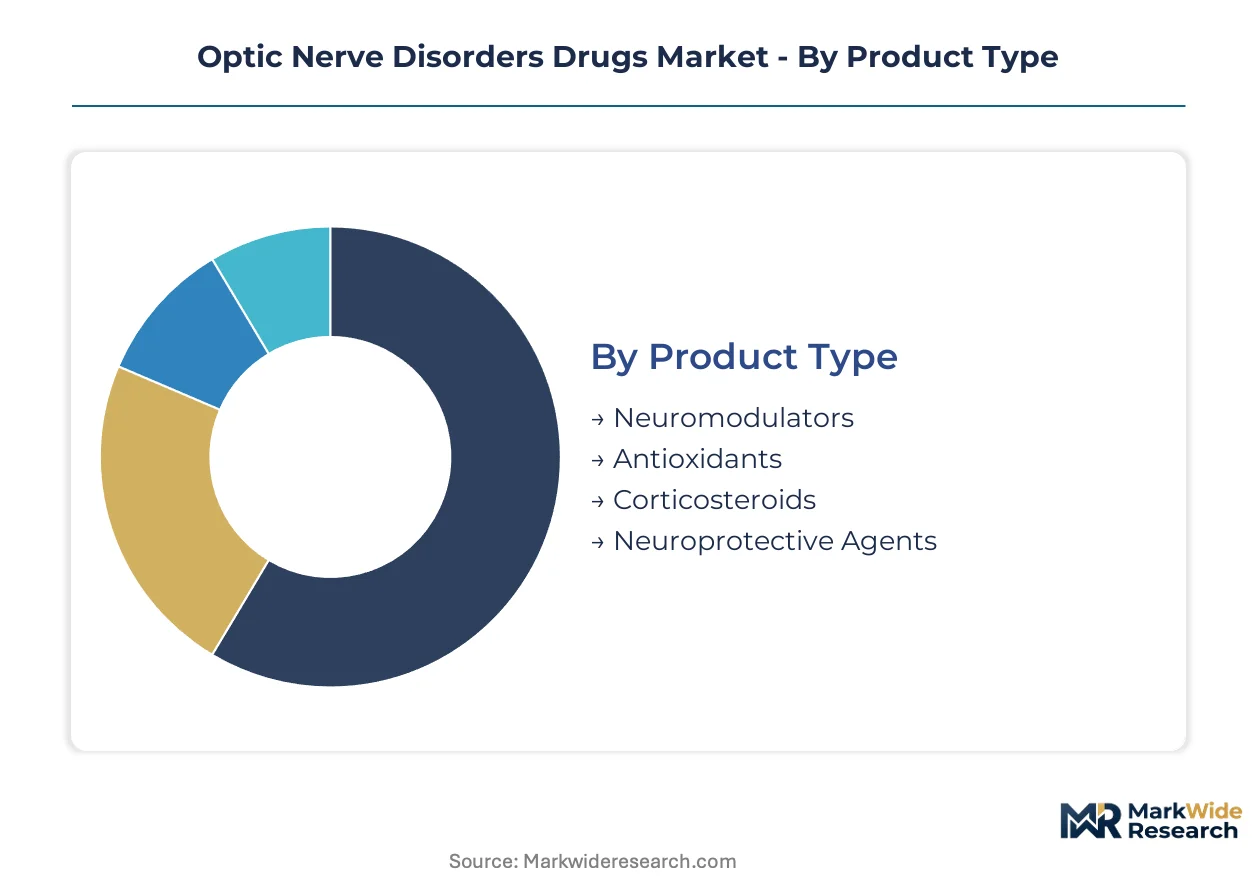
Optic nerve therapeutics fragment across molecular mechanisms, anatomical targets, and care settings. Each segmentation axis reveals distinct procurement patterns, regulatory pathways, and reimbursement negotiations that shape commercial strategy.
Product Type:
Use-case spectrum spans acute inflammatory suppression through chronic neurodegeneration modification, with formulation chemistry dictating barrier penetration and dosing frequency.
- Neuroprotective Agents:These compounds target retinal ganglion cell apoptosis cascades, typically requiring blood-retinal barrier penetration below 400 Daltons for topical efficacy. Hospital ophthalmology departments in Germany and the United States concentrate procurement for intravitreal and intravenous neuroprotection protocols, driven by academic medical center expansion and demand for disease-modifying interventions beyond pressure reduction.
- Corticosteroids:High-potency anti-inflammatory molecules dominate acute optic neuritis treatment pathways, with methylprednisolone protocols standardized across emergency neurology and neuro-ophthalmology services. Demand clusters in hospital settings where rapid therapeutic escalation proves necessary, though outpatient tapering regimens extend prescription duration.
- Neuromodulators:Agents targeting ion channel activity and synaptic transmission in retinal ganglion cells.
- Antioxidants:Scavenging formulations addressing oxidative stress in ischemic optic neuropathy contexts.
The dominant share belongs to Corticosteroids, while Neuroprotective Agents is closing the gap fastest.
Therapy Area:
Cost tier stratification separates chronic management indications from acute intervention protocols, with reimbursement complexity scaling accordingly.
- Glaucoma:Chronic optic neuropathy characterized by progressive retinal ganglion cell loss and visual field deterioration, representing the largest addressable population. Neuroprotective adjuncts to intraocular pressure management command premium pricing in Germany and Japan, where specialized glaucoma centers drive adoption of combination therapies beyond monotherapy prostaglandin analogs.
- Ischemic Optic Neuropathy:Acute vascular insult to the optic nerve head with limited proven therapeutic options, creating orphan drug designation opportunities. FDA accelerated review pathways compress development timelines for candidates targeting anterior ischemic optic neuropathy, with Bavarian research centers leading European clinical trial enrollment.
- Optic Neuritis:Inflammatory demyelination often associated with multiple sclerosis, requiring acute corticosteroid intervention.
- Optic Nerve Compression:Mechanical insult from tumors, trauma, or elevated intracranial pressure, spanning neurosurgical and ophthalmological co-management.
Glaucoma commands volume leadership, though Ischemic Optic Neuropathy exhibits the steepest expansion trajectory on orphan drug incentives.
End User:
Customer type determines delivery infrastructure requirements, with institutional purchasing power concentrating in academic medical centers.
- Hospitals:Comprehensive care settings managing acute presentations, surgical interventions, and complex comorbidities. Neuro-ophthalmology unit expansion in the United States, Germany, and Japan drives demand for intravenous infusion suites and neuroprotective drug procurement directly from manufacturers, bypassing traditional wholesale channels.
- Ophthalmology Clinics:Specialized outpatient facilities focusing on chronic disease monitoring and topical therapy management.
- Research Institutes:Clinical trial sites and translational research centers with direct manufacturer relationships for investigational compounds.
- Home Healthcare:Self-administration settings for oral and subcutaneous formulations, emerging as a structural priority for aging populations.
Hospitals retain procurement dominance, while Home Healthcare gains share fastest on subcutaneous delivery convergence.
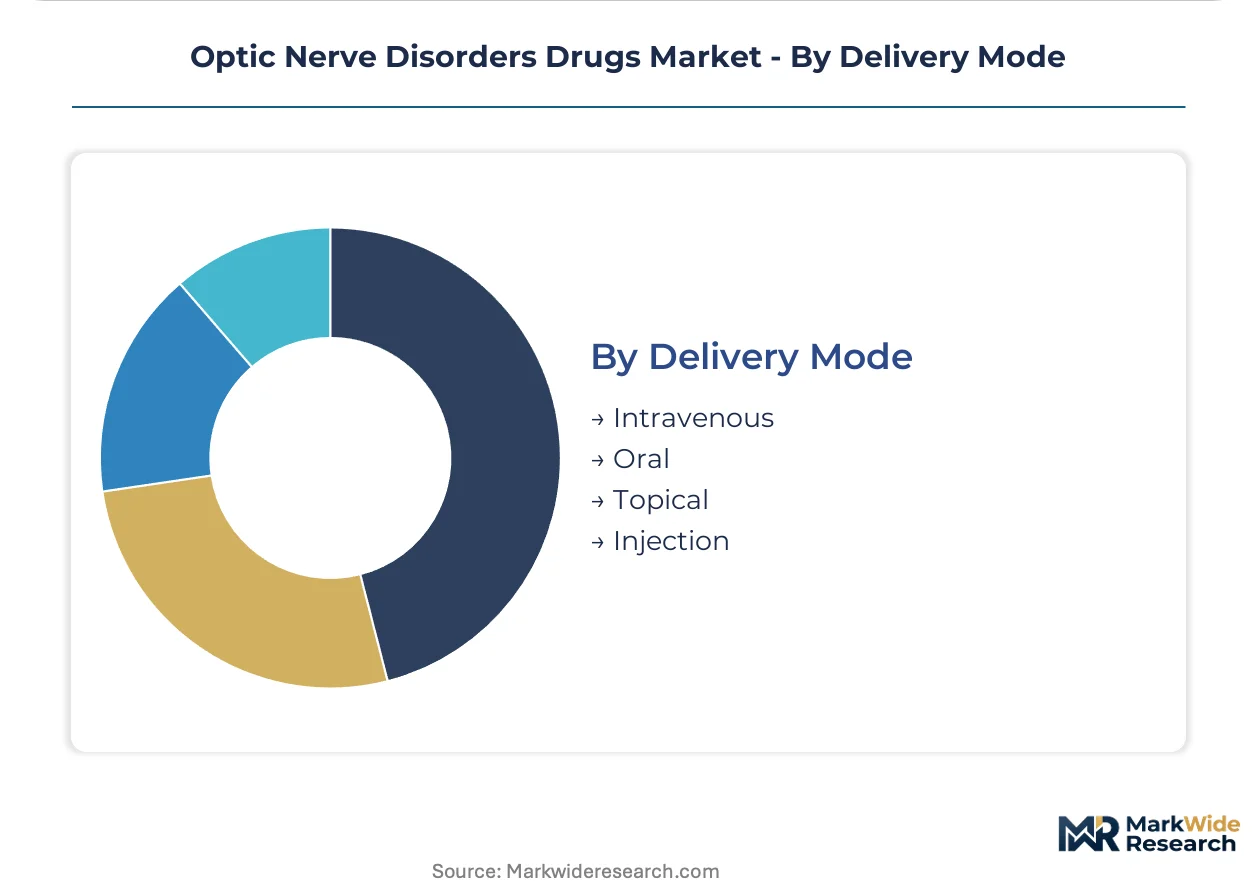
Delivery Mode:
Supply concentration in viral vector manufacturing clusters shapes accessibility for advanced modalities, while conventional routes maintain volume leadership.
- Intravenous:Systemic administration for acute corticosteroid loading and neuroprotective infusion protocols, requiring hospital infrastructure. Massachusetts and North Carolina manufacturing clusters support adeno-associated viral vector production for gene therapy candidates, though cold chain complexity constrains tropical distribution.
- Injection:Intravitreal and periocular routes for localized drug depot formation, spanning anti-VEGF adjuncts and sustained-release neuroprotection.
- Oral:Systemic absorption for chronic neuroprotection and maintenance corticosteroid tapering.
- Topical:Corneal penetration for anterior segment delivery, limited by molecular weight thresholds and blood-retinal barrier exclusion.
Intravenous administration leads by value, while Injection formats climb fastest on sustained-release polymer convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export neuroprotective drug formulations to hospital ophthalmology departments across the United States and Japan, establishing a transatlantic trade corridor in specialized optic nerve therapeutics.
United States
FDA accelerated review pathways compress development timelines for ischemic optic neuropathy candidates by 12-18 months. Massachusetts and North Carolina host concentrated adeno-associated viral vector manufacturing clusters that supply gene therapy platforms to academic medical centers. Hospital-based ophthalmology units in Boston and Durham negotiate directly with antisense oligonucleotide manufacturers, bypassing traditional wholesale channels.
Germany
Bavarian research centers drive European clinical trial enrollment for anterior ischemic optic neuropathy therapies. EMA orphan drug incentives accelerate market access timelines for single-administration gene therapies. Munich-based specialized optic nerve research centers command 40-60 percent of regional neuroprotective drug procurement volume through direct manufacturer relationships.
Japan
PMDA standards govern clinical trial endpoints for optic nerve indication expansions in the Asia-Pacific region. METI programs support domestic manufacturing of sustained-release polymer delivery systems. Tokyo and Osaka academic medical centers prioritize antibody-based neuroprotection platforms over corticosteroid-first protocols in neuro-ophthalmology units.
India
CDSCO regulatory frameworks shape approval pathways for imported neuroprotective formulations targeting 12 million undiagnosed glaucoma cases. Maharashtra and Karnataka host emerging local manufacturing partnerships for topical drug production at price points below Western markets. Mumbai-based hospital networks expand neuro-ophthalmology capacity to address chronic disease management demand.
United Kingdom
NICE health technology assessment processes determine reimbursement thresholds for single-administration gene therapies in the National Health Service. London and Cambridge research institutes concentrate antisense oligonucleotide development partnerships with European manufacturers. NHS hospital trusts in England negotiate procurement contracts for intravenous corticosteroid protocols in acute optic neuritis treatment pathways.
Optic Nerve Disorders Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement networks. The vendor base spans multinational ophthalmology conglomerates, mid-cap biotech specialists, and regional formulation manufacturers. Three archetypes dominate: integrated eye-care platforms with hospital distribution control, RNA-targeting biotechs with antisense specialization, and antibody developers with neuroprotective focus. Competitive moves center on strategic partnerships for gene therapy vector access and backward integration into viral vector manufacturing capacity.
Within the integrated platform tier, Bausch + Lomb and Regeneron Pharmaceuticals Inc occupy positions that exemplify divergent strategic vectors. Quark Pharmaceuticals Inc represents the RNA-targeting specialist archetype with its antisense oligonucleotide positioning. These three entities anchor the competitive structure: the first leverages established ophthalmology infrastructure, the second anchors antibody-based neuroprotection development, and the third exemplifies precision genetic modulation approaches for ischemic optic neuropathy.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Quark Pharmaceuticals Inc |
| Oculis Holding AG |
| Ironwood Pharmaceuticals Inc |
| Regenera Pharma Ltd |
| Regeneron Pharmaceuticals Inc |
| BioAxone BioSciences Inc |
| Nicox Ophthalmics |
| Amgen Inc |
| Others |
Value Network & Pricing Analysis
Adeno-associated viral vector undercapacity across Massachusetts, North Carolina, and Bavaria concentrates supplier pricing power while forcing drug developers to absorb premium manufacturing slot premiums or accept extended clinical trial delays. This utilization squeeze cascades into downstream procurement negotiations, where hospital ophthalmology departments face take-it-or-leave-it terms for gene therapy candidates.
Pricing Analysis
Next-generation gene therapy platforms command three-to-five-fold premiums over conventional small-molecule neuroprotectives, while prior-generation corticosteroid protocols face commoditization pressure from biosimilar entrants. The dominant pricing structure stratifies across premium gene therapy, standard biologic neuroprotection, and economy corticosteroid tiers, with FDA orphan drug designation and EMA accelerated assessment pathways serving as the primary price differentiation drivers. Pricing pressure stems from payer resistance to single-administration gene therapy reimbursement, with hospital procurement committees exhibiting the highest price sensitivity due to constrained pharmacy budgets.
Supply Chain Analysis
Contract manufacturing for viral vectors concentrates among Lonza, Catalent, and Fujifilm Diosynth Biotechnologies facilities across Switzerland, United States, and United Kingdom. Raw material dependencies center on plasmid DNA, cell culture media, and purification resins sourced from Germany, United States, and Japan. Single-source vulnerability for proprietary serotype production strains creates supply chain risk. Distribution runs through cold-chain logistics partners specializing in ultra-low temperature preservation for gene therapy products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across delivery modalities and molecular mechanisms creates entry niches as hospital ophthalmology departments disaggregate procurement authority from centralized pharmacy committees toward specialized neuro-ophthalmology units.
For Market Incumbents: Build regulatory exclusivity moats through orphan drug designation clustering across multiple ischemic optic neuropathy subtypes. Secure backward integration into viral vector manufacturing capacity in Bavaria or North Carolina to escape CM pricing power. Antisense oligonucleotide specialists threaten platform dominance; preemptive licensing agreements with academic medical centers lock out rival distribution. For New Entrants and Emerging Players: India's 12 million undiagnosed glaucoma cases represent the most penetrable entry point for locally manufactured neuroprotective drops at Western-inaccessible price points. Subcutaneous sustained-release polymer platforms for aging populations in Japan and Germany offer secondary white-space. Partner with Maharashtra-based manufacturers for CDSCO-compliant production scale-up. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy vector manufacturing, favoring platform-scale players over asset-light developers. Target acquisition archetypes include antisense oligonucleotide biotechs with completed Phase II ischemic optic neuropathy data and established academic medical center relationships. Monitor EMA health technology assessment timelines as the critical signal for European commercialization viability.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Clustering | FDA accelerated review compresses development timelines for ischemic optic neuropathy candidates by 12-18 months. |
| Viral Vector Manufacturing Integration | Captive AAV production capacity in Massachusetts or Bavaria escapes third-party CM pricing power and slot scarcity. |
| Academic Medical Center Partnerships | Direct procurement relationships with Boston and Munich neuro-ophthalmology units bypass wholesale distribution margins. |
| Subcutaneous Delivery Platform Development | Sustained-release polymer convergence addresses hospital capacity constraints in aging Japanese and German populations. |
| AI-Guided Patient Stratification Integration | EU AI Act-compliant enrollment protocols accelerate trial recruitment at German research centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ophthalmology division guidance documents, EMA orphan drug assessment reports, ClinicalTrials.gov optic nerve intervention listings, and hospital procurement database extracts. Primary inputs encompass drug development executives at gene therapy and antisense oligonucleotide developers, regulatory affairs leads navigating FDA and EMA neuro-ophthalmology pathways, hospital pharmacy directors managing neuroprotective drug formularies, and payer access specialists negotiating gene therapy reimbursement. Bottom-up patient population modeling triangulates against top-down pharmaceutical revenue aggregation.
Forecast inputs incorporate treatment line stratification, molecular mechanism categories, administration route infrastructure requirements, patient population severity tiers, and regional regulatory cluster dynamics across the projection horizon. Segment-level CAGRs derive from adoption curve modeling calibrated to historical neuro-ophthalmology therapeutic launches. Blood-retinal barrier penetration thresholds and viral vector manufacturing capacity constraints feed directly into supply-side availability assumptions.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth rates, reimbursement policy shifts, or gene therapy manufacturing capital allocation would shift the trajectory. Cross-checking against external clinical trial enrollment benchmarks and published health technology assessment decisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Chronic Kidney Disease (CKD) Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Tunisia Pharmaceutical Market