
 Rheumatoid Arthritis Treatment Market | 2026-2036
Rheumatoid Arthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rheumatoid Arthritis Treatment Market Outlook
Outcome-based contracting for biologic therapies is decoupling payment from vial volume across rheumatoid arthritis care. AbbVie Inc. anchors its position through deep R&D intensity in TNF-alpha inhibition. Pfizer Inc. competes through JAK inhibitor specialization and oral formulation leadership. Novartis AG differentiates via IL-17 and IL-23 pathway dominance in autoimmune expansion.
Rheumatoid arthritis treatment encompasses disease-modifying antirheumatic drugs, biologic response modifiers, and targeted synthetic agents designed to suppress immune-mediated synovial inflammation and prevent joint destruction. These therapies require cold-chain distribution, parenteral manufacturing sterility, and validated bioanalytical assays to ensure lot-to-lot consistency and patient safety. Biologics command the largest revenue pool within product type segmentation due to premium pricing and chronic administration protocols. JAK Inhibitors represent the fastest-expanding delivery mode segment as oral convenience displaces infusion dependency. Hospitals retain dominant procurement volume within end user segmentation, though home care infusion is gaining protocol acceptance.
The FDA accelerates biologic approvals through breakthrough therapy designation, while the EMA enforces batch-specific immunogenicity testing under centralized marketing authorization. Health Canada and the TGA align with ICH Q5A viral safety guidelines, creating harmonized barriers for non-compliant manufacturers. Stakeholders must monitor biosimilar interchangeability rulings and CMS reimbursement recalibration as these decisions reshape prescriber behavior and formulary access.
Market Dynamics
Outcome-based contracting is decoupling payment from vial volume across rheumatoid arthritis care, forcing manufacturers to demonstrate real-world efficacy rather than rely on chronic dosing protocols. This structural shift compresses margins for legacy biologics while rewarding therapies with durable clinical outcomes.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel JAK inhibitors and IL-23 pathway modulators, enabling earlier commercial access.
- Hospital Infusion Center Expansion:United States-based health systems are expanding biologic administration capacity to capture specialty pharmacy revenue streams and patient retention.
- Cold-Chain Infrastructure Maturation:Validated temperature-controlled distribution networks now reach tertiary care centers in India and Brazil, enabling biologic access beyond traditional North American and European markets.
Market Restraints
- Biosimilar Price Compression:EMA-enforced interchangeability rulings in Germany and France trigger automatic substitution at pharmacy level, eroding originator pricing power within months of entry.
- Plasma-Derived Input Volatility:Immunoglobulin and albumin feedstock costs fluctuate with donor collection cycles, squeezing manufacturing margins for fusion protein therapies.
- Infusion Center Capacity Constraints:United States nursing shortages limit expansion of hospital-based biologic administration, creating bottlenecks for prescribed therapies.
Strategic Opportunities
- Subcutaneous Self-Administration:Pen-device formulations for IL-17 and TNF-alpha inhibitors unlock home care channels, displacing infusion-dependent protocols.
- India's PLI Scheme for Biologics:Production-linked incentives for biosimilar manufacturing attract contract development investments from European originators seeking cost arbitrage.
- Real-World Evidence Integration:EMA's DARWIN EU network enables post-authorization efficacy tracking, creating differentiation pathways for therapies with superior registry outcomes.
Industry Challenges
- Bioanalytical Assay Standardization:Lot-to-lot immunogenicity testing lacks harmonized reference standards across FDA, EMA, and PMDA jurisdictions, delaying multi-region launches.
- Legacy IT Integration:Hospital systems struggle to embed patient-reported outcome capture into existing EHR workflows, compromising value-based contract data requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rheumatoid Arthritis Treatment Market |
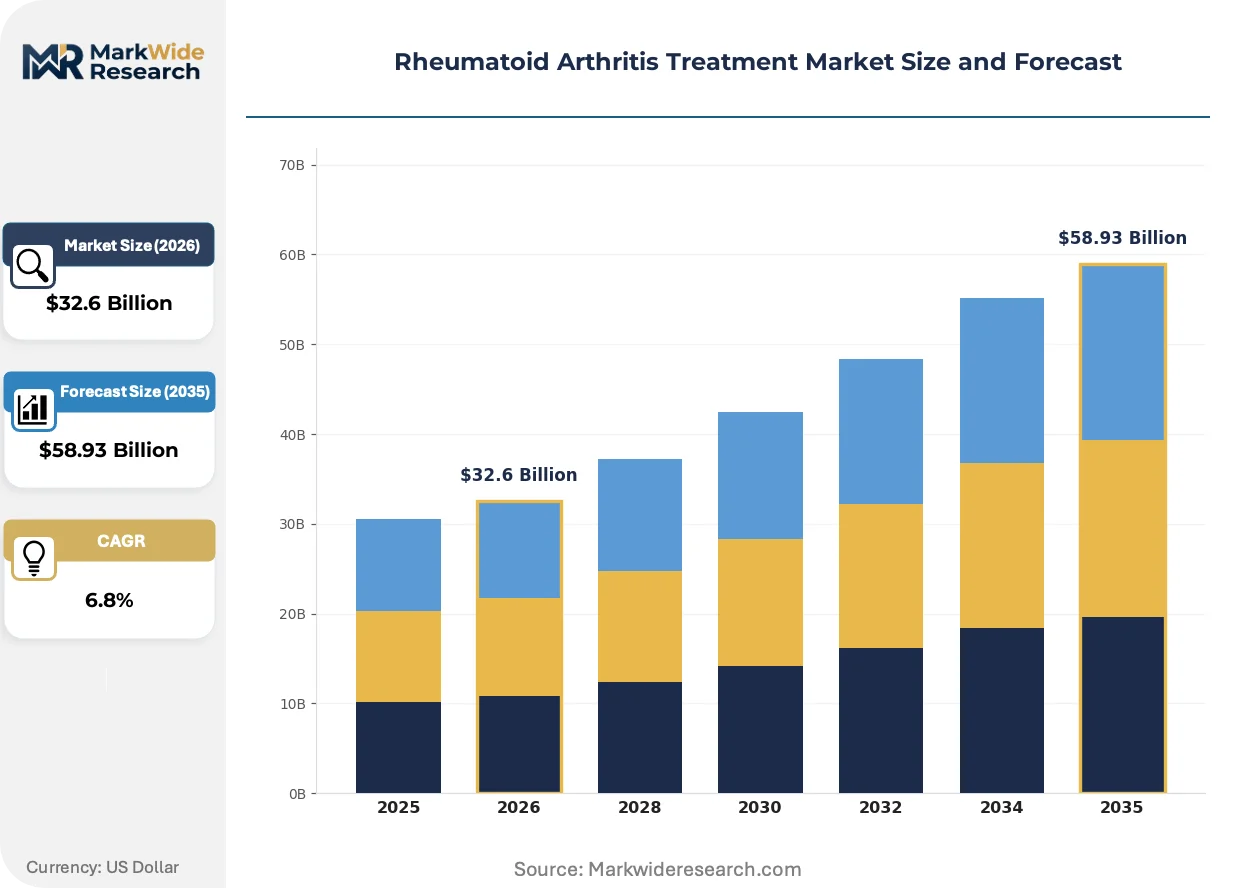
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DMARDs, Biologics, JAK Inhibitors, NSAIDs Delivery Mode: Injectable, Oral, Topical, IV End User: Hospitals, Outpatient Clinics, Home Care, Pharmacies Sales Channel: Direct Sales, Retail Pharmacies, Online Pharmacy, Wholesale |
| Companies Covered | Novartis AG, Bristol-Myers Squibb Company, AbbVie Inc., Regeneron Pharmaceuticals Inc., Johnson & Johnson Services Inc., Pfizer Inc., Eli Lilly and Company, UCB S.A., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rheumatoid Arthritis Treatment Market Strategic Shifts
Oral small-molecule therapies are compressing the dominance of parenteral biologics through convenience-driven prescribing patterns. Three forces are reshaping competitive positioning: molecular engineering advances, regulatory data requirements, and site-of-care migration.
Biospecific antibody constructs are overtaking monospecific TNF-alpha inhibition in investigator-initiated trials. These engineered modalities simultaneously block IL-6 and IL-17 signaling pathways. United States academic medical centers are adopting them for refractory patient cohorts. The technology is overtaking first-generation biologics in protocol design for head-to-head superiority studies.
EMA's centralized marketing authorization now mandates batch-specific immunogenicity testing with validated neutralizing antibody assays. This policy elevates analytical development costs for biosimilar entrants. Manufacturers must maintain dual reference product sourcing to satisfy comparator requirements. European contract research organizations are expanding bioanalytical capacity to absorb this demand.
Site-of-care decisions are migrating from physician preference to payer-mandated protocols. United States Medicare Advantage plans now require step-therapy documentation before approving hospital infusion. Home care nursing networks are capturing volume through specialty pharmacy partnerships. Germany's hospital segment exhibits the strongest resistance to this shift due to entrenched rheumatology department economics.
Rheumatoid Arthritis Treatment Market Segmentation
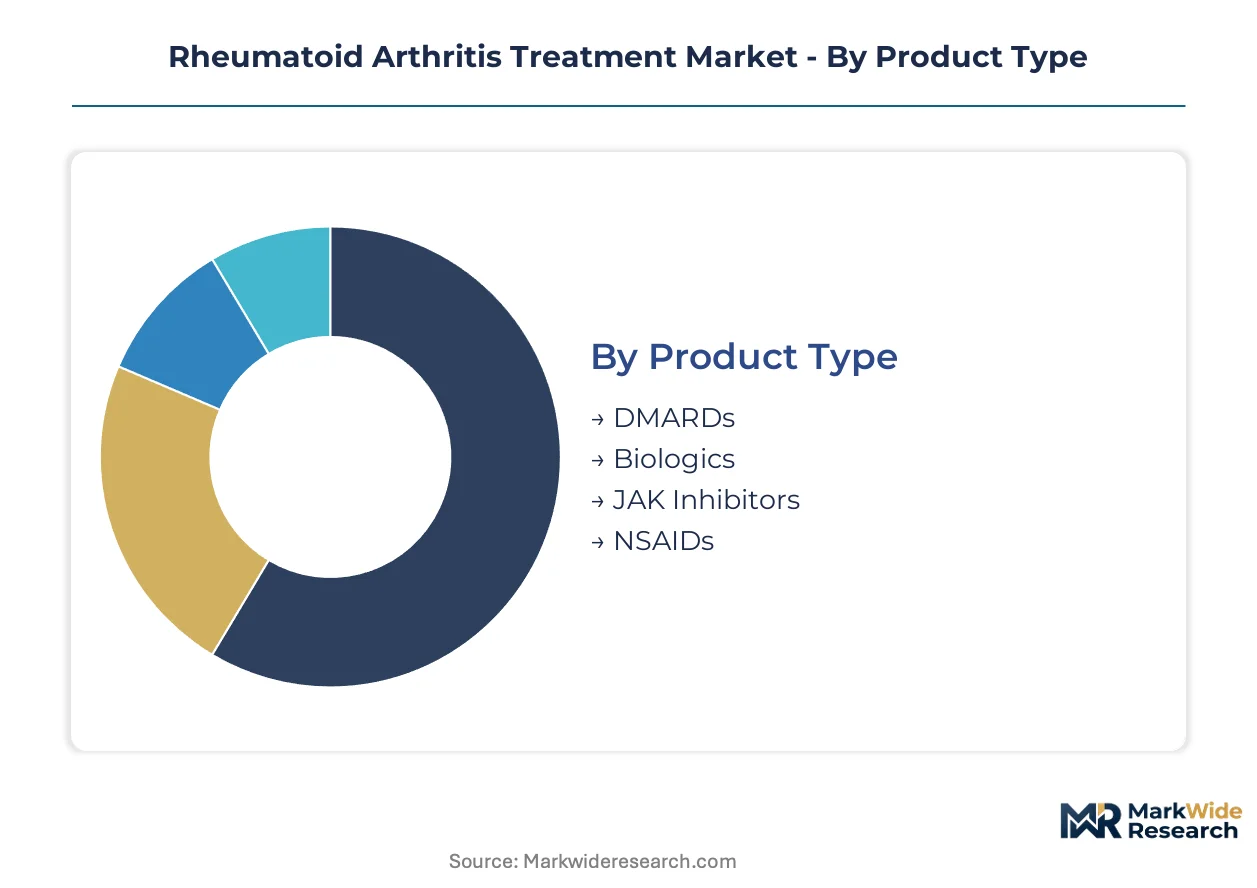
Segmentation reveals where capital deployment concentrates and which modalities command premium pricing. Understanding these divisions clarifies why biologics sustain margin leadership while oral formulations reshape prescribing patterns.
Product Type:
Biologics demand the heaviest upfront investment in cold-chain infrastructure, parenteral manufacturing suites, and validated bioanalytical assays.
- Biologics:Engineered monoclonal antibodies and fusion proteins require sterile bioreactor production and lot-to-lot consistency testing. Hospital infusion centers in the United States capture the majority of administered volume as they expand specialty pharmacy revenue streams.
- JAK Inhibitors:Small-molecule agents targeting intracellular signaling pathways enable oral administration without cold-chain dependency. Outpatient clinics in Germany are adopting these for patient cohorts seeking to avoid infusion center visits.
- DMARDs:Conventional synthetic disease-modifying agents remain foundational to first-line protocols.
- NSAIDs:Non-steroidal anti-inflammatory drugs address symptomatic relief without disease modification.
Biologics absorb the bulk of installed capacity; JAK Inhibitors are expanding most quickly.
Delivery Mode:
Cost tier stratification separates infusion-dependent biologics from self-administered alternatives that reduce site-of-care overhead.
- Injectable:Subcutaneous pen-device formulations for TNF-alpha and IL-17 inhibitors enable home administration. United States specialty pharmacies are capturing volume through nursing network partnerships that support patient training.
- Oral:Small-molecule JAK inhibitors eliminate cold-chain requirements and expand pharmacy dispensing options. Retail channels in India are scaling distribution as domestic manufacturing matures under PLI scheme incentives.
- IV:Intravenous infusion remains standard for initial loading doses and certain biologic classes.
- Topical:Localized delivery addresses limited joint involvement with minimal systemic exposure.
Injectable formats retain the largest revenue pool; oral administration is climbing the fastest as convenience drives formulary preference.
End User:
Customer type determines procurement scale and reimbursement complexity across institutional versus ambulatory settings.
- Hospitals:Integrated health systems command bulk purchasing leverage and infusion center revenue. Germany's hospital segment exhibits particular concentration as rheumatology departments defend procedural economics against site-of-care migration.
- Home Care:Nursing networks and specialty pharmacies coordinate biologic delivery and patient monitoring. United States Medicare Advantage plans are mandating step-therapy documentation before approving hospital-based administration.
- Outpatient Clinics:Ambulatory rheumatology practices manage stable patients on established regimens.
- Pharmacies:Community and specialty dispensaries handle oral therapies and self-injection training.
Hospitals retain dominant procurement volume; home care is gaining share fastest as payers enforce site-of-care optimization.
Sales Channel:
Supply concentration varies by channel control over patient access and data capture capabilities.
- Retail Pharmacies:Brick-and-mortar networks dispense oral JAK inhibitors with immediate patient counseling. France's pharmacy-level substitution rules under EMA interchangeability guidance are accelerating biosimilar uptake through this channel.
- Online Pharmacy:Digital platforms enable chronic therapy refills with direct-to-patient logistics. Brazil's expanding cold-chain infrastructure is extending biologic delivery reach beyond traditional metropolitan centers.
- Direct Sales:Manufacturer-to-institution contracting supports high-value biologic agreements.
- Wholesale:Distributor networks manage inventory and distribution for broad pharmacy coverage.
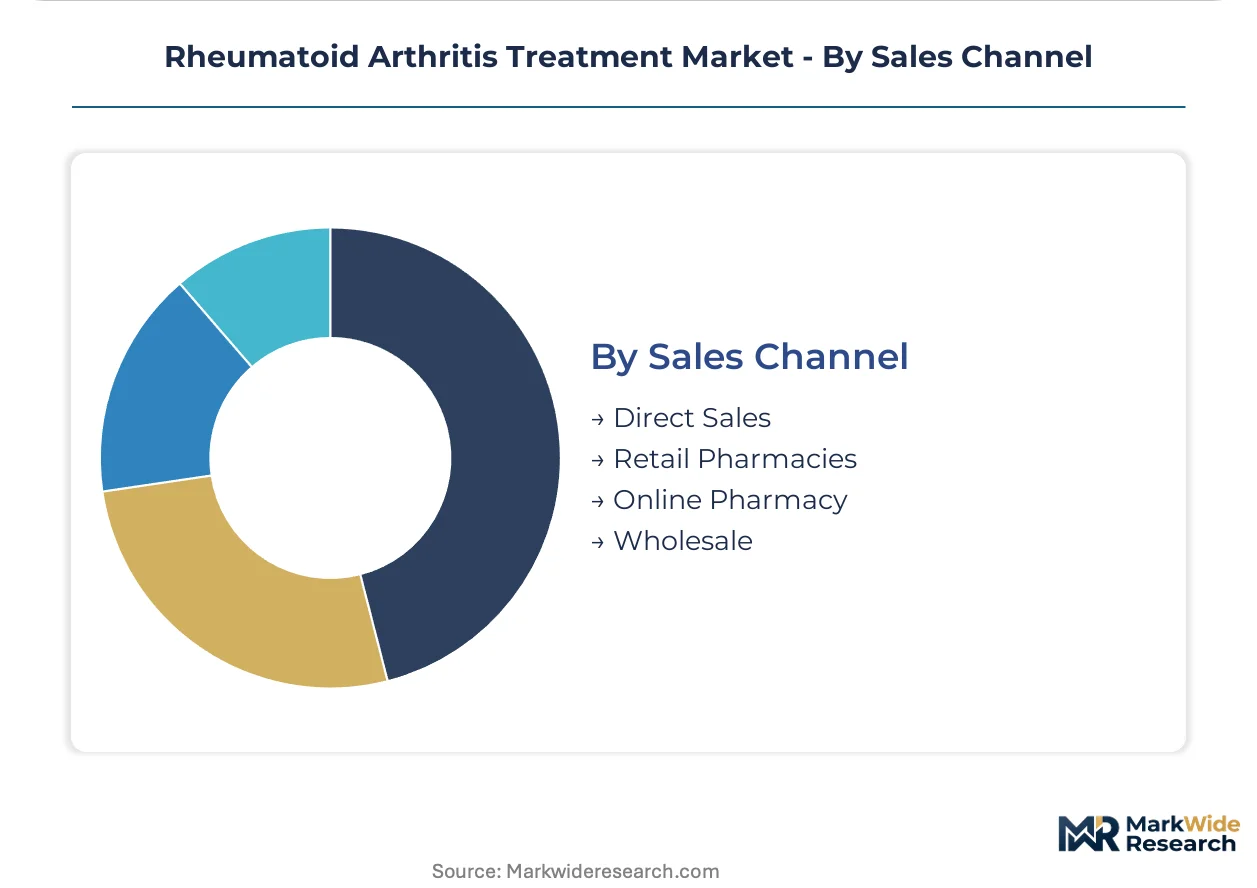
Retail pharmacies anchor volume throughput; online pharmacy is scaling fastest as logistics networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic production concentrates in Switzerland and the United States while consumption spreads across hospital networks in Germany and infusion centers in India. Cold-chain distribution capabilities now determine market access more than manufacturing origin.
United States
Hospital infusion centers in Texas and Florida are expanding biologic administration capacity to capture specialty pharmacy revenue streams. The FDA's breakthrough therapy designation accelerates approval timelines for novel JAK inhibitors. Massachusetts academic medical centers are adopting bispecific antibody constructs for refractory patient cohorts in investigator-initiated trials.
Germany
Rheumatology departments in Bavaria and North Rhine-Westphalia defend procedural economics against site-of-care migration to home care. EMA-enforced interchangeability rulings trigger automatic biosimilar substitution at pharmacy level. Berlin's hospital procurement consortia command bulk purchasing leverage for TNF-alpha inhibitors.
India
Domestic manufacturing of biosimilars is scaling under the PLI scheme incentives with contract development investments from European originators. CDSCO alignment with ICH Q5A viral safety guidelines creates harmonized barriers for non-compliant manufacturers. Maharashtra's tertiary care centers now receive validated cold-chain distribution for biologic therapies.
Japan
PMDA batch-specific immunogenicity testing requirements elevate analytical development costs for biosimilar entrants. METI production incentives support domestic bioreactor capacity expansion. Osaka-Kobe pharmaceutical clusters are expanding bioanalytical assay capacity to absorb regional demand.
Brazil
ANVISA regulatory convergence with FDA standards enables earlier commercial access for novel therapies. Cold-chain infrastructure maturation extends biologic delivery reach beyond São Paulo and Rio de Janeiro to tertiary care centers in Minas Gerais. Specialty pharmacy partnerships with home care nursing networks are capturing volume from hospital-based administration.
Rheumatoid Arthritis Treatment Market Competitive Environment
Capital-heavy biologic manufacturers compete with asset-light small-molecule specialists across the rheumatoid arthritis treatment landscape. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with sterile bioreactor networks, mid-cap autoimmune specialists with JAK inhibitor portfolios, and emerging biosimilar producers with cost-arbitrage manufacturing. Consolidation pressure intensifies as outcome-based contracting rewards therapies with durable clinical outcomes. Dominant competitive moves include subcutaneous formulation development to unlock home care channels and real-world evidence integration to satisfy EMA post-authorization requirements.
Among integrated pharmaceutical conglomerates, AbbVie Inc., Pfizer Inc., and Novartis AG occupy positions that exemplify divergent strategic archetypes. AbbVie Inc. anchors the TNF-alpha inhibition legacy segment through deep R&D intensity in biologic manufacturing. Pfizer Inc. exemplifies the oral formulation leadership model with JAK inhibitor specialization that displaces infusion dependency. Novartis AG represents the autoimmune expansion pathway through IL-17 and IL-23 pathway dominance. Each structure reflects a distinct bet on where prescribing convenience versus clinical efficacy will concentrate future value capture.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Regeneron Pharmaceuticals Inc. |
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| UCB S.A. |
| Amgen Inc. |
| Others |
Value Chain & Pricing Dynamics
Subcutaneous pen-device formulation migration simultaneously compresses infusion-center overhead costs and concentrates manufacturing scale among biologics specialists with sterile fill-finish capabilities. This dual transformation rewards originators with validated cold-chain networks while squeezing margins for legacy intravenous-dependent portfolios.
Pricing Analysis
Margin tightening in originator biologics reflects EMA-enforced biosimilar interchangeability rulings across Germany and France. Three-tier pricing structure across originator premium, biosimilar standard, and emerging-economy tiers separates patient access levels by regulatory jurisdiction and reimbursement intensity. Cost-down pressure on TNF-alpha inhibitors accelerates as automatic pharmacy substitution protocols erode brand loyalty. Hospital procurement consortia exhibit lowest price sensitivity; retail pharmacy channels face highest substitution-driven compression.
Supply Chain Analysis
Plasma-derived immunoglobulin feedstock rests on United States and European donor collection networks with cyclical availability constraints. Monoclonal antibody production draws from Swiss and Irish contract manufacturing organizations with multi-product bioreactor suites. Single-source vulnerability concentrates in specialty reagent suppliers for batch-specific immunogenicity testing. Distribution runs through validated cold-chain logistics partners serving hospital infusion centers and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rheumatoid arthritis treatment landscape is becoming a vertical-integration race, with sterile bioreactor capacity and bioanalytical assay development emerging as the decisive upstream levers for sustainable margin defense.
For Market Incumbents: Deepen captive control over fill-finish manufacturing to insulate against contract manufacturing organization capacity constraints and biosimilar price erosion. Anchor defensive positioning through real-world evidence generation for EMA post-authorization requirements, creating differentiation barriers against emerging biosimilar entrants with inferior registry outcomes. For New Entrants and Emerging Players: Begin with oral JAK inhibitor formulations targeting outpatient clinic channels in India and Brazil, where cold-chain infrastructure gaps disadvantage infusion-dependent biologics. Capture volume through specialty pharmacy partnerships that bypass hospital procurement consortia with entrenched incumbent relationships. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap autoimmune specialists possessing validated subcutaneous formulation platforms given payer-mandated site-of-care migration toward home administration. Long-term viability hinges on backward integration into bioreactor manufacturing and bioanalytical assay development capabilities. Watch FDA breakthrough therapy designation velocity as the signal indicating which pipeline assets will compress competitive timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Pen-device platforms unlock home care channels and displace hospital infusion dependency. |
| Real-World Evidence Integration | EMA's DARWIN EU network enables post-authorization differentiation through superior registry outcomes. |
| Bioanalytical Assay Scale-Up | Batch-specific immunogenicity testing capacity satisfies PMDA and FDA multi-region launch requirements. |
| Cold-Chain Infrastructure Expansion | Validated distribution networks extend biologic access to tertiary care centers in Maharashtra and Minas Gerais. |
| Biosimilar Manufacturing Investment | India's PLI scheme incentives attract contract development partnerships from European originators seeking cost arbitrage. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulary directors, hospital procurement managers, payer access specialists, and regulatory affairs leads combined with FDA submissions, EMA centralized marketing authorization records, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulated market sizing across segments.
Data-stream reconciliation integrated dosage form adoption curves, administration route migration patterns, and regional regulatory cluster dynamics across the projection horizon. CAGRs derived from treatment line progression modeling, biosimilar penetration scenario analysis, and site-of-care shift elasticity estimates. Forecast inputs incorporated cold-chain infrastructure maturity indices and payer step-therapy protocol expansion rates.
Regulatory approval delays, biosimilar interchangeability ruling reversals, and plasma collection cycle disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on therapy persistence rates and reimbursement stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market