
 Bevacizumab Market | 2026-2036
Bevacizumab Market Size, Share, and Industry Trends Forecast 2026-2036
Bevacizumab Market Analysis
A capital-intensity divergence between large-scale biologics manufacturers and emerging biosimilar specialists is reorganizing competitive dynamics in bevacizumab supply. Genentech leverages its originator infrastructure and clinical data archives to sustain premium positioning in regulated markets. Celltrion anchors its expansion strategy on high-volume biosimilar production for cost-sensitive hospital systems.
Bevacizumab is a recombinant humanized monoclonal immunoglobulin G1 antibody that binds vascular endothelial growth factor-A to inhibit angiogenesis, manufactured through mammalian cell culture in Chinese hamster ovary expression systems for intravenous oncology administration. The biosimilars segment is capturing volume leadership as patent cliffs and regulatory harmonization erode originator exclusivity, while the lung cancer indication commands concentrated R&D investment due to combination therapy expansion with immune checkpoint inhibitors. Intravenous administration dominates clinical practice but subcutaneous formulations are gaining formulary attention for outpatient efficiency.
FDA, EMA, and WHO prequalification standards govern biosimilar interchangeability, manufacturing consistency, and immunogenicity surveillance requirements that determine market access timelines. The EU Green Deal pharmaceutical sustainability criteria and US IRA drug pricing provisions are reshaping procurement evaluation frameworks for hospital formularies. Stakeholders must monitor evolving interchangeability legislation and real-world evidence requirements that will determine substitution rates and pricing power across national reimbursement systems.
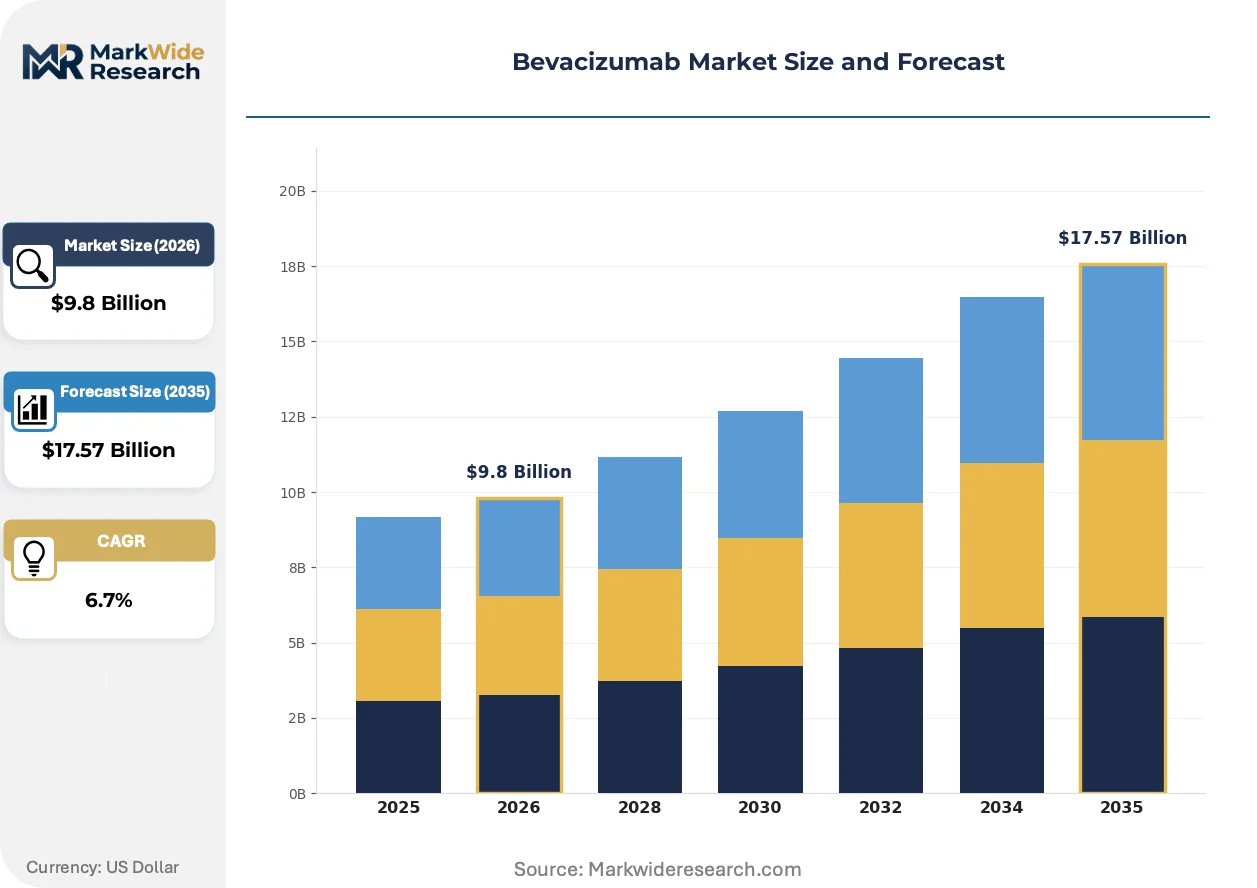
Market Dynamics
Patent cliff acceleration combined with EMA and FDA biosimilar pathway harmonization is compressing originator exclusivity windows and redistributing market power toward high-volume manufacturing specialists.
Growth Catalysts
- Combination therapy expansion:Immune checkpoint inhibitor pairing with anti-VEGF agents in non-small cell lung cancer protocols is extending treatment lines and duration. Oncology clinics in the United States and Germany are expanding infusion capacity to accommodate these regimens.
- EMA centralized biosimilar approval:Mutual recognition procedures are accelerating market entry across 27 member states from a single regulatory filing. This framework reduces duplication costs for biosimilar developers targeting European hospital procurement.
- Subcutaneous formulation development:Outpatient administration efficiency is driving formulary preference for alternative delivery routes. Japanese hospital systems are piloting these protocols to reduce chair time in oncology day units.
Market Restraints
- Mammalian cell culture input concentration:Chinese hamster ovary cell line supply and media component sourcing cluster with limited qualified suppliers. Disruption risks concentrate in single-source bioreactor equipment and serum-free media formulations.
- Immunogenicity surveillance burden:Post-market pharmacovigilance requirements for biosimilars demand extended patient monitoring databases. EMA and FDA adverse event reporting thresholds create compliance cost barriers for smaller manufacturers.
- Intravenous infusion infrastructure dependency:Clinical practice lock-in to hospital-based administration limits uptake of alternative delivery innovations. Capital investment in infusion chair capacity creates switching friction for outpatient models.
Strategic Opportunities
- Japanese biosimilar substitution policy:Ministry of Health, Labour and Welfare interchangeability guidelines are expanding pharmacist-level substitution authority. This regulatory tailwind accelerates volume capture for approved biosimilars in hospital formularies.
- Real-world evidence integration:Electronic health record linkage with oncology outcomes registries is enabling post-approval efficacy differentiation. Manufacturers investing in data infrastructure can support payer contracting with outcome guarantees.
- Biologic-digital therapeutic convergence:Patient monitoring apps paired with anti-VEGF therapy are creating adherence and dosing optimization platforms. This combination opens reimbursement dialogue with integrated delivery networks seeking total cost management.
Industry Challenges
- Process analytical technology implementation:Continuous manufacturing validation requires specialized bioprocess engineering talent scarce in emerging biosimilar firms. FDA quality by design expectations demand workforce upskilling that outpaces training program output.
- Reference product drift management:Originators modifying manufacturing processes create immunogenicity profile uncertainty for biosimilar comparability. Demonstrating equivalence amid evolving reference standards consumes analytical resources and extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bevacizumab Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avastin, Biosimilars, Monoclonal Antibodies, Combination Therapies Indication: Colorectal Cancer, Lung Cancer, Ovarian Cancer, Renal Cell Carcinoma Administration Mode: Intravenous, Subcutaneous, Oral, Combination Administration End User: Hospitals, Oncology Clinics, Research Institutions, Home Care |
| Companies Covered | Genentech, Amgen, Pfizer Inc, Celltrion, Samsung Bioepis, Biocon, Mylan, Teva Pharmaceutical Industries, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bevacizumab Market Emerging Trajectories
Bioprocess intensification and regulatory science advances are compressing development timelines while digital integration is reshaping how therapy value is demonstrated to payers and prescribers.
Continuous bioprocessing technology is displacing traditional fed-batch manufacturing in bevacizumab production. Contract development and manufacturing organizations in Ireland and Singapore are installing perfusion-based bioreactor systems to achieve higher cell densities and reduced facility footprints. This intensification is displacing capital-heavy stainless-steel infrastructure with single-use flexible capacity that responds faster to demand fluctuations.
The EU Green Deal pharmaceutical sustainability criteria are embedding carbon footprint thresholds into hospital procurement scoring. EMA guidance on environmental risk assessments now requires lifecycle analysis submission for marketing authorization renewals. German and Dutch hospital purchasing coalitions are prioritizing suppliers with verified renewable energy sourcing in their tender evaluations.
Site-of-care migration is compressing hospital infusion center dependence as oncology practices acquire in-house biologic administration capabilities. United States community oncology networks are investing in pharmacy licensure and nursing infrastructure to capture margin from specialty drug dispensing. This channel shift is most visible in Medicare Advantage populations where capitated payment models reward care setting optimization.
Bevacizumab Market Segmentation
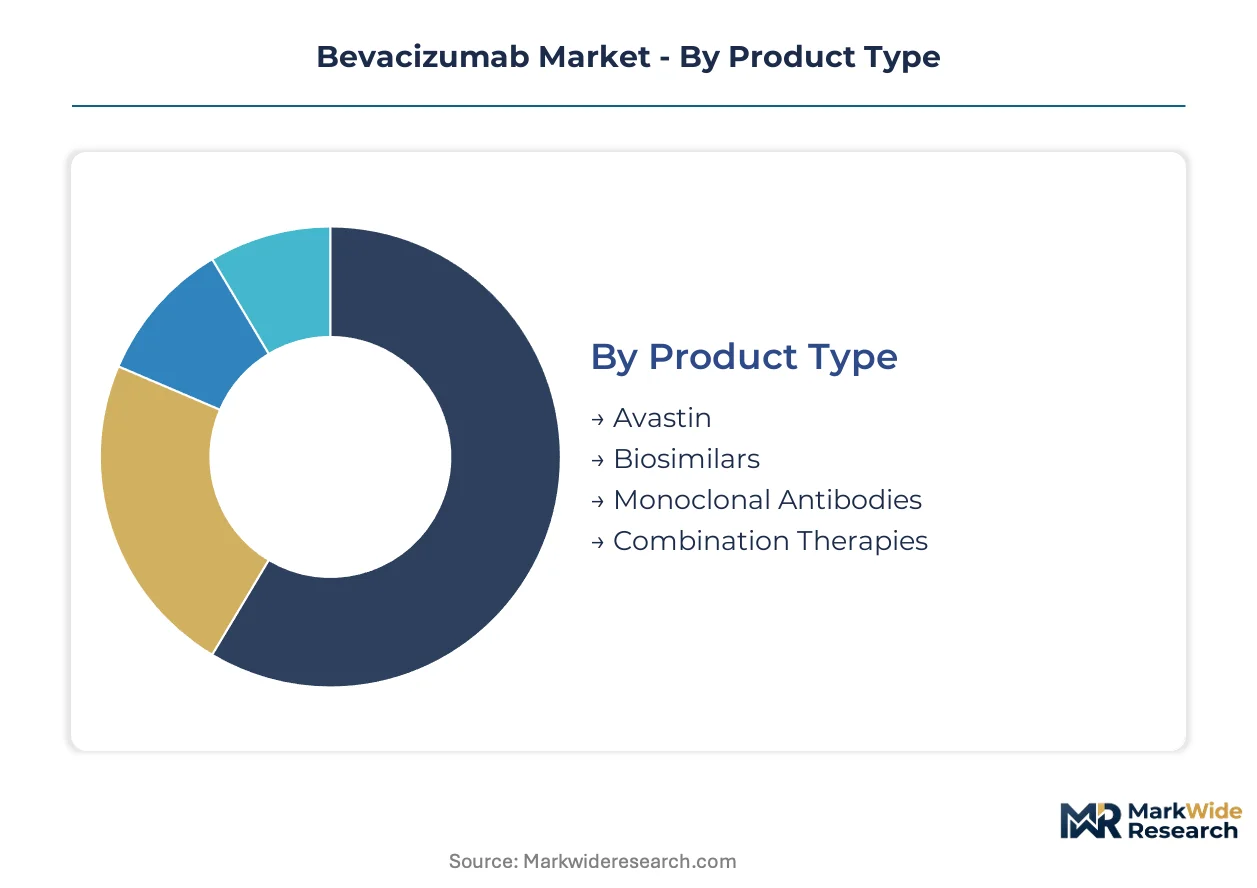
Bevacizumab market segmentation reveals how value migrates across therapeutic formats, clinical settings, and delivery innovations. Understanding these divisions exposes where manufacturing scale, regulatory approval, and reimbursement access concentrate competitive advantage.
Product Type:
Margin pools concentrate in biosimilar production where volume scale offsets price compression, while originator maintenance therapy sustains premium capture in resistant markets.
- Avastin:The originator monoclonal antibody maintains formulation consistency through Genentech's CHO cell line heritage and legacy clinical trial archives. Demand concentrates in United States academic medical centers where prior authorization frameworks favor established efficacy profiles and originator immunogenicity surveillance data.
- Biosimilars:Celltrion, Amgen, and Pfizer versions achieve pharmacokinetic equivalence through analytical comparability studies and switching trial designs. German hospital purchasing coalitions and Japan's MHLW substitution pathways are driving fastest volume migration as procurement scoring prioritizes cost per quality-adjusted life year.
- Monoclonal Antibodies:Recombinant IgG1 constructs dominate manufacturing investment across mammalian expression platforms.
- Combination Therapies:Anti-VEGF pairing with pembrolizumab or atezolizumab extends treatment duration in NSCLC protocols.
Avastin holds installed capacity in reference product supply chains. Biosimilars is rotating up the share rankings through EMA centralized approvals and US FDA interchangeability designations.
Indication:
Clinical trial investment and regulatory label expansion concentrate in tumor types where anti-VEGF mechanism demonstrates durable progression-free survival extension.
- Colorectal Cancer:First-line metastatic protocols combine bevacizumab with FOLFOX or FOLFIRI chemotherapy backbones. United States community oncology networks and German statutory health insurance formularies prioritize this indication for maintenance therapy duration.
- Lung Cancer:Non-small cell histologies drive combination therapy innovation with PD-1/PD-L1 inhibitors in KEYNOTE and IMpower trial lineages. Japanese lung cancer centers and US National Cancer Institute-designated centers are expanding infusion capacity for these resource-intensive regimens.
- Ovarian Cancer:Platinum-resistant recurrent settings anchor bevacizumab use with PARP inhibitor sequencing.
- Renal Cell Carcinoma:Tyrosine kinase inhibitor pairing dominates this indication's therapeutic algorithm.
Colorectal Cancer maintains the deepest prescriber familiarity. Lung Cancer is gaining share fastest through immunotherapy combination protocols.
Administration Mode:
Site-of-care economics and nursing labor efficiency are redistributing preference between hospital-based infusion and outpatient delivery models.
- Intravenous:Weight-based dosing over 30-90 minute infusion cycles requires pharmacy compounding and oncology nursing supervision. Hospital systems in Germany and Japan maintain this as standard-of-care due to reimbursement coding that bundles administration with facility fees.
- Subcutaneous:Fixed-dose formulations reduce chair time and enable community oncology practice administration outside hospital outpatient departments. US Medicare Advantage capitated contracts and Dutch hospital substitution policies are piloting these protocols for cost setting optimization.
- Oral:No approved bevacizumab oral formulation exists; research programs investigate VEGF pathway small molecules.
- Combination Administration:Sequential or concurrent delivery with cytotoxic agents requires protocol standardization.
Intravenous holds installed capacity in hospital infrastructure. Subcutaneous is rotating up the share rankings through formulary preference for outpatient efficiency.
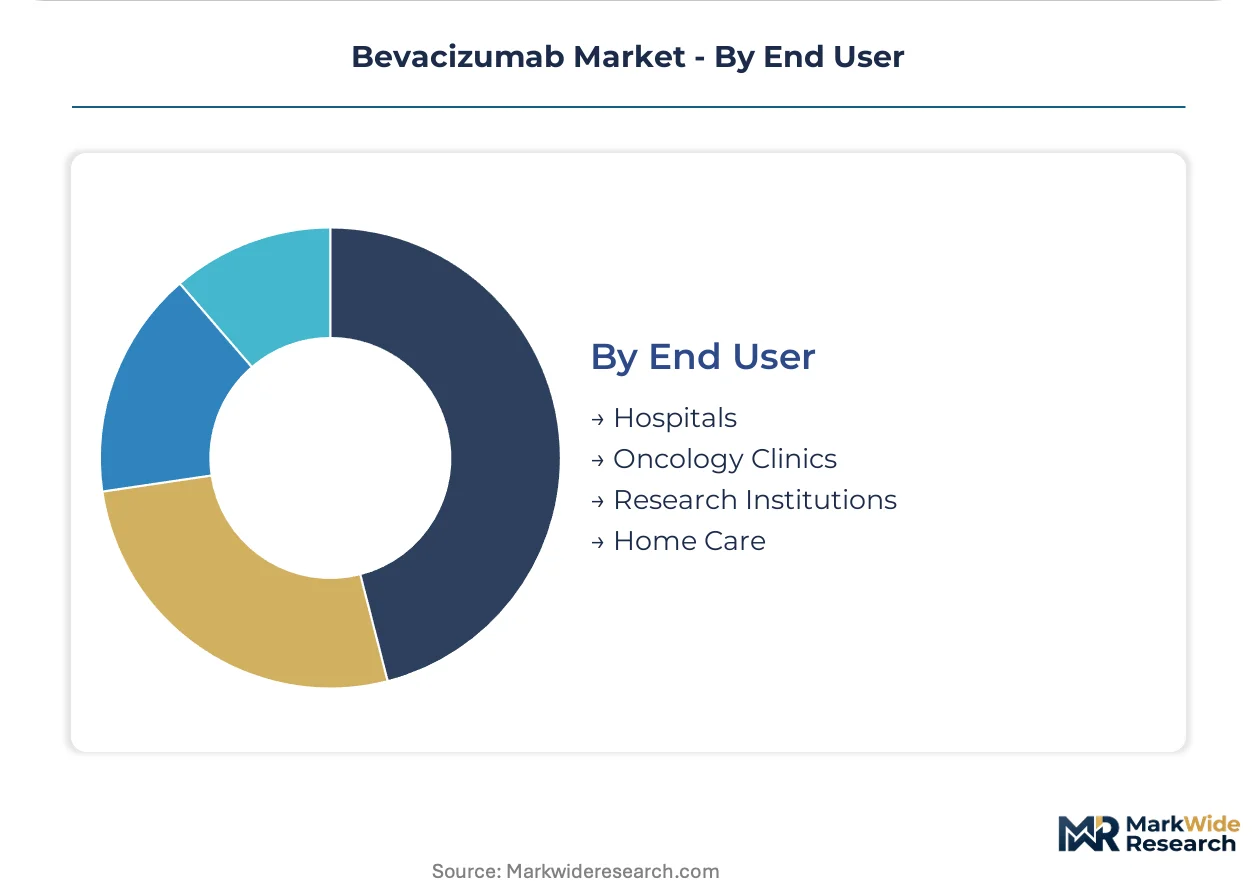
End User:
Reimbursement channel design and care setting policy determine where biologic acquisition margin concentrates across institutional purchasers.
- Hospitals:Inpatient and outpatient oncology departments capture 340B drug pricing discounts and bundled payment advantages in US markets. German DRG-based hospital financing and Japan's diagnosis procedure combination reimbursement sustain volume concentration in acute care settings.
- Oncology Clinics:Community-based practices in the United States are acquiring in-house biologic administration capabilities through pharmacy licensure and nursing infrastructure investment. These sites capture specialty drug dispensing margin under Medicare Part B and commercial payer contracts.
- Research Institutions:Academic medical centers anchor investigator-initiated trials and real-world evidence generation.
- Home Care:Limited bevacizumab administration occurs outside clinical settings due to infusion monitoring requirements.
Hospitals hold installed capacity in reimbursement infrastructure. Oncology Clinics is rotating up the share rankings through site-of-care migration and specialty pharmacy integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across national reimbursement systems, with Japanese and German hospital buyers exhibiting high price sensitivity through biosimilar substitution frameworks while United States academic medical centers maintain originator preference through prior authorization lock-in.
United States
Medicare Part B reimbursement and 340B drug pricing programs concentrate hospital purchasing power in oncology networks. FDA interchangeability guidelines and IRA price negotiation provisions reshape procurement evaluation timelines. Community oncology practices in Florida and Texas expand in-house biologic administration to capture specialty pharmacy margin.
Germany
Statutory health insurance formularies and hospital DRG financing accelerate biosimilar volume migration in cost-sensitive regions. EMA centralized approval pathways enable rapid market entry across federal states. The Rhine-Ruhr metropolitan cluster anchors high-volume manufacturing investment for European hospital supply.
Japan
Ministry of Health, Labour and Welfare substitution guidelines expand pharmacist-level biosimilar authority in acute care settings. Diagnosis procedure combination reimbursement bundles sustain hospital-based administration preference. The Kanto region around Tokyo concentrates lung cancer combination therapy expansion with immune checkpoint inhibitors.
India
CDSCO biosimilar approval pathways and government hospital tendering drive cost-optimized procurement in oncology departments. National health mission coverage expansion extends biologic access to tier-two cities. Hyderabad and Bangalore biotech clusters anchor contract manufacturing investment for export markets.
United Kingdom
NICE cost-effectiveness thresholds and NHS England commissioning frameworks prioritize biosimilar switching protocols in cancer alliances. MHRA post-Brexit regulatory autonomy enables tailored approval timelines. The Greater Manchester and London cancer vanguard sites pilot real-world evidence collection for outcome-based contracting.
Bevacizumab Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the bevacizumab supply base. The market structure concentrates around originator heritage manufacturers and high-volume biosimilar specialists, with contract manufacturing organizations filling capacity gaps. Three archetypes dominate: legacy biologics innovators with clinical data archives, Asian biosimilar scale players with mammalian cell culture expertise, and integrated pharmaceutical conglomerates with hospital contracting breadth. Competitive moves center on manufacturing capacity expansion in low-cost jurisdictions and strategic partnerships for real-world evidence generation.
Within the originator heritage tier, Genentech anchors premium positioning through legacy clinical trial archives and reference product supply continuity. Among biosimilar scale specialists, Celltrion and Samsung Bioepis exemplify high-volume mammalian cell culture production for cost-sensitive hospital procurement. These players occupy positions across the pricing spectrum, with geography and reimbursement channel determining volume capture.
| Leading Market Players |
|---|
| Genentech |
| Amgen |
| Pfizer Inc |
| Celltrion |
| Samsung Bioepis |
| Biocon |
| Mylan |
| Teva Pharmaceutical Industries |
| Boehringer Ingelheim |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German hospital purchasing coalitions and high-volume biosimilar manufacturers lock in multi-year supply access while anchoring price visibility against volatile mammalian cell culture input costs. These arrangements concentrate procurement power in cost-sensitive European markets while insulating manufacturers from spot-market media component fluctuations.
Pricing Analysis
After-sales revenue from patient monitoring and adherence platforms drives lifetime value capture beyond the initial biologic sale. Three-tier pricing structure across premium originator, standard biosimilar, and economy tender-awarded tiers dominates hospital procurement. Price differentiation hinges on FDA interchangeability designation and volume commitment scale. Cost compression in the economy tier intensifies as Indian and Korean manufacturers compete for government hospital tenders. German statutory health insurance formularies exhibit highest price sensitivity; United States academic medical centers maintain lowest sensitivity due to prior authorization lock-in.
Supply Chain Analysis
Strategic stockpiling of Chinese hamster ovary cell lines and serum-free media formulations buffers against single-source bioreactor equipment vulnerabilities. Manufacturing concentrates in South Korea, Ireland, and Singapore where contract development organizations anchor perfusion-based capacity. Raw material dependencies include recombinant protein A resins, single-use bioreactor bags, and pharmaceutical-grade glucose. Tariff exposure on bioprocessing equipment sourced from Germany threatens cost structures. Distribution runs through hospital-centered procurement networks with limited direct-to-clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar pathway harmonization between FDA and EMA is compressing development timelines and redistributing market power toward manufacturing scale specialists. This regulatory inflection creates asymmetric opportunity across incumbent and entrant archetypes.
For Market Incumbents: Fortify reference product supply continuity through captive CHO cell line banking and legacy clinical data archive monetization. Invest in continuous bioprocessing validation to defend against emerging high-volume specialists. Prioritize real-world evidence infrastructure to support payer contracting with outcome guarantees.
For New Entrants and Emerging Players: Anchor in Japanese biosimilar substitution protocols where MHLW pharmacist-level authority accelerates volume capture. Target cost-sensitive German hospital purchasing coalitions with EMA centralized approval leverage. Deploy site-of-care partnership models to bypass entrenched hospital infusion infrastructure.
For Investors and Strategic Acquirers: Mid-scale CDMOs with perfusion bioreactor expertise and established FDA quality by design track records present asymmetric upside. Long-term viability rests on manufacturing flexibility across originator and biosimilar contract portfolios. Watch FDA interchangeability designation velocity as the inflection signal for substitution rate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Scale-Up | Perfusion-based manufacturing reduces facility footprints and accelerates demand response in CDMO hubs. |
| Real-World Evidence Infrastructure | Electronic health record linkage enables outcome-based contracting with Medicare Advantage networks. |
| Subcutaneous Formulation Development | Fixed-dose delivery captures site-of-care migration toward community oncology practices. |
| EMA Centralized Approval Pathway | Mutual recognition procedures reduce duplication costs across 27 member state hospital tenders. |
| Biologic-Digital Therapeutic Convergence | Patient monitoring apps create adherence platforms for integrated delivery network reimbursement dialogue. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up treatment line modeling and top-down reimbursement framework analysis were triangulated to anchor volume estimates.
Across the analysis window, forecasts were derived from segmented modeling across indication, product type, administration mode, and regional regulatory cluster. CAGRs were computed from fitted trend extrapolation with cross-validation against historical biosimilar penetration curves. Key inputs included EMA approval velocity, Japanese substitution policy implementation timelines, and US Medicare Part B reimbursement rate trajectories.
Underlying assumptions cover biosimilar interchangeability legislative progression and mammalian cell culture input cost stability, with deviation risk concentrated in reference product manufacturing drift and immunogenicity surveillance threshold changes. Practitioners should keep alternative scenarios live as FDA quality by design expectation evolution and EU Green Deal pharmaceutical sustainability criteria reshape procurement scoring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Global Anticoccidial Drugs Market