
 Intranasal Migraine Drugs Market | 2026-2036
Intranasal Migraine Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Intranasal Migraine Drugs Market Foresight
Subscription-based patient support programs is recalibrating how pharmaceutical companies monetize intranasal migraine therapies beyond the initial prescription fill. Pfizer Inc. leverages its established neurology infrastructure to sustain commercial traction across hospital and retail channels. Eli Lilly and Company differentiates through biologic-adjacent positioning of its intranasal portfolio. Impel Pharmaceuticals Inc. specializes in precision olfactory delivery technology that extends therapeutic onset speed.
Intranasal migraine drugs comprise serotonergic triptans and ergot alkaloids formulated for absorption across the nasal mucosa, with particle size distribution and viscosity parameters governing bioavailability and onset kinetics. Liquid delivery systems dominate current prescribing patterns due to established manufacturing scale and familiar administration protocols. Powder delivery platforms represent the fastest-expanding technology segment as patients seek portable, preservative-free alternatives. Hospital procurement of dihydroergotamine intranasal formulations anchors the highest-margin channel within acute care settings.
The FDA oversees New Drug Application requirements for intranasal formulations while the EMA enforces centralized marketing authorization standards across European member states, with both agencies tightening pharmacovigilance expectations for CNS-active nasal sprays. The IRA's Medicare price negotiation provisions reshape commercial forecasting for branded intranasal therapies in the United States. Stakeholders must monitor evolving bioequivalence standards for complex nasal generics and calibrate portfolio investments between liquid and powder delivery modalities.
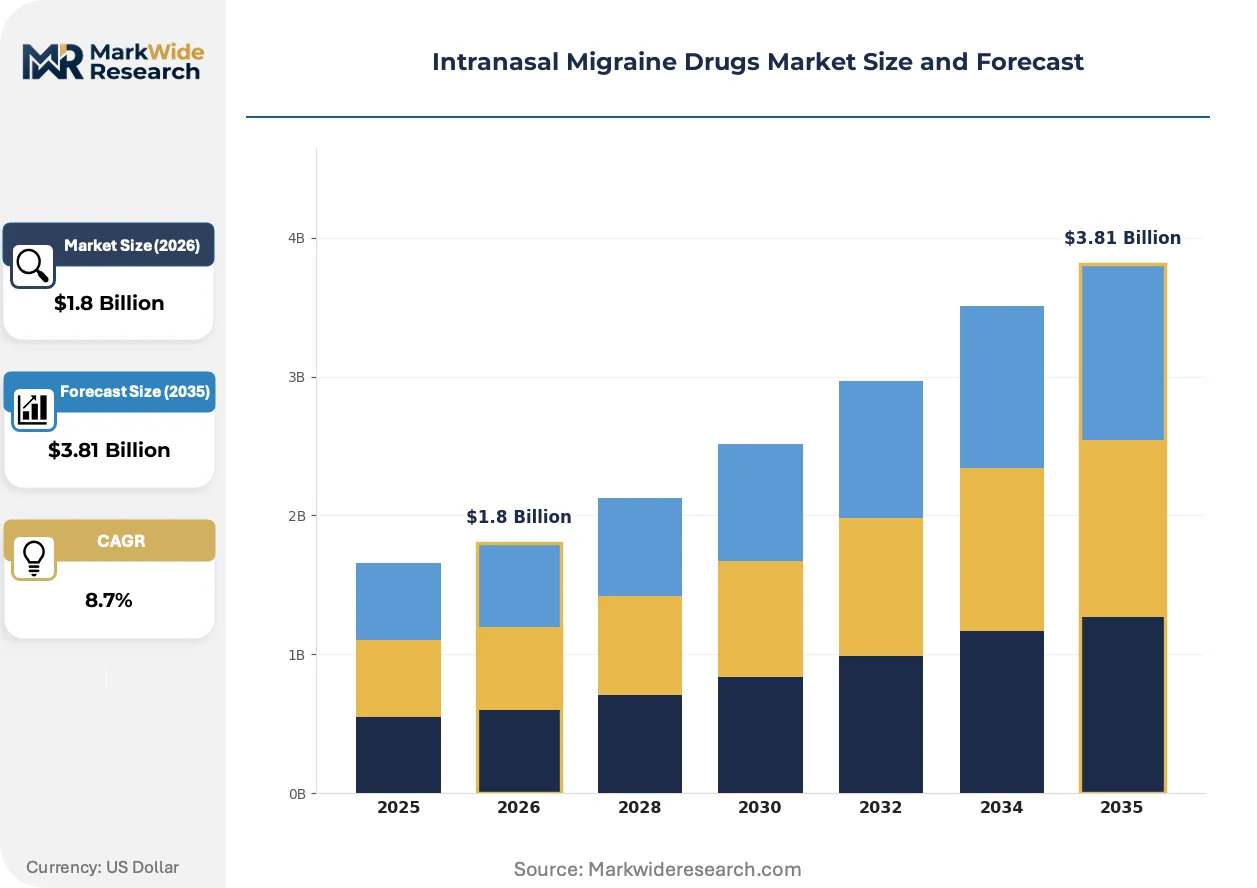
Market Dynamics
The FDA's 505(b)(2) regulatory pathway is compressing development timelines for generic intranasal formulations, forcing branded manufacturers to defend market position through delivery technology differentiation rather than composition patents alone.
Growth Catalysts
- Streamlined FDA Approval:The 505(b)(2) pathway reduces clinical burden for intranasal generics by referencing existing safety data, accelerating market entry for alternative delivery formats.
- Hospital Formulary Expansion:Acute care settings in the United States are adding dihydroergotamine intranasal options to emergency department protocols, creating institutional prescribing momentum.
- Precision Olfactory Targeting:Advances in particle engineering now enable direct trigeminal nerve activation, compressing therapeutic onset below oral triptan benchmarks.
Market Restraints
- API Supply Concentration:Dihydroergotamine mesylate production concentrates among European contract manufacturers, exposing formulators to single-source dependency risk.
- Medicare Price Negotiation:The IRA's cost-control provisions compress revenue forecasting for branded intranasal therapies reaching statutory eligibility thresholds.
- Oral Generic Substitution:Low-cost sumatriptan tablets continue displacing intranasal prescriptions in cost-sensitive payer environments despite inferior onset kinetics.
Strategic Opportunities
- Preservative-Free Powder Platforms:Lyophilized intranasal formats address patient sensitivity to benzalkonium chloride preservatives in liquid formulations, opening differentiation in retail pharmacy channels.
- Subscription Support Programs:Recurring revenue models for adherence monitoring and acute rescue dosing are capturing lifetime value beyond initial prescription capture.
- European Centralized Authorization:EMA marketing authorization procedures enable simultaneous multi-country launch, reducing fragmentation costs relative to national filing routes.
Industry Challenges
- Bioequivalence Complexity:Nasal spray deposition patterns and regional absorption variability complicate generic approval under evolving FDA guidance for locally-acting products.
- Device Manufacturing Scale-Up:Precision powder delivery systems require specialized filling equipment with extended validation timelines, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intranasal Migraine Drugs Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sumatriptan, Zolmitriptan, Dihydroergotamine, Others Technology: Liquid Delivery, Powder Delivery, MDPI, Others End User: Hospitals, Clinics, At-Home Users, Pharmacies Form: Sprays, Solutions, Inhalable Powders, Others |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Novartis AG, Dr. Reddy's Laboratories Ltd., Cipla Limited, Tonix Medicines, Inc., Impel Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intranasal Migraine Drugs Market Shifts & Advancements
Delivery modality innovation is fragmenting competitive advantage away from active pharmaceutical ingredients toward device engineering and patient experience design, with three convergent developments reshaping product development priorities.
Portable powder delivery systems are decentralizing acute migraine treatment from clinical settings to workplace and travel environments. Patients managing episodic attacks now prioritize discreet, refrigeration-free formats over traditional liquid sprays requiring preservative stabilization. This shift is compressing retail pharmacy preference toward unit-dose powder devices that eliminate priming requirements and reduce dosing variability.
The IRA's Medicare price negotiation provisions are forcing branded manufacturers to accelerate lifecycle management strategies. Formulators now prioritize 505(b)(2) eligible improvements—altered particle size distributions, modified viscosity profiles—to extend exclusivity periods ahead of statutory price-setting eligibility. United States commercial teams are responding by concentrating field resources on specialist prescribers less sensitive to formulary tier shifts.
Hospital procurement committees are unbundling acute migraine therapy from bundled neurological service contracts. Separate line-item negotiation for intranasal dihydroergotamine is enabling pharmacy directors to optimize emergency department stocking independent of bundled vendor relationships. This pattern is most visible in United States health systems consolidating formulary governance under centralized pharmacy and therapeutics committees.
Intranasal Migraine Drugs Market Segmentation
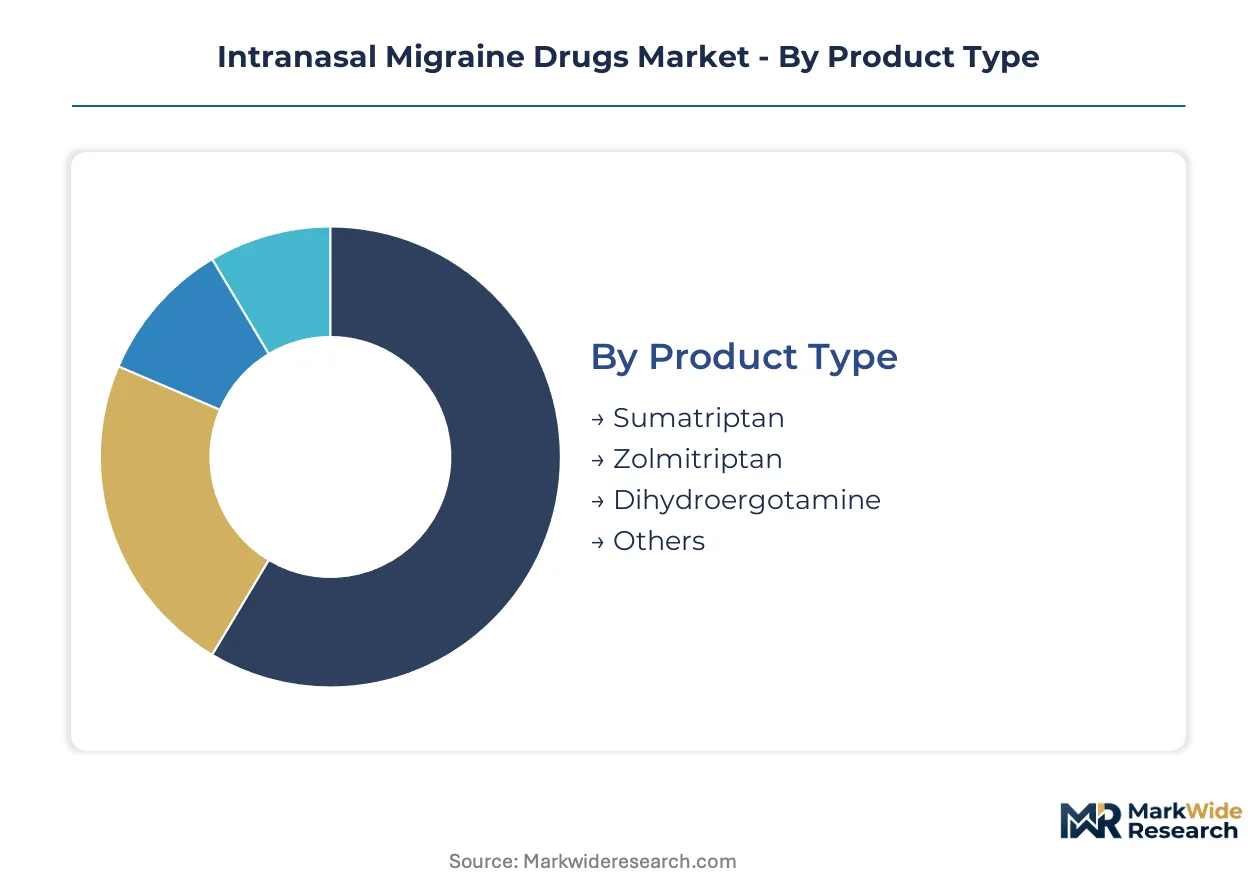
Intranasal migraine therapies fragment across four distinct taxonomies that determine regulatory pathway complexity and commercial access strategy. Each segmentation axis carries specific FDA and EMA filing requirements that reshape portfolio investment priorities for formulation developers.
Product Type:
FDA 505(b)(2) eligibility varies sharply across this category, with established reference drugs accelerating approval timelines for some molecules while others require full NDA submissions.
- Sumatriptan:The first-generation triptan dominates prescription volume through multiple generic intranasal entrants. Hospital formularies in the United States favor this molecule for emergency department protocols due to extensive safety databases and rapid onset kinetics.
- Dihydroergotamine:Ergot alkaloid formulations command premium positioning in acute care settings where oral triptan failure rates climb. Supply concentration among European API manufacturers creates procurement vulnerability for United States hospital systems dependent on just-in-time inventory.
- Zolmitriptan:Second-generation triptan with superior central nervous system penetration compared to sumatriptan equivalents.
- Others:Emerging molecules including novel serotonin receptor modulators and calcitonin gene-related peptide antagonists in intranasal development.
Dihydroergotamine sits at the top of the volume ranking, with Others climbing the fastest as pipeline candidates advance through Phase III programs.
Technology:
Manufacturing capital intensity separates these platforms, with liquid systems leveraging existing infrastructure while powder formats demand specialized lyophilization and filling equipment.
- Liquid Delivery:Established aqueous formulations with benzalkonium chloride preservation dominate current prescribing. United States retail pharmacies stock these products most heavily due to familiar patient counseling protocols and established reimbursement codes.
- Powder Delivery:Lyophilized unit-dose formats eliminate refrigeration requirements and preservative sensitivity concerns. Workplace and travel environments drive fastest expansion here as patients prioritize portability over clinical setting administration.
- MDPI:Metered-dose pressurized inhalers adapted for nasal deposition with precise particle engineering.
- Others:Nasal gels, mucoadhesive films, and emerging electromechanical atomization platforms.
Liquid Delivery maintains volume leadership, though Powder Delivery gains share fastest as device engineering investments mature.
End User:
Procurement authority concentration determines pricing leverage, with centralized hospital purchasing contrasting against fragmented at-home consumer decision-making.
- Hospitals:Emergency departments and neurology units anchor the highest-margin channel through dihydroergotamine stocking protocols. United States health systems consolidating under pharmacy and therapeutics committees unbundle migraine therapy from bundled neurological service contracts.
- At-Home Users:Direct-to-patient subscription models capture lifetime value beyond initial prescription through adherence monitoring and rescue dosing programs. This segment shows steepest expansion trajectory as telehealth prescribing normalizes post-pandemic.
- Clinics:Outpatient neurology and headache specialist practices with sample-driven prescribing patterns.
- Pharmacies:Retail dispensing locations including independent and chain operators with formulary tier sensitivity.
Hospitals lead absolute volume, while At-Home Users expand most quickly through digital health integration.
Form:
Patient handling complexity and dosing reproducibility separate these formats, with spray mechanisms requiring priming protocols that powder devices eliminate.
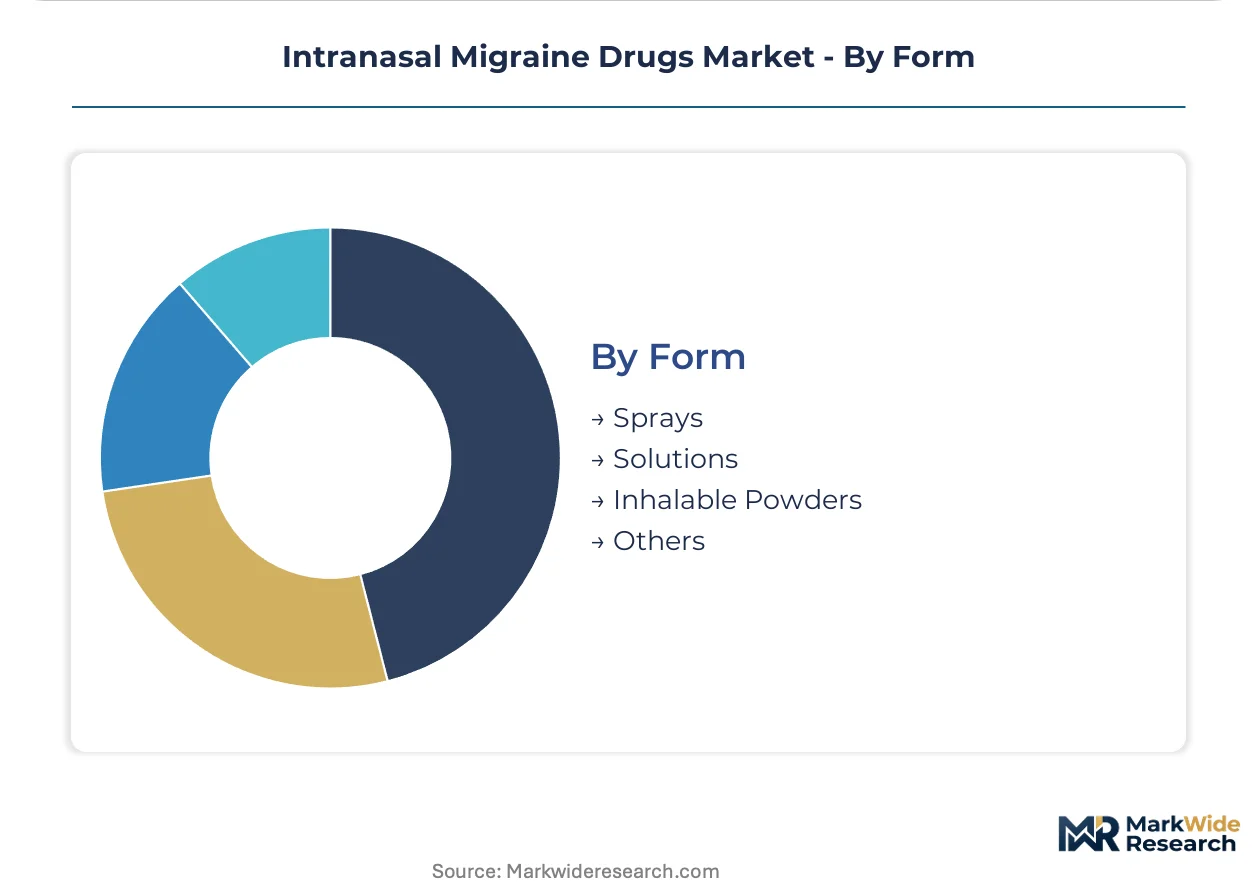
- Sprays:Pump-actuated liquid delivery systems with established patient familiarity but variable deposition patterns. United States prescribing concentrates here due to manufacturing scale and pharmacist comfort with counseling requirements.
- Inhalable Powders:Breath-actuated or device-powered dry powder systems with superior stability profiles. Travel and workplace storage without refrigeration constraints drives fastest uptake among episodic migraine patients.
- Solutions:Dropper-administered liquid formats with precise volume control but higher contamination risk.
- Others:Nasal inserts, gels, and experimental microarray patches.
Sprays dominate current volume, with Inhalable Powders showing the sharpest growth curve as patient preference shifts toward preservative-free alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States captures substantially higher intranasal migraine prescription volume than Germany, though both markets face divergent reimbursement pressures shaping manufacturer commercial strategies.
United States
Emergency department protocols and pharmacy benefit manager formulary tiers drive intranasal dihydroergotamine procurement. The IRA's Medicare price negotiation provisions compress revenue forecasting for branded therapies approaching statutory eligibility thresholds. Greater Boston anchors neurology specialist density and clinical trial recruitment for novel delivery platforms.
Germany
Headache specialist practices and statutory health insurance reimbursement frameworks concentrate demand for second-generation triptans. The EMA enforces centralized marketing authorization standards that streamline multi-country launch planning. Baden-Württemberg hosts contract manufacturing organizations supplying active pharmaceutical ingredients to European formulators.
United Kingdom
National Health Service formularies prioritize cost-effectiveness assessments for acute migraine therapies against oral generic benchmarks. The MHRA operates post-Brexit regulatory autonomy while maintaining EMA guideline alignment for nasal spray bioequivalence. London's headache centers drive specialist prescribing patterns for precision olfactory delivery technologies.
Japan
PMDA marketing authorization procedures and aging demographics expand the addressable patient population for non-oral acute therapies. METI industrial policy supports domestic device manufacturing for metered-dose nasal delivery systems. The Kanto region concentrates pharmaceutical distribution infrastructure and hospital procurement authority.
India
CDSCO regulatory pathways and domestic manufacturing cost advantages position the market for generic intranasal export supply. The PLI scheme incentivizes active pharmaceutical ingredient production for ergot alkaloid derivatives. Maharashtra clusters contract research organizations supporting bioequivalence studies for complex nasal generics.
Intranasal Migraine Drugs Market Competitive Landscape
Top-tier vendors anchor hospital formulary negotiations and specialist prescribing networks, while mid-scale formulators compete on 505(b)(2) pathway speed and regional regulatory expertise. The market structure stratifies across three archetypes: vertically integrated pharmaceutical conglomerates with neurology franchises, delivery technology specialists licensing precision olfactory platforms, and generic manufacturers exploiting abbreviated approval pathways. Consolidation activity concentrates on device engineering capabilities and European API supply security.
Among the delivery technology specialists, Impel Pharmaceuticals Inc. exemplifies precision olfactory engineering approaches, while Pfizer Inc. and Eli Lilly and Company occupy positions within the integrated pharmaceutical tier leveraging established neurology infrastructure. These three entities represent the competitive spectrum from device-centric differentiation to portfolio-scale commercial execution.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Novartis AG |
| Dr. Reddy's Laboratories Ltd. |
| Cipla Limited |
| Tonix Medicines, Inc. |
| Impel Pharmaceuticals Inc. |
| Others |
Supply & Pricing Matrix
Dihydroergotamine mesylate API costs cascade through three pricing tiers as European contract manufacturers feed United States hospital systems and retail pharmacy channels. The concentration of ergot alkaloid production in Baden-Württemberg contract manufacturing organizations creates asymmetric pricing power that branded formulators exploit through delivery technology premiums.
Pricing Analysis
Capacity additions in Indian generic manufacturing are reshaping price floors for sumatriptan intranasal formulations, compressing margins for first-generation triptan suppliers. Three-tier pricing structure across premium, standard, and economy levels separates precision olfactory delivery platforms from conventional liquid sprays and commodity generics. Pricing pressure stems from oral generic substitution in Medicare Part D formularies, where low-cost sumatriptan tablets displace intranasal prescriptions despite inferior onset kinetics. At-home users exhibit highest price sensitivity through direct-to-patient subscription comparison shopping, while emergency department procurement committees prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Regional distribution centers in the United States Northeast and Midwest operate hub-and-spoke patterns for temperature-controlled intranasal liquid formulations requiring preservative stabilization. API production concentrates in Germany, Switzerland, and India, with ergot alkaloid extraction tethered to European agricultural sourcing and Indian contract manufacturing cost advantages. Dihydroergotamine mesylate, benzalkonium chloride preservatives, and precision powder device components constitute critical input dependencies. Single-source vulnerability runs through European API manufacturers supplying United States hospital systems on just-in-time inventory protocols. Distribution runs through specialty pharmaceutical wholesalers with cold-chain capabilities serving hospital formularies and retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intranasal migraine drugs market represents a late-cycle quality story as patient preference shifts toward preservative-free powder platforms commanding premium positioning over commodity liquid alternatives.
For Market Incumbents: Deploy lifecycle management through 505(b)(2) eligible delivery improvements to extend exclusivity periods ahead of IRA Medicare price negotiation eligibility. Branded manufacturers must accelerate particle engineering investments and precision olfactory targeting capabilities to defend against generic intranasal entrants exploiting abbreviated FDA approval pathways. Channel control through hospital formulary anchoring and specialist prescriber networks provides defensive moats against oral generic substitution threats. For New Entrants and Emerging Players: Workplace and travel-oriented patients represent an underserved buyer archetype seeking portable, refrigeration-free alternatives to traditional liquid sprays. White-space opportunities concentrate in preservative-free powder platforms for benzalkonium chloride-sensitive populations and subscription-based adherence programs capturing lifetime value beyond initial prescription capture. European centralized EMA authorization enables simultaneous multi-country launch with reduced fragmentation costs relative to national filing routes. For Investors and Strategic Acquirers: Consolidation pressure builds where device engineering capabilities and European API supply security concentrate competitive advantage away from composition patents alone. Long-term viability favors vertically integrated pharmaceutical conglomerates with captive neurology infrastructure and delivery technology specialists licensing precision olfactory platforms. Acquisition targets include mid-scale formulators with 505(b)(2) pathway expertise and regional regulatory capabilities. The signal to watch is hospital procurement committee unbundling of acute migraine therapy from bundled neurological service contracts, enabling independent line-item negotiation for intranasal dihydroergotamine stocking.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | 505(b)(2) submissions accelerate generic intranasal entry by referencing existing safety databases. |
| Manufacturing Scale-Up | Specialized lyophilization equipment for powder delivery platforms requires extended validation timelines. |
| Hospital System Partnership | Emergency department formulary anchoring creates institutional prescribing momentum for acute care protocols. |
| Reimbursement Strategy | Medicare price negotiation eligibility reshapes commercial forecasting for branded intranasal therapies. |
| Pipeline Diversification | Novel serotonin receptor modulators and CGRP antagonists expand intranasal development candidates. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative insights in practitioner realities. Secondary validation drew from FDA 505(b)(2) filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and United States hospital formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated demand estimates across delivery technology and end-user segments.
Bottom-up segmentation analysis modeled patient population flows across treatment lines, dosage forms, and regional regulatory clusters over the projection horizon. Top-down validation referenced pharmaceutical industry revenue disclosures and therapeutic category expenditure patterns. CAGRs were derived from prescription volume trajectories and pricing evolution assumptions. Forecast inputs incorporated IRA Medicare price negotiation implementation timelines and EMA bioequivalence guidance evolution for complex nasal generics.
Underlying measurement precision varies by segment; hospital procurement data and established liquid delivery prescriptions carry tighter precision than emerging powder platform adoption curves. Forecasts reflect documented assumptions regarding regulatory pathway timelines, API supply continuity, and reimbursement framework stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market