
 Buprenorphine and Naloxone Market | 2026-2036
Buprenorphine and Naloxone Market Size, Share, and Industry Trends Forecast 2026-2036
Buprenorphine and Naloxone Market Insights
Modular dosing configurations are restructuring how physicians match buprenorphine-naloxone products to patient stabilization needs. Indivior PLC dominates the branded sublingual film segment through proprietary formulation technology and REMS compliance infrastructure. Teva Pharmaceutical Industries Ltd. competes across multiple dosage strengths with a portfolio spanning tablets and generic films. Hikma Pharmaceuticals PLC anchors hospital and institutional procurement channels with injectable presentations.
Buprenorphine and naloxone constitute a fixed-dose combination of a partial mu-opioid agonist and a full antagonist, formulated in ratios such as 4:1 or 2.5:1 to deter intravenous misuse while maintaining agonist efficacy for opioid dependence treatment. The combination functions primarily to reduce withdrawal symptoms and cravings in medication-assisted therapy for opioid use disorder. Sublingual films command premium positioning due to faster dissolution kinetics and child-resistant packaging requirements, while tablets sustain volume leadership through pharmacy benefit manager formulary placement and lower acquisition costs. Injectable solutions capture concentrated margin pools in supervised clinical settings where adherence monitoring takes priority over take-home convenience.
FDA REMS certification mandates restrict prescribing authority to qualified physicians, directly constraining market access and shaping distribution through certified pharmacies and opioid treatment programs. DEA scheduling under the Controlled Substances Act imposes quota-based manufacturing limits and chain-of-custody documentation that elevate compliance costs across the value chain. State-level Medicaid expansion decisions and parity legislation determine reimbursement breadth for outpatient medication-assisted therapy. Stakeholders must monitor evolving FDA guidance on depot formulations and digital therapeutics combinations that could reshape the competitive landscape for long-acting maintenance therapy.
Market Dynamics
FDA REMS certification mandates and DEA quota restrictions create a bifurcated access structure where certified prescribers and pharmacies control patient flow, concentrating volume through opioid treatment programs and institutional channels.
Growth Catalysts
- Medicaid Expansion:State-level Medicaid expansion under the Affordable Care Act broadens reimbursement for outpatient medication-assisted therapy, particularly in states with high opioid mortality rates.
- Suboxone Film Formulation:Sublingual film technology accelerates dissolution kinetics and satisfies child-resistant packaging mandates, driving preference in take-home dispensing protocols.
- Telehealth Integration:Remote prescribing flexibilities introduced during public health emergencies extend prescriber reach into rural counties with provider shortages.
Market Restraints
- DEA Manufacturing Quotas:Annual aggregate production limits for Schedule III controlled substances constrain supply elasticity and create allocation bottlenecks during demand surges.
- Single-Source API Concentration:Active pharmaceutical ingredient supply concentrates among limited FDA-registered manufacturers, elevating vulnerability to quality enforcement actions.
- Generic Tablet Substitution:Pharmacy benefit manager formulary placement favors lower-acquisition-cost generic tablets, compressing branded film margins.
Strategic Opportunities
- Depot Formulation Development:Long-acting injectable and implantable presentations address adherence gaps in supervised clinical settings and reduce diversion risk.
- Digital Therapeutic Pairing:FDA breakthrough device designation pathways enable combination products linking pharmacotherapy with cognitive behavioral intervention apps.
- Correctional Institution Expansion:Federal Bureau of Prisons medication-assisted therapy mandates create captive demand pools with guaranteed reimbursement.
Industry Challenges
- REMS Compliance Workforce:Qualified prescriber certification requirements strain specialized training capacity, limiting prescriber base expansion.
- Cold Chain Integrity:Temperature-controlled distribution for film formulations demands validated logistics infrastructure that smaller regional pharmacies lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buprenorphine and Naloxone Market |
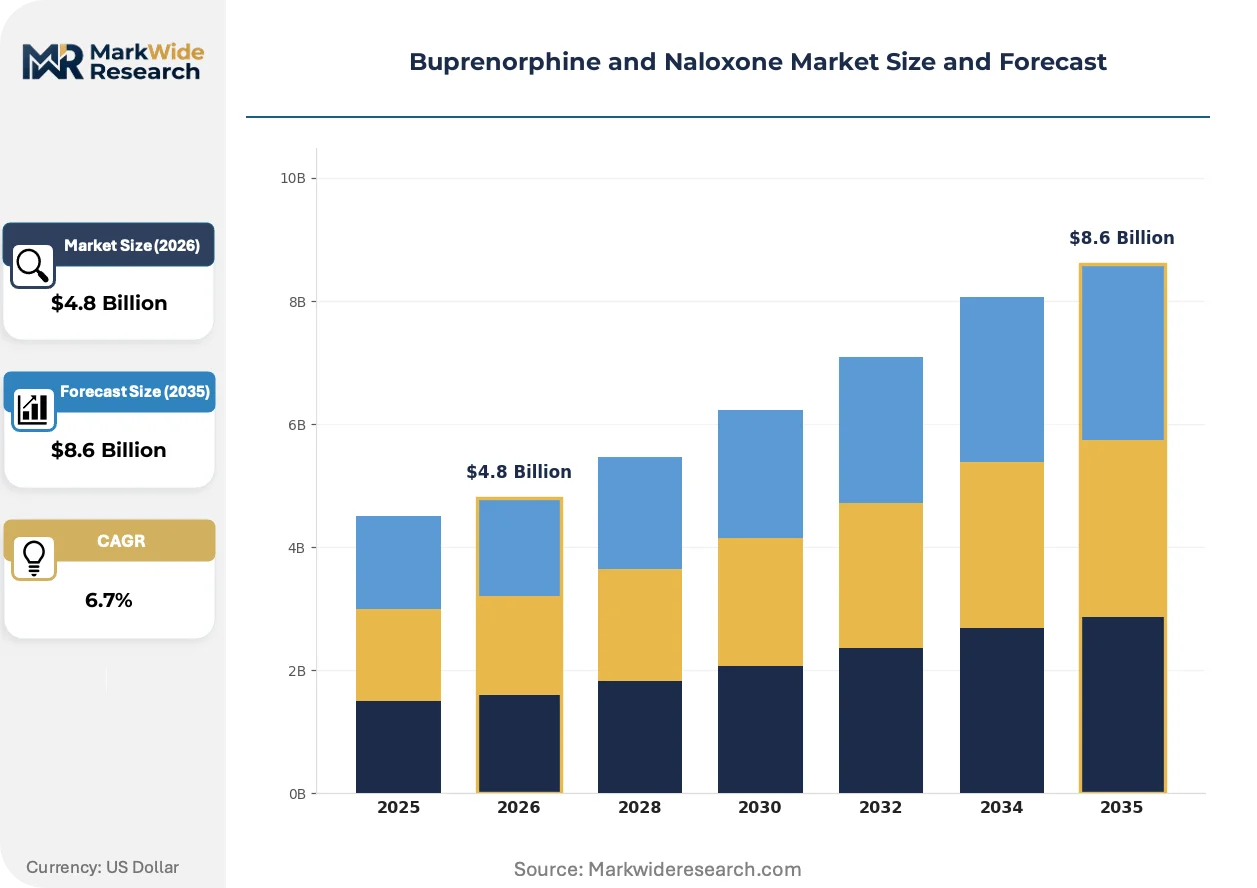
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable Solutions, Transdermal Patches, Sublingual Films Therapy Area: Opioid Dependence, Pain Management, Withdrawal Management, Substance Use Disorder Delivery Mode: Oral, Injectable, Sublingual, Transdermal End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Pharmacies |
| Companies Covered | Indivior PLC, Viatris Inc., Sandoz AG, Dr. Reddy's Laboratories Ltd., Hikma Pharmaceuticals PLC, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Mallinckrodt, Alvogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buprenorphine and Naloxone Market Trends and Innovations
Formulation science and digital health convergence are redefining adherence monitoring and diversion prevention, while procurement centralization reshapes how institutions acquire maintenance therapy products.
Long-acting injectable buprenorphine formulations are expanding into medication-assisted therapy protocols where monthly administration replaces daily dosing. Federally qualified health centers and Veterans Health Administration facilities adopt these presentations to reduce patient visit frequency. This technology is expanding into take-home dispensing restrictions, compressing the addressable market for daily-dose tablets.
DEA electronic prescribing mandates for controlled substances impose interoperable prescription routing requirements that eliminate paper-based workflows. Pharmacy management systems must upgrade infrastructure to accept validated electronic data. Retail pharmacy chains and independent dispensaries in states with early compliance deadlines accelerate capital deployment.
Correctional health systems consolidate procurement through national cooperative purchasing agreements, displacing fragmented county-level acquisition. State prison systems and large urban jail complexes aggregate volume to extract price concessions. This concentration is most visible in the Southeast and Southwest, where privatized correctional healthcare operators manage multiple facilities under single contracts.
Buprenorphine and Naloxone Market Segmentation
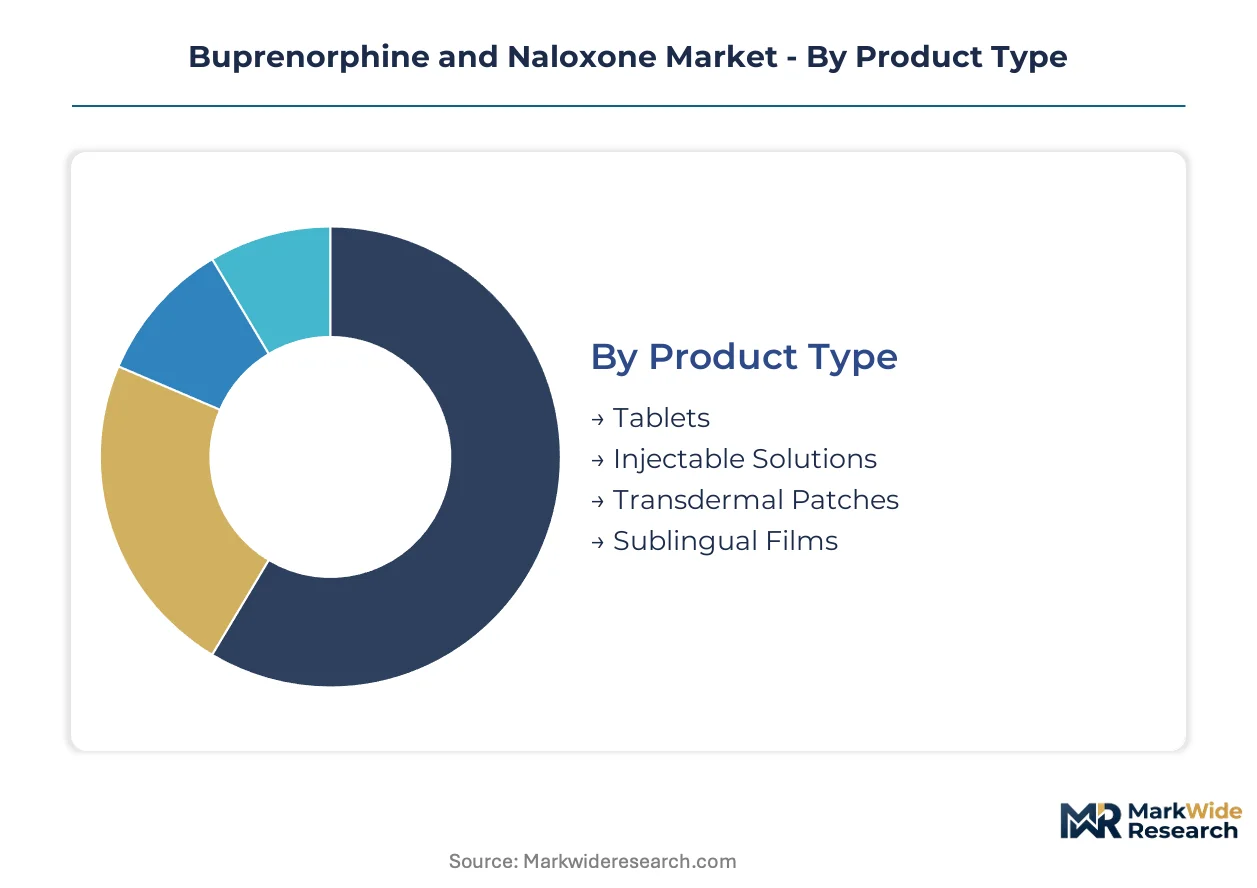
Product differentiation in buprenorphine-naloxone markets follows prescriber certification pathways and reimbursement structures. Each segment carries distinct compliance burdens and margin profiles that reshape procurement decisions across certified treatment channels.
Product Type:
Replacement cycles vary sharply across administration formats, with daily-dose presentations facing substitution pressure from long-acting alternatives.
- Sublingual Films:Proprietary polymer matrices enable rapid buccal absorption and satisfy FDA child-resistant packaging mandates. Demand clusters in take-home dispensing protocols at federally qualified health centers, where film formulations command preferential reimbursement under medication-assisted therapy guidelines.
- Tablets:Compressed buprenorphine-naloxone combinations in 2 mg/0.5 mg through 8 mg/2 mg strengths dominate pharmacy benefit manager formularies. Volume concentrates in retail chains across states with broad Medicaid coverage, though generic substitution erodes branded margins.
- Injectable Solutions:Sterile buprenorphine formulations for intramuscular or subcutaneous administration serve supervised clinical settings.
- Transdermal Patches:Extended-release adhesive systems deliver steady plasma concentrations over multi-day intervals.
Volume placements concentrate in Tablets; the faster expansion belongs to Sublingual Films.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance programs, with reimbursement intensity varying by diagnostic classification.
- Opioid Dependence:Long-term maintenance therapy for diagnosed opioid use disorder constitutes the core commercial indication, requiring REMS-certified prescribers and documented counseling components. Federal funding streams through SAMHSA block grants sustain demand in high-mortality states.
- Substance Use Disorder:Broader diagnostic coding captures polysubstance presentations and co-occurring mental health conditions. Treatment expansion concentrates in Veterans Health Administration facilities and correctional health systems where integrated care models justify higher per-patient reimbursement.
- Pain Management:Off-label utilization for chronic non-cancer pain faces escalating scrutiny.
- Withdrawal Management:Short-term detoxification protocols employ tapered dosing regimens.
Revenue concentration sits with Opioid Dependence; Substance Use Disorder applications are climbing the fastest.
Delivery Mode:
Application-specific requirements dictate infrastructure investment, with supervised administration demanding tighter chain-of-custody controls than take-home regimens.
- Sublingual:Buccal mucosa absorption bypasses first-pass hepatic metabolism, enabling lower effective doses. Film and tablet sublingual formats dominate outpatient medication-assisted therapy, with FDA bioequivalence standards governing generic substitution.
- Injectable:Parenteral administration ensures adherence in supervised settings and eliminates diversion risk. Long-acting depot formulations extend dosing intervals to monthly intervals, reshaping visit frequency at opioid treatment programs.
- Oral:Swallowed tablet formulations see limited utilization due to reduced bioavailability and naloxone activation concerns.
- Transdermal:Skin-adhesive systems require intact dermal surfaces and carry temperature-dependent release kinetics.
Patient visit patterns favor Injectable modes for institutional capture; Sublingual retains the broadest prescriber base.
End User:
Customer type determines procurement scale and contracting sophistication, with consolidated health systems extracting steeper discounts than fragmented independent operators.
- Outpatient Clinics:Federally qualified health centers and private medication-assisted therapy practices generate recurring prescription volume through REMS-certified physician extenders. Medicaid reimbursement rates and state parity legislation shape site profitability.
- Hospitals:Acute care facilities manage withdrawal protocols and initiate maintenance therapy prior to discharge. Formulary committees prioritize single-source contracts with guaranteed supply security over price minimization.
- Rehabilitation Centers:Residential treatment facilities employ buprenorphine-naloxone for structured tapering programs.
- Pharmacies:Retail dispensaries face DEA electronic prescribing mandates and cold chain requirements for film storage.
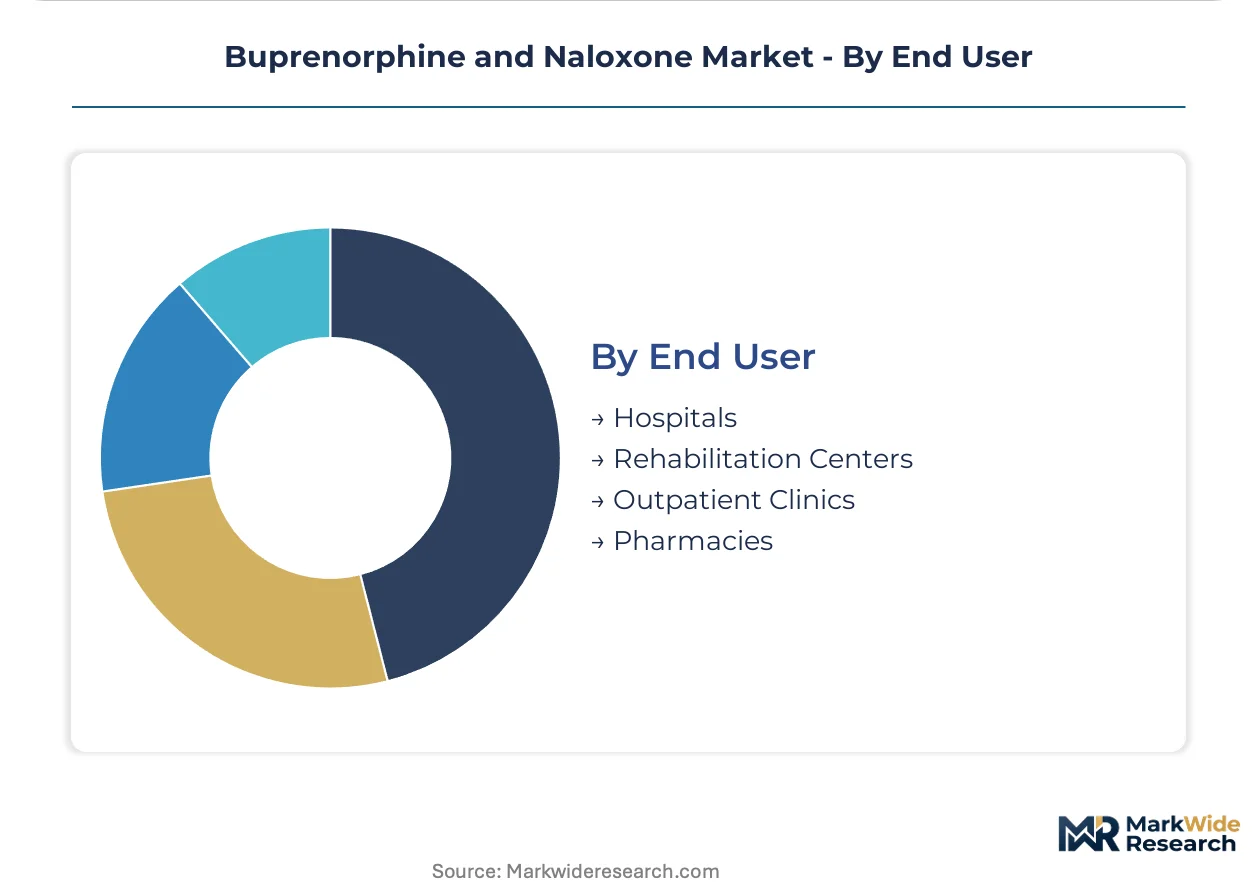
Prescription volume concentrates in Outpatient Clinics; Rehabilitation Centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for buprenorphine-naloxone concentrates in India and the United States, while consumption tilts heavily toward American outpatient clinics and correctional systems. European demand remains fragmented across national reimbursement schemes. The analysis tracks five countries where regulatory frameworks and treatment infrastructure shape competitive access.
United States
Medicaid expansion and SAMHSA block grants sustain medication-assisted therapy volume across high-mortality states. The FDA REMS program restricts prescribing authority to certified physicians, concentrating patient flow through opioid treatment programs. Texas and Florida anchor institutional procurement through consolidated correctional health contracts.
Germany
Substitution therapy protocols in Bavaria and North Rhine-Westphalia drive demand for long-acting depot formulations. The EMA centralized marketing authorization process governs product entry, while German sickness funds negotiate reimbursement through the Federal Joint Committee. Berlin hosts several specialized addiction medicine centers expanding supervised dosing capacity.
United Kingdom
NHS England community pharmacy agreements enable take-home dispensing for stabilized patients, expanding addressable volume beyond clinical settings. The MHRA regulates buprenorphine products through national licensing pathways that diverge from EU procedures post-Brexit. Manchester and Glasgow cluster specialist addiction services with embedded pharmacy partnerships.
India
API manufacturing concentrates in Hyderabad and Ahmedabad, where FDA-registered facilities supply global generic formulation demand. The CDSCO regulates domestic marketing authorization while export volumes flow to regulated markets under contract manufacturing arrangements. Indian manufacturers face increasing quality enforcement actions that reshape supplier qualification requirements.
Canada
Health Canada exemption pathways for supervised consumption sites expand medication-assisted therapy access in British Columbia and Ontario. Provincial formularies determine reimbursement breadth, with British Columbia's public payer leading coverage expansion. Toronto and Vancouver anchor urban treatment networks with integrated pharmacy and clinical service delivery.
Buprenorphine and Naloxone Market Competitive Landscape
The competitive structure tilts toward formulation specialists with REMS compliance infrastructure and generic manufacturers with API backward integration. Branded film producers compete on dissolution technology and child-resistant packaging certification, while tablet genericizers extract volume through pharmacy benefit manager placement. Three archetypes dominate: proprietary formulation innovators, vertically integrated generic houses, and institutional channel specialists. Competitive moves center on depot formulation development and correctional procurement consolidation.
Among formulation innovators, Indivior PLC and Alvogen occupy positions defined by proprietary sublingual film technology and regulatory compliance systems. Teva Pharmaceutical Industries Ltd. exemplifies the scale-driven generic archetype with multi-strength tablet portfolios. Hikma Pharmaceuticals PLC anchors the institutional specialist tier through injectable presentations and hospital procurement relationships.
| Leading Market Players |
|---|
| Indivior PLC |
| Viatris Inc. |
| Sandoz AG |
| Dr. Reddy's Laboratories Ltd. |
| Hikma Pharmaceuticals PLC |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Mallinckrodt |
| Alvogen |
| Others |
Pricing and Supply Chain Analysis
API synthesis costs for buprenorphine base traverse from Indian chemical manufacturers through DEA-registered formulators to Medicaid-reimbursed dispensaries, with cold chain logistics for sublingual films layering temperature-controlled freight premiums atop standard pharmaceutical distribution economics.
Pricing Analysis
Margin tightening in branded film formulations reflects pharmacy benefit manager formulary placement favoring generic tablets. Three-tier pricing structure across REMS-certified specialty, standard retail, and institutional procurement channels separates prescriber certification requirements from volume scale discounts. Cost-down pressure on sublingual presentations accelerates because Medicaid expansion states negotiate supplemental rebate agreements. Outpatient clinics exhibit highest price sensitivity; correctional systems with national purchasing agreements demonstrate lowest.
Supply Chain Analysis
Temperature-controlled freight for film formulations elevates per-unit logistics costs above ambient tablet distribution. API manufacturing concentrates in India and the United States, with sterile injectable finishing in European facilities. Finished dosage form production draws from buprenorphine base, naloxone hydrochloride, and polymer film substrates. Single-source API vulnerability persists among limited FDA-registered manufacturers. Distribution runs through DEA-certified wholesale distributors to REMS-authorized pharmacies and opioid treatment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where API backward integration and REMS compliance infrastructure constitute the decisive upstream and downstream levers separating sustainable competitors from margin-compressed assemblers.
For Market Incumbents: Cement REMS certification capacity through prescriber training program expansion and pharmacy network lock-in agreements. Defend against generic tablet substitution by accelerating depot formulation development. Prioritize captive API supply through contract manufacturing organization acquisitions or long-term offtake arrangements with Indian manufacturers facing quality enforcement actions. For New Entrants and Emerging Players: The pricing gap between Indivior's premium film positioning and Teva's economy tablet portfolio opens white-space at mid-tier institutional channels. Target hospital procurement committees with single-source injectable contracts. Exploit correctional health system consolidation in Texas and Florida through national cooperative purchasing agreement qualification. Lead with guaranteed supply security messaging over price minimization. For Investors and Strategic Acquirers: Distressed-cycle entries favor formulation specialists with dormant REMS infrastructure in high-Medicaid-expansion states. Five-to-ten-year viability hinges on depot technology transition completion rather than daily-dose market share defense. Watch FDA guidance on digital therapeutic combinations as inflection indicator for maintenance therapy platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Expansion | Prescriber certification capacity directly constrains addressable patient volume in expansion states. |
| Depot Formulation Development | Long-acting injectable presentations reshape visit frequency at federally qualified health centers. |
| API Backward Integration | Captive supply of buprenorphine base insulates against Indian quality enforcement disruptions. |
| Correctional Procurement Consolidation | National cooperative purchasing agreements in Texas and Florida aggregate guaranteed-reimbursement volume pools. |
| Digital Therapeutic Pairing | FDA breakthrough device designation pathways enable cognitive behavioral intervention app combinations. |
Research Methodology
FDA REMS program documentation, DEA manufacturing quota publications, and SAMHSA block grant disbursement records formed the secondary backbone, supplemented by CMS Medicaid reimbursement data and state parity legislation tracking. Primary fieldwork encompassed regulatory affairs specialists at generic manufacturers, formulary directors at pharmacy benefit managers, procurement managers at correctional health systems, and medication-assisted therapy program directors at federally qualified health centers. Bottom-up prescription volume modeling and top-down expenditure flow analysis were cross-validated through triangulation.
Bottom-up patient flow estimation by dosage form and administration route was reconciled against top-down pharmaceutical expenditure reporting across the projection horizon. Segmentation dimensions encompassed product type, therapy area, delivery mode, and end-user channel, with regional regulatory clusters modeled separately. CAGRs were derived from stabilized patient population projections and per-patient maintenance therapy cost trajectories. Key inputs included DEA quota allocation trends and Medicaid expansion state identification.
Inputs from FDA advisory committee minutes and state Medicaid formulary filings were available through the study window; gaps in real-time diversion incident reporting introduce uncertainty bands around adherence-adjusted demand estimates. Forecasts reflect documented assumptions regarding REMS certification expansion rates and depot formulation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Budesonide Market