
 Smoking Cessation Drugs Market | 2026-2036
Smoking Cessation Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Smoking Cessation Drugs Market Outlook
FDA labeling revisions for smoking cessation pharmacotherapies is shifting the cost-of-entry calculus for manufacturers seeking market authorization. Pfizer leverages its established manufacturing infrastructure to sustain varenicline supply continuity amid regulatory scrutiny. GlaxoSmithKline anchors its competitive position through nicotine replacement therapy dominance across patch and gum formats. Johnson & Johnson competes in the over-the-counter segment with differentiated lozenge and gum delivery systems.
Smoking cessation drugs comprise prescription and over-the-counter pharmacological agents designed to reduce nicotine withdrawal symptoms and tobacco dependence, typically formulated as transdermal patches releasing nicotine at controlled rates or as oral tablets modulating neurotransmitter activity. The primary commercial purpose centers on supporting behavioral cessation programs by attenuating physiological cravings. Nicotine Replacement Therapy occupies the largest volume position due to established safety profiles and broad OTC availability, while varenicline commands premium positioning despite regulatory turbulence. Extended-release tablet formulations represent the fastest-growing formulation category as patients and providers prioritize dosing convenience and adherence optimization.
The FDA, EMA, and WHO Framework Convention on Tobacco Control collectively shape product standards, clinical trial endpoints, and market access pathways for cessation pharmacotherapies across developed and emerging markets. These regulators mandate cardiovascular safety monitoring and standardized efficacy benchmarks that determine formulary inclusion and reimbursement eligibility. Stakeholders must monitor evolving pharmacovigilance requirements and real-world evidence demands that will determine which therapeutic modalities retain prescriber confidence and payer support.
Market Dynamics
FDA boxed warning mandates for varenicline products have forced hospital formulary committees to reweight safety profiles against efficacy data, compressing prescribing windows and accelerating portfolio diversification among pharmacotherapy providers.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage for cessation counseling paired with pharmacotherapy removes cost barriers for beneficiaries aged 65 and older, expanding addressable patient populations in federally qualified health centers.
- WHO Framework Convention implementation:Article 14 obligations push 182 signatory nations to integrate cessation services into national health systems, creating procurement pipelines for NRT and prescription therapies.
- Extended-release tablet adoption:Once-daily dosing formats improve adherence metrics in employer-sponsored wellness programs, reducing dropout rates in behavioral support protocols.
Market Restraints
- Active pharmaceutical ingredient concentration:Indian and Chinese API manufacturers supply over 80 percent of nicotine polacrilex and bupropion precursors, creating single-source vulnerability for patch and tablet formulations.
- Cardiovascular safety monitoring burdens:FDA post-market surveillance requirements for varenicline impose ongoing clinical trial obligations that extend time-to-market for reformulated products by 18-24 months.
- E-cigarette substitution dynamics:Disposable nicotine vapor products capture price-sensitive cessation seekers in convenience retail channels, diverting demand from clinically supervised pharmacotherapy pathways.
Strategic Opportunities
- Digital therapeutic convergence:Smartphone-based craving prediction algorithms paired with transdermal patch dosing adjustments enable personalized tapering protocols, attracting employer wellness contracts.
- Community pharmacy channel expansion:State-level scope-of-practice reforms allow pharmacists to prescribe NRT directly, bypassing physician gatekeeping in rural and underserved markets.
- Combination therapy protocols:Patch-plus-lozenge regimens demonstrate superior quit rates in VA healthcare system trials, creating formulary preference for dual-format manufacturers.
Industry Challenges
- Behavioral health integration complexity:Smoking cessation protocols must interface with electronic health record systems from Epic, Cerner, and Meditech, requiring costly interoperability certification for pharmacotherapy vendors.
- Pharmacovigilance talent scarcity:Manufacturers face recruitment bottlenecks for cardiovascular safety analysts capable of managing FDA-mandated adverse event reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoking Cessation Drugs Market |
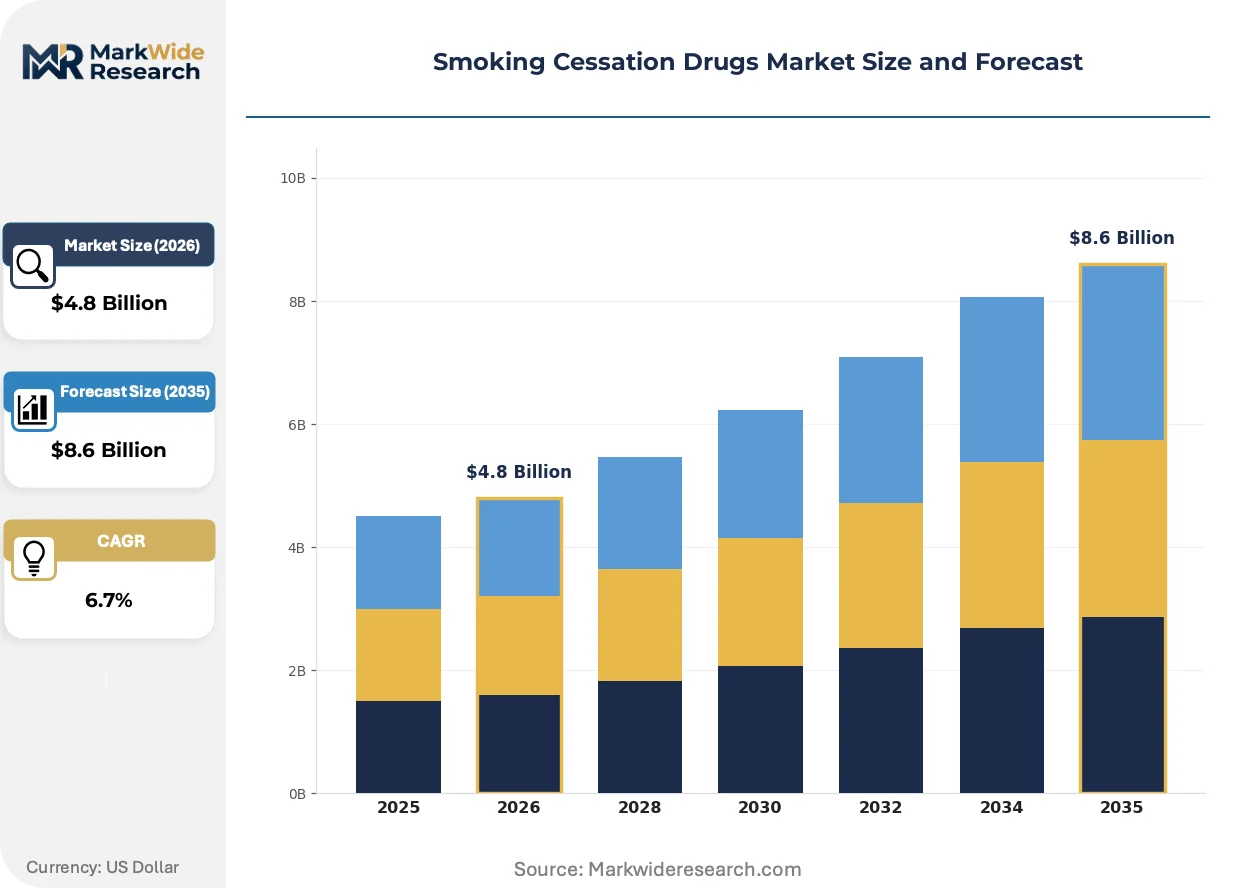
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Nicotine Replacement Therapy, Bupropion, Varenicline, Nortriptyline Delivery Mode: Gum, Patch, Inhaler, Tablet End User: Hospitals, Clinics, Pharmacies, Rehabilitation Centers Formulation: Injection, Extended-Release, Sustained-Release, Oral |
| Companies Covered | Pfizer, GlaxoSmithKline, Johnson & Johnson, Novartis, Sanofi, AstraZeneca, Boehringer Ingelheim, Reckitt Benckiser, Perrigo Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoking Cessation Drugs Market Strategic Shifts
Pharmacotherapy delivery systems are converging with digital health infrastructure, rewiring how providers prescribe, monitor, and adjust cessation interventions in real time.
Transdermal patch technology is integrating microprocessor-controlled nicotine release mechanisms that respond to biometric stress indicators. Veterans Health Administration facilities in California and Texas have piloted these sensor-augmented systems since 2023. The technology is compressing the gap between physiological craving onset and therapeutic response, reducing breakthrough smoking incidents during high-stress intervals.
EMA pharmacovigilance guidelines now mandate real-world evidence collection for all new smoking cessation drug approvals, extending post-authorization study obligations across EU member states. Pharmaceutical sponsors must deploy patient registries tracking cardiovascular outcomes for minimum five-year horizons. This regulatory architecture most heavily affects extended-release tablet developers seeking centralized marketing authorization in Germany and France.
Employer-sponsored cessation benefits are unbundling pharmacotherapy from traditional telephonic counseling packages. Large self-insured employers in the manufacturing and logistics sectors now contract directly with digital health platforms for app-based behavioral support paired with OTC NRT fulfillment. This procurement fragmentation is most pronounced in Midwestern states where union-negotiated health benefits previously channeled members through centralized quitline services.
Smoking Cessation Drugs Market Segmentation
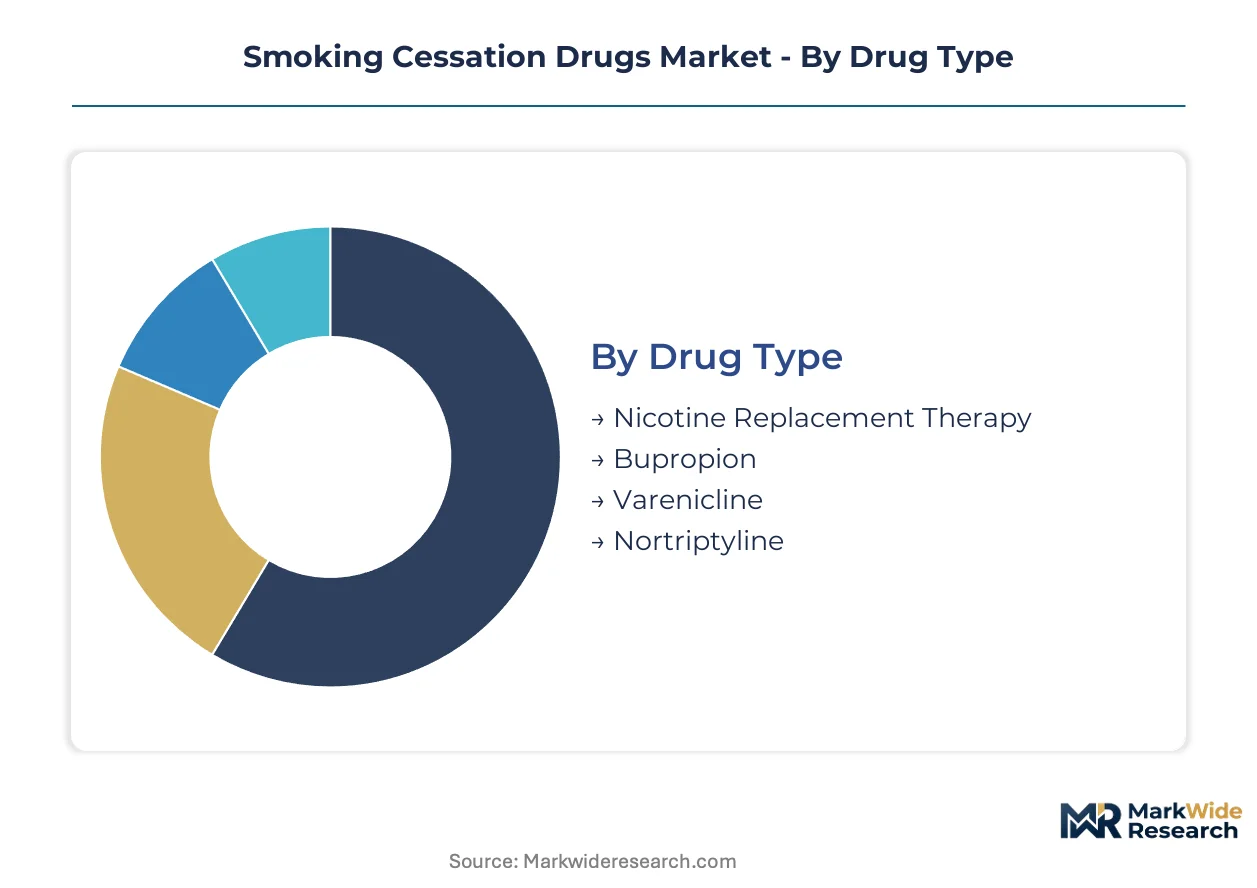
Smoking cessation pharmacotherapy segments diverge sharply by prescriber authority, reimbursement pathways, and patient adherence profiles. Manufacturers configure portfolio investments around these divides, as hospital formulary access and OTC retail penetration demand distinct regulatory strategies and distribution architectures.
Drug Type:
Patient risk tolerance and prescriber confidence in cardiovascular safety profiles differentiate purchasing patterns across this category.
- Nicotine Replacement Therapy:Transdermal patches, gums, and lozenges deliver controlled nicotine doses to attenuate withdrawal without prescription barriers. Demand concentrates in United States retail pharmacy chains where Medicare Part D coverage and employer wellness subsidies remove cost friction for beneficiaries seeking first-line intervention.
- Varenicline:Partial nicotine agonist tablets modulate dopamine receptor activity to reduce craving intensity and reward satisfaction. Hospital systems in Germany and France maintain restricted formularies following EMA cardiovascular safety alerts, compressing prescribing to supervised tapering protocols in cardiology-monitored settings.
- Bupropion:Atypical antidepressant formulation originally developed for depression repurposed for smoking cessation through dopamine and norepinephrine reuptake inhibition. Psychiatric comorbidity screening requirements limit uptake in primary care settings.
- Nortriptyline:Tricyclic antidepressant prescribed off-label for cessation where first-line therapies fail, requiring cardiac monitoring due to arrhythmia risk. Specialist psychiatrists in Australia's public health system retain prescribing authority.
Volume sits with Nicotine Replacement Therapy; growth tilts toward Varenicline as extended-release formulations restore prescriber confidence.
Delivery Mode:
Adherence optimization and discretion preferences shape patient selection, with convenience retail channels favoring portable formats over clinical administration.
- Patch:Transdermal systems release nicotine across 16-24 hour intervals through rate-controlling membrane technology. Veterans Health Administration facilities in California and Texas have scaled procurement of sensor-augmented patches integrating biometric stress response.
- Gum:Polacrilex resin buffers nicotine absorption through buccal mucosa, allowing patient-controlled dosing during acute craving episodes. Pharmacies in the United Kingdom dominate volume through NHS smoking cessation service vouchers.
- Inhaler:Handheld devices aerosolize nicotine for pulmonary absorption mimicking behavioral rituals of cigarette use. Pulmonology specialists in Italy prescribe for patients with concurrent chronic obstructive pulmonary disease.
- Tablet:Oral formulations including varenicline and bupropion enable precise dose titration with documented compliance tracking. Extended-release tablet development pipelines are expanding most quickly among manufacturers seeking once-daily dosing advantages.
Patch formats command the largest prescription volumes; tablet formulations are climbing the fastest as digital adherence monitoring integrates with EHR systems.
End User:
Reimbursement complexity and prescriber gatekeeping intensity create tiered access barriers that segment demand by institutional setting.
- Hospitals:Inpatient cessation protocols initiated during acute cardiac events leverage varenicline under cardiology supervision. United States health systems face FDA-mandated boxed warning documentation requirements.
- Clinics:Federally qualified health centers integrate pharmacotherapy with behavioral counseling under HRSA grant funding. Rural clinics in the United States Midwest report staffing shortages for cessation counseling certification.
- Pharmacies:Community pharmacists in United Kingdom and Australian jurisdictions exercise independent prescribing authority for NRT, bypassing physician consultation delays. State-level scope-of-practice reforms in the United States are expanding this channel.
- Rehabilitation Centers:Substance use disorder treatment facilities address tobacco dependence as co-occurring condition. Minnesota's residential addiction programs mandate simultaneous nicotine cessation for program completion.
Pharmacy channel volumes dominate OTC procurement; rehabilitation center integration is gaining share fastest as bundled payment models expand.
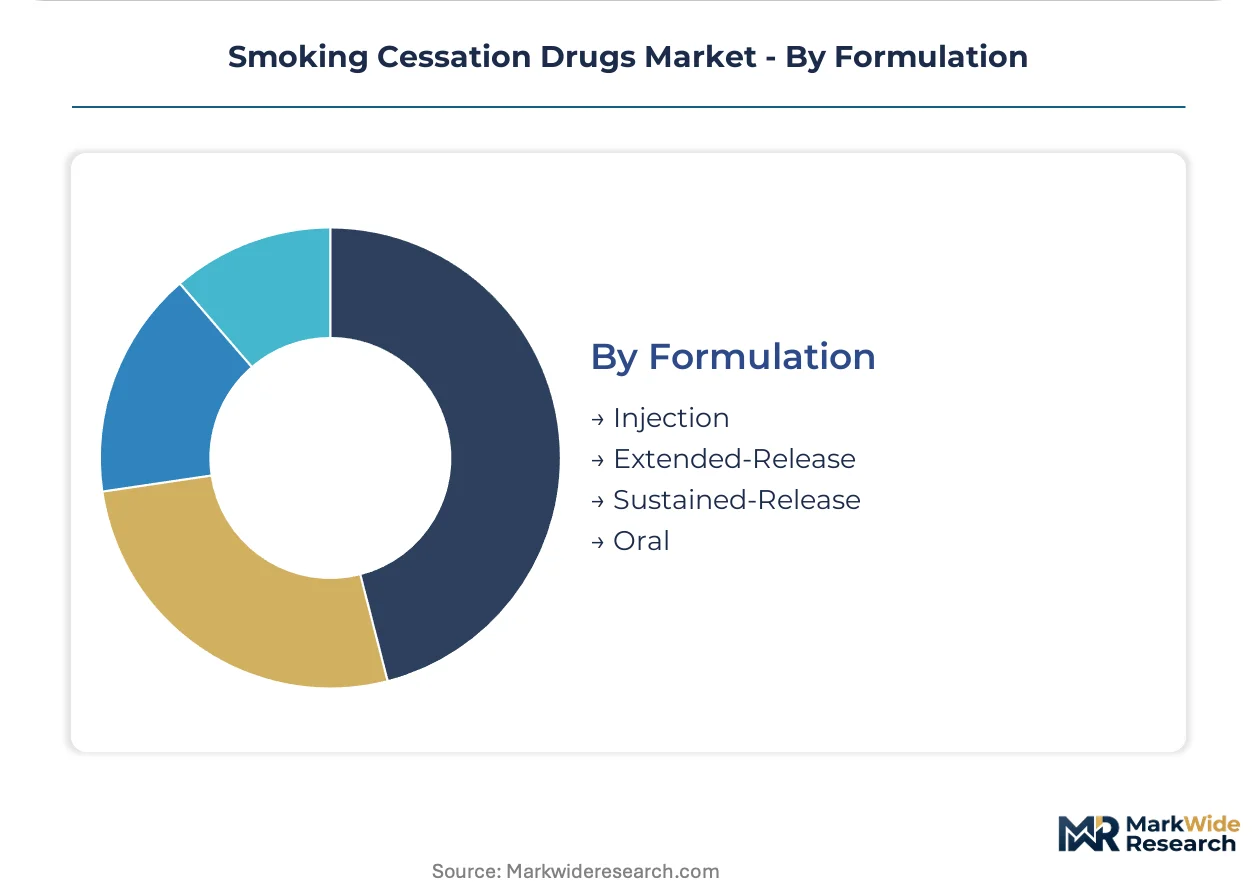
Formulation:
Release kinetics and administration route determine therapeutic windows, with long-acting formats reducing dosing frequency to improve completion rates in behavioral support programs.
- Extended-Release:Matrix or reservoir systems sustain plasma nicotine or active metabolite concentrations across 24-hour intervals. Employer wellness programs in United States manufacturing sectors prioritize these formats for adherence metrics.
- Sustained-Release:Bupropion formulations engineered for gradual absorption reduce seizure risk associated with immediate-release predecessors. Psychiatric practices in Canada maintain preference for this safety profile.
- Oral:Immediate-release tablets and lozenges enable patient-controlled dosing responsive to acute craving intensity. Retail pharmacy shelves in Japan stock diverse flavor variants competing with nicotine pouches.
- Injection:Depot formulations in clinical trial phases promise monthly administration intervals for recalcitrant dependence cases. Phase III investigators in Switzerland are enrolling participants for naltrexone-nicotine combination depot studies.
Oral formulations retain volume leadership; extended-release platforms are expanding most quickly as real-world evidence requirements favor adherence-optimized designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates through Medicare reimbursement pathways and employer wellness program procurement, shaping prescriber behavior and formulary access across hospital systems and retail pharmacy chains.
United States
FDA boxed warning mandates for varenicline products have compressed prescribing windows in cardiology-monitored hospital settings, while Medicare Part D coverage expansion removes cost barriers for beneficiaries aged 65 and older. CMS reimbursement for cessation counseling paired with pharmacotherapy drives volume through federally qualified health centers. Veterans Health Administration facilities in California and Texas pilot sensor-augmented transdermal patches integrating biometric stress response mechanisms.
Germany
EMA cardiovascular safety alerts have restricted varenicline formularies to supervised tapering protocols in hospital cardiology departments, shifting demand toward nicotine replacement therapies with established safety profiles. The country's national pharmaceutical regulator mandates real-world evidence collection for all new smoking cessation drug approvals, extending post-authorization study obligations. Pharmaceutical procurement in Bavaria and North Rhine-Westphalia concentrates through hospital system tenders prioritizing extended-release tablet formulations.
United Kingdom
NHS smoking cessation service vouchers drive nicotine gum volume through community pharmacy channels, where independent prescribing authority for NRT bypasses physician consultation delays. The country's national pharmaceutical procurement framework negotiates centralized contracts for transdermal patch and lozenge formats. London and Manchester health systems integrate pharmacotherapy with digital therapeutic platforms for app-based behavioral support.
Japan
PMDA approval pathways for extended-release tablet formulations prioritize adherence-optimized designs as employer wellness programs in manufacturing sectors seek once-daily dosing advantages. The country's national pharmaceutical regulator evaluates cardiovascular safety data under harmonized ICH guidelines. Tokyo and Osaka metropolitan clusters concentrate specialty psychiatric practices prescribing bupropion for patients with comorbid depression.
Australia
TGA pharmacovigilance requirements align with EMA cardiovascular safety monitoring standards, shaping prescriber confidence in varenicline products. The country's public health system retains specialist psychiatrist prescribing authority for nortriptyline off-label cessation use. Sydney and Melbourne rehabilitation centers mandate simultaneous nicotine cessation for substance use disorder program completion, expanding bundled payment models for pharmacotherapy integration.
Smoking Cessation Drugs Market Competitive Environment
United States and European pharmaceutical producers anchor one tier; Asian-Pacific API suppliers hold critical upstream positions in nicotine polacrilex and bupropion precursor manufacturing. The market structure consolidates around diversified multinational pharmaceutical conglomerates with established manufacturing infrastructure and regulatory compliance capabilities. Three strategic archetypes dominate: prescription-focused innovators managing cardiovascular safety portfolios, over-the-counter nicotine replacement therapy specialists with retail distribution scale, and generic manufacturers competing on cost-optimized formulations. Competitive moves center on portfolio diversification beyond varenicline amid regulatory turbulence and vertical integration into API supply chains to mitigate single-source vulnerability.
Within the prescription pharmaceutical tier, Pfizer and GlaxoSmithKline occupy positions exemplifying contrasting strategic approaches to regulatory headwinds and portfolio composition. Pfizer represents the archetype of established manufacturers leveraging manufacturing infrastructure to sustain supply continuity amid FDA scrutiny of boxed warning requirements. GlaxoSmithKline anchors the nicotine replacement therapy dominance model across patch and gum formats, demonstrating how OTC scale can offset prescription product volatility. Johnson & Johnson sits within the diversified consumer health segment, competing through differentiated lozenge and gum delivery systems in retail pharmacy channels.
| Leading Market Players |
|---|
| Pfizer |
| GlaxoSmithKline |
| Johnson & Johnson |
| Novartis |
| Sanofi |
| AstraZeneca |
| Boehringer Ingelheim |
| Reckitt Benckiser |
| Perrigo Company |
| Others |
Value Chain & Pricing Dynamics
Extended-release tablet manufacturing transitions are compressing unit economics for varenicline and bupropion formulations while concentrating API sourcing leverage among Indian and Chinese precursors suppliers. This production-method shift simultaneously elevates quality-assurance costs for FDA-compliant facilities and deepens dependency on specialized nicotine polacrilex resin manufacturers.
Pricing Analysis
Volume concentrates in over-the-counter nicotine replacement therapy patches and gums where Medicare Part D subsidies and employer wellness programs compress margins to single-digit territory. Prescription varenicline commands premium positioning through cardiology-monitored hospital protocols, with price differentiation driven by cardiovascular safety certification tiers and extended-release formulation patents. Pricing pressure stems from e-cigarette substitution in convenience retail channels diverting price-sensitive cessation seekers. Employer-sponsored wellness programs exhibit lowest price sensitivity due to bundled behavioral support contracts, while uninsured retail pharmacy customers face highest out-of-pocket exposure.
Supply Chain Analysis
Nicotine polacrilex resin and bupropion hydrochloride precursors rest on API manufacturers in India and China supplying over eighty percent of patch and tablet active ingredients. Raw material dependencies center on tobacco-derived nicotine extracts, pharmaceutical-grade polymers for transdermal matrices, and specialized coating excipients for extended-release tablets. Single-source vulnerability concentrates in nicotine resin purification where European botanical extraction capacity has contracted. Distribution runs through hospital system formularies for prescription therapies and retail pharmacy chains for over-the-counter formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into API supply and forward integration into digital therapeutic platforms defines the current vertical-integration race, with manufacturers capturing margin pools previously ceded to nicotine resin suppliers and behavioral counseling providers.
For Market Incumbents: Deploy manufacturing infrastructure leverage to sustain varenicline supply continuity amid FDA boxed warning documentation requirements. Consolidate position through exclusive formulary contracts with Veterans Health Administration facilities and cardiology-monitored hospital systems. Counter e-cigarette substitution threat by bundling sensor-augmented patches with employer wellness program adherence guarantees.
For New Entrants and Emerging Players: Direct-to-employer digital therapeutic platforms offer the most penetrable route, bypassing physician gatekeeping through smartphone-based craving prediction algorithms paired with OTC NRT fulfillment. Target state-level pharmacist prescribing authority expansions in rural United States markets where scope-of-practice reforms enable NRT dispensing without physician consultation. Pursue community pharmacy channel partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking cardiovascular safety-compliant prescription portfolios. Long-term viability hinges on five-to-ten year real-world evidence generation capabilities for EMA pharmacovigilance compliance. Watch FDA post-market surveillance requirement modifications as the critical inflection signal for varenicline reformulation investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Backward Integration | Captive nicotine polacrilex production mitigates single-source vulnerability from Indian and Chinese suppliers. |
| Digital Therapeutic Platform Launch | Smartphone craving prediction algorithms attract employer wellness contracts from manufacturing sector self-insured plans. |
| Extended-Release Formulation Patent | Once-daily dosing advantages secure formulary preference in Veterans Health Administration procurement tenders. |
| Community Pharmacy Channel Partnership | State scope-of-practice reforms enable direct pharmacist prescribing authority bypassing physician consultation delays. |
| Cardiovascular Safety Database Investment | Five-year patient registries satisfy EMA pharmacovigilance guidelines for centralized EU marketing authorization. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA adverse event reporting system extracts, EMA submission documents, ClinicalTrials.gov protocols, and CMS Medicare reimbursement databases provided structured validation. Bottom-up patient-volume modeling triangulated against top-down pharmaceutical expenditure estimates across the analysis window.
Granularity extended to drug type, delivery mode, end-user institution, and formulation release kinetics for volume and value outputs over the projection horizon. CAGRs derived from longitudinal prescription audit data and real-world adherence metrics. Forecast inputs incorporated Medicare Part D coverage expansion trajectories and WHO Framework Convention Article 14 implementation timelines across signatory nations.
The model holds under stable FDA pharmacovigilance requirements and uninterrupted API trade flows; deviation in cardiovascular safety alert severity or nicotine resin export restrictions would shift prescription volume forecasts. A small set of named triggers—boxed warning modifications, pharmacist scope-of-practice legislation, and employer wellness procurement fragmentation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Pregabalin Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Peptic Ulcer Drugs Market