
 Brugada Syndrome Treatment Market | 2026-2036
Brugada Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Brugada Syndrome Treatment Market Outlook
Japan's electrophysiology infrastructure build-out is reshaping regional access to advanced Brugada interventions. Medtronic leverages its integrated catheter and device portfolio to sustain leadership in implantable systems across East Asian markets. Abbott Laboratories anchors its position through specialized diagnostic catheter technology that supports precise risk stratification workflows. Boston Scientific Corporation competes on device miniaturization and battery longevity, differentiating its ICD offerings for younger patient cohorts.
Brugada syndrome treatment encompasses pharmacological and interventional modalities targeting a channelopathy characterized by ST-segment elevation in V1-V3 leads and heightened risk of sudden cardiac death. Implantable cardioverter defibrillators deliver tiered antitachycardia pacing and high-energy shocks, with modern devices incorporating subcutaneous lead systems to reduce vascular complications. Antiarrhythmic drugs, particularly quinidine, retain structural importance for electrical storm suppression and bridge-to-device scenarios in resource-limited settings. The indication dimension reveals primary prevention as the dominant revenue pool, while symptomatic management through pharmacotherapy represents a faster-growing segment driven by ambulatory monitoring expansion.
FDA premarket approval requirements and CE marking under the EU Medical Device Regulation impose escalating clinical evidence burdens on novel ICD and catheter submissions. Japan's PMDA maintains distinct pharmacovigilance protocols for antiarrhythmic agents, shaping post-approval study commitments for multinational sponsors. Stakeholders must monitor evolving reimbursement thresholds for subcutaneous versus transvenous ICD systems as health technology assessment bodies recalibrate value frameworks.
Market Dynamics
Subcutaneous ICD technology is compressing procedural timelines and expanding candidate pools beyond traditional transvenous indications, forcing recalibration of electrophysiology service line economics across cardiac centers.
Growth Catalysts
- Japan's PMDA screening protocols:National electrophysiology specialization mandates are channeling diagnostic volumes toward tertiary centers equipped for advanced ablation and device implantation.
- Ambulatory arrhythmia monitoring:Extended-wear patch technologies are capturing cryptogenic syncope episodes that previously escaped detection, expanding the addressable patient base for risk stratification workflows.
- Quinidine pharmacovigilance frameworks:Structured post-approval study commitments under Japan's PMDA are generating real-world evidence that supports expanded labeling for electrical storm suppression.
Market Restraints
- Platinum-iridium electrode supply concentration:Refining capacity for catheter electrode materials clusters in limited geographic corridors, exposing device manufacturers to input cost volatility.
- EU MDR clinical evidence requirements:Class III cardiac device submissions now demand extended follow-up cohorts, extending regulatory friction and compressing competitive windows for novel ICD form factors.
- Transvenous lead extraction complexity:Vascular complication risks associated with legacy lead systems are constraining upgrade pathways and deferring replacement decisions.
Strategic Opportunities
- Subcutaneous ICD reimbursement recalibration:Health technology assessment bodies in Japan are revisiting value frameworks for leadless systems, creating tailwinds for procedural volume expansion.
- Electrophysiology training network gaps:Underpenetrated provinces in Southeast Asia present white space for catheter ablation service line deployment through academic medical center partnerships.
- Remote monitoring integration:Convergence of cloud-based transmission platforms with predictive analytics is enabling shift from reactive shock therapy to preemptive intervention protocols.
Industry Challenges
- Electrophysiologist workforce density:Fellowship-trained specialist scarcity in secondary Japanese cities is constraining procedural throughput despite installed device capacity.
- CE marking transition timelines:Legacy certificate expiration under EU MDR is forcing portfolio rationalization decisions ahead of notified body capacity recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brugada Syndrome Treatment Market |
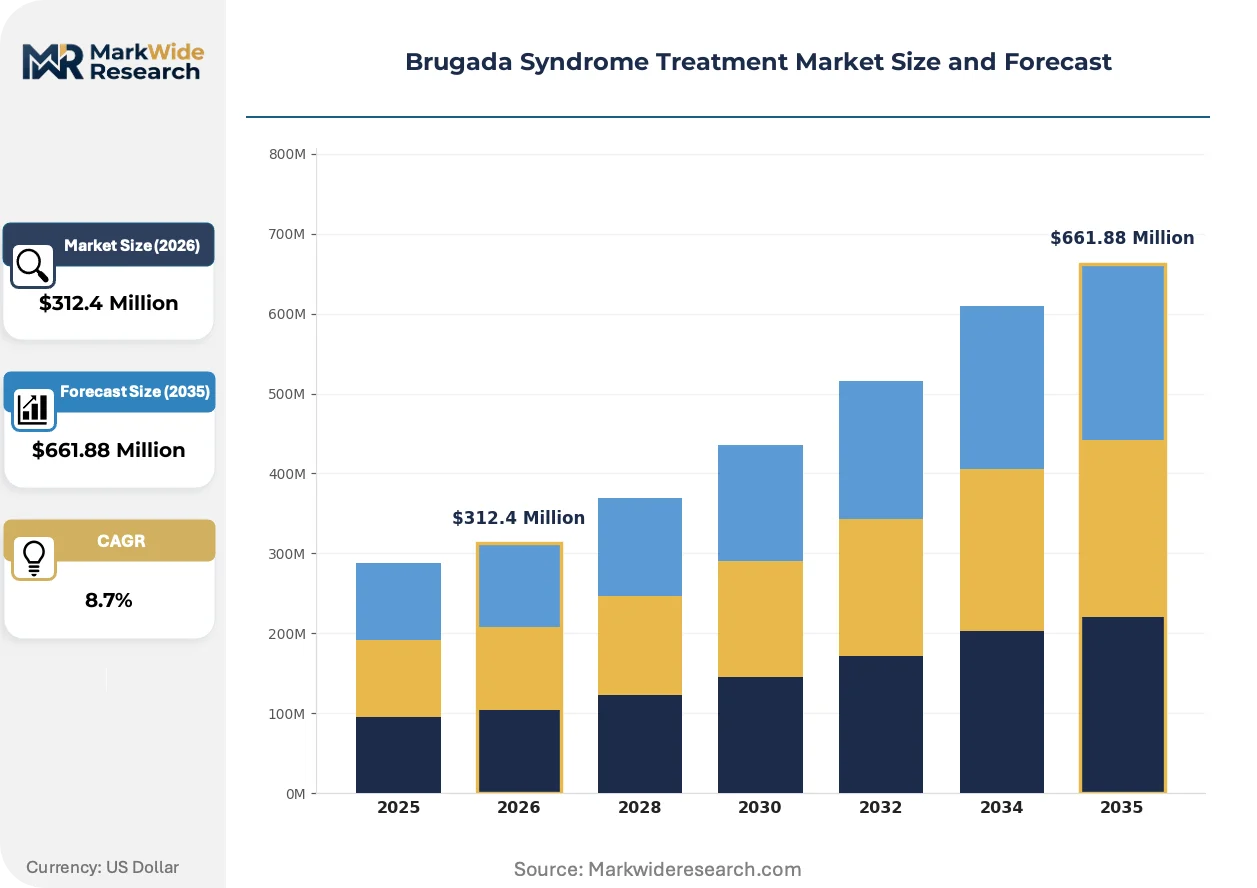
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiarrhythmic Drugs, Implantable Cardioverter Defibrillators, Catheters, Monitoring Devices End User: Hospitals, Cardiac Clinics, Research Institutes, Home Care Settings Delivery Mode: Intravenous, Oral, Transdermal, Subcutaneous Indication: Primary Prevention, Secondary Prevention, Pacing Therapy, Symptomatic Management |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Novartis AG, Pfizer, AstraZeneca, LivaNova, Johnson & Johnson, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brugada Syndrome Treatment Market Strategic Shifts
Device miniaturization and algorithmic sophistication are converging to reshape risk stratification workflows and post-implant surveillance economics in Brugada syndrome management.
Subcutaneous ICD systems with extravascular sensing electrodes are hybridizing the therapeutic paradigm by eliminating transvenous lead dependency while preserving antitachycardia pacing capability. Cardiac centers in Japan are adopting these systems for younger patient cohorts where lead longevity concerns previously deferred implantation decisions. The technology is hybridizing service line planning by collapsing the traditional boundary between electrophysiology and thoracic surgery departments.
EU MDR post-market surveillance requirements are intensifying clinical evidence obligations for Class III cardiac devices, mandating extended follow-up registries that capture long-term lead performance. Device manufacturers are restructuring quality management systems to accommodate periodic safety update reports and trend analysis obligations. Subcutaneous ICD submissions are most affected, as notified bodies demand comparator data against established transvenous benchmarks.
After-sales service unbundling is emerging as procurement departments in Japanese university hospitals separate device acquisition from long-term remote monitoring contracts. Third-party monitoring platforms are capturing transmission infrastructure contracts that device manufacturers previously bundled with hardware sales. This decoupling is most visible in Tokyo and Osaka metropolitan clusters where consolidated purchasing authorities command leverage over vendor lock-in strategies.
Brugada Syndrome Treatment Market Segmentation
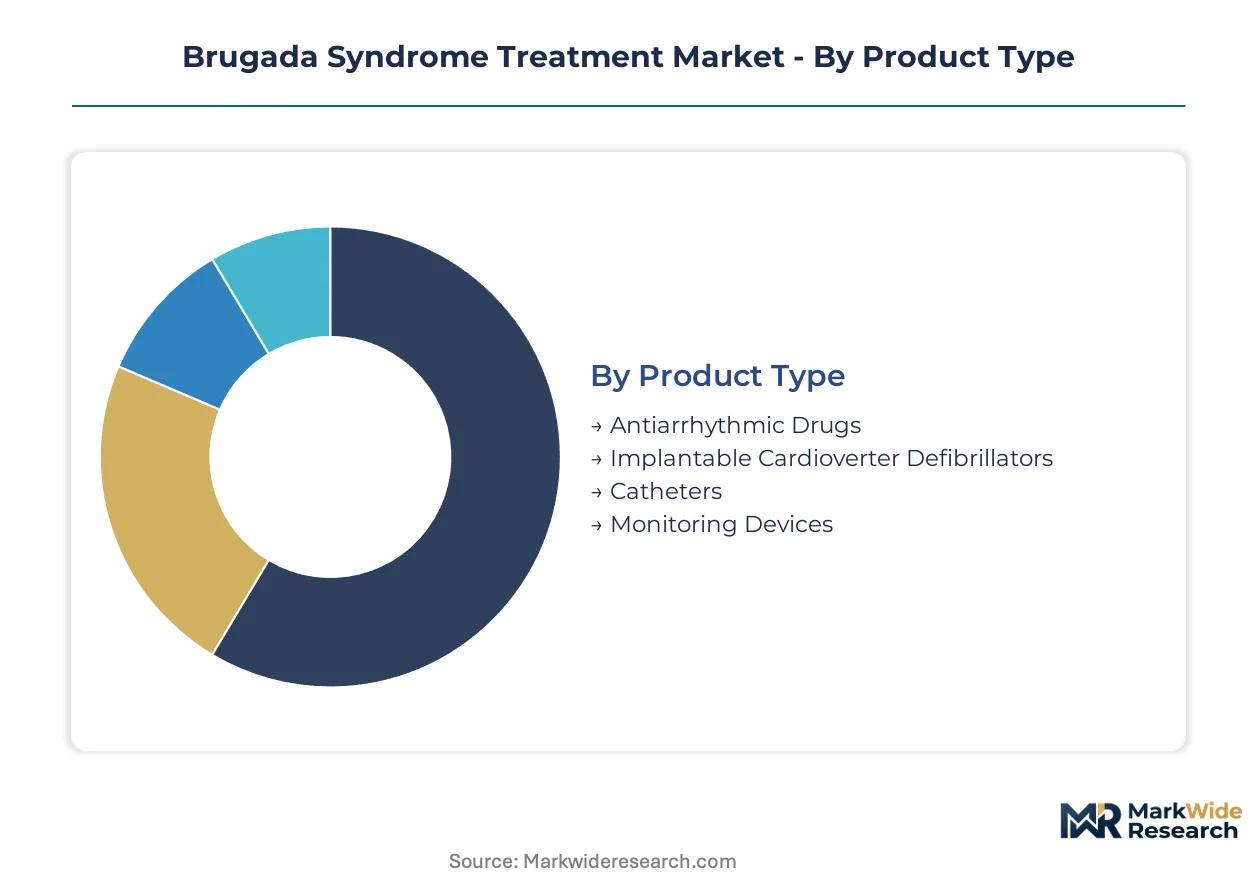
Brugada syndrome treatment modalities span device-based interventions, pharmacological management, and diagnostic workflows. Segmentation reveals how reimbursement pathways, procedural complexity, and patient acuity stratify commercial opportunity across distinct product and service categories.
Product Type:
Mature implantable systems coexist with emerging diagnostic platforms, creating divergent margin profiles and replacement cycle dynamics.
- Antiarrhythmic Drugs:Quinidine and isoproterenol formulations provide acute electrical storm suppression and bridge-to-device therapy. Demand concentrates in Japanese emergency departments and Philippine provincial hospitals where device implantation capacity remains constrained.
- Implantable Cardioverter Defibrillators:Tiered antitachycardia pacing and high-energy shock delivery systems incorporate subcutaneous lead configurations to reduce vascular complications. Japanese cardiac centers in Tokyo and Osaka are expanding procedural volumes for younger cohorts seeking leadless alternatives.
- Catheters:Electrophysiology mapping and ablation catheters enable substrate modification in high-risk phenotypes.
- Monitoring Devices:Extended-wear patch technologies capture cryptogenic syncope episodes for risk stratification.
Implantable Cardioverter Defibrillators handle the majority of throughput; Monitoring Devices are climbing the fastest on share.
End User:
Institutional capacity and reimbursement tiering shape where procedural economics concentrate versus fragment.
- Hospitals:Tertiary academic medical centers maintain electrophysiology suites with hybrid operating room configurations for complex device extractions. Japan's national university hospitals in Kyoto and Fukuoka anchor regional referral networks for high-risk Brugada phenotypes.
- Cardiac Clinics:Specialized ambulatory centers perform diagnostic workup and remote monitoring follow-up. Southeast Asian private clinic chains in Bangkok and Jakarta are deploying subcutaneous ICD screening protocols to capture patients deferred from hospital queues.
- Research Institutes:Genotyping and familial screening programs drive longitudinal cohort enrollment.
- Home Care Settings:Post-implant remote monitoring and pharmacotherapy adherence management shift care outside institutional walls.
Hospitals retain the dominant revenue position; Cardiac Clinics are expanding most quickly as service line unbundling accelerates.
Delivery Mode:
Route selection reflects acuity gradients, bioavailability requirements, and vascular access risk profiles.
- Intravenous:Rapid bioavailability for electrical storm stabilization and peri-procedural arrhythmia suppression. Japanese emergency medical services protocols mandate IV isoproterenol availability for Brugada-triggered ventricular fibrillation events.
- Oral:Chronic quinidine maintenance therapy and outpatient rhythm control. Philippine rural health units rely on oral formulations where cold-chain infrastructure for biologics remains unreliable.
- Transdermal:Alternative absorption pathways for patients with compromised gastrointestinal function.
- Subcutaneous:Leadless device delivery and depot formulations for extended pharmacokinetic profiles.
Oral administration dominates chronic management volumes; Subcutaneous delivery is gaining share fastest through device innovation.
Indication:
Prophylactic versus reactive intervention paradigms split the market across risk-stratification sophistication levels.
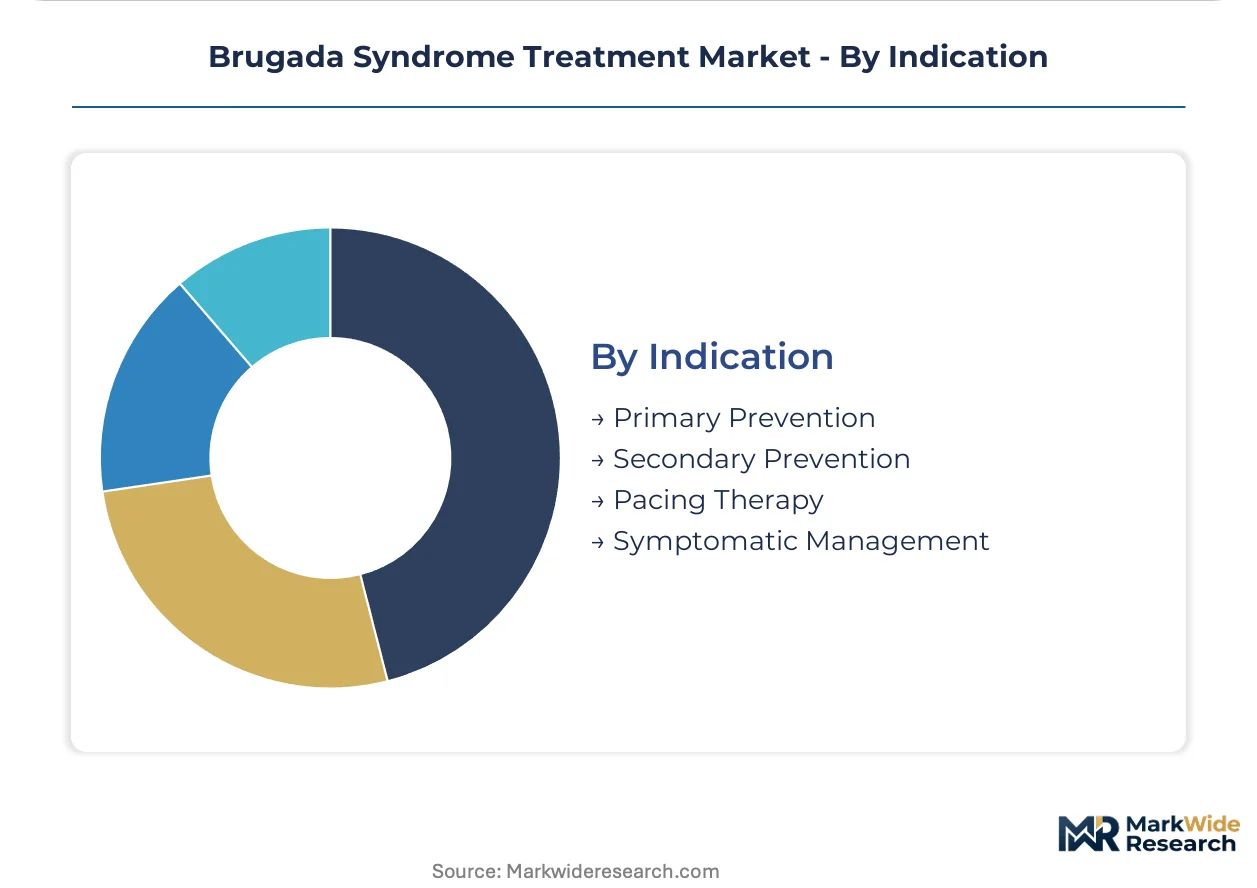
- Primary Prevention:ICD implantation for asymptomatic patients with spontaneous Type 1 ECG patterns and family history of sudden death. Japanese PMDA screening protocols in Osaka and Nagoya are channeling diagnostic volumes toward tertiary centers equipped for risk stratification.
- Secondary Prevention:Device therapy following aborted sudden cardiac death or documented ventricular arrhythmia. Indonesian national health insurance expansion is broadening access to secondary prevention ICDs in Surabaya and Bandung.
- Pacing Therapy:Antibradycardic and antitachycardic pacing configurations for rhythm stabilization.
- Symptomatic Management:Pharmacological suppression of palpitations and syncope episodes without definitive device therapy.
Primary Prevention captures the largest installed base; Symptomatic Management is expanding most quickly through ambulatory monitoring penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refining capacity for catheter electrode materials clusters in limited geographic corridors, exposing device manufacturers to input cost volatility. Japan anchors regional procedural volumes through national screening protocols, while Southeast Asian cardiac clinics expand subcutaneous ICD adoption. European notified bodies impose extended follow-up requirements under MDR frameworks.
Japan
PMDA electrophysiology specialization mandates channel diagnostic volumes toward tertiary centers in Tokyo and Osaka equipped for advanced ablation. Japan's national health insurance recalibration for leadless systems creates reimbursement tailwinds for younger patient cohorts. The Kansai region surrounding Osaka anchors regional referral networks for high-risk Brugada phenotypes requiring complex device extraction.
United States
FDA premarket approval pathways for Class III cardiac devices demand extended clinical evidence cohorts, compressing competitive windows for novel ICD form factors. The agency's tightening requirements for subcutaneous system submissions force comparator studies against transvenous benchmarks. Boston and Minneapolis metropolitan clusters concentrate electrophysiology training programs and device manufacturer headquarters.
Germany
CE marking transition timelines under EU MDR force portfolio rationalization decisions as legacy certificates expire ahead of notified body capacity recovery. Germany's national health technology assessment body recalibrates value frameworks for leadless versus transvenous ICD systems. The Rhine-Ruhr and Bavarian medical device clusters host specialized catheter manufacturing and electrophysiology research institutes.
China
NMPA regulatory harmonization initiatives accelerate local clinical trial requirements for imported cardiac devices while domestic manufacturers expand subcutaneous ICD development. China's dual carbon goals influence medical device manufacturing energy efficiency standards. Shanghai and Shenzhen electrophysiology centers pioneer remote monitoring integration with cloud-based transmission platforms.
Australia
TGA post-market surveillance requirements for Class III cardiac devices align with extended follow-up registry mandates capturing long-term lead performance data. Australia's pharmaceutical benefits scheme maintains distinct reimbursement thresholds for quinidine maintenance therapy in electrical storm suppression. Sydney and Melbourne cardiac institutes anchor familial screening programs driving longitudinal cohort enrollment for research protocols.
Brugada Syndrome Treatment Market Competitive Environment
Integrated device manufacturers and specialized pharmaceutical developers split the market across interventional and pharmacological modalities. Consolidation pressures concentrate around catheter electrode supply chains and remote monitoring platform unbundling. Three archetypes dominate: diversified medtech conglomerates with electrophysiology portfolios, mid-cap cardiac rhythm management specialists, and research-driven pharmaceutical firms with antiarrhythmic pipelines. Competitive moves center on M&A for catheter technology capabilities and strategic partnerships for third-party monitoring infrastructure.
Within the diversified medtech tier, Medtronic and Abbott Laboratories exemplify integrated portfolio strategies spanning implantable systems and diagnostic workflows. Boston Scientific Corporation occupies a position emphasizing device miniaturization and battery longevity differentiation. Among pharmaceutical developers, Novartis AG and Pfizer anchor antiarrhythmic drug segments through established quinidine and isoproterenol formulations. These named entities represent strategic archetypes rather than exhaustive market coverage, with additional participants including LivaNova, Johnson & Johnson, Bayer, and AstraZeneca contributing to segment-specific competitive dynamics.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Novartis AG |
| Pfizer |
| AstraZeneca |
| LivaNova |
| Johnson & Johnson |
| Bayer |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's container rate volatility transmits directly into landed costs for platinum-iridium electrode consignments, compressing margin buffers for catheter manufacturers while amplifying price spreads between CE-marked and non-certified device tiers across European and East Asian procurement desks.
Pricing Analysis
EU MDR dictates the pricing tier structure for Class III cardiac devices, separating premium-labeled systems with extended follow-up registries from standard-tier submissions lacking comparator data against transvenous benchmarks. Price differentiation centers on certification completeness and after-sales service bundling, with Japanese university hospitals now unbundling remote monitoring contracts to drive procurement leverage. Pricing pressure stems from notified body capacity constraints extending regulatory timelines and inflating compliance overhead. Cardiac clinics in Southeast Asia exhibit highest price sensitivity, while tertiary academic centers in Tokyo and Osaka prioritize lead longevity and algorithmic sophistication over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for electrophysiology catheter manufacturers, forcing dual-sourcing strategies for platinum-iridium electrode materials. Refining capacity clusters in South Africa, Russia, and Canada, with finished catheter assembly concentrated in Costa Rica, Malaysia, and Ireland. Raw material dependencies center on platinum group metals, iridium wire stock, and biocompatible polymer sheathing. Single-source vulnerability persists for high-purity iridium feedstock given limited global smelter capacity. Distribution runs through device manufacturer direct sales forces in developed markets, shifting to specialized cardiovascular distributors in Southeast Asian growth corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subcutaneous ICD technology is disrupting established electrophysiology economics, with FDA and PMDA regulatory pathways for leadless systems compressing competitive windows and rewarding first-movers with extended data exclusivity.
For Market Incumbents: Pre-empt emerging entrant challenges by securing captive platinum-iridium electrode supply through backward integration into precious metals refining partnerships, while accelerating CE marking submissions ahead of legacy certificate expiration under EU MDR transition timelines. Channel control through exclusive remote monitoring platform contracts remains essential as Japanese procurement authorities unbundle service offerings.
For New Entrants and Emerging Players: Indonesian provincial cardiac clinics outside Jakarta and Surabaya represent the most penetrable geography for subcutaneous ICD screening protocols, with national health insurance expansion broadening reimbursement access. Target diagnostic catheter partnerships with Bangkok-based private clinic chains as the fastest go-to-market angle, leveraging ambulatory monitoring integration to bypass established hospital queue constraints.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-cap cardiac rhythm management specialists with subcutaneous ICD regulatory submissions already filed and electrophysiology training network relationships in secondary Japanese cities. Long-term viability hinges on remote monitoring platform convergence with predictive analytics capabilities. Watch FDA premarket approval timelines for leadless systems as the critical inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Submission for Subcutaneous ICD | Japan's reimbursement recalibration for leadless systems creates procedural volume tailwinds for early entrants. |
| CE Marking Pathway Acceleration | EU MDR transition timelines compress competitive windows for novel ICD form factors requiring extended follow-up. |
| Hospital System Partnership | Tertiary center alliances in Osaka and Fukuoka anchor regional referral networks for high-risk phenotypes. |
| Software Companion Development | Cloud-based transmission platforms with predictive analytics enable shift from reactive to preemptive intervention protocols. |
| Reimbursement Strategy | Health technology assessment body engagement in Japan and Germany recalibrates value frameworks for leadless versus transvenous systems. |
Study Parameters
A spread of perspectives from electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary interviews with device manufacturer regulatory affairs leads and catheter electrode material suppliers were cross-referenced against FDA 510(k) and PMA filings, PMDA approval summaries, and EU MDR notified body guidance documents. Bottom-up procedural volume estimates from Japanese cardiac centers and Southeast Asian clinic chains were triangulated with top-down market sizing from national health insurance reimbursement data.
Demand-supply balance framing anchored the forecast framework across the projection horizon, modeling segmentation dimensions spanning device type, delivery mode, indication severity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to procedural volume trajectories, with specific inputs including PMDA electrophysiology specialization mandate implementation schedules and subcutaneous ICD reimbursement threshold revisions by Japan's Central Social Insurance Medical Council.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medtech conglomerates into precious metals refining or predictive analytics platform acquisition would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Angina Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Atherosclerosis Therapeutics Market