
 Dose Monitoring Devices Market | 2026-2036
Dose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dose Monitoring Devices Market Foresight
Software-defined analytics layers is rebalancing how dose monitoring contracts are structured, pulling recurring revenue ahead of hardware margins. Siemens Healthcare leverages its imaging install base to bundle dose tracking with CT and angiography systems. Mirion Technologies Inc. anchors its position through specialized dosimetry services for nuclear medicine departments. Thermo Fisher Scientific competes by extending laboratory-grade calibration protocols into clinical radiation monitoring workflows.
Dose monitoring devices measure ionizing radiation exposure through solid-state or gas-filled detectors, quantifying absorbed dose in grays or sieverts to protect medical personnel and patients from cumulative radiation harm. Portable monitors and wearable devices lead unit shipments, while cloud-based platforms capture the fastest expansion as hospitals integrate real-time dose dashboards with existing IT infrastructure. Software solutions concentrate margin pools where subscription renewals and regulatory compliance reporting create recurring value.
FDA radiation safety requirements and the EU Medical Device Regulation shape product standards for electromagnetic compatibility and clinical validation, directly influencing design cycles and market access timelines. The EPA and OSHA maintain overlapping jurisdiction for occupational exposure limits in US healthcare settings, creating dual compliance obligations for device manufacturers. Stakeholders must weigh cloud data residency rules against the operational benefits of centralized dose registries as procurement criteria evolve.
Market Dynamics
Cloud-based dose registries are compressing hospital procurement cycles from multi-year capital commitments to annual SaaS renewals, forcing hardware vendors to restructure revenue models around recurring compliance services.
Growth Catalysts
- Wearable solid-state detectors:German hospital networks mandate real-time staff monitoring under BfS occupational exposure rules, accelerating replacement of film badge systems.
- EHR integration mandates:US health systems face Joint Commission accreditation pressure to document radiation dose in patient records, pulling software subscriptions forward.
- Nuclear medicine expansion:Theranostics programs in France and Belgium require continuous personnel dosimetry, expanding addressable hardware install bases.
Market Restraints
- Semiconductor supply concentration:Silicon photomultiplier production concentrates in East Asian foundries, exposing detector manufacturers to single-source fragility.
- MDR certification timelines:EU notified body backlogs extend clinical validation periods for new wearable form factors, delaying market entry by 18-24 months.
- Calibration gas scarcity:Xenon-133 and krypton-85 shortages inflate maintenance costs for gas-filled ionization chambers used in legacy hospital installations.
Strategic Opportunities
- Interventional radiology underpenetration:Latin American catheterization labs operate without continuous staff monitoring, representing unserved installed base.
- AI-augmented anomaly detection:Machine learning overlays on dose dashboards enable predictive exposure alerts, differentiating premium software tiers.
- Veterinary oncology:Pet radiation therapy clinics in Japan and Australia lack occupational safety infrastructure, creating channel expansion potential.
Industry Challenges
- Health physics talent scarcity:Certified medical physicist training programs in the US and Germany fail to match hospital hiring velocity, constraining device utilization.
- Legacy PACS integration:DICOM-RT dose objects require custom middleware to populate older radiology information systems, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dose Monitoring Devices Market |
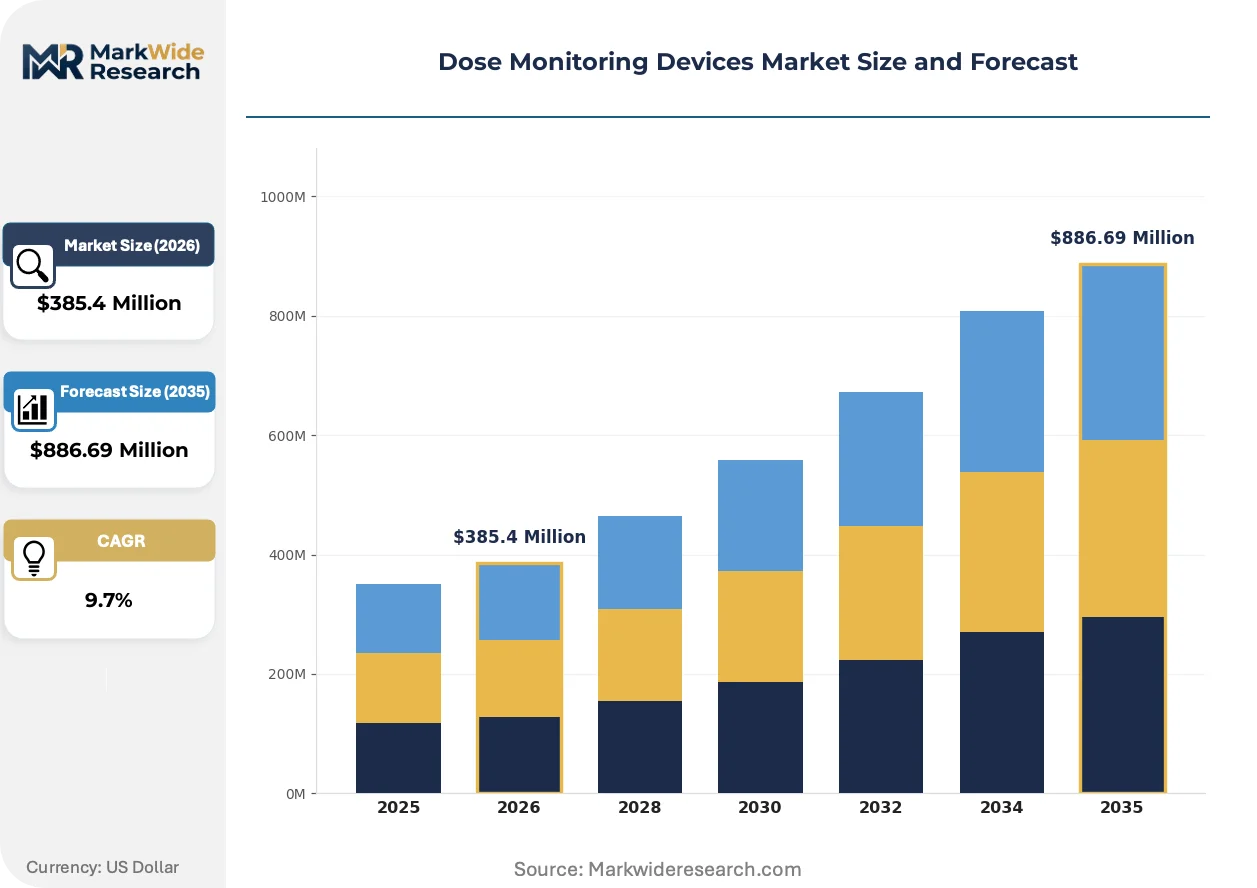
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Monitors, Wearable Devices, Smartphone Integrations Technology: Digital Sensors, Analog Sensors, Software Solutions, Cloud-Based Platforms End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Diagnostic Centers Application: Radiotherapy, Chemotherapy, Clinical Trials, Home Care |
| Companies Covered | GE Healthcare, Siemens Healthcare, Mirion Technologies Inc., FUJIFILM Holdings Corporation, Fortive Corporation, Landauer Inc., Philips Healthcare, Canon Inc., Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dose Monitoring Devices Market Shifts & Advancements
Real-time connectivity architectures are displacing batch-processed dose reporting, enabling proactive exposure intervention rather than retrospective compliance documentation.
Artificial intelligence is automating pattern recognition in cumulative exposure trajectories, flagging anomalous readings before regulatory thresholds trigger. Interventional cardiologists at US academic medical centers deploy these tools during complex electrophysiology procedures. The technology is compressing liability exposure for hospital risk managers while reducing manual data review burdens.
The EU Medical Device Regulation's post-market surveillance requirements impose systematic clinical follow-up obligations on wearable dosimeter manufacturers. German notified bodies interpret MDR Article 83 to mandate annual performance verification for active implantable adjacent devices. French hospital purchasing consortia now embed these compliance costs into total-cost-of-ownership calculations, disadvantaging vendors without European service infrastructure.
Subscription pricing for dose analytics is displacing perpetual software licenses in North American health system RFPs. Procurement committees at integrated delivery networks prioritize interoperability scores over standalone device specifications. This behavioral shift concentrates contract value with vendors offering API-first architectures that federate data across multi-hospital footprints, particularly visible in California and Texas IDN consolidation activity.
Dose Monitoring Devices Market Segmentation
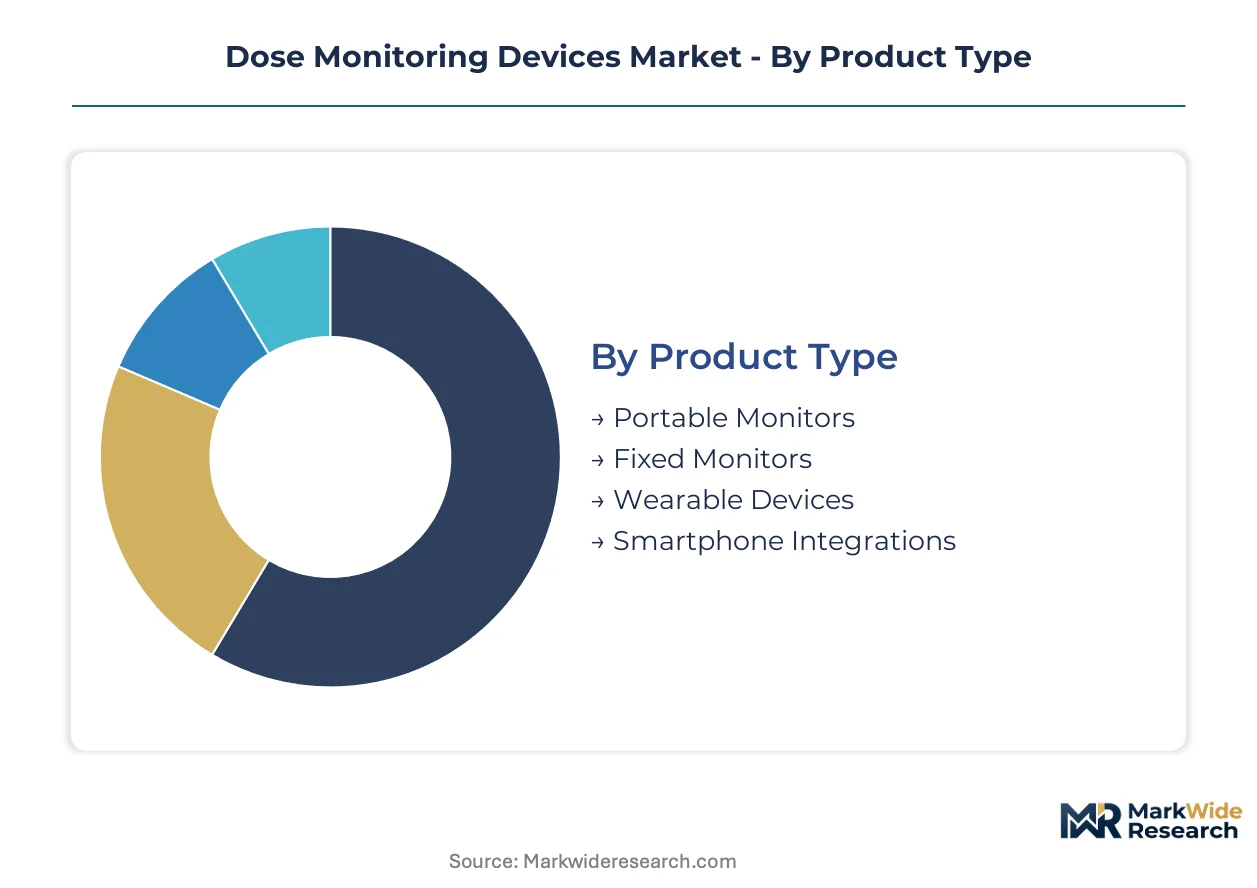
Dose monitoring devices fragment across hardware form factors, detection architectures, and clinical workflows. Procurement committees evaluate total-cost-of-ownership across calibration requirements, integration complexity, and regulatory compliance pathways.
Product Type:
Solid-state miniaturization and wireless telemetry are redistributing unit economics across form factor categories.
- Portable Monitors:Handheld ionization chambers and scintillation probes serve mobile health physics teams during equipment commissioning. German hospital networks deploy these for quarterly beam output verification in radiotherapy suites.
- Wearable Devices:Clip-on solid-state dosimeters transmit real-time exposure data via Bluetooth to cloud registries. BfS occupational exposure mandates in Germany accelerate replacement of film badge systems with continuous monitoring.
- Fixed Monitors:Wall-mounted area monitors with gamma-neutron discrimination protect controlled radiation zones. Installations concentrate in cyclotron facilities and radioisotope production suites.
- Smartphone Integrations:CMOS-based accessories pair with clinical smartphones for decentralized dose verification. Early pilots target veterinary oncology clinics in Japan.
Wearable devices lead on scale; smartphone integrations lead on momentum.
Technology:
Detection modality determines calibration protocols, maintenance cadence, and margin structure across the technology stack.
- Digital Sensors:Silicon photomultipliers and CMOS arrays enable single-photon counting with microgray resolution. Supply concentration in East Asian foundries exposes manufacturers to single-source fragility.
- Cloud-Based Platforms:SaaS dose registries compress hospital procurement from capital cycles to annual renewals. FDA 21 CFR Part 11 validation requirements shape software development timelines for US deployments.
- Software Solutions:Analytics layers automate regulatory reporting and anomaly detection. Subscription pricing displaces perpetual licenses in North American health system RFPs.
- Analog Sensors:Gas-filled ionization chambers and Geiger-Müller tubes persist in legacy installations. Xenon-133 and krypton-85 shortages inflate maintenance costs for calibration-dependent hardware.
Digital sensors anchor installed base value; cloud-based platforms capture the steepest expansion trajectory.
End User:
Procurement authority and compliance obligations vary sharply across institutional categories.
- Healthcare Providers:Hospital networks bundle dose tracking with imaging system purchases. Joint Commission accreditation pressure pulls software subscriptions forward in US markets.
- Research Institutions:Academic medical centers deploy AI-augmented anomaly detection during complex electrophysiology procedures.
- Diagnostic Centers:Independent imaging facilities prioritize interoperability scores over standalone device specifications in procurement evaluations.
- Pharmaceutical Companies:Radiopharmaceutical manufacturing operations require continuous personnel dosimetry under EMA guidelines.
Healthcare providers dominate contract volume; pharmaceutical companies concentrate spending per site.
Application:
Clinical setting dictates exposure patterns, regulatory scrutiny, and integration requirements.
- Radiotherapy:Linear accelerator suites require real-time staff monitoring during patient treatments. MDR post-market surveillance mandates annual performance verification for active dosimetry systems.
- Clinical Trials:Protocol-mandated dose documentation drives software adoption across multi-site oncology studies.
- Chemotherapy:Handling of radiolabeled compounds in compounding pharmacies requires area monitoring and personnel badges.
- Home Care:Ambulatory patients receiving radiopharmaceutical therapies present emerging monitoring requirements for household exposure assessment.
Radiotherapy commands premium pricing; home care represents the most nascent addressable expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as manufacturers relocate production to jurisdictions with streamlined medical device certification pathways. Compliance cost differentials between the EU MDR and FDA frameworks now influence where dose monitoring device assembly concentrates.
Germany
The Federal Office for Radiation Protection enforces the strictest occupational exposure limits for medical staff across Europe, mandating real-time wearable monitoring in catheterization labs. BfS regulations require quarterly performance verification for all active dosimetry systems deployed in hospital networks. Manufacturing clusters in Bavaria and Baden-Württemberg host precision sensor fabrication for Siemens Healthcare and regional OEM suppliers.
United States
Joint Commission accreditation standards now require documented radiation dose tracking in patient electronic health records, accelerating software subscription adoption at integrated delivery networks. FDA 21 CFR Part 11 validation requirements shape cloud platform development timelines for domestic deployments. Texas and California health systems lead procurement volume, with Houston Methodist and Stanford Health Care deploying enterprise-wide dose registries.
France
Theranostics expansion at Gustave Roussy and Curie Institute facilities drives continuous personnel dosimetry demand for radiopharmaceutical handling operations. ANSM post-market surveillance obligations align with MDR Article 83 mandates for annual device performance verification. The Paris-Saclay medical technology cluster anchors regional distribution infrastructure for wearable detector systems.
Japan
PMDA streamlined approval pathways for software-as-a-medical-device are attracting cloud-based dose analytics vendors seeking faster market entry than EU or US routes permit. METI industrial standards for electromagnetic compatibility govern detector interoperability with imaging equipment. Osaka-based manufacturing facilities supply solid-state sensors throughout the Asia-Pacific region.
United Kingdom
Medicines and Healthcare products Regulatory Agency guidance on radiation protection in healthcare settings maintains alignment with pre-Brexit EU standards while introducing UKCA marking requirements for new device registrations. London teaching hospitals and Manchester cancer centers concentrate procurement authority for national health service trusts. Cambridge medical physics research clusters support calibration service networks.
Dose Monitoring Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with imaging system OEMs bundling dose tracking software alongside hardware purchases while independent dosimetry service providers capture recurring calibration revenue. The market structure concentrates around three strategic archetypes: diversified imaging conglomerates leveraging install base relationships, specialized radiation safety vendors with health physics expertise, and laboratory instrumentation companies extending analytical protocols into clinical settings. Dominant competitive moves include strategic partnerships between detector manufacturers and cloud platform developers, plus geographic expansion through notified body certification in multiple jurisdictions.
Among diversified imaging conglomerates, GE Healthcare and Siemens Healthcare exemplify the bundling archetype, anchoring competitive positioning through captive distribution channels embedded in radiology department procurement workflows. Mirion Technologies Inc. occupies a distinct tier as a specialized radiation safety vendor, representing the pure-play dosimetry service model. Thermo Fisher Scientific exemplifies the laboratory-to-clinical extension strategy, leveraging analytical instrumentation credibility to penetrate hospital quality assurance workflows.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthcare |
| Mirion Technologies Inc. |
| FUJIFILM Holdings Corporation |
| Fortive Corporation |
| Landauer Inc. |
| Philips Healthcare |
| Canon Inc. |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap sensor specialists in Bavaria and Baden-Württemberg anchor German precision manufacturing clusters, translating captive calibration expertise into pricing discipline that resists commoditization pressures from Asian module assemblers. Their ownership structure insulates long-term R&D commitments from quarterly margin compression, reinforcing supply security premiums in hospital procurement evaluations.
Pricing Analysis
Capacity additions in Japan and Taiwan are reshaping price floors for silicon photomultiplier arrays, compressing hardware margins while cloud-based SaaS tiers capture recurring value. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated enterprise deployments from CE-marked regional offerings and unbundled sensor modules. Pricing pressure stems from semiconductor foundry consolidation in East Asia, which constrains detector manufacturers to volume commitments. Independent imaging facilities exhibit highest price sensitivity; integrated delivery networks prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Siemens Healthcare and GE Healthcare, while specialized dosimetry service providers distribute through health physics consulting networks. Manufacturing concentrates in Germany, Japan, and the United States for precision sensor fabrication, with final assembly drawing from Malaysian and Mexican facilities to manage tariff exposure. Xenon-133 and krypton-85 isotope supply rests on limited radiopharmaceutical production sites, creating single-source vulnerability for gas-filled detector calibration. Distribution runs through hospital procurement consortia in Europe and group purchasing organizations in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dose Monitoring Devices Market functions as a stable compounder, with regulatory mandates for occupational exposure tracking generating predictable replacement cycles and SaaS renewal streams.
For Market Incumbents: Lock in hospital system partnerships through API-first architectures that federate dose data across multi-hospital footprints, defending against cloud-native entrants. Pursue backward integration into silicon photomultiplier supply through strategic foundry agreements in Japan, mitigating East Asian single-source fragility. Accelerate MDR Article 83 compliance infrastructure to capture French and German purchasing consortia evaluating total-cost-of-ownership. For New Entrants and Emerging Players: Veterinary oncology clinics in Japan and Australia present unserved installed base with minimal incumbent presence and simplified regulatory pathways. Interventional radiology labs in Latin American catheterization facilities operate without continuous staff monitoring, offering white-space expansion. Pursue smartphone-integrated CMOS accessories for decentralized verification, bypassing capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized radiation safety vendors lacking imaging OEM bundling relationships, particularly those with health physics service infrastructure. Five-to-ten-year viability hinges on cloud platform recurring revenue ratios exceeding hardware dependency. Monitor FDA 21 CFR Part 11 validation completion timelines as inflection indicator for US market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | API-first architectures capture multi-hospital IDN contracts in California and Texas consolidation zones. |
| CE Marking Pathway | MDR Article 83 compliance unlocks French purchasing consortia embedding verification costs into TCO calculations. |
| Software Companion Development | AI-augmented anomaly detection differentiates premium tiers for US academic medical center electrophysiology programs. |
| FDA Submission | 21 CFR Part 11 validation accelerates cloud platform adoption at Joint Commission-accredited health systems. |
| Reimbursement Strategy | Documentation of radiation dose in EHRs satisfies accreditation pressure pulling subscription renewals forward. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers, health physicists, and GPO contracts managers grounded qualitative findings, cross-referenced against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit shipment estimates triangulated with top-down addressable market sizing across hardware form factors and SaaS penetration assumptions.
Segment-level CAGRs derived from modeled adoption curves across wearable devices, portable monitors, fixed installations, and cloud-based platforms, with technology splits for solid-state digital sensors versus analog gas-filled detectors. End-user stratification incorporated healthcare provider consolidation patterns, research institution grant funding cycles, and pharmaceutical radiopharmaceutical manufacturing expansion trajectories throughout the projection horizon.
Underlying measurement precision varies by segment; cloud-based platform revenue carries tighter precision than nascent smartphone integration pilots. Forecasts reflect assumptions regarding BfS enforcement continuity, MDR notified body backlog resolution, and semiconductor supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Global Medical Implants Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Pharmacy Automation Devices Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Ventilators Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Global Interspinous Spacers Market