
 SGLT2 Inhibitors Market | 2026-2036
SGLT2 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
SGLT2 Inhibitors Market Outlook
Hospital-based cardiologists are unwinding the traditional endocrinology-centric prescription pattern for SGLT2 inhibitors as heart failure and chronic kidney disease indications reshape patient routing. AstraZeneca leverages its cardiovascular outcomes data to sustain formulary access across integrated delivery networks. Boehringer Ingelheim anchors its position through deep clinical trial investment in renal endpoints. Eli Lilly and Company competes by extending its diabetes portfolio into overlapping metabolic indications.
SGLT2 inhibitors are a class of oral antihyperglycemic agents that block sodium-glucose cotransporter-2 proteins in renal proximal tubules, producing glucosuria and natriuresis with hemodynamic benefits independent of insulin secretion. Empagliflozin and dapagliflozin dominate the product type landscape due to established cardiovascular and renal outcome data that commands premium positioning. The application segment shows diabetes management as the mature revenue base while heart failure treatment and chronic kidney disease represent the fastest-expanding margin pools as prescribers cross-specialize.
The FDA's cardiovascular outcomes trial requirements and EMA's evolving guidance on heart failure indications shape clinical development pathways and label expansion timelines. The EU MDR and national pricing authorities such as Germany's G-BA enforce evidence thresholds that filter market access for new entrants. Stakeholders must monitor how FDA advisory committee deliberations on broadened indications and EMA parallel assessment procedures will reshape competitive positioning and investment priorities.
Market Dynamics
The SGLT2 inhibitors market pivots on cardiovascular outcome trial data that is restructuring prescriber routing from endocrinology toward cardiology and nephrology departments.
Growth Catalysts
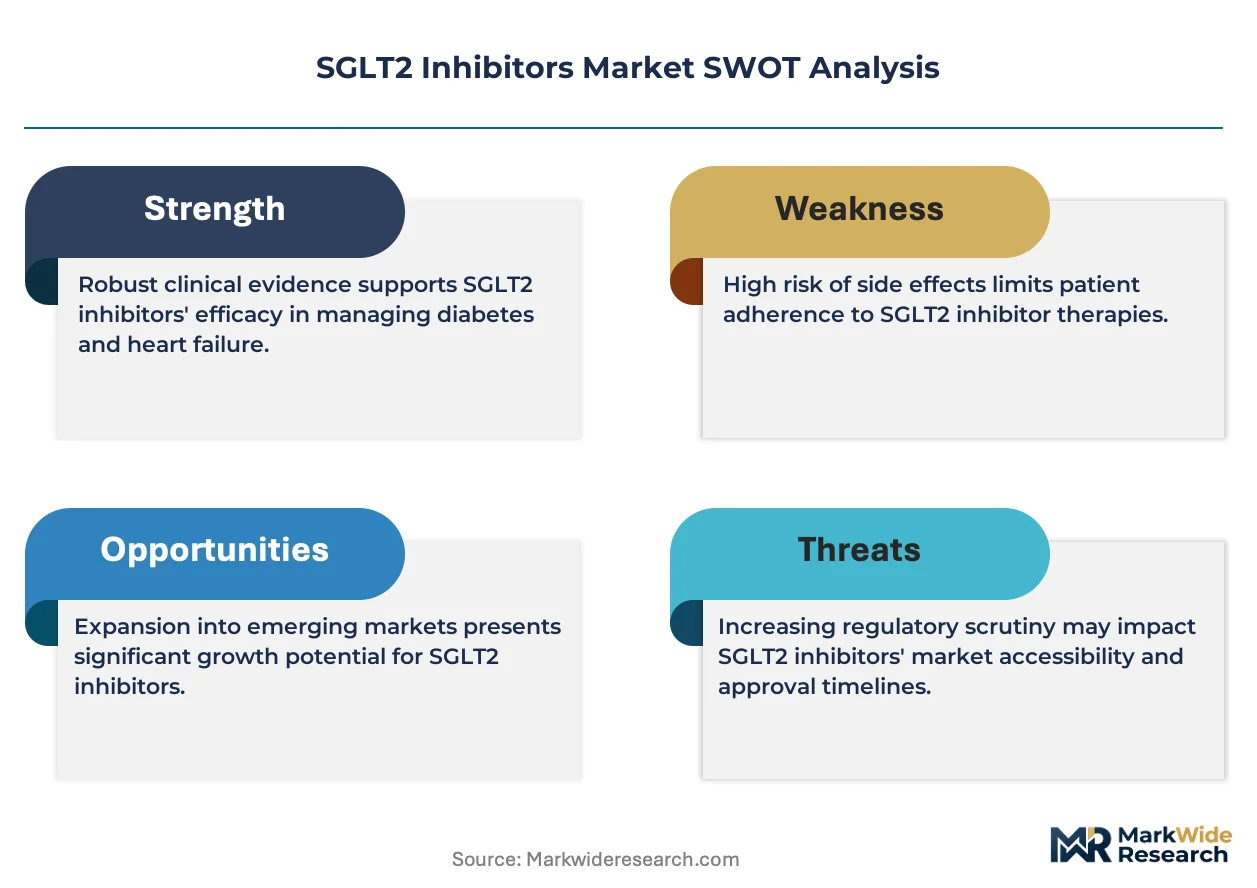
- FDA cardiovascular outcomes mandates:Trial requirements have generated robust mortality and hospitalization data that expands label indications beyond glycemic control into heart failure and chronic kidney disease.
- Medicare reimbursement pathways:Integrated delivery networks in the United States accelerate formulary placement through bundled payment models that reward reduced cardiovascular events.
- Renal hemodynamics:SGLT2 inhibitors' natriuretic and tubuloglomerular feedback mechanisms create organ-protective effects independent of glucose lowering, opening nephrology prescribing.
Market Restraints
- EU MDR evidence thresholds:Germany's G-BA and parallel national pricing authorities demand outcome data that extends market access timelines for new molecular entities.
- Genital mycotic infections:Glucosuria-induced adverse events create discontinuation risk that limits first-line positioning in certain patient populations.
- Specialist concentration:Prescribing authority concentrates among academic medical centers and integrated delivery networks, creating access barriers for independent practitioners.
Strategic Opportunities
- Heart failure with preserved ejection fraction:Label expansion into HFpEF represents underpenetrated volume opportunity as trial data accumulates.
- Non-diabetic chronic kidney disease:Regulatory pathways for renoprotection without diabetes indication open primary care and nephrology channels.
- Fixed-dose combinations:Convergence with GLP-1 receptor agonists and metformin creates adherence-enhancing formulations that simplify polypharmacy regimens.
Industry Challenges
- Cardiometabolic trial design:Endpoint adjudication and composite outcome construction require specialized biostatistical expertise that strains mid-cap development teams.
- Cross-specialty education:Primary care physicians face knowledge gaps in heart failure guideline interpretation that slows adoption velocity outside tertiary centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SGLT2 Inhibitors Market |
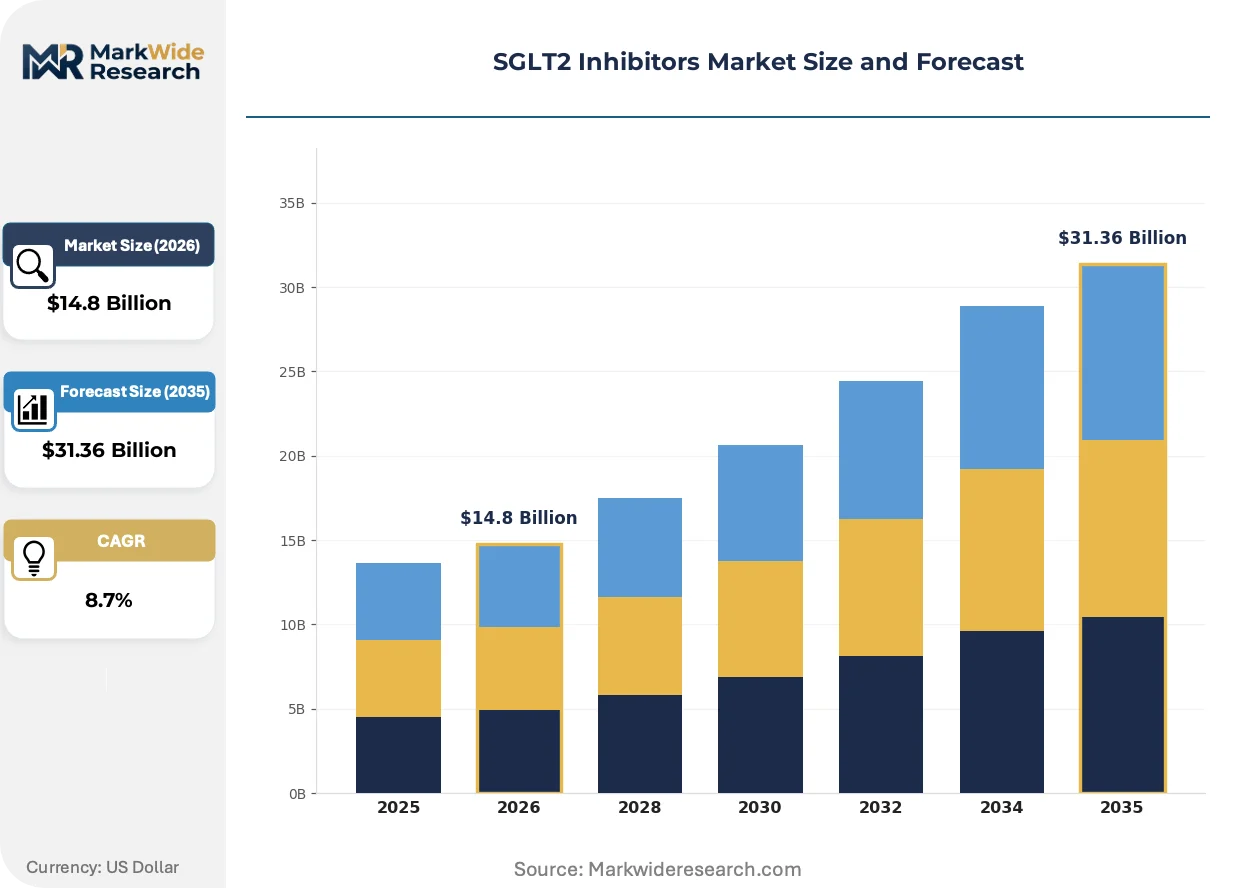
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canagliflozin, Dapagliflozin, Empagliflozin, Ertugliflozin End User: Hospitals, Clinics, Home Care, Pharmacies Application: Diabetes Management, Heart Failure Treatment, Weight Loss, Chronic Kidney Disease Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Johnson & Johnson, Sanofi, AstraZeneca, Lexicon Pharmaceuticals, Astellas Pharma, Boehringer Ingelheim, Merck & Co., Novo Nordisk, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SGLT2 Inhibitors Market Strategic Shifts
Clinical development strategies are pivoting toward organ protection claims that decouple commercial potential from diabetes prevalence curves.
Dual SGLT1/SGLT2 inhibition is supplanting selective SGLT2 blockade as the next mechanistic frontier, with intestinal glucose absorption blockade offering additional glycemic and weight benefits. Developers at academic medical centers and large pharmaceutical sponsors are advancing molecules through Phase II trials at accelerated cadences. This mechanism is compressing the addressable market for pure SGLT2 agents by promising superior metabolic outcomes in obesity-diabetes overlap populations.
EMA parallel assessment procedures for heart failure indications are compressing label expansion timelines across European markets, with centralized scientific advice streamlining renal endpoint strategies. The industrial consequence is reduced regulatory consulting expenditure and faster revenue recognition in Germany, France, and Italy. Cardiology-focused indications face the most accelerated review, with sponsors restructuring submission packages to emphasize cardiovascular mortality data.
Specialty pharmacy distribution is displacing traditional wholesale channels for oral antihyperglycemic agents, with hub services managing prior authorization and patient assistance programs. This channel shift concentrates fulfillment among three national specialty pharmacy networks that capture adherence data and influence prescriber switching behavior. The United States exhibits the most pronounced channel migration, where Medicare Part D structures and manufacturer rebate contracting drive consolidation.
SGLT2 Inhibitors Market Segmentation
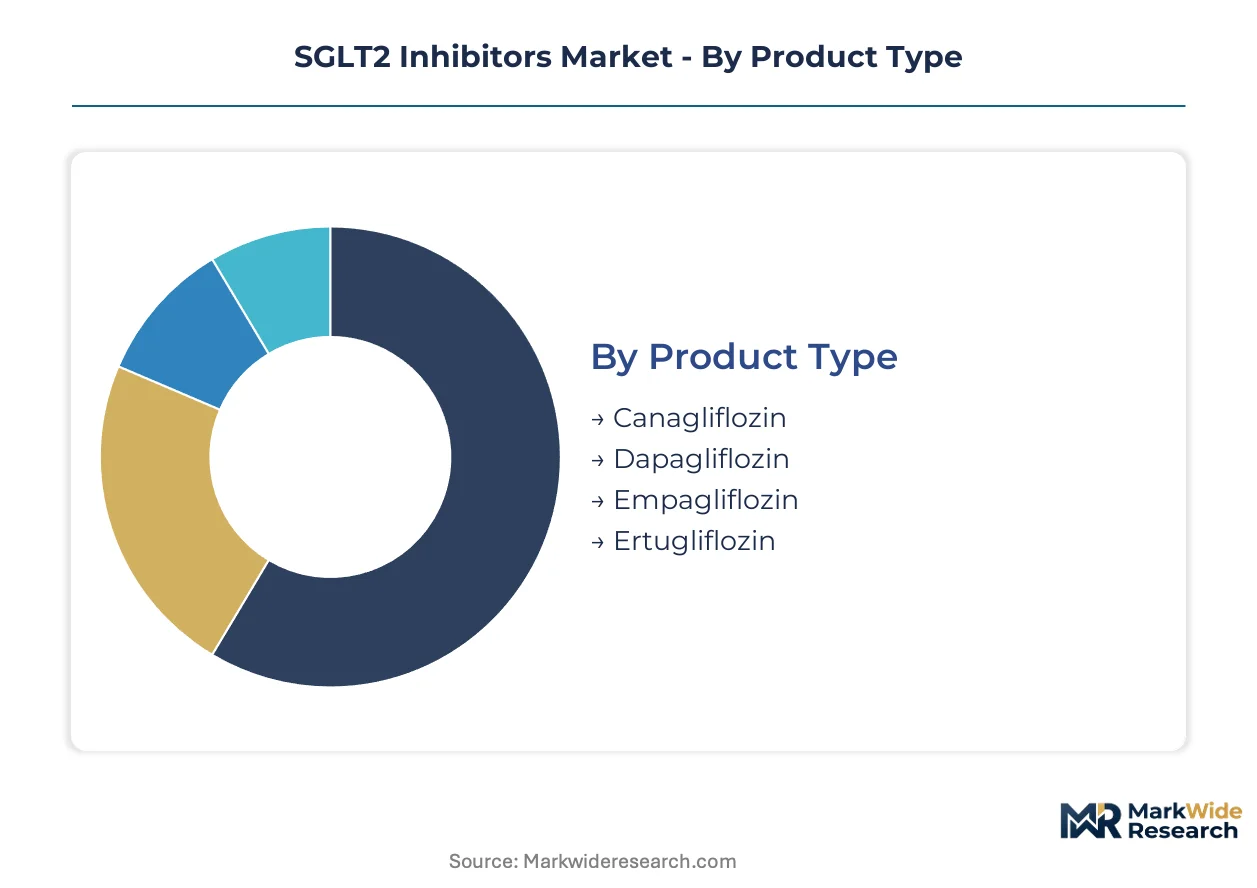
SGLT2 inhibitor commercial strategy hinges on matching molecule profiles to prescriber specialty and reimbursement pathway. Segmentation reveals where cardiovascular outcome data commands premium positioning versus where cost compression dominates.
Product Type:
Margin pools concentrate where cardiovascular and renal outcome trials have generated regulatory labels that unlock cardiology and nephrology prescribing.
- Empagliflozin:The EMPA-REG OUTCOME trial established cardiovascular mortality reduction that secured FDA and EMA heart failure indications. Demand concentrates in German and US hospital systems where integrated delivery networks reward reduced hospitalization rates through bundled cardiac care contracts.
- Dapagliflozin:DAPA-HF and DAPA-CKD trials delivered heart failure with reduced ejection fraction and chronic kidney disease approvals independent of diabetes status. Prescription volume is accelerating in NHS England and Medicare Advantage plans where renal protective claims justify prior authorization investment.
- Canagliflozin:Selective SGLT2 blockade with established glycemic control positioning faces amputation risk warnings that constrain first-line use.
- Ertugliflozin:Newest entrant with narrower outcome data profile competing on price in commercial pharmacy benefit manager formularies.
The dominant share belongs to Empagliflozin, while Dapagliflozin is closing the gap fastest.
End User:
Prescription authority is migrating from traditional diabetes clinics toward cardiovascular and renal specialists with distinct procurement patterns.
- Hospitals:Academic medical centers and integrated delivery networks command the steepest expansion trajectory as cardiology departments build heart failure protocols around SGLT2 inhibitors. Cleveland Clinic, Mayo Clinic, and Kaiser Permanente systems drive protocol standardization that locks in molecule selection across network hospitals.
- Clinics:Endocrinology and nephrology group practices represent mature volume with formulary decisions increasingly influenced by specialty pharmacy hub arrangements rather than physician preference.
- Home Care:Post-acute and long-term care facilities are emerging channels where medication reconciliation programs identify eligible heart failure patients.
- Pharmacies:Retail fulfillment concentrates 340B contract pharmacy arrangements and Medicare Part D preferred network positioning.
Hospitals capture the dominant share, while home care channels are gaining share fastest as post-discharge protocols extend therapy initiation.
Application:
Commercial value is decoupling from diabetes prevalence as organ protection claims open non-glycemic indications.
- Diabetes Management:Mature revenue base with prescriber concentration in endocrinology practices. Medicare Part D and commercial formularies tier placement by cardiovascular risk stratification.
- Heart Failure Treatment:Fastest-expanding margin pool as HFrEF and HFpEF labels restructure patient routing through cardiology departments. FDA advisory committee deliberations on broadened indications are compressing label expansion timelines.
- Chronic Kidney Disease:Regulatory pathways for renoprotection without diabetes indication are opening nephrology channels and primary care screening protocols.
- Weight Loss:Adjunctive metabolic benefit positioning in obesity-diabetes overlap populations, facing competition from GLP-1 receptor agonists.
Diabetes management holds the dominant share, while heart failure treatment is expanding most quickly as guideline updates embed SGLT2 inhibitors in standard of care.
Distribution Channel:
Fulfillment economics are restructuring around patient assistance complexity and adherence monitoring value.
- Retail Pharmacies:CVS Health, Walgreens Boots Alliance, and Rite Aid networks dominate commercial insured volume with formulary tier placement determining market access.
- Online Pharmacies:Amazon Pharmacy and Capsule are capturing cash-pay and high-deductible plan patients with transparent pricing models.
- Specialty Pharmacy (via Wholesalers):McKesson, AmerisourceBergen, and Cardinal Health specialty divisions manage prior authorization and hub services for Medicare and Medicaid populations.
- Direct Sales:Limited to institutional contracting with integrated delivery networks and VA health systems.
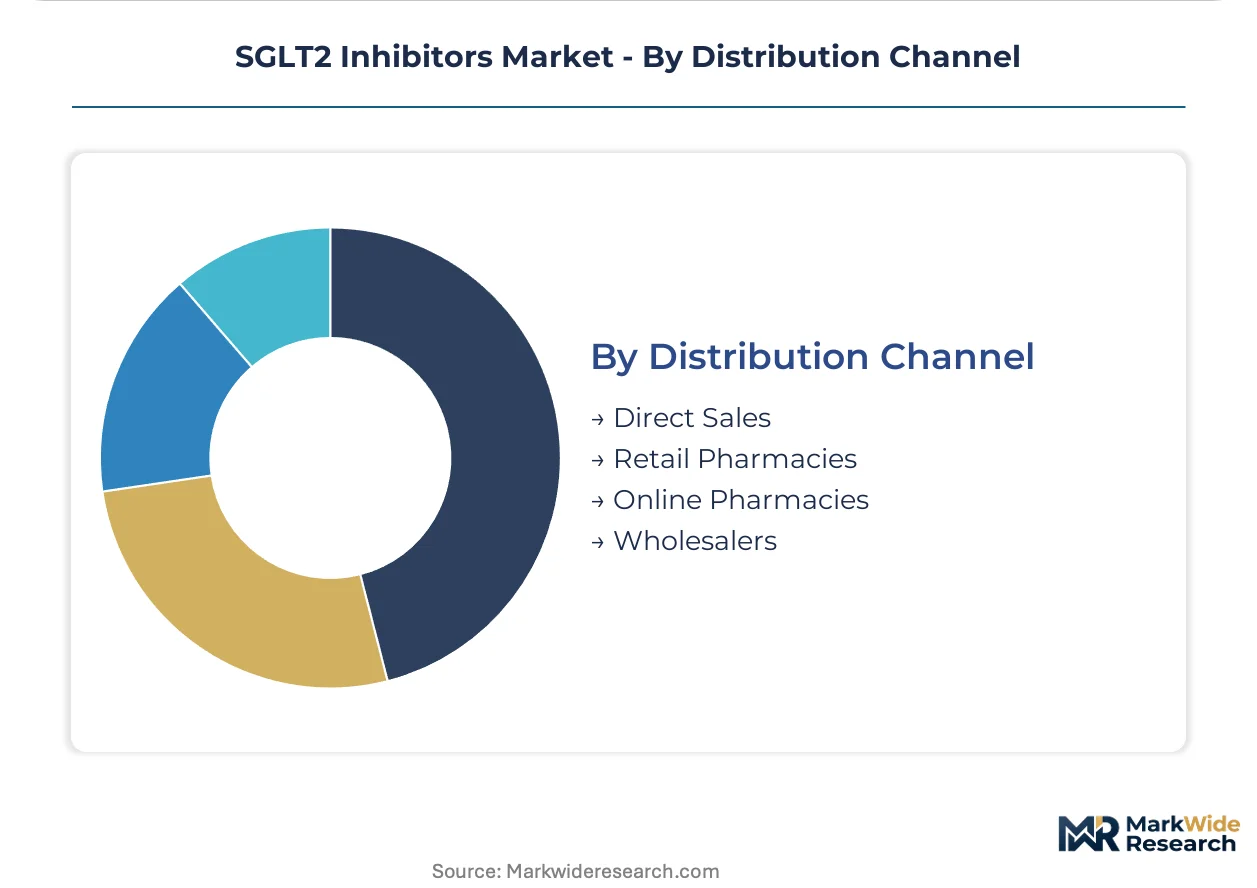
Retail pharmacies command the dominant share, while specialty pharmacy channels through wholesale networks are capturing share fastest as hub services consolidate patient support functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive biologics, while Newark Liberty International Airport's cargo terminals anchor North American import volumes for finished dosage forms.
United States
Medicare Advantage bundled payment models and integrated delivery networks like Kaiser Permanente drive hospital formulary standardization. The FDA's cardiovascular outcomes trial mandates reshape prescriber routing toward cardiology departments. The Cleveland Clinic and Mayo Clinic systems in Ohio and Minnesota pilot protocol-driven SGLT2 inhibitor initiation across heart failure admissions.
Germany
Germany's G-BA demands outcome data thresholds that extend market access timelines for new molecular entities. The EMA's parallel assessment procedures compress label expansion timelines across European markets. Bavaria's university hospital clusters in Munich and Erlangen concentrate nephrology prescribing trials for chronic kidney disease indications.
Japan
PMDA's accelerated review pathways for cardiovascular mortality data prioritize heart failure label expansions. METI's pharmaceutical pricing reforms reward drugs demonstrating hospitalization reduction. The Kansai region's Osaka University Hospital network generates real-world evidence protocols influencing regional prescribing patterns.
United Kingdom
NHS England's integrated care systems embed SGLT2 inhibitors in heart failure treatment pathways through NICE technology appraisals. The MHRA's post-Brexit recognition procedures align with EMA scientific advice for renal endpoint strategies. London's Guy's and St Thomas' NHS Foundation Trust leads multi-site implementation studies across Southeast England.
India
CDSCO's abbreviated approval pathways for drugs with established US FDA or EMA labels accelerate domestic market entry. The government's PLI scheme for active pharmaceutical ingredients reduces import dependency for SGLT2 inhibitor intermediates. Maharashtra's Mumbai-Pune pharmaceutical corridor concentrates formulation manufacturing for export to regulated markets.
SGLT2 Inhibitors Market Competitive Environment
Listed leaders compete with private specialists across cardiovascular outcome trial investment capacity, creating a tiered structure where publicly traded pharmaceutical conglomerates command formulary access through integrated delivery network contracting. The market consolidates around three strategic archetypes: Big Pharma incumbents with diabetes portfolio breadth, cardiovascular-focused mid-cap developers, and regional generic manufacturers. Dominant competitive moves include strategic partnerships for fixed-dose combination development and geographic licensing arrangements for emerging market access.
Within the cardiovascular outcome data tier, AstraZeneca and Boehringer Ingelheim occupy positions anchored by EMPA-REG and DAPA trial portfolios. Eli Lilly and Company sits within the metabolic convergence archetype, extending diabetes assets into overlapping indications. Johnson & Johnson represents the diversified health science conglomerate model with hospital system contracting leverage.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Sanofi |
| AstraZeneca |
| Lexicon Pharmaceuticals |
| Astellas Pharma |
| Boehringer Ingelheim |
| Merck & Co. |
| Novo Nordisk |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Dual SGLT1/SGLT2 inhibitor development is displacing pure SGLT2 blockade in obesity-diabetes overlap populations, simultaneously shifting API sourcing toward Indian and Chinese contract manufacturers while compressing pricing power for legacy molecules in commercial pharmacy benefit manager formularies.
Pricing Analysis
Volume-discount tiering structures stratify across cardiovascular outcome data tiers, with empagliflozin and dapagliflozin commanding premium positioning in Medicare Advantage and integrated delivery network contracts while ertugliflozin competes on price in commercial formularies. Price differentiation hinges on trial-generated label breadth and FDA advisory committee endorsement status, with hospital systems least price-sensitive due to bundled cardiac care contracts and independent practitioners most exposed to prior authorization cost barriers. Pricing pressure intensifies as dual SGLT1/SGLT2 inhibitors advance through Phase II, threatening to commoditize selective SGLT2 agents in diabetes management indications.
Supply Chain Analysis
Inventory lead times for SGLT2 inhibitor APIs have compressed as Maharashtra's Mumbai-Pune pharmaceutical corridor scales fermentation capacity for key intermediates. Active pharmaceutical ingredient production draws from India, China, and the United States, with formulation finishing concentrated in Germany and Japan for regulated markets. Supply chain risk centers on single-source dependency for chiral synthesis precursors. Distribution runs through three national specialty pharmacy networks that consolidate prior authorization and patient assistance functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against dual SGLT1/SGLT2 inhibitors that threaten to compress selective SGLT2 agent pricing and displace volume in metabolic indications.
For Market Incumbents: Consolidate cardiovascular outcome data advantages through nephrology endpoint investment and heart failure with preserved ejection fraction trial acceleration. Lock in formulary positioning across Kaiser Permanente and Cleveland Clinic integrated delivery networks before dual-mechanism competitors achieve label expansion. Prioritize backward integration into API production to insulate margins from Indian and Chinese intermediate pricing volatility. For New Entrants and Emerging Players: Patient assistance program gaps in Medicare Part D high-deductible plans represent the most penetrable service layer where hub services consolidation has degraded incumbent responsiveness. Target non-diabetic chronic kidney disease regulatory pathways where nephrology prescribing protocols remain underdeveloped. Pursue geographic licensing arrangements with Maharashtra-based manufacturers to access CDSCO abbreviated approval pathways for established-label molecules. For Investors and Strategic Acquirers: The market sits at a label-expansion phase that favors cardiovascular-focused mid-cap developers with renal endpoint trial infrastructure. Long-term viability hinges on organ protection claims that decouple revenue from diabetes prevalence curves. Acquisition targets should demonstrate EMA parallel assessment procedure experience and heart failure advisory committee engagement. Monitor FDA advisory committee deliberation schedules as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Renal endpoint investment secures nephrology channel access beyond glycemic indications. |
| Regulatory Approval Pathway | EMA parallel assessment procedures compress European label expansion timelines. |
| Manufacturing Scale-Up | Maharashtra corridor capacity addresses API import dependency for domestic markets. |
| Licensing Agreement | Geographic partnerships unlock CDSCO abbreviated pathways in emerging markets. |
| Pipeline Diversification | Dual SGLT1/SGLT2 development hedges against selective agent commoditization. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare Part D formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to converge on segment-level estimates.
Variance decomposition across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory analysis incorporating cardiovascular outcome trial publication schedules and label expansion probability weighting. Forecast inputs included Medicare reimbursement pathway evolution and integrated delivery network formulary standardization protocols.
Forecasts assume regulatory continuity in FDA cardiovascular outcomes mandates and EMA heart failure guidance; material policy shifts would require re-modeling. Specific risks include EU MDR evidence threshold elevation and PMDA accelerated review pathway modification. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Global Immuno Oncology Drugs Market