
 North America Anticoccidial Drugs Market | 2026-2036
North America Anticoccidial Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Anticoccidial Drugs Market Analytics
Polyether ionophore synthesis combined with precision fermentation is reconfiguring active pharmaceutical ingredient production for coccidiostats. Zoetis leverages backward integration into fermentation capacity to secure narasin supply chains. Elanco anchors its position through veterinary clinic distribution networks across the United States and Canada. Merck Animal Health differentiates via sustained R&D investment in novel chemical entities beyond traditional ionophores.
Anticoccidial drugs comprise chemical agents and ionophore compounds administered in feed or water to prevent or treat coccidial infections in livestock, with polyether ionophores functioning as monovalent cation transporters that disrupt parasite membrane potential. These agents primarily serve intensive poultry, swine, and cattle operations where subclinical coccidiosis erodes feed conversion ratios and carcass yield. The poultry application segment dominates volume consumption due to continuous-flow housing systems that amplify oocyst cycling. Premix formulations capture the largest share of value given their integration into commercial feed mill operations and compatibility with automated batching systems.
The FDA Veterinary Feed Directive mandates veterinary oversight for all medically important antimicrobials in feed, while the EPA evaluates environmental discharge from ionophore manufacturing facilities under Clean Water Act provisions. Health Canada and PMRA coordinate residue tolerance harmonization through joint maximum residue limit reviews for cross-border meat trade. Stakeholders must monitor evolving regulatory divergence between U.S. state-level antibiotic stewardship programs and federal feed additive approval pathways.
Market Dynamics
The FDA Veterinary Feed Directive has fundamentally restructured prescription requirements for medicated feeds, forcing feed mills and poultry operations to reconfigure their supplier relationships and veterinary oversight protocols across the United States.
Growth Catalysts
- Vertically integrated broiler operations:Large-scale poultry producers in Georgia, Arkansas, and Alabama drive concentrated demand for ionophore premixes through continuous-flow housing systems that amplify coccidial cycling risks.
- REACH-aligned residue standards:Health Canada and PMRA joint maximum residue limit reviews facilitate cross-border meat trade, harmonizing tolerance thresholds for narasin and salinomycin in carcass exports.
- Precision fermentation advances:Bioprocess engineering improvements lower active pharmaceutical ingredient production costs for polyether ionophores, expanding supply security for commercial feed formulations.
Market Restraints
- API supply concentration:Fermentation capacity for narasin and semduramicin concentrates among three domestic manufacturers, creating vulnerability to batch contamination or equipment failure events.
- Environmental discharge compliance:EPA Clean Water Act provisions governing ionophore manufacturing effluent impose capital-intensive wastewater treatment upgrades on production facilities.
- Coccidial resistance accumulation:Field isolates of Eimeria species demonstrate reduced sensitivity to monensin following decades of continuous dietary administration in southeastern U.S. broiler belts.
Strategic Opportunities
- Canadian prairie cattle feedlots:Underpenetrated Alberta and Saskatchewan backgrounding operations present expansion potential for lasalocid and laidlomycin propionate formulations in starter rations.
- Organic poultry exemption pathways:USDA National Organic Program regulations permitting ionophore use in organic production create differentiated positioning for certified-humane supply chains.
- Water-soluble delivery systems:Solubilized anticoccidial formulations compatible with automated drinking line medication systems address labor constraints in cage-free layer housing conversions.
Industry Challenges
- Veterinary oversight capacity:The FDA VFD mandate strains rural practitioner availability, with feed mill veterinarians facing appointment backlogs that delay feed additive approvals.
- Legacy feed mill infrastructure:Automated batching systems designed for antibiotic premixes require mechanical retrofits to handle ionophore cross-contamination protocols between production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Anticoccidial Drugs Market |
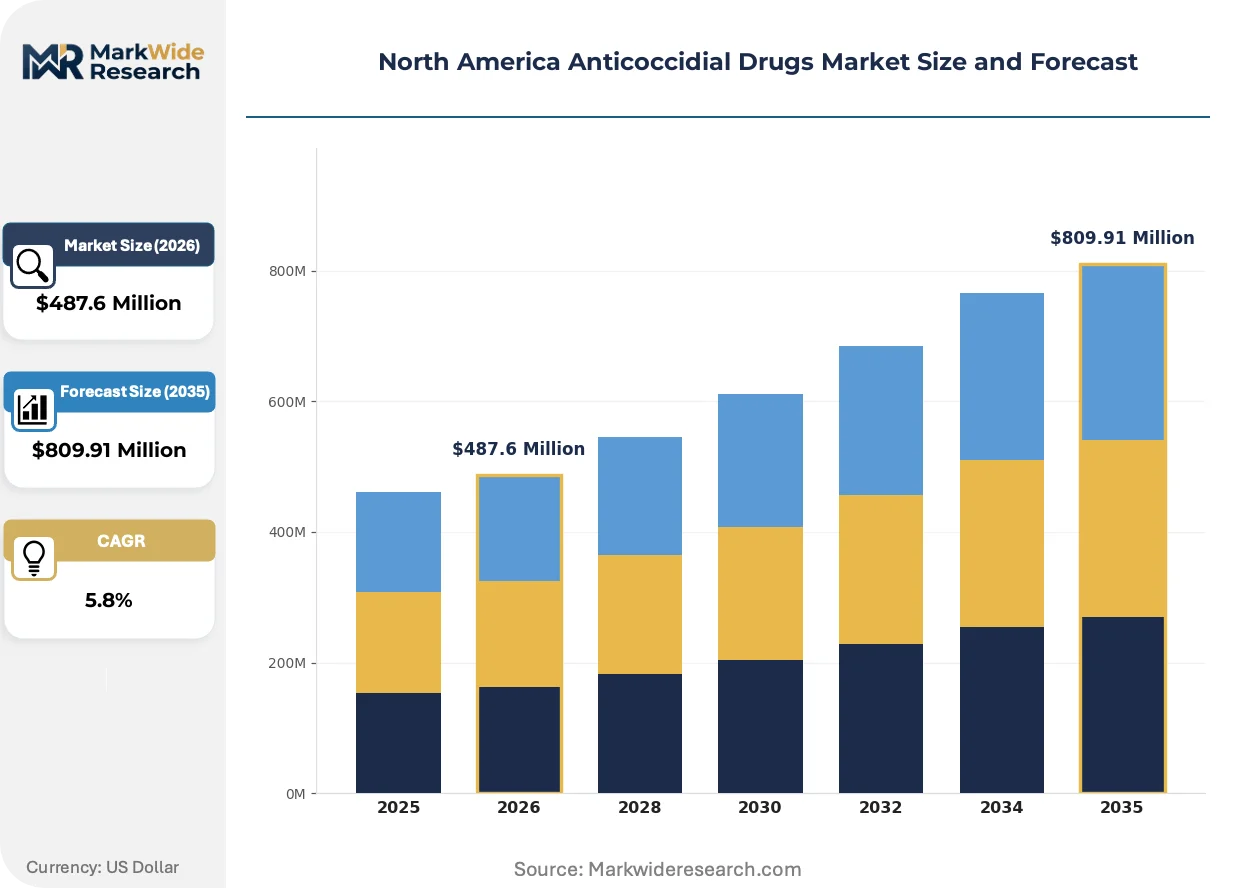
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salinomycin, Monensin, Narasin, Polyether Ionophores Application: Poultry, Swine, Cattle, Aquaculture Formulation: Powder, Liquid, Premix, Granules Distribution Channel: Veterinary Clinics, Online Retail, Agricultural Suppliers, Pharmacies |
| Companies Covered | Zoetis, Elanco, Merck Animal Health, Bayer HealthCare, Boehringer Ingelheim Animal Health, Ceva Santé Animale, Virbac, Huvepharma, Phibro Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Anticoccidial Drugs Market Evolving Landscape
Bioprocess engineering and regulatory chemistry are converging to transform how coccidiostats are manufactured, prescribed, and administered across North American livestock operations.
Precision fermentation platforms utilizing engineered yeast strains for polyether ionophore biosynthesis are rendering obsolete traditional Streptomyces-based batch fermentation. Mid-sized contract manufacturers in the Midwest adopt these platforms to reduce lot-to-lot variability and shorten production cycles from six weeks to ten days. The compression of API lead times enables just-in-time premix formulation for regional feed mills.
Health Canada and PMRA accelerated their joint maximum residue limit review timeline for coccidiostats in 2023, compressing harmonization cycles from thirty-six months to eighteen months. This regulatory synchronization reduces dual-registration burdens for suppliers seeking access to both U.S. and Canadian protein markets. Cross-border meat processors in Manitoba and North Dakota benefit most from unified tolerance standards for salinomycin and narasin residues.
Direct-to-feed-mill distribution networks are displacing traditional veterinary clinic intermediaries for anticoccidial procurement. Large integrated poultry operators in Mississippi and North Carolina negotiate annual volume contracts with API manufacturers, bypassing distributor markups. This channel consolidation concentrates purchasing leverage among the ten largest U.S. broiler producers, who now account for the majority of ionophore volume flowing through southeastern feed mill complexes.
North America Anticoccidial Drugs Market Segmentation
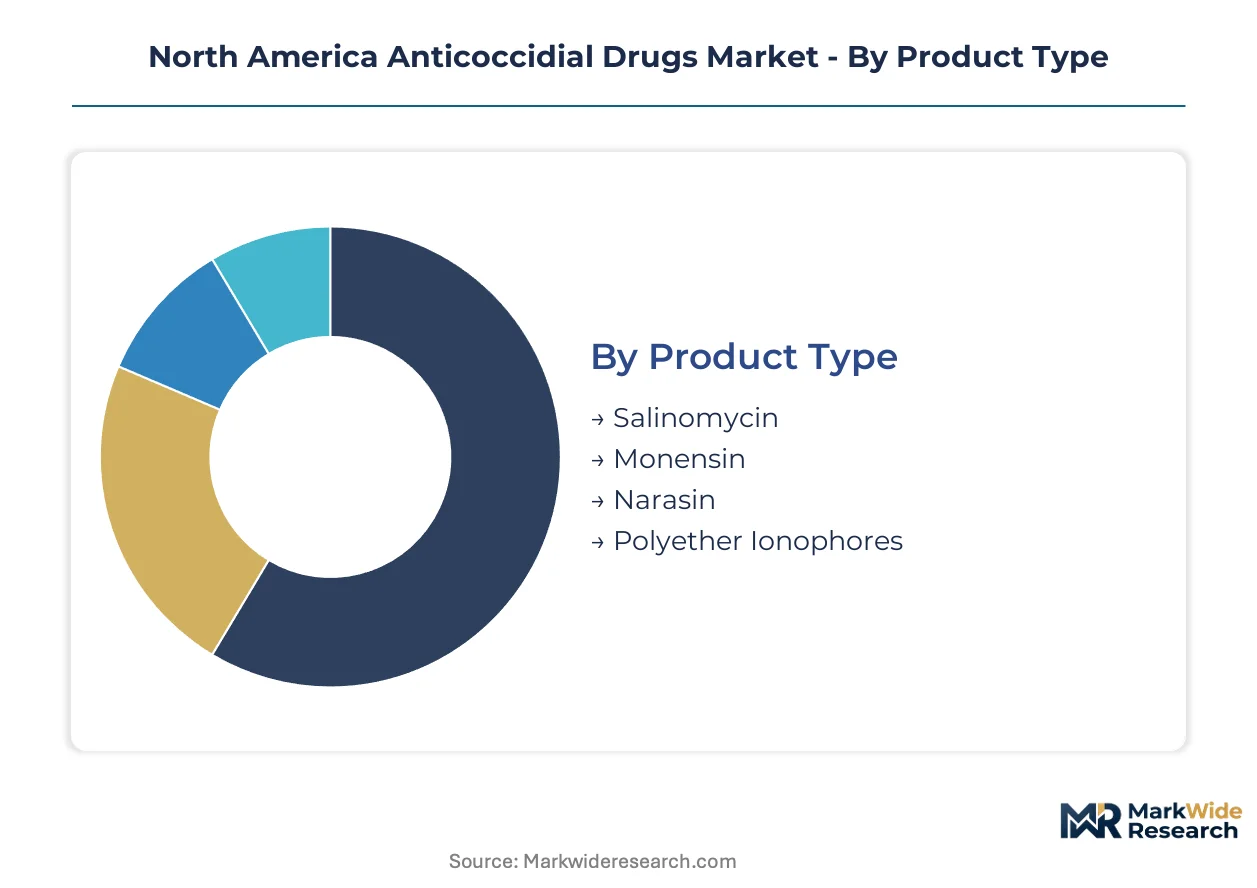
Anticoccidial drug segmentation reveals how formulation chemistry, species targeting, and channel economics create distinct competitive arenas. Each dimension carries regulatory and operational implications that reshape supplier priorities across North American livestock operations.
Product Type:
Mature ionophore chemistries dominate commercial volumes, while emerging biosynthetic platforms threaten incumbent manufacturing economics.
- Salinomycin:A divalent cation ionophore with broad-spectrum efficacy against Eimeria tenella and E. acervulina. Demand concentrates in vertically integrated broiler complexes across Georgia and Alabama, where continuous-flow housing amplifies subclinical infection pressure and drives preventive inclusion rates.
- Monensin:The first commercialized polyether ionophore, functioning as a sodium/proton antiporter that disrupts parasite mitochondrial function. Field isolates in the southeastern U.S. broiler belt show accumulating resistance following decades of uninterrupted dietary administration, forcing rotation protocols with alternative chemistries.
- Narasin:Narrow-spectrum ionophore with enhanced activity against E. maxima. Alberta cattle feedlots adopt narasin-sodium combinations in backgrounding rations for coccidiosis control combined with improved feed efficiency.
- Polyether Ionophores:Class-wide term encompassing lasalocid, semduramicin, and laidlomycin propionate. Precision fermentation advances are compressing API production cycles and reducing lot-to-lot variability for contract manufacturers.
Monensin handles the majority of throughput; narasin is expanding most quickly on share as resistance management protocols accelerate rotation adoption.
Application:
Volume distribution across species reflects housing intensity and economic value at risk from subclinical infection.
- Poultry:Dominant consumption segment driven by continuous-flow housing systems that amplify oocyst cycling. Southeastern U.S. broiler operations account for concentrated premix demand through automated feed mill batching systems.
- Cattle:Feedlot applications in Alberta and Saskatchewan backgrounding operations represent underpenetrated expansion territory. Lasalocid and laidlomycin propionate formulations in starter rations address coccidiosis during high-stress receiving periods.
- Swine:Isospora suis control in farrowing facilities drives water-soluble formulation demand. Nursery phase applications concentrate in Iowa and North Carolina swine production clusters.
- Aquaculture:Emerging application for Eimeria spp. control in intensive catfish and salmonid operations. Regulatory residue limits under FDA Center for Veterinary Medicine oversight constrain rapid adoption.
Poultry commands the dominant volume position; cattle is gaining share fastest as feedlot operators recognize subclinical coccidiosis impacts on average daily gain.
Formulation:
Physical presentation determines compatibility with existing feed mill infrastructure and labor constraints in evolving housing systems.
- Premix:Concentrated ionophore-carrier blends designed for automated batching systems at commercial feed mills. Integration into vertically integrated poultry operations in Mississippi and North Carolina secures annual volume contracts with API manufacturers.
- Powder:Dry formulations for on-farm mixing in smaller operations lacking centralized feed mill access. Manual handling requirements limit adoption in large-scale continuous-flow systems.
- Liquid:Solubilized anticoccidial formulations compatible with automated drinking line medication systems. Cage-free layer housing conversions in California and Washington drive demand for labor-reducing delivery mechanisms.
- Granules:Dust-reduced physical forms improving handler safety and environmental containment. EPA Clean Water Act discharge compliance favors granule adoption near sensitive watersheds.
Premix formulations carry the bulk of value; liquid formulations are climbing the fastest as housing system conversions reshape administration economics.
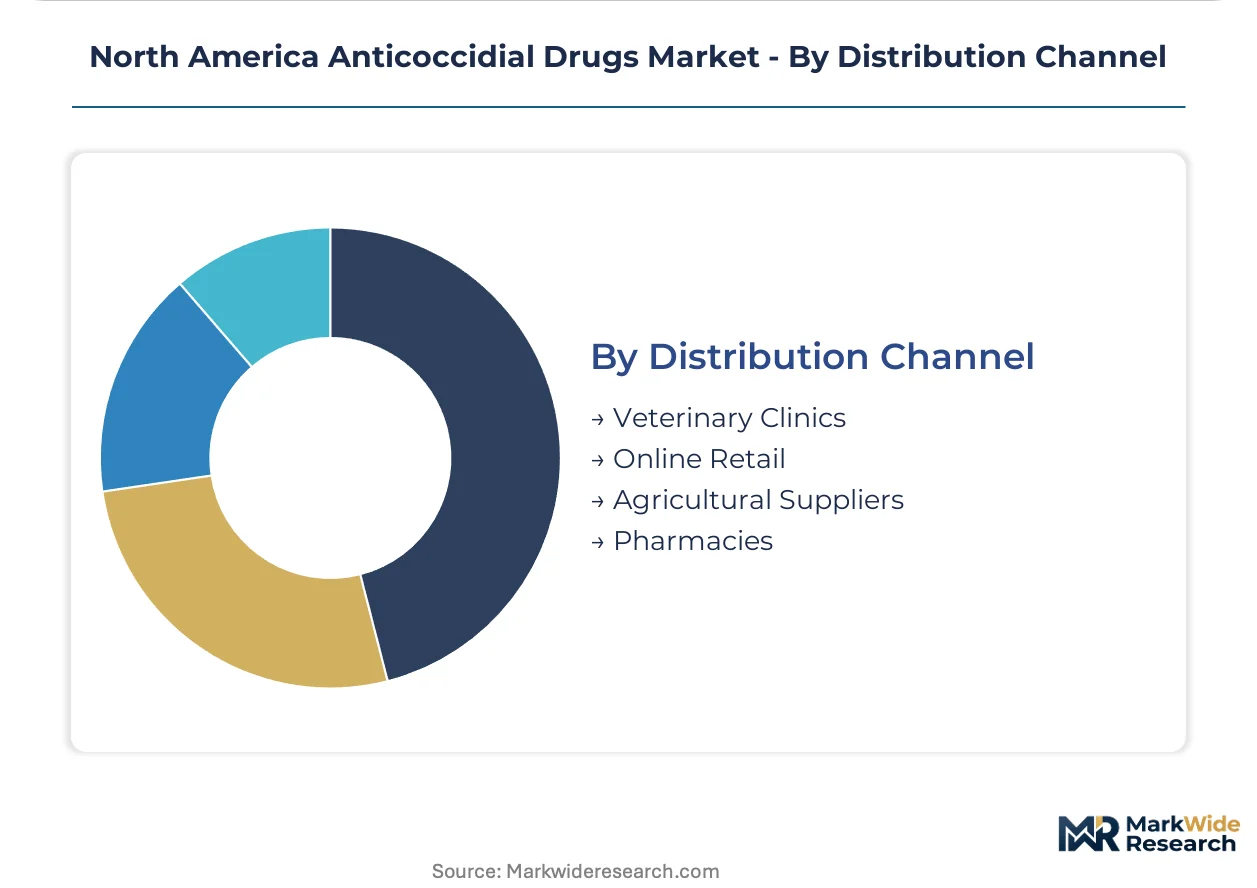
Distribution Channel:
Channel structure is concentrating as direct procurement displaces traditional intermediaries among large integrated operators.
- Agricultural Suppliers:Regional distributors serving mid-sized independent producers across the Midwest and Southeast. Inventory positioning near poultry production clusters enables just-in-time premix delivery.
- Veterinary Clinics:Prescription gatekeepers under FDA Veterinary Feed Directive mandates. Rural practitioner capacity constraints create appointment backlogs that delay feed additive approvals.
- Online Retail:Emerging channel for smaller operations seeking price transparency and reduced procurement friction. Regulatory documentation requirements limit growth for VFD-covered products.
- Pharmacies:Limited role restricted to companion animal and specialty livestock applications. Human health regulatory separation constrains anticoccidial stocking.
Agricultural suppliers move the majority of volume; online retail is expanding most rapidly among non-integrated producers seeking procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border meat trade flows between the United States and Canada dominate regional export-import dynamics, with ionophore residue harmonization enabling seamless carcass shipments. Mexico's expanding feedlot sector imports premix formulations from U.S. Gulf Coast manufacturing clusters.
United States
Vertically integrated broiler operations in Georgia, Arkansas, and Alabama consume concentrated ionophore premix volumes through automated feed mill systems. The FDA Veterinary Feed Directive mandates veterinary oversight for all medicated feeds, restructuring supplier relationships across southeastern poultry belts. Mississippi and North Carolina host direct procurement negotiations between large integrators and API manufacturers.
Canada
Alberta and Saskatchewan cattle feedlots represent underpenetrated territory for lasalocid and laidlomycin propionate starter rations. Health Canada and PMRA coordinate joint maximum residue limit reviews, compressing harmonization cycles to eighteen months for cross-border trade facilitation. Manitoba processors benefit from unified tolerance standards with adjacent North Dakota operations.
Mexico
Expanding beef feedlot capacity in northern states drives import dependency for U.S.-manufactured ionophore premixes. Mexico's national agricultural regulator evaluates veterinary drug registrations under standards increasingly aligned with FDA protocols. Sonora and Chihuahua concentrate demand from cross-border supply chains serving American meatpackers.
North America Anticoccidial Drugs Market Competitive Landscape
On the supply side, the industry is consolidating around fermentation-capable API manufacturers and distribution-anchored pharmaceutical conglomerates. Three domestic producers concentrate polyether ionophore biosynthesis capacity, creating vulnerability to batch contamination events. Strategic archetypes include backward-integrated fermentation specialists, veterinary clinic network operators, and sustained R&D investors in novel chemical entities. Dominant competitive moves encompass captive supply chain construction and direct-to-feed-mill channel displacement of traditional intermediaries.
Among the named participants, Zoetis exemplifies the fermentation-integrated archetype through captive narasin production infrastructure. Elanco anchors its position via veterinary clinic distribution networks spanning the United States and Canada. Merck Animal Health occupies the novel chemistry tier, differentiating through investment in chemical entities beyond traditional ionophores. These three represent distinct strategic vectors within a market where manufacturing scale and regulatory navigation capability determine competitive endurance.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Merck Animal Health |
| Bayer HealthCare |
| Boehringer Ingelheim Animal Health |
| Ceva Santé Animale |
| Virbac |
| Huvepharma |
| Phibro Animal Health |
| Others |
Value Network & Pricing Analysis
Three domestic fermentation facilities concentrate polyether ionophore biosynthesis capacity, anchoring margin pools with API manufacturers who negotiate annual volume contracts directly with integrated poultry operators. This upstream concentration transfers pricing power downstream to feed mill procurement desks while squeezing distributor intermediaries out of the value chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with annual volume agreements between the ten largest U.S. broiler producers and API manufacturers displacing spot-market transactions. Price differentiation rests on fermentation scale and veterinary feed directive compliance certification tier, with premium pricing attaching to just-in-time delivery guarantees. Cost compression in standard-grade ionophore premixes is intensifying because precision fermentation advances shorten production cycles, though least price-sensitive buyers remain the vertically integrated operators who prioritize supply security over unit economics.
Supply Chain Analysis
Midwestern contract manufacturers hold expanding precision fermentation capacity, drawing from engineered yeast strain platforms that reduce lot-to-lot variability versus traditional Streptomyces batch processes. Raw material dependencies center on glucose feedstock, specialized bioreactor vessels, and polyether precursor compounds. Single-source vulnerability concentrates in narasin and semduramicin fermentation trains, where equipment failure would disrupt southeastern U.S. feed mill operations. Distribution runs through direct-to-feed-mill networks that displace traditional agricultural supplier intermediaries among large integrated operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-capable manufacturing assets and veterinary oversight infrastructure represent scarce capabilities that determine competitive endurance, with backward integration into biosynthesis capacity separating sustainable participants from margin-squeezed distributors.
For Market Incumbents: Entrench position through captive narasin supply chains and direct annual contracting with the largest southeastern broiler integrators. Add fermentation capacity in the Midwest to reduce geographic concentration risk from coastal manufacturing clusters. Defensive priority rests on preventing contract manufacturers from scaling precision fermentation platforms that could erode proprietary biosynthesis advantages.
For New Entrants and Emerging Players: Establish a beachhead in Alberta and Saskatchewan cattle feedlots, where lasalocid and laidlomycin propionate penetration remains underdeveloped relative to U.S. poultry saturation. Target water-soluble formulation development for cage-free layer housing conversions in California and Washington. Go-to-market angle should emphasize automated drinking line compatibility that addresses labor constraints in evolving housing systems.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed veterinary clinic networks that face margin pressure from FDA Veterinary Feed Directive consolidation and direct procurement displacement. Long-term viability across the analysis window favors fermentation-integrated API manufacturers over distribution-anchored pharmaceutical conglomerates. Watch for Health Canada and PMRA regulatory divergence from FDA residue tolerance standards as a signal for cross-border trade friction that would reshape supply chain economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Zoetis secures narasin supply chains against batch contamination events at competitor facilities. |
| Direct-to-Feed-Mill Distribution Expansion | Large integrators in Mississippi and North Carolina bypass distributor markups through annual API volume contracts. |
| Precision Fermentation Platform Adoption | Midwestern contract manufacturers compress production cycles from six weeks to ten days using engineered yeast strains. |
| Water-Soluble Formulation Development | Cage-free layer conversions in California drive demand for automated drinking line medication systems. |
| Canadian Prairie Market Entry | Alberta and Saskatchewan feedlots represent underpenetrated territory for lasalocid starter rations. |
Research Methodology
A standing panel of fermentation plant managers, poultry procurement directors at integrated operations, veterinary feed directive compliance officers, and Health Canada regulatory affairs specialists provided ongoing calibration across the study period. Primary interview insights triangulated against FDA Veterinary Feed Directive enforcement records, EPA Clean Water Act discharge filings for ionophore manufacturing facilities, USDA National Agricultural Statistics Service poultry production data, and SEC 10-K disclosures from publicly traded animal health conglomerates. Bottom-up premix volume estimates from southeastern U.S. feed mill complexes reconciled with top-down API production capacity assessments.
Scenario bracketing around FDA regulatory stringency, coccidial resistance accumulation rates, and precision fermentation adoption curves shaped the analytical framework. Segmentation dimensions modeled encompassed ionophore chemistry class, species application, physical formulation type, and distribution channel structure. CAGRs derived from production capacity expansion timelines and broiler housing stock growth projections across Georgia, Arkansas, and Alabama. Forecast inputs incorporated veterinary oversight capacity constraints and cross-border meat trade flow harmonization between U.S. and Canadian regulatory frameworks.
Stress conditions across EPA effluent compliance costs, batch contamination events at concentrated fermentation facilities, and veterinary practitioner availability shortages were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued FDA Veterinary Feed Directive enforcement without state-level antibiotic stewardship program divergence. Quarterly review of Health Canada and PMRA joint maximum residue limit review timelines is advised to detect inflection in cross-border trade facilitation dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market