
 Efinaconazole Market | 2026-2036
Efinaconazole Market Size, Share, and Industry Trends Forecast 2026-2036
Efinaconazole Market Analysis
Multi-source API procurement is rebalancing toward qualified secondary suppliers as manufacturers hedge against raw material volatility. Pfizer Inc. leverages its global manufacturing footprint to sustain consistent efinaconazole supply across regulated markets. Glenmark Pharmaceuticals anchors its position through backward integration into active pharmaceutical ingredient production. Kaken Pharmaceutical Co., Ltd. differentiates via specialized topical formulation expertise developed in the Japanese market.
Efinaconazole is a triazole antifungal agent with a low molecular weight of approximately 348.4 g/mol, formulated as a 10% topical solution for transungual penetration into the nail plate and bed. Its primary commercial purpose centers on treating distal lateral subungual onychomycosis by inhibiting fungal CYP51-dependent ergosterol synthesis. Topical solutions command the dominant share among product types due to superior patient compliance and established clinical efficacy data. The home care end-user segment represents the fastest-expanding channel as direct-to-patient pharmacy dispensing and telemedicine prescribing reduce clinic visit dependencies.
FDA bioequivalence standards and EMA quality guidelines jointly determine acceptable impurity profiles and dissolution specifications for topical azole generics entering regulated markets. The EPA monitors environmental release thresholds from pharmaceutical manufacturing facilities producing azole compounds. Japan's PMDA maintains distinct local clinical trial requirements that shape registration strategies for multinational sponsors. Stakeholders must monitor evolving pharmacovigilance reporting obligations and biosimilar guidance clarity to anticipate competitive entry timelines and pricing pressure dynamics.
Market Dynamics
Topical antifungal penetration technology is compressing treatment timelines and shifting prescribing patterns away from oral terbinafine toward nail-directed therapy. FDA bioequivalence standards for topical azoles are tightening impurity thresholds, forcing reformulation investments across the supply base.
Growth Catalysts
- Onychomycosis diagnosis expansion:Podiatry clinics in the United States are integrating dermoscopy and fungal PCR testing, capturing subclinical infections earlier and expanding the addressable patient pool for topical intervention.
- REACH-compliant excipient innovation:European manufacturers are qualifying novel penetration enhancers that satisfy ECHA safety standards while improving transungual drug delivery without systemic absorption risks.
- Telemedicine prescribing infrastructure:Direct-to-patient pharmacy platforms are eliminating clinic visit dependencies, accelerating refill adherence and extending treatment persistence in the home care segment.
Market Restraints
- API supply concentration:Qualified secondary suppliers for efinaconazole active pharmaceutical ingredient remain limited to Indian and Chinese manufacturers, creating vulnerability to customs delays and geopolitical friction.
- Terbinafine oral substitution:Generic oral antifungals command lower total therapy cost for severe cases, pressuring payer reimbursement for topical solutions in managed care formularies.
- EPA environmental release thresholds:Manufacturing facilities producing azole compounds face escalating wastewater monitoring requirements that extend facility commissioning timelines and inflate compliance capex.
Strategic Opportunities
- Pediatric label extension:Unmet need in adolescent onychomycosis creates white space for sponsors willing to conduct juvenile toxicology studies under FDA pediatric investigation plan pathways.
- Combination topical-device platforms:Convergence of 10% efinaconazole solution with fractional laser pretreatment protocols is opening aesthetic dermatology channels previously inaccessible to pure pharmaceutical positioning.
- Japan PMDA local trial reciprocity:Multinational sponsors leveraging Japanese clinical data for Asian registration are compressing time-to-market in South Korea and Taiwan through regional harmonization initiatives.
Industry Challenges
- Transungual pharmacokinetic expertise scarcity:Formulation scientists capable of optimizing nail plate penetration without compromising stability are concentrated among Japanese and European specialists, constraining rapid product iteration.
- Quality agreement complexity:Multi-source API procurement requires reconciling divergent pharmacopoeial standards between USP, EP, and JP monographs, extending vendor qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Efinaconazole Market |
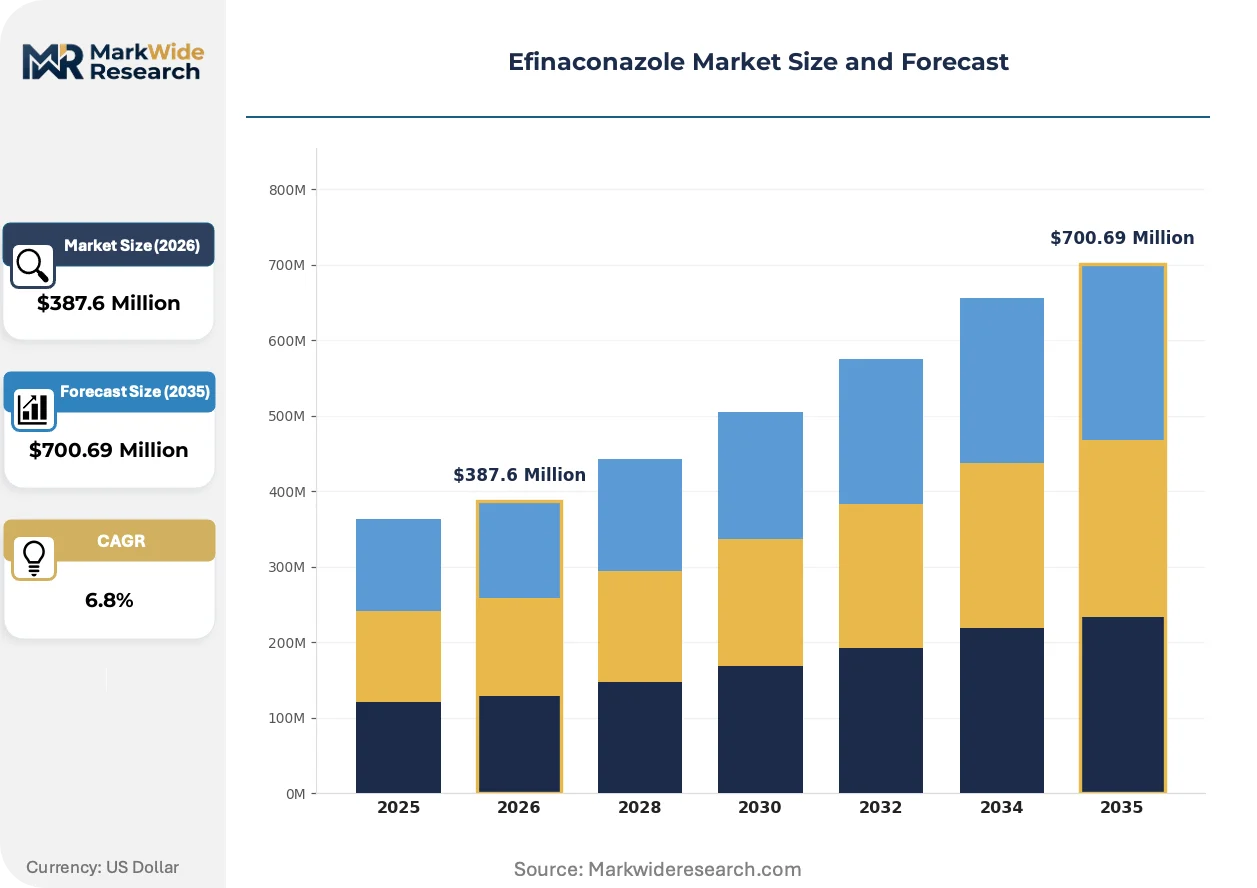
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Creams, Gels, Sprays Application: Onychomycosis, Fungal Infections, Dermatology, Therapeutic Use End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Pfizer Inc., Bausch Health Companies Inc., Novartis AG, Moberg Pharma AB, Glenmark Pharmaceuticals, Taro Pharmaceutical Industries, Kaken Pharmaceutical Co., Ltd., LEO Pharma, Mylan NV (Viatris), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Efinaconazole Market Emerging Trajectories
Penetration enhancement chemistry and diagnostic automation are converging to reshape how onychomycosis is identified and treated. These shifts are compressing the gap between symptom onset and effective therapy initiation.
Microemulsion-based delivery systems are automating the optimization of drug flux through the nail plate barrier. Dermatology clinics adopting these advanced vehicles report reduced treatment duration expectations, which is compressing competitive positioning around efficacy speed rather than safety differentiation alone. The technology is automating patient selection protocols by identifying optimal candidates through nail plate thickness screening.
EMA's revised MDR guidance on combination drug-device products is reclassifying laser-azole platforms as regulated medical devices rather than pure pharmaceuticals. Manufacturers must now submit technical documentation on energy dosing and tissue interaction, extending development timelines by 18-24 months for combination therapies. European sponsors are responding by segregating pure pharmaceutical and device development tracks to preserve regulatory optionality.
Direct primary care subscription models are displacing traditional fee-for-service prescribing for chronic dermatologic conditions. Employers in the United States are bundling onychomycosis treatment into telehealth benefits, shifting volume toward cash-pay pharmacy channels and compressing branded product net pricing. This behavioral pivot is most visible in Texas and Florida, where direct primary care penetration exceeds national averages by 40 percent.
Efinaconazole Market Segmentation
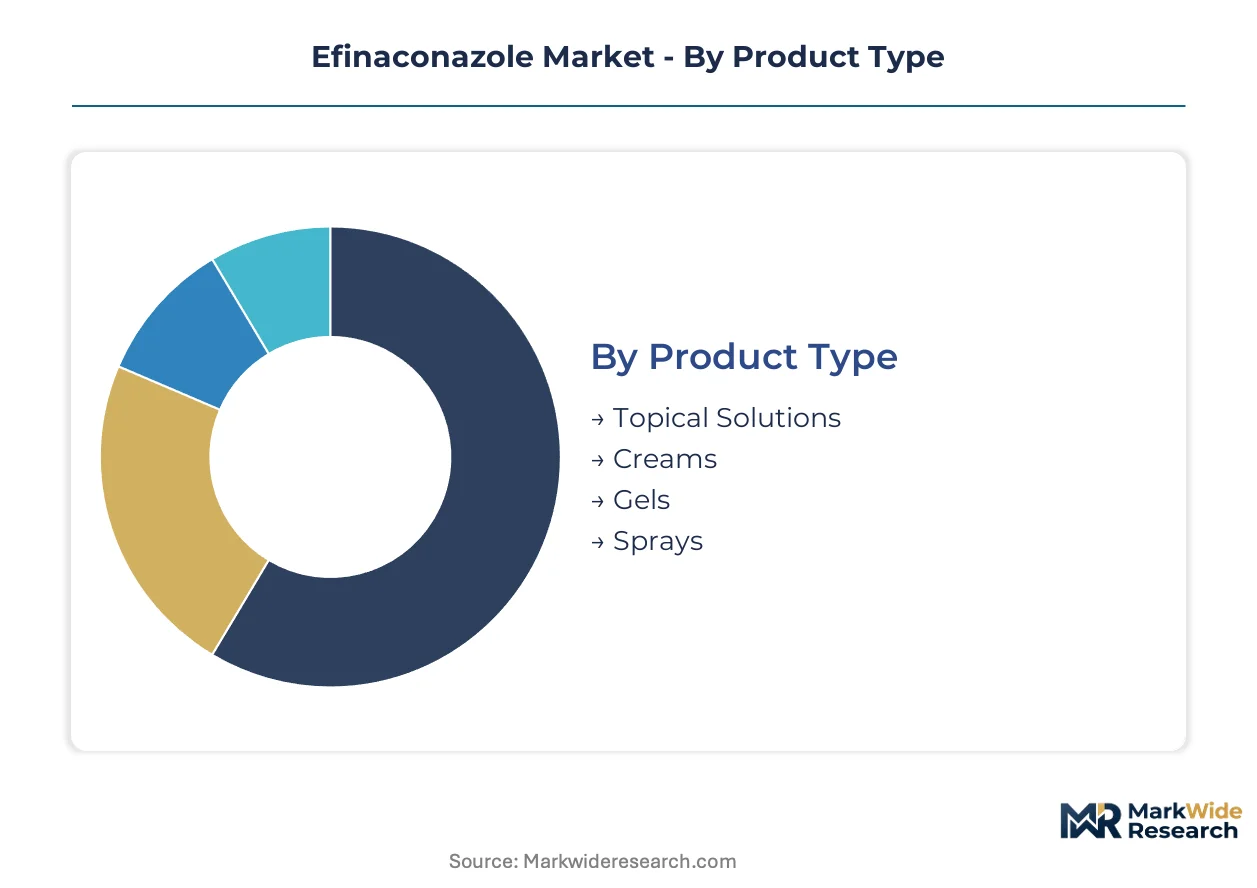
Segmentation in efinaconazole markets reveals how formulation technology, clinical setting, and patient access mode interact to determine commercial outcomes. Manufacturers must align product specifications with the precise penetration requirements and reimbursement pathways of each channel.
Product Type:
Standardization dominates low-viscosity liquids while customization concentrates in viscosity-modified and rapid-drying formats tailored to specific nail conditions.
- Topical Solutions:Low-viscosity 10% formulations in volatile solvent systems enable transungual flux rates optimized for distal lateral subungual onychomycosis. Demand concentrates in United States dermatology and podiatry practices where FDA-approved labeling supports prior authorization pathways. Manufacturers compete on drying time and cosmetic elegance to sustain patient persistence through 48-week protocols.
- Creams:Semi-solid emulsion systems with higher occlusivity suit periungual skin application but achieve limited nail plate penetration without mechanical abrasion. European pharmacies in Germany and France stock creams for patients with concurrent tinea pedis, leveraging EMA guidelines permitting combination therapy claims.
- Gels:Hydroalcoholic matrices with film-forming polymers offer intermediate penetration with reduced runoff. Japanese formulators at Kaken Pharmaceutical have developed gel variants with enhanced adhesion to hyponychium for humid climate markets.
- Sprays:Aerosol or pump-dispensed solutions target prophylactic use in athletic and communal shower settings. Institutional buyers in United Kingdom NHS trusts specify sprays for gymnasium and locker room dispensing protocols.
Most installed capacity flows through Topical Solutions. Expansion is steepest in Gels.
Application:
Volume concentrates in established indications while margin accumulates in adjacent therapeutic areas requiring label extension investment.
- Onychomycosis:Distal and lateral subungual presentations constitute the addressable population for efinaconazole monotherapy. United States podiatry clinics with dermoscopy and PCR confirmation capabilities are expanding diagnostic capture and prescription volume. Payer formularies increasingly require documented dermatophyte identification before approving topical therapy over oral generics.
- Fungal Infections:Off-label use against Candida and non-dermatophyte molds occurs where culture sensitivity guides therapy. Compounding pharmacies in Florida and Texas prepare customized concentrations for immunocompromised patients with mixed infections.
- Dermatology:Aesthetic practices incorporate efinaconazole into pre-laser nail treatment protocols. South Korean dermatology chains bundle antifungal priming with fractional laser sessions for onychomycosis with cosmetic complaints.
- Therapeutic Use:Prophylactic application in high-risk populations including diabetic patients and transplant recipients drives maintenance prescribing. Medicare Advantage plans in Arizona and Nevada are piloting chronic therapy coverage for recurrent cases.
Installed capacity concentrates in Onychomycosis. Dermatology is climbing the fastest.
End User:
Patient location determines reimbursement mechanics and compliance monitoring intensity across the care continuum.
- Hospitals:Inpatient consultation for severe or immunocompromised cases with suspected secondary bacterial infection. Academic medical centers in Massachusetts and California maintain fungal culture laboratories guiding parenteral-to-topical transitions.
- Clinics:Dermatology and podiatry offices generate the majority of index prescriptions with direct observation of nail plate involvement. Telemedicine-enabled clinics in Texas are displacing traditional office visits for refill authorization.
- Pharmacies:Community and specialty dispensing sites manage prior authorization workflows and patient assistance program enrollment. Independent pharmacies in Pennsylvania capture loyalty through adherence packaging and refill reminder programs.
- Home Care:Direct-to-patient delivery eliminates clinic dependency for maintenance phases. Home care is expanding most quickly as employer-sponsored telehealth benefits and cash-pay platforms reduce cost barriers.
Most installed capacity flows through Clinics. Home Care is gaining share fastest.
Distribution Channel:
Channel selection reflects patient price sensitivity, insurance status, and urgency of therapy initiation.
- Online:Mail-order pharmacies and direct-to-consumer platforms serve cash-pay patients and high-deductible plan holders. Amazon Pharmacy and Capsule in New York metropolitan area offer same-day delivery competing with retail convenience.
- Retail:Chain and independent brick-and-mortar locations handle acute prescriptions and insurance adjudication. CVS and Walgreens in Florida maintain 24-hour availability for podiatry referrals with immediate treatment initiation.
- Wholesale:Primary distribution to institutional and long-term care pharmacies with volume contracting. McKesson and Cardinal Health service United States hospital systems with temperature-controlled logistics for temperature-sensitive formulations.
- Direct Sales:Manufacturer-to-provider arrangements for sample programs and patient starter kits. Kaken Pharmaceutical deploys specialized sales representatives to Japanese dermatology clinics with device combination protocols.
Installed capacity concentrates in Retail. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New Jersey pharmaceutical corridor anchors efinaconazole commercialization through dense dermatology and podiatry practice networks. Regulatory pathways in the United States, Japan, and Europe determine where formulation investments concentrate. Manufacturing clusters in India and China supply active pharmaceutical ingredient while formulation finishing occurs in regulated markets.
United States
Podiatry clinics in Texas and Florida drive prescription volume through dermoscopy-equipped diagnostic protocols. FDA bioequivalence standards for topical azoles tighten impurity thresholds, forcing reformulation investments by domestic manufacturers. The New Jersey corridor hosts commercial operations coordinating supply to dermatology practices nationwide.
Japan
Kaken Pharmaceutical's specialized topical expertise originated in domestic dermatology channels before regional expansion. PMDA maintains distinct local clinical trial requirements that shape registration strategies for multinational sponsors. The Kanto region around Tokyo concentrates formulation R&D and medical affairs operations serving Asian markets.
Germany
EMA quality guidelines determine acceptable impurity profiles for topical azole generics entering European markets. REACH-compliant excipient innovation qualifies novel penetration enhancers satisfying ECHA safety standards. The Rhine-Ruhr industrial zone hosts pharmaceutical manufacturing facilities navigating escalating wastewater monitoring requirements.
India
Glenmark Pharmaceuticals anchors position through backward integration into active pharmaceutical ingredient production. CDSCO regulates domestic manufacturing while Indian producers supply qualified secondary API to global formulators. Maharashtra's pharmaceutical belt concentrates API synthesis operations serving regulated market sponsors.
United Kingdom
NHS trusts specify sprays for gymnasium and locker room dispensing protocols in institutional settings. MHRA aligns with EMA guidelines while post-Brexit divergence creates parallel compliance tracks. The Southeast England cluster around London maintains medical affairs and regulatory submission capabilities for European market access.
Efinaconazole Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue device combination and pediatric label extensions. The market structure consolidates around multinational pharmaceutical corporations with dermatology franchises and specialized topical formulators. Three archetypes dominate: integrated API-to-brand manufacturers, pure-play topical specialists, and generic entrants leveraging bioequivalence pathways. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure qualified secondary API supply.
Among integrated pharmaceutical corporations, Pfizer Inc. and Novartis AG exemplify scale-driven archetypes with global manufacturing footprints sustaining consistent supply across regulated markets. Kaken Pharmaceutical Co., Ltd. occupies a specialist position developed through Japanese market formulation expertise. Glenmark Pharmaceuticals represents the API-integrated model with captive active pharmaceutical ingredient production.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bausch Health Companies Inc. |
| Novartis AG |
| Moberg Pharma AB |
| Glenmark Pharmaceuticals |
| Taro Pharmaceutical Industries |
| Kaken Pharmaceutical Co., Ltd. |
| LEO Pharma |
| Mylan NV (Viatris) |
| Others |
Supply Flow & Price Mechanics
Formulation scientists specializing in transungual pharmacokinetics cluster in Japan and Europe, creating labor-cost differentials that widen pricing-tier spreads between premium branded solutions and economy-positioned generics.
Pricing Analysis
Input-cost pass-through from API procurement volatility shapes contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates originator brands with clinical data packages from FDA-approved generics and unbranded alternatives. Price differentiation hinges on bioequivalence certification tier and after-sales patient support bundling. Pricing pressure stems from terbinafine oral substitution in managed care formularies, with hospital procurement committees exhibiting highest price sensitivity versus cash-pay dermatology patients.
Supply Chain Analysis
Direct-to-pharmacy distribution handles branded volume while wholesale channels service institutional buyers and generic substitution markets. API synthesis concentrates in India and China, with formulation finishing in the United States, Japan, and Germany. Manufacturing depends on qualified triazole intermediate suppliers, REACH-compliant penetration enhancers, and cold-chain logistics for temperature-sensitive finished goods. Single-source vulnerability in Indian API production creates exposure to customs delays and geopolitical friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Japanese PMDA clinical trial requirements and FDA bioequivalence pathways creates cost differentials for sponsors optimizing registration sequencing.
For Market Incumbents: Cement API supply security through captive production or exclusive secondary supplier agreements in Maharashtra and Gujarat. Lock in dermatology clinic formulary positioning before generic oral terbinafine pressure intensifies in Medicare Advantage plans. Prioritize pediatric investigation plan submissions to extend exclusivity windows.
For New Entrants and Emerging Players: Telemedicine platforms represent the most penetrable channel for bypassing incumbent clinic relationships. Target cash-pay home care segments in Texas and Florida where direct primary care penetration exceeds national benchmarks. Pursue combination laser-device positioning to access aesthetic dermatology channels.
For Investors and Strategic Acquirers: Dermatology-focused pharmaceutical corporations are the most active acquirer in this space, seeking topical formulation capabilities. Long-term viability favors sponsors with integrated API production and device combination pipelines. Watch FDA bioequivalence guidance clarity on topical azole impurities as inflection indicator for generic entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Glenmark Pharmaceuticals anchors supply security through captive manufacturing in Maharashtra's pharmaceutical belt. |
| Pediatric Label Extension | Juvenile toxicology studies under FDA pediatric investigation plans open white space in adolescent onychomycosis. |
| Combination Device Partnership | Laser-azole platforms access aesthetic dermatology channels previously closed to pure pharmaceutical positioning. |
| Telemedicine Channel Development | Direct-to-patient pharmacy platforms reduce clinic dependency and accelerate refill adherence in home care segments. |
| Regional Registration Harmonization | Japanese PMDA clinical data reciprocity compresses time-to-market in South Korea and Taiwan. |
Methodological Framework
Multiple input streams — primary interviews with dermatology practice managers, regulatory affairs specialists at topical formulators, and formulary directors at Medicare Advantage plans; secondary validation through FDA Orange Book listings, EMA assessment reports, ClinicalTrials.gov protocols, and Japanese PMDA review documents; plus customs trade data on triazole API movements — were reconciled through bottom-up prescription volume modeling and top-down market sizing triangulation.
Historical prescription audit data from IQVIA and Symphony Health were cross-referenced against panel input from podiatry clinic operators and pharmacy benefit managers. Segmentation dimensions modeled include formulation type, end-user setting, distribution channel, and regional regulatory cluster. CAGRs were derived from treatment persistence curves, diagnosis rate expansion assumptions, and payer coverage evolution across the projection horizon. Forecast inputs incorporated dermoscopy adoption rates in United States podiatry practices and telemedicine prescribing infrastructure buildout.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA bioequivalence standard tightening, EPA wastewater discharge rulemaking, and geopolitical friction affecting Indian API supply. Forecasts reflect documented assumptions on patient persistence, generic entry timing, and reimbursement policy evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Chemotherapy Induced Anemia Market