
 Global Oncolytic Virotherapy Market | 2026-2036
Global Oncolytic Virotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncolytic Virotherapy Market Foresight
The divergence between premium engineered viral platforms and commodity viral backbone supply is hardening in the oncolytic virotherapy space. Amgen leverages its approved T-VEC franchise to anchor commercial infrastructure in melanoma and head and neck indications. Replimune specializes in next-generation armed viruses with dual mechanism payloads, competing on immunogenic cell death potency rather than direct lysis alone.
Oncolytic virotherapy employs replication-competent or replication-deficient viruses engineered to selectively infect and destroy malignant cells while sparing healthy tissue, with functional parameters including tumor selectivity ratios, viral titer thresholds measured in plaque-forming units per milliliter, and payload delivery efficiency determining clinical utility. Genetically modified viruses command the deepest margin pools as developers stack transgenes for cytokine expression and checkpoint modulation, while intratumoral injection retains primacy in delivery mode due to established pharmacokinetic control and reduced systemic neutralization compared to intravenous routes. Non-replicating viruses occupy a narrower niche where safety concerns override efficacy optimization in immunocompromised patient populations.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme reshape demand by compressing regulatory review timelines for qualifying oncolytic constructs, while the EU's ATMP framework imposes centralized manufacturing and traceability standards that filter out undercapitalized developers. Japan's PMDA operates a distinct sakigake designation that accelerates access for companies navigating Asian market entry. Stakeholders must monitor how evolving biosafety containment requirements and evolving gene therapy GMP standards will redistribute competitive advantage between platform-owning biotechs and contract manufacturing organizations.
Market Dynamics
The engineered virus arms race between replication-competent and replication-deficient platforms is compressing development cycles while fragmenting manufacturing standards across jurisdictions. Developers must now synchronize payload design with evolving biosafety containment tiers and gene therapy GMP requirements.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated pathway compresses regulatory review timelines for qualifying oncolytic constructs, enabling earlier commercialization for melanoma and head and neck cancer indications.
- Intratumoral Injection Dominance:This delivery mode retains primacy due to established pharmacokinetic control and reduced systemic neutralization compared to intravenous administration routes.
- Boston-Houston-San Diego Clustering:Specialized immuno-oncology hubs concentrate investigator-initiated trial funding from the National Cancer Institute, anchoring early-phase development infrastructure.
Market Restraints
- Gene Therapy GMP Capital Intensity:Biosafety Level 2+ containment requirements for replication-competent viruses demand specialized cleanroom infrastructure that filters out undercapitalized developers.
- Systemic Neutralization Barriers:Pre-existing immunity and complement activation limit intravenous delivery efficacy, constraining addressable patient populations to accessible lesions.
- EU ATMP Centralization:The European Union's Advanced Therapy Medicinal Products framework imposes centralized manufacturing and traceability standards that raise compliance costs.
Strategic Opportunities
- Japan Sakigake Pathway:The PMDA's designation accelerates Asian market entry for companies navigating distinct reimbursement and clinical trial requirements.
- Armed Virus Payload Stacking:Dual-mechanism constructs combining cytokine expression with checkpoint modulation represent white space beyond direct lysis platforms.
- Academic Medical Center Partnerships:Hospital oncology departments are expanding adoption of investigator-initiated trials, creating alternative funding channels outside traditional biopharma structures.
Industry Challenges
- Viral Titer Manufacturing Consistency:Plaque-forming unit reproducibility across batches remains technically demanding, with potency assays requiring specialized analytical capabilities.
- Payload Immunogenicity Prediction:Transgene expression levels and host immune response modeling lack standardized preclinical frameworks, extending IND-enabling timelines.
- Multi-jurisdictional GMP Harmonization:Divergent containment requirements between FDA, EMA, and PMDA standards complicate single-site manufacturing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncolytic Virotherapy Market |
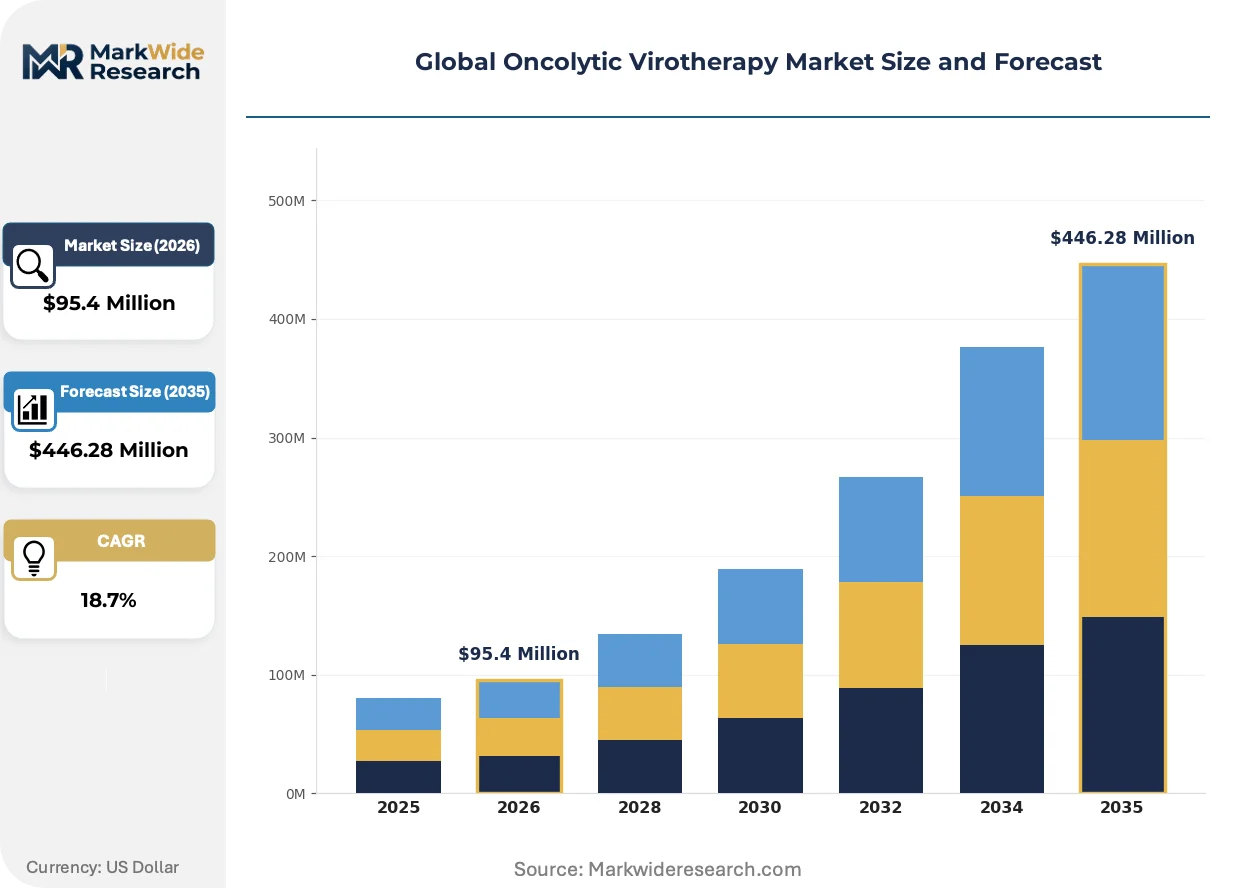
| Market Size in 2026 | $95.4 Million |
| Market Size in 2035 | $446.28 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Replicating Viruses, Non-Replicating Viruses, Genetically Modified Viruses, Natural Viruses Therapy Area: Melanoma, Glioblastoma, Pancreatic Cancer, Bladder Cancer, Head & Neck Cancer End User: Research Institutes, Biopharmaceutical Firms, Clinical Research Organizations, Specialized Clinics Delivery Mode: Intratumoral Injection, Intravenous Administration, Intraperitoneal Injection, Aerosol Delivery |
| Companies Covered | Amgen, Transgene SA, Sorrento Therapeutics, Oncolytics Biotech, SillaJen, Replimune, Genelux Corporation, CG Oncology, Oncolys BioPharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncolytic Virotherapy Market Shifts & Advancements
Engineered viral platforms are converging with synthetic biology toolkits to enable programmable tumor selectivity and payload delivery. This convergence is redrawing competitive boundaries between platform-owning biotechs and contract manufacturing organizations.
Next-generation armed viruses are integrating transgenes for cytokine expression and checkpoint modulation into single constructs. Academic medical centers in the United States are adopting these dual-mechanism platforms at pace for early-phase trials. The technology is integrating immunogenic cell death potency with direct lysis, compressing the efficacy gap between local and systemic administration routes.
The EMA's PRIME scheme is reshaping European development priorities by offering accelerated assessment for oncolytic constructs addressing unmet needs. Manufacturers are restructuring regulatory submission timelines to align with centralized ATMP manufacturing requirements. Developers targeting orphan indications are reallocating resources toward EU market entry to leverage this tailwind.
Buyer concentration is consolidating demand around integrated immuno-oncology hubs that combine clinical trial infrastructure with specialized manufacturing partnerships. Hospital systems are displacing standalone research institutes as the primary trial sponsors in the United States. This shift is most visible in melanoma and head and neck cancer verticals, where academic medical centers bundle patient access with GMP-adjacent production capabilities.
Global Oncolytic Virotherapy Market Segmentation
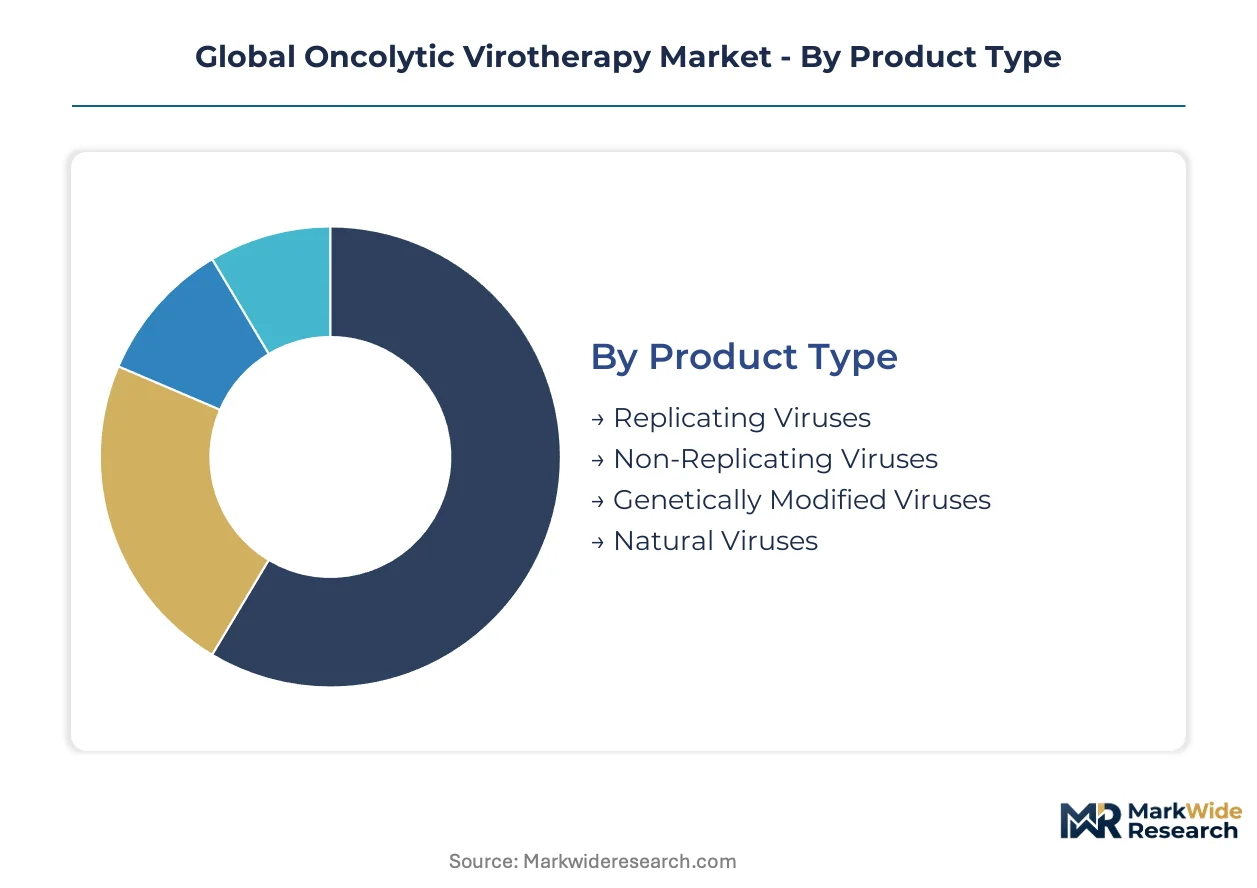
Oncolytic virotherapy segmentation reveals where capital allocation concentrates versus where clinical utility actually materializes. Product engineering decisions, delivery route selection, and end-user infrastructure requirements create divergent margin profiles across the value chain.
Product Type:
Capital intensity varies sharply across viral engineering tiers, with containment infrastructure and genetic modification complexity driving facility investment requirements.
- Genetically Modified Viruses:These constructs incorporate stacked transgenes for cytokine expression and checkpoint modulation, requiring Biosafety Level 2+ cleanrooms and specialized potency assay capabilities. Demand concentrates in Boston and San Diego immuno-oncology hubs where the National Cancer Institute funds early-phase investigator-initiated trials, with payload immunogenicity prediction bottlenecks extending IND-enabling timelines.
- Replicating Viruses:Replication-competent platforms like T-VEC selectively infect and destroy malignant cells through direct lysis, demanding stringent viral titer manufacturing consistency across plaque-forming unit batches. Hospital oncology departments favor these platforms for melanoma indications where intratumoral pharmacokinetic control is established.
- Non-Replicating Viruses:Replication-deficient constructs occupy narrower niches where safety concerns override efficacy optimization in immunocompromised populations.
- Natural Viruses:Unmodified viral backbones serve primarily as supply inputs for engineered platform developers rather than standalone therapeutic products.
Genetically modified viruses absorb the bulk of installed capacity; replicating viruses are expanding most quickly.
Therapy Area:
Addressable patient populations and regulatory pathway eligibility reshape commercial prioritization across oncology verticals.
- Melanoma:The FDA's breakthrough therapy designation has compressed review timelines for oncolytic constructs in this indication, with Amgen's approved franchise anchoring commercial infrastructure. Academic medical centers in Houston cluster phase I/II trial activity for armed virus candidates.
- Head & Neck Cancer:Intratumoral injection accessibility drives adoption where lesion surface area permits direct visualization, with the EMA's PRIME scheme accelerating European assessment for constructs addressing this unmet need.
- Glioblastoma:Blood-brain barrier penetration challenges constrain delivery mode selection to intratumoral or convection-enhanced approaches.
- Pancreatic Cancer:Dense stromal microenvironments limit viral spread efficiency, compressing efficacy expectations relative to other solid tumors.
- Bladder Cancer:Intravesical delivery routes offer localized administration potential with reduced systemic neutralization exposure.
Melanoma commands the deepest clinical trial investment; head and neck cancer is gaining share fastest.
End User:
Buyer concentration is consolidating around entities that combine patient access with manufacturing-adjacent capabilities.
- Biopharmaceutical Firms:Platform-owning developers like Replimune anchor demand for dual-mechanism armed viruses, integrating payload design with contract manufacturing organization partnerships to navigate multi-jurisdictional GMP harmonization challenges.
- Research Institutes:Standalone research institutes are losing primacy as trial sponsors to hospital systems that bundle GMP-adjacent production with patient recruitment.
- Clinical Research Organizations:CROs capture outsourcing demand from undercapitalized developers filtered out by EU ATMP centralized manufacturing requirements.
- Specialized Clinics:Boutique oncology practices lack the infrastructure for oncolytic virotherapy administration, constraining their role in the value chain.
Biopharmaceutical firms deploy the most capital; hospital-affiliated academic medical centers are displacing standalone institutes.
Delivery Mode:
Pharmacokinetic control and systemic neutralization barriers create tiered efficacy profiles that reshape addressable populations.
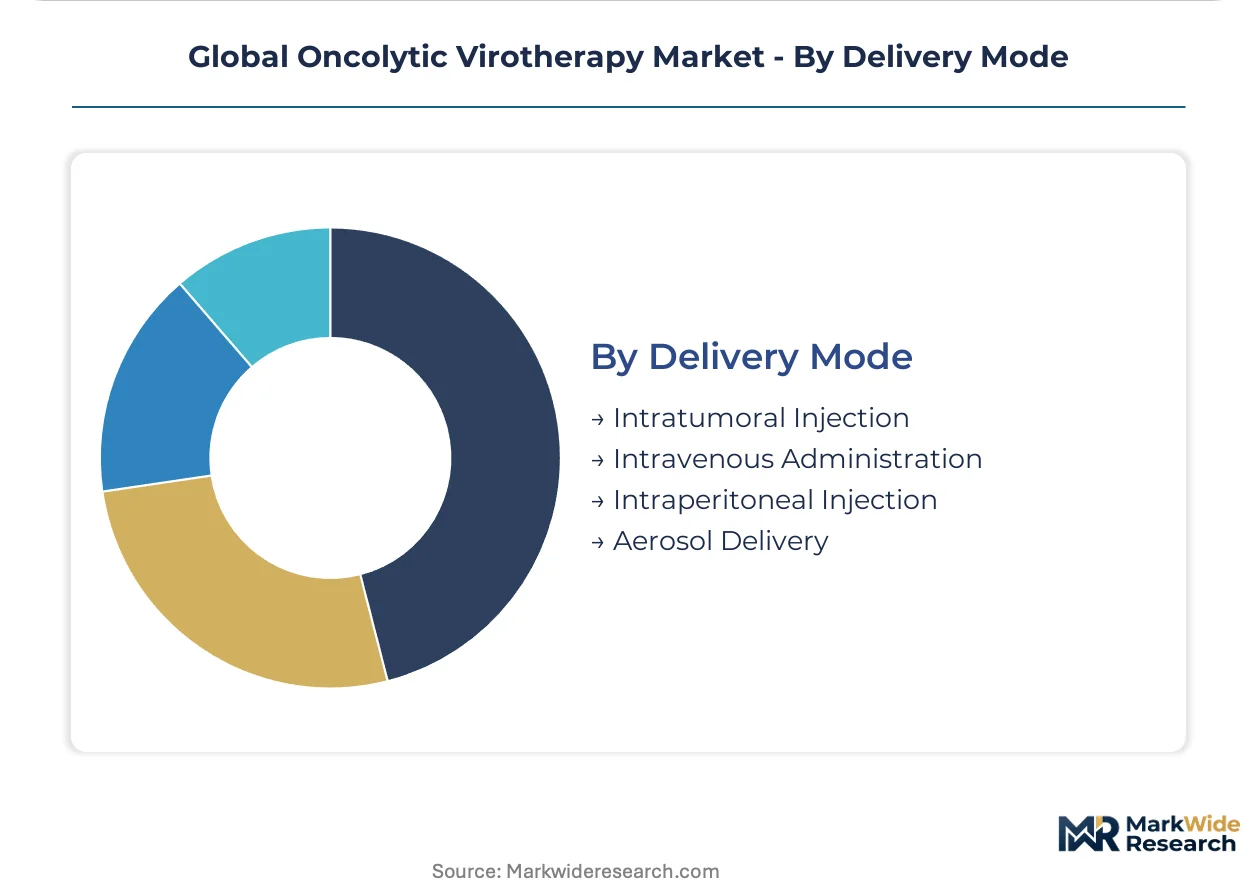
- Intratumoral Injection:Direct lesion administration retains primacy due to established pharmacokinetic control and reduced systemic neutralization compared to intravenous routes, limiting addressable patients to those with accessible tumors.
- Intravenous Administration:Pre-existing immunity and complement activation constrain efficacy, though next-generation armed viruses with immunogenic cell death potency are compressing the gap with local administration.
- Intraperitoneal Injection:Peritoneal carcinomatosis indications offer a defined niche for regional delivery with cavity-specific viral distribution.
- Aerosol Delivery:Pulmonary administration remains experimental, with biosafety containment requirements for replication-competent viruses complicating inhalation device development.
Intratumoral injection dominates current utilization; intravenous routes are climbing the fastest as payload engineering advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the global oncolytic virotherapy research infrastructure through its concentration of academic medical centers and National Cancer Institute-funded investigator-initiated trials. Hospital systems in this cluster bundle patient access with GMP-adjacent production capabilities, creating integrated development ecosystems that attract platform-owning biotechs.
United States
Specialized immuno-oncology hubs in Houston and San Diego complement Boston's research dominance, with the FDA's breakthrough therapy designation compressing regulatory timelines for melanoma and head and neck cancer constructs. The National Cancer Institute channels early-phase funding through these clusters, while Biosafety Level 2+ containment requirements filter undercapitalized developers from manufacturing participation.
Japan
The PMDA's sakigake designation accelerates Asian market entry for companies navigating distinct reimbursement frameworks, creating regulatory arbitrage opportunities for developers targeting orphan indications. Tokyo and Osaka academic medical centers are expanding adoption of armed virus platforms, with centralized manufacturing requirements under the Pharmaceuticals and Medical Devices Act raising compliance thresholds for foreign entrants.
Germany
The EMA's PRIME scheme and centralized ATMP manufacturing standards are restructuring European development priorities, with Munich and Heidelberg emerging as gene therapy GMP hubs. German hospital oncology departments are displacing standalone research institutes as primary trial sponsors, bundling patient recruitment with specialized containment infrastructure for replication-competent viruses.
United Kingdom
London's concentration of contract manufacturing organizations is capturing outsourcing demand from platform developers facing multi-jurisdictional GMP harmonization challenges. The MHRA operates post-Brexit regulatory pathways that retain alignment with EMA standards while offering distinct early access schemes, with Cambridge and Oxford academic centers driving early-phase armed virus adoption.
China
The NMPA's accelerated review pathways for innovative biologics are attracting domestic developers of engineered viral platforms, with Shanghai and Beijing biotech clusters expanding manufacturing capacity. China's gene therapy GMP standards are converging with international containment requirements, though viral titer manufacturing consistency remains a technical bottleneck for local producers.
Global Oncolytic Virotherapy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the oncolytic virotherapy value chain. The market structure fragments between platform-owning biotechs with integrated manufacturing capabilities and developers reliant on contract manufacturing organizations for Biosafety Level 2+ containment. Three archetypes dominate: approved franchise holders leveraging commercial infrastructure, next-generation armed virus specialists stacking dual-mechanism payloads, and regional developers exploiting accelerated regulatory pathways. Competitive moves concentrate on strategic partnerships for GMP capacity access and payload licensing arrangements that circumvent capital-intensive facility builds.
Within the approved franchise tier, Amgen anchors commercial infrastructure through its established melanoma and head and neck cancer presence. Among next-generation platform developers, Replimune and CG Oncology occupy positions emphasizing immunogenic cell death potency beyond direct lysis mechanisms. Transgene SA represents European developers navigating centralized EMA manufacturing requirements. These companies exemplify divergent strategic postures between leveraging existing commercial footprints and building specialized armed virus capabilities from development-stage foundations.
| Leading Market Players |
|---|
| Amgen |
| Transgene SA |
| Sorrento Therapeutics |
| Oncolytics Biotech |
| SillaJen |
| Replimune |
| Genelux Corporation |
| CG Oncology |
| Oncolys BioPharma |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up contract manufacturing organizations have consolidated Biosafety Level 2+ containment capacity across the United States and Germany, tightening supply discipline and anchoring premium pricing for genetically modified viral platforms. This ownership concentration lets specialized producers enforce value-based contracting while filtering price-sensitive developers from the replication-competent virus tier.
Pricing Analysis
Value-based pricing anchored to immunogenic cell death potency and clinical response rates dominates the engineered virus tier, with three-tier pricing structure across premium armed viruses, standard replication-competent platforms, and economy-grade natural backbones. Price differentiation hinges on payload complexity and FDA breakthrough therapy designation status, with certification under gene therapy GMP standards commanding substantial premiums. Pricing pressure stems from EU ATMP centralized manufacturing requirements raising compliance costs for smaller developers. Academic medical centers exhibit lowest price sensitivity due to National Cancer Institute funding channels, while standalone research institutes face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Boston, San Diego, and Houston operate hub-and-spoke patterns for clinical-grade viral vectors, with cold-chain logistics feeding trial sites across the United States. Manufacturing concentrates in the United States, Germany, and Japan, where gene therapy GMP infrastructure meets divergent FDA, EMA, and PMDA containment standards. Production draws from specialized plasmid suppliers, fetal bovine serum providers, and cell substrate vendors. Single-source vulnerability around master cell banks poses structural risk. Distribution runs through hospital-affiliated academic medical centers displacing standalone research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Oncolytic Virotherapy Market operates as a cost-of-compliance story where the FDA's gene therapy GMP standards and the EU's ATMP framework erect formidable barriers to entry, entrenching first-mover advantages for platform-owning biotechs with captive manufacturing infrastructure.
For Market Incumbents: Extend payload stacking capabilities into cytokine expression and checkpoint modulation combinations before next-generation armed virus specialists capture melanoma and head and neck cancer share. Lock in contract manufacturing organization partnerships across multiple jurisdictions to preempt multi-jurisdictional GMP harmonization disruptions. Vertical integration into viral titer manufacturing consistency capabilities defends margin position against biosafety containment cost inflation. For New Entrants and Emerging Players: The PMDA's sakigake designation in Japan opens a window for orphan indication developers to establish Asian market presence before competing for FDA breakthrough therapy pathways. Target intravenous administration routes for armed virus platforms where payload engineering advances are compressing efficacy gaps with intratumoral injection. Pursue academic medical center partnerships as an alternative funding channel outside traditional biopharma venture structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-owning biotechs with approved franchises or late-stage clinical assets in the United States, where regulatory moats deepen with each FDA breakthrough therapy designation. Long-term viability hinges on manufacturing-adjacent capabilities rather than pure development-stage pipelines. Watch for viral titer manufacturing consistency failures as an inflection signal for acquisition opportunities among capital-constrained developers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mechanism Payload Development | Armed viruses combining cytokine expression with checkpoint modulation address unmet needs in melanoma beyond direct lysis platforms. |
| Multi-Jurisdictional GMP Harmonization | Single-site manufacturing strategies navigating FDA, EMA, and PMDA standards reduce capital intensity for replication-competent virus production. |
| Academic Medical Center Partnerships | Hospital oncology departments bundle patient access with GMP-adjacent capabilities, displacing standalone research institutes as trial sponsors. |
| Intravenous Route Efficacy Advancement | Payload engineering advances compress the efficacy gap with intratumoral injection, expanding addressable patient populations. |
| Orphan Indication Regulatory Arbitrage | EMA PRIME scheme and PMDA sakigake designation accelerate market entry for constructs addressing unmet needs in rare cancers. |
Research Methodology
FDA filings, ClinicalTrials.gov records, and EMA ATMP submission databases formed the secondary backbone, cross-referenced against SEC 10-K disclosures and National Cancer Institute grant portfolios. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors validated demand assumptions across the United States, Germany, and Japan. Bottom-up and top-down triangulation reconciled viral titer manufacturing capacity estimates with investigator-initiated trial enrollment projections.
Bottom-up modeling segmented the market across genetically modified, replicating, and non-replicating virus product types; melanoma, head and neck cancer, glioblastoma, pancreatic cancer, and bladder cancer therapy areas; and intratumoral, intravenous, intraperitoneal, and aerosol delivery modes. CAGRs derived from fitted adoption curves for armed virus platforms and regulatory pathway acceleration effects. Forecast inputs included payload immunogenicity prediction timelines, biosafety containment capacity expansion rates, and academic medical center infrastructure investment patterns across the projection horizon.
The model assumes a particular technology adoption path favoring replication-competent armed viruses; alternative pathways for non-replicating platforms in immunocompromised populations would alter the outlook. Forecasts reflect stated assumptions around FDA breakthrough therapy designation eligibility and EU ATMP manufacturing standard harmonization. Emerging biosafety containment requirements or gene therapy GMP standard revisions could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market