
 Neoantigen Targeted Therapies Market | 2026-2036
Neoantigen Targeted Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Neoantigen Targeted Therapies Market Outlook
Platform licensing revenue from neoantigen prediction algorithms is tilting toward companies with proprietary bioinformatics stacks. BioNTech SE leverages its mRNA manufacturing infrastructure to sustain clinical-scale vaccine production. Moderna, Inc. anchors its position through integrated RNA sequencing capabilities that shorten design-to-dose timelines. Gritstone bio differentiates via its EDGE artificial intelligence platform for tumor-specific antigen identification.
Neoantigen targeted therapies constitute precision immunotherapies that engineer patient-specific treatments by identifying tumor-specific mutations through genomic profiling and synthesizing corresponding therapeutic agents, typically requiring turnaround times under twelve weeks from biopsy to administration. Their primary purpose centers on eliciting durable T-cell responses against malignancies while sparing healthy tissue. Cell-based therapies command premium pricing due to autologous manufacturing complexity and limited production slots, whereas vaccines represent the fastest-expanding category as outpatient administration reduces hospital burden. Bioinformatics platforms increasingly determine competitive positioning, with proprietary algorithm accuracy directly influencing clinical trial success rates.
The FDA maintains accelerated approval and breakthrough therapy designations that compress neoantigen product development timelines, while the EMA's adaptive pathways framework creates parallel European market access. The NIH and NCI jointly govern trial funding standards that shape investigator site selection and patient recruitment priorities. Stakeholders must monitor evolving FDA guidance on personalized medicine manufacturing controls as these standards will determine which platforms achieve scalable commercial validation.
Market Dynamics
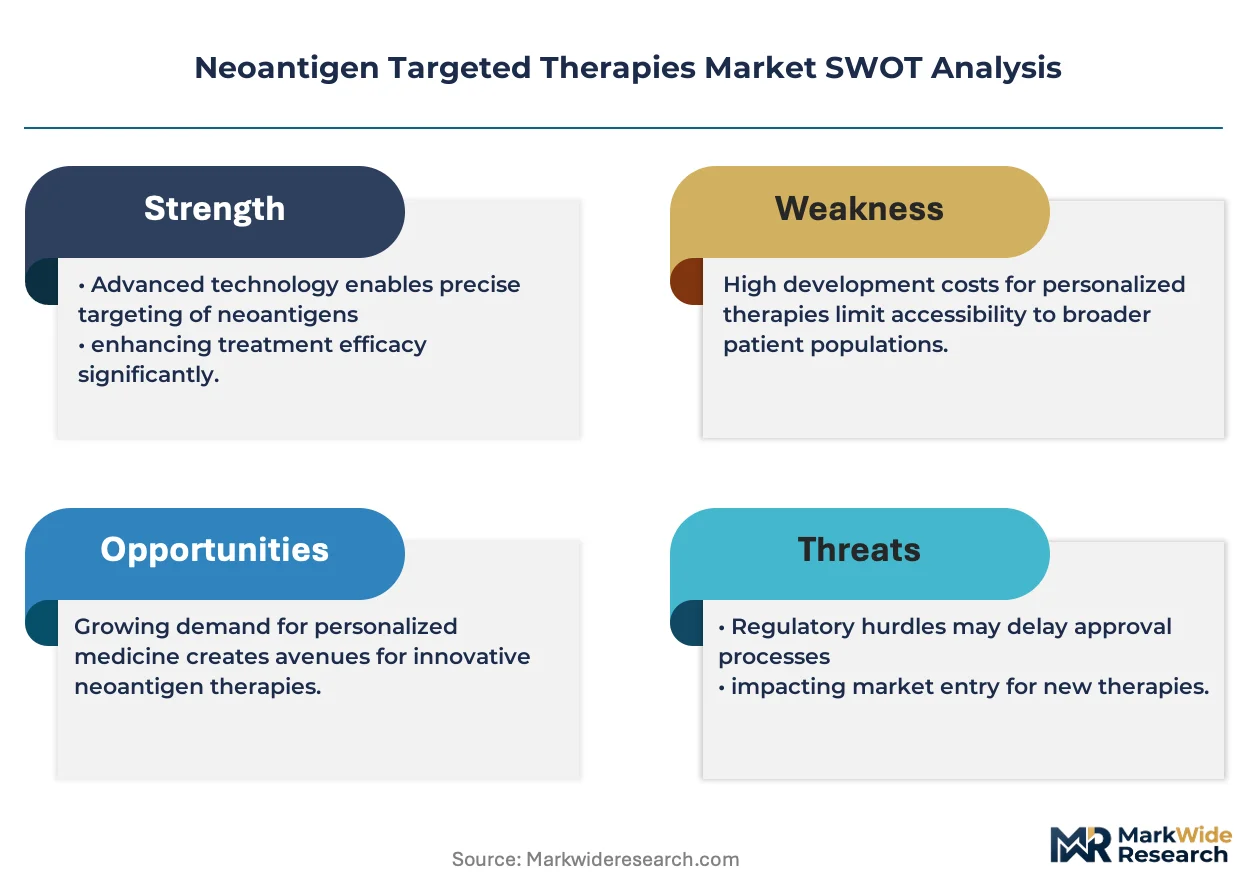
The compression of design-to-dose timelines below twelve weeks is restructuring competitive advantage around bioinformatics infrastructure and manufacturing slot availability rather than molecule chemistry alone.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation compresses Phase I-to-approval timelines for personalized cancer vaccines, enabling faster clinical validation cycles.
- mRNA Manufacturing Scale-Up:Lipid nanoparticle formulation capacity expansion at academic medical centers is reducing per-dose production costs for outpatient-administered neoantigen vaccines.
- NCI Trial Network Funding:The National Cancer Institute's dedicated neoantigen clinical trial infrastructure is concentrating patient recruitment and biomarker validation in United States oncology departments.
Market Restraints
- Autologous Cell Therapy Cost Structure:Patient-specific manufacturing requires dedicated cleanroom slots and vector production runs that cannot achieve economies of scale.
- Bioinformatics Talent Concentration:Predictive algorithm development depends on computational immunologists concentrated in Boston, San Francisco, and Basel, creating hiring bottlenecks.
- Tumor Heterogeneity Limitations:Clonal evolution during treatment windows reduces neoantigen target persistence, compromising durable response rates in solid malignancies.
Strategic Opportunities
- Allogeneic Off-the-Shelf Platforms:Shared antigen libraries derived from common oncogenic mutations could bypass autologous manufacturing constraints and expand addressable patient populations.
- EMA Adaptive Pathways:Parallel scientific advice and conditional marketing authorization in Europe enable synchronized US-EU launch timelines for breakthrough-designated therapies.
- Real-World Evidence Integration:Post-market registry requirements under FDA guidance create opportunities for continuous algorithm refinement using treatment response data.
Industry Challenges
- Quality Control Standardization:Batch release testing for personalized vaccines lacks harmonized potency assays, forcing platform-specific validation studies that extend regulatory submission timelines.
- Cold Chain Integrity:mRNA stability requirements demand continuous ultra-low temperature monitoring from manufacturing through administration, complicating site qualification for community oncology practices.
- Intellectual Property Fragmentation:Neoantigen prediction algorithms, manufacturing processes, and delivery vectors are patented across multiple institutions, creating licensing complexity for integrated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neoantigen Targeted Therapies Market |
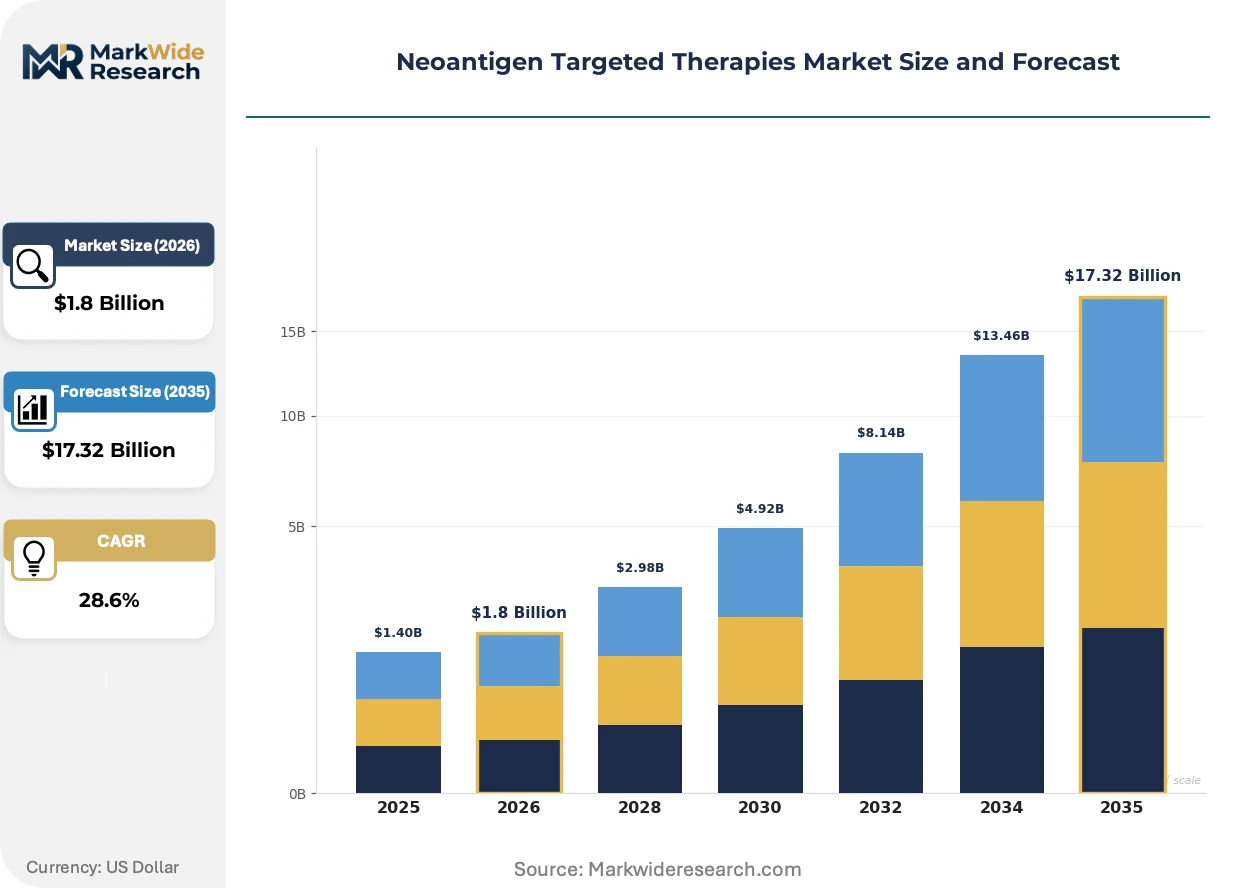
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cell-Based Therapies, Checkpoint Inhibitors Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Genetic Disorders Technology: CRISPR, RNA Sequencing, Bioinformatics, Genomic Profiling End User: Hospitals, Research Institutes, Pharmaceutical Companies, Biotechnology Firms |
| Companies Covered | BioNTech SE, Moderna, Inc., Gritstone bio, Achilles Therapeutics plc, Advaxis, Inc., Genocea Biosciences Inc., Medigene AG, Agenus Inc., Immatics NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neoantigen Targeted Therapies Market Strategic Shifts
Computational methods are displacing empirical screening as the primary determinant of target selection, while regulatory frameworks adapt to lot sizes of one.
Artificial intelligence-driven epitope prediction is hybridizing with multiplexed mass spectrometry to validate algorithm outputs against actual HLA-presented peptides. Oncology biopharma sponsors are adopting these integrated workflows to reduce clinical failure rates from immunogenicity mismatches. The convergence is compressing preclinical validation phases and raising barriers for platforms lacking both computational and experimental capabilities.
The FDA's emerging guidance on personalized medicine manufacturing controls is mandating process analytical technology for autologous cell and gene therapy production. Sponsors must demonstrate real-time release testing capabilities and closed-system manufacturing to qualify for expedited review. Cell therapy developers are responding by retrofitting facilities with integrated data capture systems, while vaccine platforms face lighter compliance burdens due to shorter production cycles.
Academic medical centers are consolidating procurement decisions through centralized neoantigen therapy committees that evaluate platforms based on trial portfolio fit and manufacturing slot guarantees. Community oncology networks are losing direct contracting authority as referral patterns concentrate at NCI-designated comprehensive cancer centers. The United States exhibits the most pronounced consolidation, with major metropolitan hospital systems capturing the majority of personalized vaccine administration volume.
Neoantigen Targeted Therapies Market Segmentation
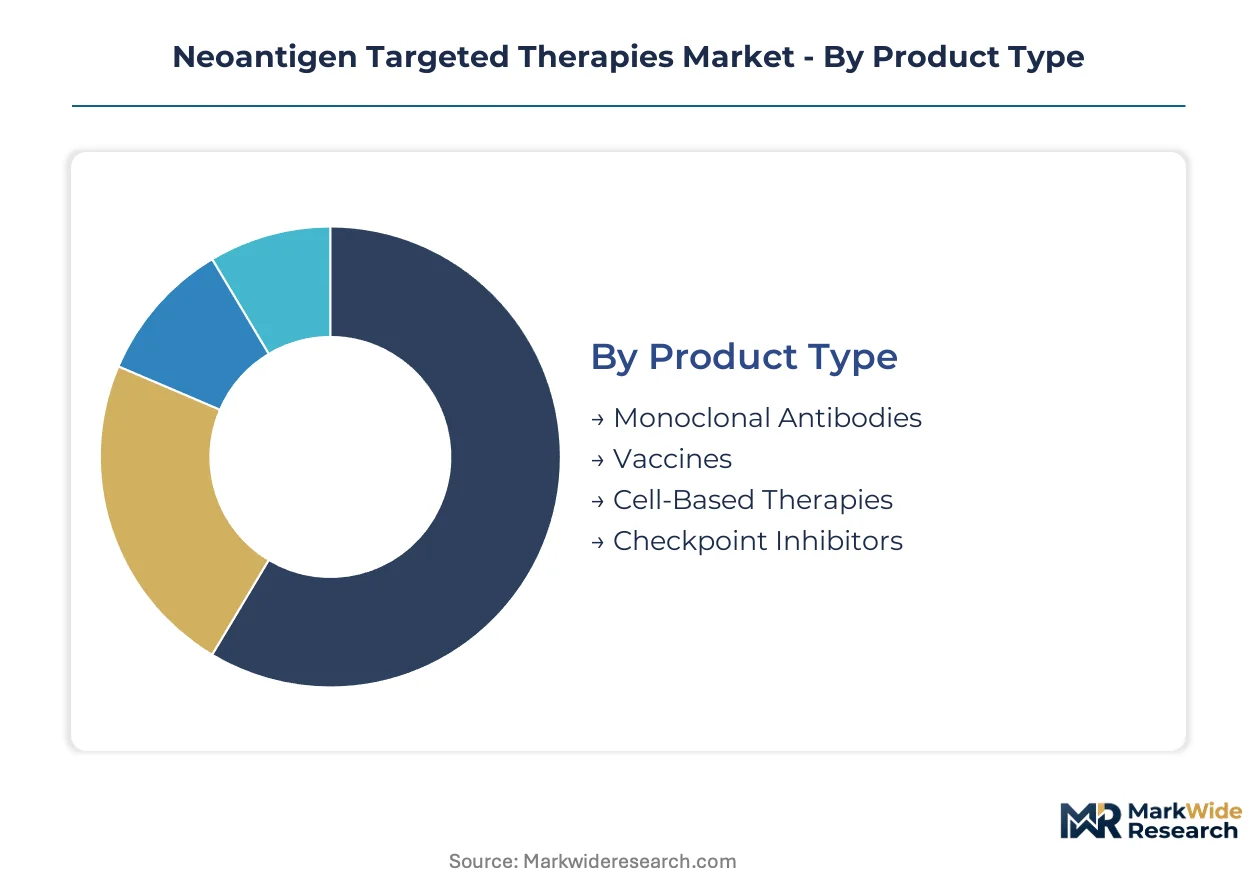
Neoantigen therapy segmentation reflects divergent manufacturing economics and clinical administration requirements. Product architecture determines pricing power and reimbursement complexity. Technology infrastructure separates scalable platforms from bespoke artisanal production.
Product Type:
The use-case spectrum spans outpatient prophylactic intervention to intensive inpatient cellular engineering.
- Vaccines:Synthetic peptide or mRNA constructs encoding patient-specific neoantigen sequences. Demand concentrates at NCI-designated comprehensive cancer centers in the United States, driven by outpatient administration protocols that preserve hospital bed capacity and compress reimbursement cycles.
- Cell-Based Therapies:Autologous T-cell products engineered ex vivo to express neoantigen-specific receptors. Manufacturing slots at academic medical centers in Boston, Houston, and Seattle command premium pricing due to cleanroom scarcity and vector production bottlenecks.
- Monoclonal Antibodies:Off-the-shelf biologics targeting shared tumor-associated antigens with neoantigen-like specificity.
- Checkpoint Inhibitors:Systemic immunomodulators that potentiate endogenous neoantigen recognition without patient-specific manufacturing.
Established volume favors Cell-Based Therapies; emerging adoption favors Vaccines.
Therapy Area:
Clinical development intensity correlates with unmet need severity and biomarker validation maturity.
- Oncology:Solid tumor and hematologic malignancy applications dominate pipeline investment. Melanoma and non-small cell lung cancer in the United States attract the deepest trial sponsorship due to high tumor mutational burden and established T-cell infiltration biomarkers.
- Autoimmune Disorders:Tolerance induction via neoantigen-specific regulatory T-cell engineering. Early-phase trials at University of Pennsylvania and Stanford University target multiple sclerosis and type 1 diabetes with autologous cell platforms.
- Infectious Diseases:Pathogen-derived neoantigen vaccines for chronic viral persistence.
- Genetic Disorders:Correction of neoantigen presentation defects in primary immunodeficiencies.
Clinical validation depth favors Oncology; pipeline expansion favors Autoimmune Disorders.
Technology:
Platform differentiation hinges on computational prediction accuracy married to experimental validation throughput.
- Bioinformatics:Proprietary algorithms for HLA-binding prediction and immunogenicity scoring. Licensing revenue concentrates with Boston and Basel-based computational immunology groups whose training datasets encompass diverse ethnic HLA repertoires.
- RNA Sequencing:Tumor-normal exome and transcriptome analysis for mutation identification. Integrated sequencing-to-manufacturing workflows at Moderna and BioNTech facilities compress design-to-dose timelines below industry benchmarks.
- Genomic Profiling:Multi-omic characterization of tumor microenvironment and antigen presentation machinery.
- CRISPR:Gene editing for T-cell receptor engineering and antigen presentation enhancement.
Revenue concentration favors Bioinformatics; capability integration favors RNA Sequencing.
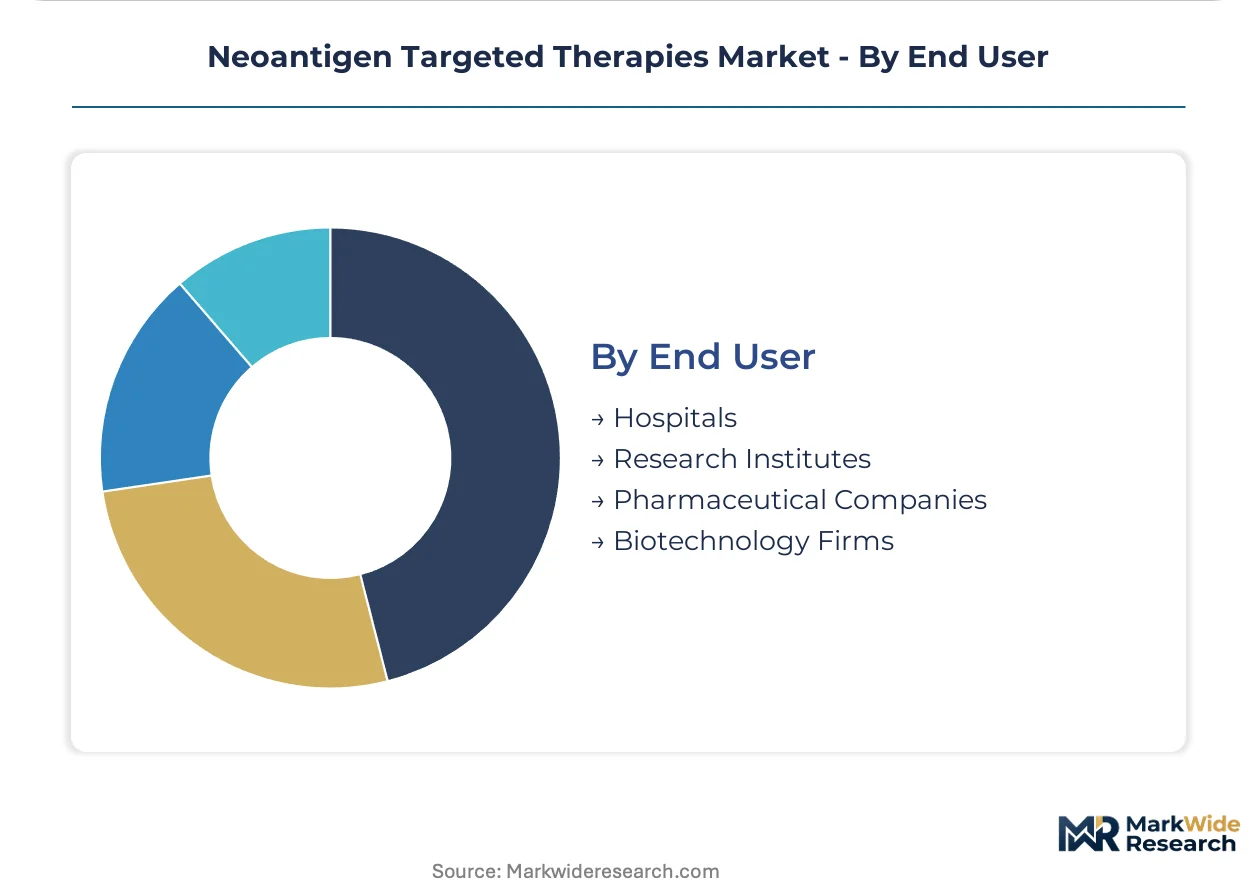
End User:
Purchasing authority is consolidating toward institutions with integrated trial infrastructure and manufacturing slot control.
- Hospitals:Academic medical centers with embedded GMP facilities and NCI trial network membership. Procurement decisions in the United States increasingly centralize through neoantigen therapy committees at Mayo Clinic, MD Anderson, and Memorial Sloan Kettering.
- Research Institutes:National laboratory and university-affiliated centers conducting biomarker validation and algorithm training. Funding from NIH and Wellcome Trust shapes platform prioritization at Broad Institute and Sanger Centre.
- Pharmaceutical Companies:Sponsor organizations outsourcing patient-specific manufacturing to contract development partners.
- Biotechnology Firms:Venture-backed platform developers seeking manufacturing slot guarantees through hospital partnerships.
Treatment volume concentrates at Hospitals; platform innovation originates at Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States oncology departments administer neoantigen therapies through outpatient protocols that compress reimbursement cycles, while European centers emphasize inpatient cellular engineering with longer production timelines. This consumption-mix differential reflects divergent healthcare infrastructure and regulatory pathway priorities across major markets.
United States
NCI-designated comprehensive cancer centers in Houston and Boston capture the deepest patient recruitment volumes for personalized vaccine trials. The FDA's breakthrough therapy designation accelerates Phase I-to-approval timelines, compressing development cycles for sponsors. Manufacturing slot scarcity at academic medical centers in Seattle and New York Metro commands premium pricing for autologous cell therapies.
Germany
BioNTech SE's mRNA manufacturing infrastructure in Mainz anchors European vaccine production capacity for neoantigen platforms. The EMA's adaptive pathways framework enables parallel scientific advice that synchronizes US-EU launch timelines. The Rhine-Main cluster concentrates computational immunology talent and lipid nanoparticle formulation expertise.
Switzerland
Basel-based computational immunology groups license proprietary HLA-binding prediction algorithms to global pharma sponsors. Swissmedic maintains alignment with FDA breakthrough designation standards, facilitating streamlined market access. The Basel-Zurich corridor hosts specialized bioinformatics training datasets encompassing diverse ethnic HLA repertoires.
United Kingdom
London and Cambridge research institutes conduct biomarker validation studies funded by the Wellcome Trust and Cancer Research UK. The MHRA's reliance on FDA determinations for personalized medicine approvals accelerates entry timelines for US-validated platforms. The Cambridge-London corridor concentrates early-phase trial infrastructure for autologous T-cell products.
China
NMPA regulatory reforms for cell and gene therapy manufacturing controls are attracting sponsor investment in Shanghai and Suzhou GMP facilities. Domestic biotech firms partner with US algorithm developers to access prediction platforms while building local sequencing capacity. The Yangtze River Delta cluster is consolidating outpatient administration infrastructure for mRNA vaccine candidates.
Neoantigen Targeted Therapies Market Competitive Environment
Capability concentration sits with bioinformatics specialists; scale advantage sits with mRNA manufacturing incumbents. The market structures around three tiers: integrated platform owners with end-to-end sequencing-to-dose workflows, algorithm licensors with proprietary training datasets, and contract manufacturers with scarce cleanroom slots. Dominant competitive moves include strategic partnerships for manufacturing slot guarantees and technology licensing for prediction algorithm access.
Within the integrated platform tier, BioNTech SE and Moderna, Inc. occupy positions that exemplify manufacturing scale married to RNA sequencing capabilities. Gritstone bio represents the algorithm-centric archetype, anchoring competitive positioning around artificial intelligence-driven epitope prediction. These three firms illustrate how divergent capability foundations—mRNA infrastructure versus computational immunology—produce distinct pathways to market presence.
| Leading Market Players |
|---|
| BioNTech SE |
| Moderna, Inc. |
| Gritstone bio |
| Achilles Therapeutics plc |
| Advaxis, Inc. |
| Genocea Biosciences Inc. |
| Medigene AG |
| Agenus Inc. |
| Immatics NV |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on lipid nanoparticle formulation capacity in the United States and Germany compresses pricing spreads between autologous cell therapies and outpatient vaccines while forcing sponsors into long-term manufacturing slot commitments. FDA cold chain requirements and EMA adaptive pathway compliance costs cascade through both pricing tiers, concentrating procurement authority at NCI-designated centers with integrated GMP facilities.
Pricing Analysis
Long-term offtake agreements for manufacturing slots dominate the contract landscape, with academic medical centers in Boston and Houston commanding premium rates for autologous cell therapies due to cleanroom scarcity. Price differentiation separates patient-specific cell platforms from synthetic peptide vaccines, with the latter facing compression from mRNA manufacturing scale-up at BioNTech and Moderna facilities. Margins are tightening in the cell therapy segment because vector production bottlenecks limit slot availability. Community oncology practices exhibit the highest price sensitivity due to cold chain infrastructure gaps, while NCI-designated comprehensive cancer centers absorb premium pricing through trial sponsorship offsets.
Supply Chain Analysis
Export control regimes on CRISPR reagents and synthetic biology tools limit flows from the United States to Chinese GMP facilities, fragmenting global production networks. Supply concentrates in the United States, Germany, and Switzerland, with the Rhine-Main and Boston corridors anchoring lipid nanoparticle formulation and computational immunology talent. Raw material dependencies on plasmid DNA, modified nucleosides, and HLA-typed reference strains create vulnerability to single-source suppliers. Tariff exposure on sequencing instrumentation imported from China into United States academic medical centers threatens cost structures. Distribution runs through NCI trial network sites with validated cold chain protocols, excluding community oncology practices from direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating toward NCI-designated comprehensive cancer centers with embedded GMP facilities and trial infrastructure, fragmenting access for community oncology networks and forcing sponsors into exclusive slot commitments.
For Market Incumbents: Harden manufacturing slot guarantees through exclusive partnerships with Mayo Clinic, MD Anderson, and Memorial Sloan Kettering to lock out emerging platform competitors. Deepen backward integration into plasmid DNA production to reduce vector supply vulnerability from single-source contract manufacturers. The priority defensive lever rests on controlling scarce cleanroom capacity in Boston and Houston against new entrant encroachment. For New Entrants and Emerging Players: Geographic underpenetration in China's Yangtze River Delta offers the most penetrable white-space target, where NMPA regulatory reforms and domestic GMP buildout outpace algorithm licensing penetration. Second-tier autoimmune disorder applications at University of Pennsylvania and Stanford University present lower competitive density than oncology. A go-to-market angle anchored on allogeneic off-the-shelf platforms bypasses autologous manufacturing constraints that entrench incumbents. For Investors and Strategic Acquirers: The market sits at a manufacturing-scale phase that favors integrated platform owners with end-to-end sequencing-to-dose workflows over pure-play algorithm licensors. Long-term viability over the next decade hinges on proprietary bioinformatics training datasets encompassing diverse ethnic HLA repertoires. Acquisition targets should display integrated RNA sequencing and lipid nanoparticle formulation capabilities. The signal to watch is FDA guidance finalization on personalized medicine manufacturing controls, which will determine which platforms achieve scalable commercial validation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | NCI trial network enrollment compresses biomarker validation timelines at designated centers. |
| Manufacturing Scale-Up | Lipid nanoparticle capacity expansion at academic medical centers reduces per-dose production costs. |
| Licensing Agreement | Proprietary algorithm access from Basel-based computational groups accelerates design-to-dose workflows. |
| Regulatory Approval Pathway | FDA breakthrough designation and EMA adaptive pathways synchronize US-EU launch timelines. |
| Pipeline Diversification | Autoimmune disorder expansion at Penn and Stanford reduces oncology concentration risk. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions underlying this analysis. Primary interviews with formulary directors at NCI-designated centers and GMP facility operators in Boston and Houston were cross-validated against secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient recruitment flow analysis and top-down platform revenue triangulation anchored the market sizing framework.
Demand-supply balance across the projection horizon was modeled through segmentation by product type, therapy area, technology platform, and end-user institution tier. The analytical framework incorporated treatment line positioning, administration route, and regional regulatory cluster as cross-cutting dimensions. CAGRs were derived from enrollment velocity in active trials and manufacturing slot utilization rates at academic medical centers. Forecast inputs included biomarker validation maturity and adaptive pathway approval timelines.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing slot acquisition by emerging biotech platforms or accelerated FDA guidance finalization would shift outcomes. Material shifts in NCI funding priorities, EMA adaptive pathway scope, or CRISPR export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market