
 Rare Disease Gene Therapy Market | 2026-2036
Rare Disease Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
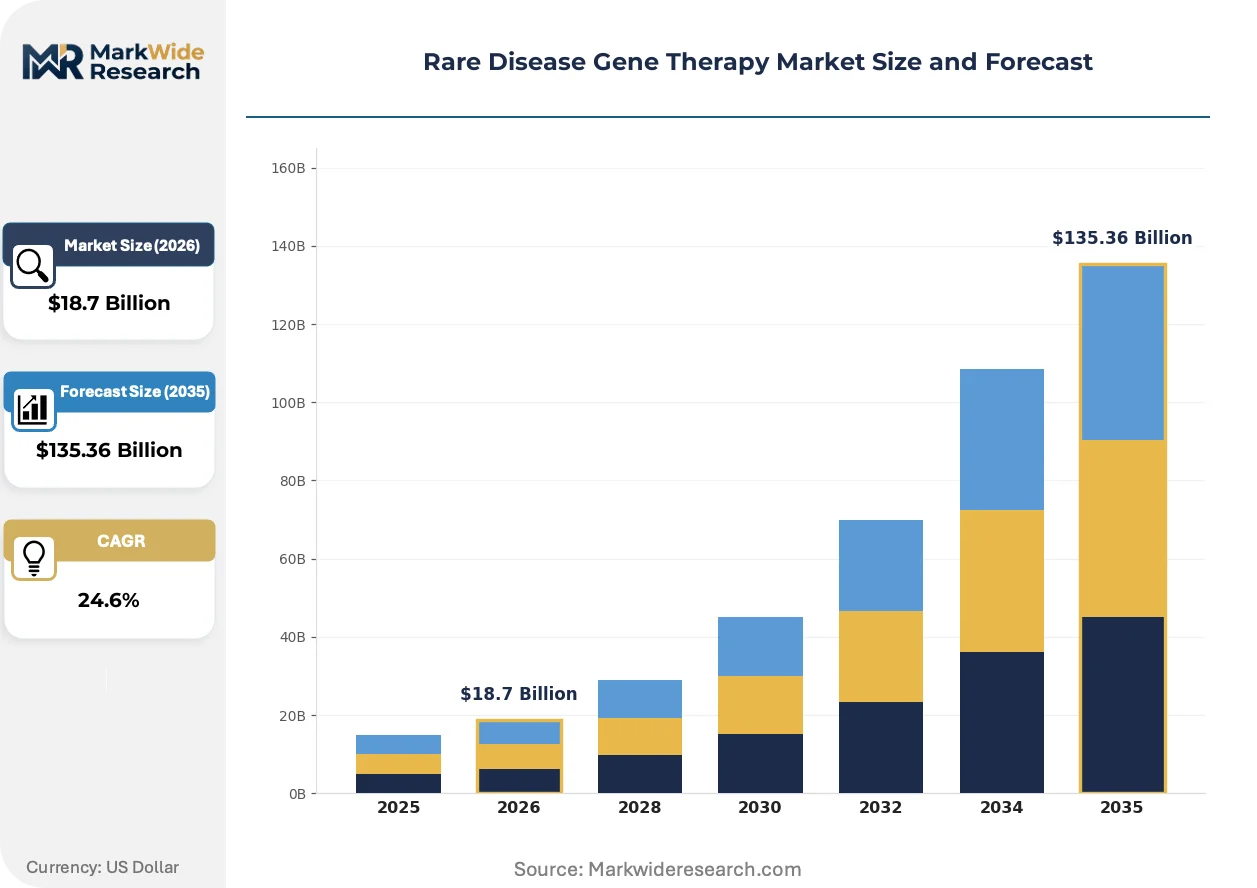
Rare Disease Gene Therapy Market Outlook
Single-source viral vector supply is decoupling from sponsor control as CDMO networks mature. Novartis leverages captive manufacturing capacity for its lentiviral platform. BioMarin anchors hemophilia A gene therapy production through European facilities. Sarepta Therapeutics competes in Duchenne muscular dystrophy via differentiated exon-skipping combinations with AAV delivery.
Rare disease gene therapy encompasses therapeutic interventions that introduce, remove, or alter genetic material within a patient's cells to treat monogenic disorders with prevalence below specific population thresholds, typically utilizing recombinant adeno-associated virus or lentiviral vectors manufactured through triple-transfection or baculovirus systems in suspension HEK293 cultures. Its primary purpose is to correct disease-causing mutations at their source rather than managing symptoms chronically. AAV-based platforms dominate current commercialization due to established safety profiles in non-dividing tissues, though CRISPR-edited therapies represent the fastest-expanding pipeline segment as manufacturing yields improve. Intravenous delivery commands the largest installed treatment base, while intraocular administration captures premium pricing in inherited retinal disorders where surgical precision limits addressable volumes.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for orphan indications, while WHO gene editing governance frameworks are shaping clinical trial standards across jurisdictions. The EU AI Act and MDR convergence will force adaptive compliance investments for automated vector quality analytics. Stakeholders must monitor payer willingness to finance single-administration curative therapies against annualized chronic treatment benchmarks.
Market Dynamics
Single-source viral vector manufacturing is concentrating competitive advantage among sponsors with captive HEK293 suspension capacity, while CDMO network maturation is decoupling supply security from proprietary infrastructure investments.
Growth Catalysts
- EMA PRIME Eligibility:The European Medicines Agency's priority medicines scheme compresses regulatory review timelines for gene therapies targeting unmet rare disease needs, accelerating European patient access.
- Intravenous Delivery Infrastructure:Pediatric hospital networks across the United States are building dedicated gene therapy infusion centers with cryogenic storage and on-site vector thawing capabilities.
- CRISPR Manufacturing Yields:Improved baculovirus system titers in suspension cultures are reducing cost-per-dose for gene-edited therapies, expanding addressable patient populations.
Market Restraints
- Plasmid DNA Supply Volatility:GMP-grade plasmid production concentrates among three North American contract manufacturers, creating input bottlenecks during clinical trial ramp phases.
- Pre-existing AAV Immunity:Population seroprevalence rates against common adeno-associated virus capsids exclude substantial patient subsets from vector-based interventions.
- IRA Price Negotiation Exposure:The United States Inflation Reduction Act's small-molecule carve-out timeline creates reimbursement uncertainty for oral gene therapy adjuncts.
Strategic Opportunities
- Intraocular Administration:Surgical precision in inherited retinal disorder treatment commands premium pricing with limited competition from systemic delivery platforms.
- WHO Gene Editing Governance:Emerging international clinical trial standards are creating first-mover advantages for sponsors with established safety databases.
- EU AI Act Convergence:Automated vector quality analytics systems will face harmonized compliance requirements, favoring early adopters of machine-learning release assays.
Industry Challenges
- Cell Culture Specialist Scarcity:Suspension HEK293 platform expertise concentrates among legacy biologics manufacturers, constraining workforce mobility for gene therapy scale-up.
- MDR Certification Timelines:European Medical Device Regulation conformity assessment for combination products extends commercialization schedules by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Disease Gene Therapy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AAV, Lentivirus, RNAi, CRISPR Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intraocular End User: Hospitals, Research Institutes, Contract Research Organizations, Specialty Clinics Indication: Cystic Fibrosis, Duchenne Muscular Dystrophy, Hemophilia, Spinal Muscular Atrophy |
| Companies Covered | Novartis, BioMarin, bluebird bio, Sarepta Therapeutics, uniQure, REGENXBIO, Rocket Pharma, Orchard Therapeutics, Ultragenyx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Disease Gene Therapy Market Strategic Shifts
Process analytical technology is displacing offline quality testing in viral vector manufacturing, compressing batch release cycles while tightening critical quality attribute control. These shifts are reconfiguring where value accrues across the supply chain.
Continuous bioprocessing is automating upstream vector production through perfusion-based HEK293 culture systems. Contract manufacturers in Switzerland and Singapore are adopting these platforms to reduce facility footprint requirements. The technology is automating real-time titer monitoring, enabling dynamic harvest decisions that maximize full-to-empty capsid ratios.
The EU AI Act and MDR convergence is forcing adaptive compliance investments for automated vector quality analytics. European sponsors must validate machine-learning models used in release testing under both medical device and pharmaceutical frameworks. This dual classification most affects lentiviral platform developers with integrated manufacturing software systems.
Payer preference for single-administration curative therapies is displacing annualized chronic treatment benchmarks in United States reimbursement negotiations. Integrated delivery networks are consolidating gene therapy procurement under pharmacy benefit managers with specialized rare disease units. This concentration is most visible in hemophilia A and Duchenne muscular dystrophy categories where prior authorization requirements are tightening.
Rare Disease Gene Therapy Market Segmentation
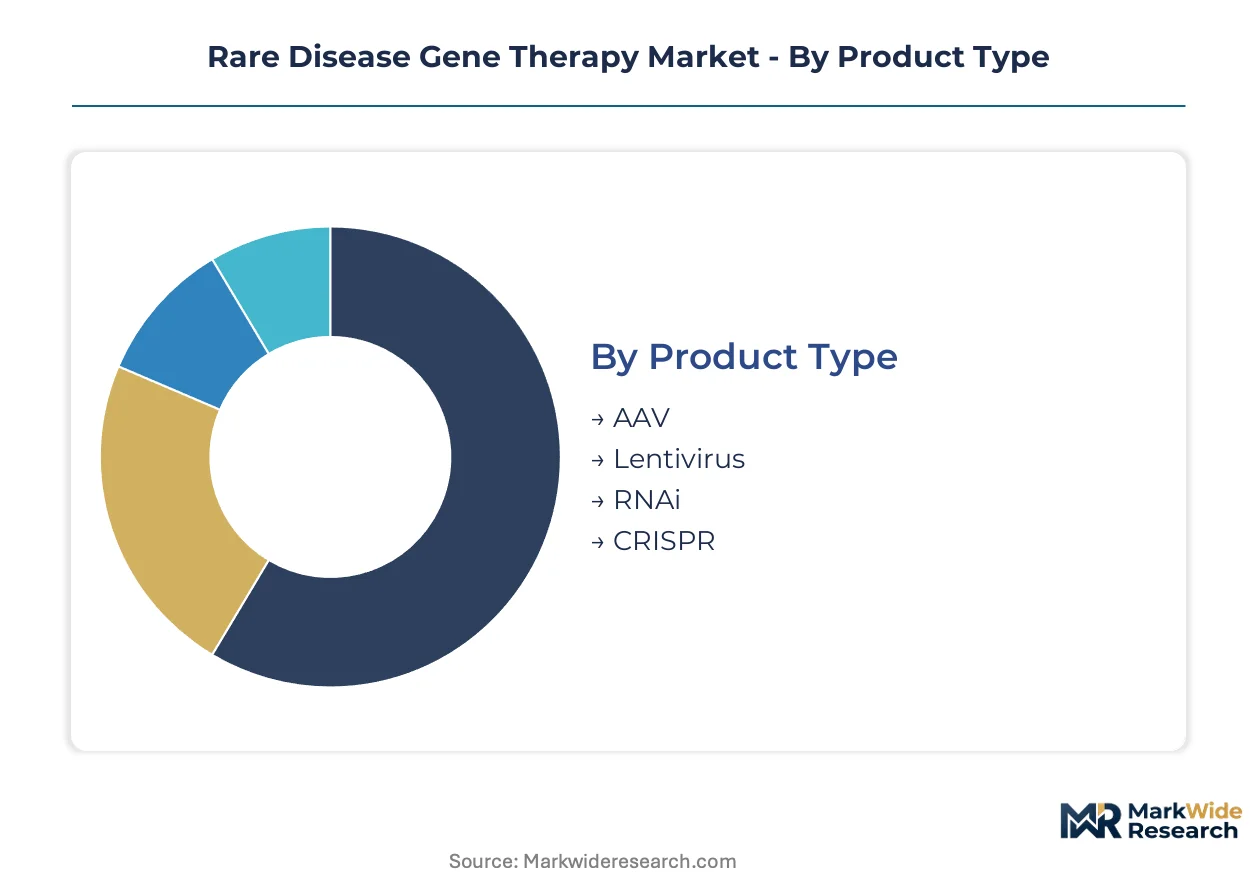
Gene therapy segmentation tracks how vector engineering, anatomical targeting, and care setting economics reshape competitive positioning. Vector platform selection determines manufacturing complexity and regulatory pathway, while delivery mode dictates reimbursement structure and addressable patient pools.
Product Type:
Platform upgrades follow a predictable replacement cycle: sponsors migrate from first-generation viral systems toward precision editing tools as manufacturing yields improve and regulatory precedents accumulate.
- AAV:Recombinant adeno-associated virus vectors dominate commercialized therapies due to established safety profiles in non-dividing tissues. Demand concentrates in the United States at pediatric hospital networks with cryogenic storage infrastructure, driven by compressed FDA breakthrough therapy timelines.
- CRISPR:Gene-editing platforms utilizing guide RNA-directed nucleases represent the pipeline's steepest expansion trajectory as baculovirus system titers in suspension cultures reduce cost-per-dose. Manufacturing investments cluster in Switzerland and Singapore where automated quality analytics face harmonized EU AI Act and MDR compliance requirements.
- Lentivirus:Integrating vectors enable stable transgene expression in dividing hematopoietic cells.
- RNAi:Small interfering RNA therapeutics target post-transcriptional gene silencing in liver-localized rare diseases.
AAV sits at the top of the volume ranking, with CRISPR climbing the fastest.
Delivery Mode:
Cost tier separation between delivery modes is pronounced: surgical precision commands premium pricing while systemic administration maximizes patient throughput.
- Intravenous:Systemic infusion enables broad tissue biodistribution for hematologic and metabolic disorders. Pediatric hospital networks across the United States are building dedicated infusion centers with on-site vector thawing capabilities, compressing treatment logistics.
- Intraocular:Subretinal and intravitreal injection platforms command premium pricing in inherited retinal disorders where surgical precision limits addressable volumes. European EMA PRIME eligibility accelerates patient access for ocular gene therapies.
- Subcutaneous:Dermal depot administration reduces infusion infrastructure requirements for select indications.
- Intramuscular:Direct vector delivery to skeletal muscle targets Duchenne muscular dystrophy and related myopathies.
Intravenous infusion retains the largest installed treatment base, with intraocular administration capturing the highest per-dose reimbursement.
End User:
Customer type fragmentation reflects divergent procurement authority: integrated delivery networks consolidate purchasing under pharmacy benefit managers while research institutes retain protocol development autonomy.
- Hospitals:Academic medical centers with integrated manufacturing capabilities anchor gene therapy adoption in the United States. These institutions negotiate directly with sponsors for vector supply security, bypassing traditional wholesale distribution.
- Specialty Clinics:Focused rare disease centers concentrate patient access for single-administration curative therapies. Prior authorization requirements are tightening in hemophilia A and Duchenne muscular dystrophy categories.
- Research Institutes:University-affiliated centers drive early-phase clinical trial enrollment.
- Contract Research Organizations:CDMO network maturation is decoupling supply security from proprietary infrastructure investments.
Hospitals dominate current procurement volume, with specialty clinics expanding capacity fastest.
Indication:
Application maturity varies sharply: hemophilia and spinal muscular atrophy have crossed regulatory approval thresholds while muscular dystrophy remains in label expansion phases.
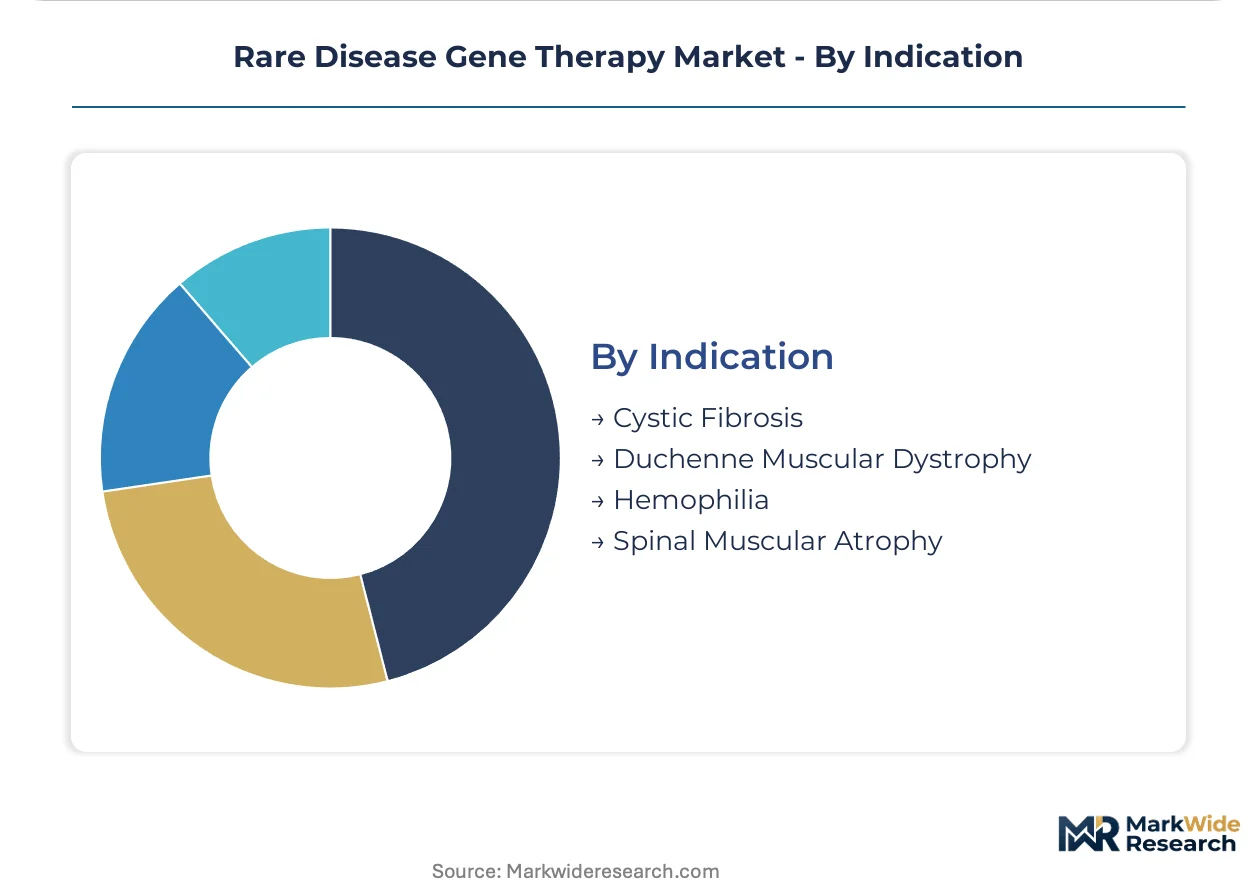
- Hemophilia:Factor VIII and IX deficiency programs have established durable expression benchmarks. European production facilities anchor supply for this indication category.
- Spinal Muscular Atrophy:Intravenous and intrathecal delivery platforms have transformed patient survival curves. United States demand concentrates at clustered academic medical centers.
- Duchenne Muscular Dystrophy:Exon-skipping combinations with AAV delivery face competitive differentiation pressures.
- Cystic Fibrosis:Pulmonary delivery challenges have delayed vector-based approaches relative to other indications.
Hemophilia sits at the top of the volume ranking, with Duchenne muscular dystrophy climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vector manufacturing location decisions, with sponsors migrating production toward jurisdictions offering streamlined clinical trial frameworks and harmonized quality standards. Cost-of-compliance gaps between the FDA's breakthrough therapy pathway and EMA's PRIME scheme are accelerating facility investments in specific European markets.
United States
Academic medical centers in Boston, Philadelphia, and the Research Triangle anchor domestic gene therapy demand through integrated manufacturing capabilities. FDA breakthrough therapy designation compresses development timelines for orphan indications, attracting sponsor investment toward clustered pediatric hospital networks. The Philadelphia-Camden corridor concentrates lentiviral production capacity for hematologic applications.
Switzerland
Contract manufacturers in Basel and Zurich are adopting continuous bioprocessing platforms to reduce facility footprints for AAV production. Swissmedic alignment with EU AI Act and MDR convergence creates compliance predictability for automated vector quality analytics. The Basel biotech cluster hosts specialized suspension HEK293 expertise that constrains workforce mobility elsewhere.
Germany
EMA PRIME eligibility accelerates patient access timelines, drawing vector manufacturing investment toward Frankfurt and Munich hubs. The country's central European location reduces logistics costs for multi-national clinical trial supply. Bavarian production facilities anchor hemophilia A gene therapy supply chains for European distribution.
Singapore
CDMO network maturation is decoupling viral vector supply security from sponsor proprietary infrastructure in Asia-Pacific markets. Automated perfusion-based culture systems reduce cost-per-dose for CRISPR-edited therapies targeting regional patient populations. The Biopolis research cluster concentrates process analytical technology expertise for real-time titer monitoring.
United Kingdom
London and Oxford academic centers retain early-phase clinical trial enrollment autonomy despite post-Brexit regulatory divergence from EMA frameworks. MHRA innovative licensing pathways compete with FDA timelines for rare disease sponsor attention. The Oxford-Cambridge arc concentrates exon-skipping combination research for muscular dystrophy applications.
Rare Disease Gene Therapy Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue CRISPR-edited precision platforms and automated manufacturing software integration. The market structures around three maturity tiers: integrated pharmaceutical sponsors with captive vector capacity, specialized gene therapy developers with CDMO partnerships, and platform-technology licensors supplying viral vector components. Competitive moves concentrate on backward integration into plasmid DNA supply and strategic alliances for intraocular delivery surgical networks.
Within the integrated sponsor tier, Novartis and BioMarin exemplify archetypes of captive manufacturing investment versus European-anchored production strategies. Sarepta Therapeutics occupies a differentiated position combining exon-skipping technology with AAV delivery platforms. These three entities represent contrasting approaches to vector supply security: wholly owned suspension culture facilities, contracted European manufacturing networks, and technology-licensing arrangements for specialized indications.
| Leading Market Players |
|---|
| Novartis |
| BioMarin |
| bluebird bio |
| Sarepta Therapeutics |
| uniQure |
| REGENXBIO |
| Rocket Pharma |
| Orchard Therapeutics |
| Ultragenyx |
| Others |
Value Chain & Pricing Dynamics
Curative therapy premium capture versus chronic treatment displacement creates a bifurcation that separates single-administration gene therapies from annualized biologic regimens, with that divergence manifesting in both reimbursement negotiations and vector manufacturing investment decisions across United States integrated delivery networks and European hospital systems.
Pricing Analysis
Distributor margin compression in gene therapy channels runs through pharmacy benefit manager consolidation under specialized rare disease units. Three-tier pricing structure across premium, standard, and economy levels separates intraocular surgical delivery from intravenous infusion from subcutaneous depot administration. Pricing pressure stems from IRA small-molecule carve-out timeline uncertainty affecting oral gene therapy adjuncts. Academic medical centers with captive manufacturing capabilities exhibit lowest price sensitivity; specialty clinics face tightening prior authorization requirements.
Supply Chain Analysis
Domestic-content mandates in United States biosecurity frameworks are reshaping plasmid DNA sourcing away from concentrated North American contract manufacturers toward diversified supplier networks. GMP-grade plasmid production concentrates in the United States, Switzerland, and Germany. Suspension HEK293 culture media and baculovirus system components draw from specialized chemical suppliers in Singapore and Basel. Single-source vulnerability in viral vector supply creates exposure during clinical trial ramp phases. Distribution runs through direct sponsor-to-hospital negotiations bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare disease gene therapy functions as a stable compounder anchored by irreversible regulatory precedent accumulation at FDA and EMA that locks in accelerated approval pathways for orphan indications.
For Market Incumbents: Extend captive manufacturing capacity into automated perfusion-based culture systems to defend against CDMO network maturation eroding proprietary infrastructure advantages. Secure backward integration into plasmid DNA supply chains to neutralize input bottlenecks during clinical trial expansion phases. Strengthen EMA PRIME eligibility positioning to compress European commercialization timelines against emerging CRISPR-edited therapy competition. For New Entrants and Emerging Players: Begin with intraocular administration platforms in inherited retinal disorders where surgical precision limits addressable volumes and incumbent presence remains sparse. Target Switzerland and Singapore manufacturing jurisdictions where EU AI Act and MDR convergence creates compliance predictability for automated vector quality analytics. Pursue licensing arrangements with established academic medical centers for cryogenic storage infrastructure access. For Investors and Strategic Acquirers: Consolidation pressure builds where CDMO network maturation decouples supply security from proprietary infrastructure investments, favoring platform-technology licensors over asset-heavy manufacturers. Five-to-ten year viability hinges on CRISPR manufacturing yield improvement trajectories and payer willingness to finance curative therapies. Watch FDA breakthrough therapy designation velocity as inflection indicator for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses orphan indication timelines for sponsors with established safety databases. |
| Manufacturing Scale-Up | Continuous bioprocessing adoption in Switzerland reduces facility footprint requirements for AAV production platforms. |
| Backward Integration | Captive plasmid DNA supply neutralizes input bottlenecks from concentrated North American contract manufacturers. |
| Reimbursement Strategy | Payer preference for single-administration curative therapies displaces annualized chronic treatment benchmarks in United States negotiations. |
| Pipeline Diversification | CRISPR-edited platforms represent fastest-expanding pipeline segment as baculovirus system titers improve in suspension cultures. |
Study Parameters
Direct dialogue with gene therapy development executives, regulatory affairs leads at sponsors and CDMOs, hospital procurement managers at academic medical centers, and payer access specialists anchors the qualitative foundation. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling triangulates against top-down market sizing across vector platform, delivery mode, and indication segments.
Projected value outputs synthesize epidemiological prevalence data, treatment penetration assumptions, and pricing benchmarks across the analysis window. Segmentation dimensions include vector platform type, anatomical delivery mode, end-user procurement authority, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical approval timelines and manufacturing capacity expansion trajectories. Forecast inputs incorporate CRISPR manufacturing yield improvement rates and payer contract structuring evolution.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals at FDA or EMA, disruptive non-viral delivery technology emergence, and sovereign pricing controls in major European markets. Forecasts reflect documented assumptions about vector immunogenicity profiles and plasmid supply stability. A small set of named triggers warrants ongoing watch: IRA implementation scope expansion, WHO gene editing governance framework adoption velocity, and suspension HEK293 specialist workforce mobility constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market