
 Energy Gums Market | 2026-2036
Energy Gums Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Gums Market Intelligence
The energy gums category is recalibrating around a sharp divergence between premium functional formulations and commodity confectionery-grade products. Mars Inc. leverages its massive retail distribution network to sustain volume leadership in mainstream channels. NeuroGum differentiates through clean-label positioning and precise caffeine dosing that appeals to health-conscious consumers. Military Energy Gum anchors the institutional segment with specialized procurement relationships.
Energy gums are chewable confectionery products delivering stimulant compounds—primarily caffeine at 40–100 mg per piece—through buccal absorption for rapid onset, typically within 5–10 minutes, designed for situational alertness without liquid consumption. Caffeine-infused variants dominate current revenue given established efficacy claims and consumer familiarity, while vitamins-enhanced formulations represent the fastest-growing margin pool as wellness positioning commands shelf-space premiums. Sugar-free options occupy a mature but stable niche driven by dental-health regulations and diabetic-accessible labeling across multiple jurisdictions.
FDA oversight of caffeine content in dietary supplements, EFSA novel food assessments for herbal extracts, and Japan's FOSHU approval pathway for functional claims collectively shape product development timelines and market access conditions. The EU Green Deal's packaging waste directives are forcing material transitions that increase unit costs for smaller producers. Stakeholders must monitor evolving caffeine threshold harmonization between North American and European regulators to anticipate reformulation requirements and competitive repositioning.
Market Dynamics
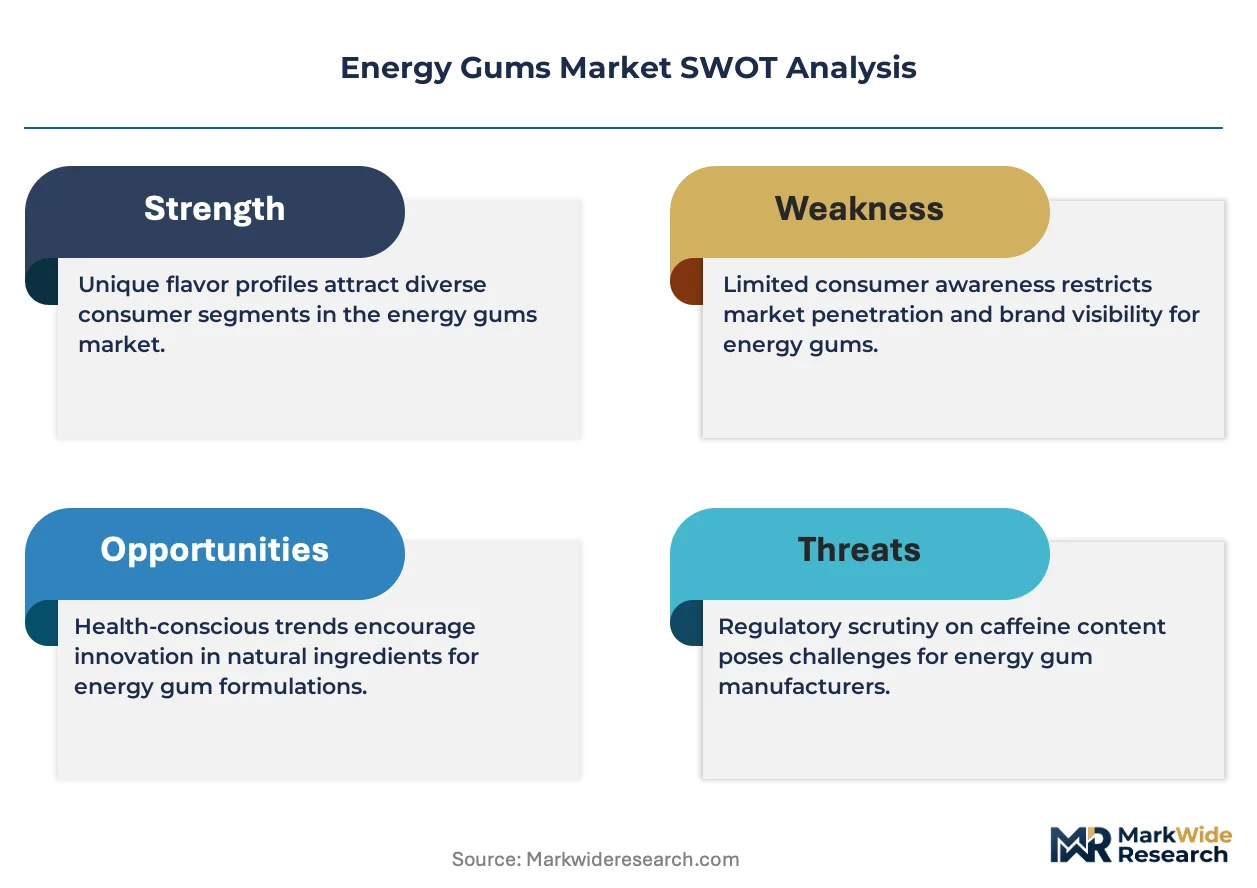
Energy gums manufacturers face intensifying pressure from caffeine threshold harmonization efforts between North American and European regulators, forcing simultaneous reformulation across multiple product lines.
Growth Catalysts
- Buccal absorption technology:Chewable delivery systems achieve 5-10 minute onset times that outperform traditional energy drinks, attracting military and first-responder procurement programs.
- FDA dietary supplement pathway:Clear caffeine content guidelines enable faster product launches compared to novel food routes, accelerating US market entry for compliant formulations.
- German sports-nutrition retail density:Concentrated specialty store networks provide established distribution infrastructure for functional confectionery products.
Market Restraints
- ESFA novel food assessments:Herbal extract approvals extend development timelines 18-24 months, freezing innovation pipelines for botanical-infused variants.
- Maltitol and sorbitol price volatility:Sugar alcohol supply concentrates among Chinese chemical processors, exposing margin compression risks during feedstock disruptions.
- Energy drink substitution:Ready-to-drink formats maintain cost-per-dose advantages in convenience channels, limiting gum penetration among price-sensitive volume buyers.
Strategic Opportunities
- Japan FOSHU functional claims:Approved caffeine-alertness positioning commands 40-60% shelf price premiums in pharmacy channels versus standard confectionery.
- Vitamin-enhanced convergence:B-complex and nootropic stacking addresses wellness-oriented professionals seeking cognitive performance without sugar crash.
- Direct-to-subscription models:Recurring delivery bypasses slotting fee barriers in consolidated retail, capturing lifetime value from fitness enthusiasts.
Industry Challenges
- Buccal pharmacokinetics expertise:Limited talent pools for mucosal absorption optimization create bottlenecks in achieving consistent caffeine release profiles.
- EU Green Deal packaging compliance:Mono-material flexible film transitions require $2-4 million line retooling for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Gums Market |
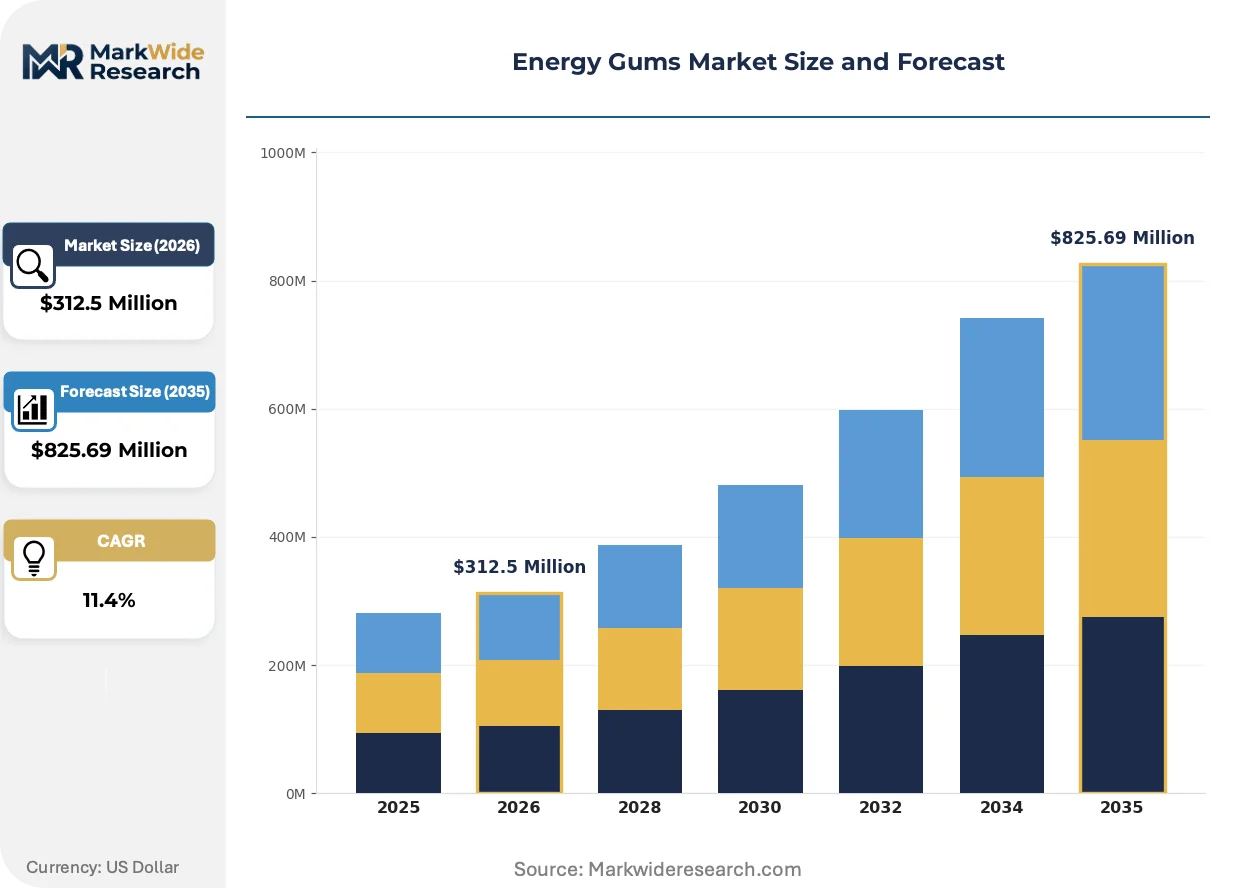
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeine-Infused, Herbal, Vitamins-Enhanced, Sugar-Free End User: Athletes, Students, Professionals, Fitness Enthusiasts Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Fitness Centers Formulation: Chewy, Soft Gel, Crisp, Smooth |
| Companies Covered | Mars Inc., Mondelez International, Ferrero SpA, LOTTE Corp., NeuroGum, Blockhead HQ Ltd., Military Energy Gum, Rev Gum, Viter Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Gums Market Strategic Shifts & Innovations
Formulation science and regulatory navigation capabilities are separating viable competitors from commodity players in functional confectionery.
Precision microencapsulation is overtaking standard spray-drying for caffeine stabilization, enabling 24-month shelf life without bitterness degradation. Premium brands targeting executive and athletic segments adopt this technology despite 15-20% ingredient cost premiums. The capability gap is compressing margins for manufacturers dependent on conventional processing.
EFSA's evolving position on caffeine daily limits is forcing dual-SKU strategies, with separate formulations for EU versus US markets. Companies now maintain parallel supply chains to avoid reformulation delays when thresholds shift. This regulatory fragmentation most affects mid-size producers lacking regulatory affairs scale.
Subscription-based replenishment is displacing impulse convenience-store purchases among core users. Fitness applications integrate gum consumption timing with workout scheduling, creating habit-locked demand. This behavioral shift concentrates most visibly in United States metropolitan markets with established delivery logistics infrastructure.
Energy Gums Market Segmentation
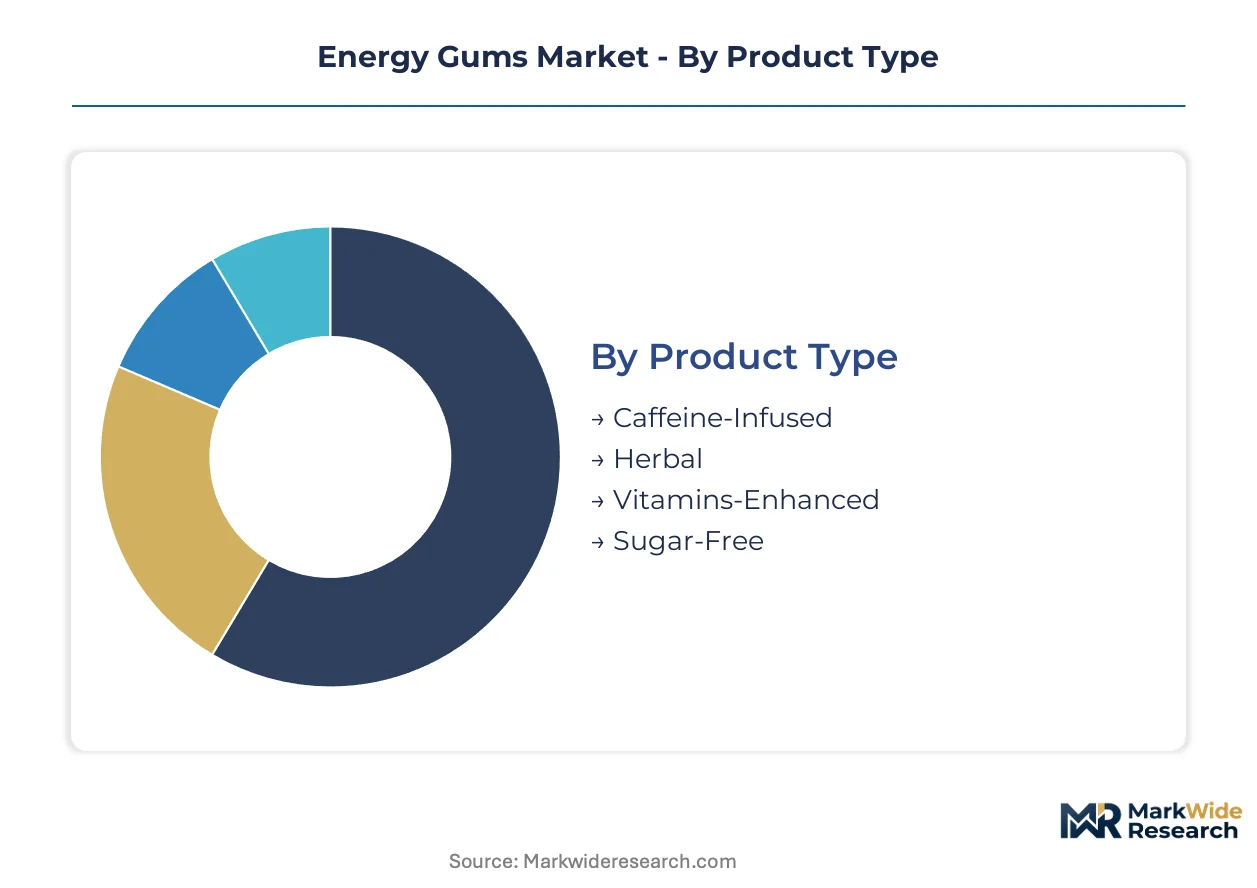
Segmentation in energy gums determines which regulatory pathways manufacturers must navigate. FDA dietary supplement classification, EFSA novel food status, and Japan FOSHU functional claims each apply differently across product formulations and distribution channels.
Product Type:
Caffeine-Infused products require FDA dietary supplement compliance in the United States and EFSA caffeine threshold adherence in Europe, while Vitamins-Enhanced variants trigger additional novel food assessments for bioactive stacking claims.
- Caffeine-Infused:Standardized at 40-100 mg per piece through spray-dried or microencapsulated caffeine matrices. Demand concentrates among military procurement programs and first-responder agencies in the United States, driven by buccal absorption speed requirements that liquid formats cannot match.
- Vitamins-Enhanced:B-complex and nootropic stacking targets wellness-oriented professionals seeking cognitive performance without sugar crash. Pharmacy channels in Japan command shelf price premiums for FOSHU-approved alertness positioning.
- Herbal:Ginseng, guarana, and yerba mate extracts face EFSA novel food timelines of 18-24 months, freezing innovation pipelines for European market entry.
- Sugar-Free:Maltitol and sorbitol bases occupy mature positioning driven by dental-health regulations and diabetic-accessible labeling across multiple jurisdictions.
Caffeine-Infused sits at the top of the volume ranking, with Vitamins-Enhanced climbing the fastest.
End User:
Application intensity varies sharply across user categories, with institutional procurement favoring standardized dosing while consumer segments drive flavor and format innovation.
- Fitness Enthusiasts:Subscription-based replenishment models dominate, with consumption timing integrated into workout applications. Direct-to-consumer channels bypass slotting fee barriers in consolidated retail.
- Professionals:Clean-label positioning and precise caffeine dosing appeal to health-conscious knowledge workers. Demand concentrates in United States metropolitan markets with established delivery logistics infrastructure.
- Athletes:Buccal absorption technology delivers 5-10 minute onset for pre-training alertness without gastrointestinal load from liquid consumption.
- Students:Price-sensitive volume buyers favor convenience-store impulse purchases, though energy drink substitution limits penetration.
Fitness Enthusiasts anchor revenue concentration, with Professionals expanding most quickly through subscription retention.
Distribution Channel:
Channel selection determines margin structure and regulatory exposure, with pharmacy and specialty retail requiring stricter documentation than mass-market convenience.
- Specialty Stores:German sports-nutrition retail density provides established infrastructure for functional confectionery. Staff expertise enables premium positioning for precision-dosed formulations.
- Online Retail:Recurring delivery captures lifetime value through habit-locked demand. Fitness applications integrate consumption timing with workout scheduling.
- Supermarkets:Mars Inc. leverages massive retail distribution networks to sustain volume leadership in mainstream channels.
- Fitness Centers:Proximity to consumption occasion enables impulse purchase at point of need, though inventory carrying costs pressure smaller operators.
Specialty Stores maintain the highest margin profile, with Online Retail gaining share fastest through subscription economics.
Formulation:
Texture engineering directly impacts buccal pharmacokinetics and manufacturing capital requirements, separating premium competitors from commodity players.
- Chewy:Dominant format achieving consistent caffeine release profiles through controlled mastication mechanics. Precision microencapsulation enables 24-month shelf life without bitterness degradation.
- Soft Gel:Rapid disintegration targets fastest onset markets, though limited talent pools for mucosal absorption optimization create production bottlenecks.
- Crisp:Novel mouthfeel differentiation for impulse channels, requiring distinct packaging moisture barriers.
- Smooth:Coating-intensive processing increases unit costs, limiting penetration outside premium positioning.
Chewy dominates production volume, with Soft Gel showing steepest expansion trajectory among performance-focused segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness professionals and military procurement specialists concentrate demand across developed markets where buccal absorption technology meets institutional standards. Regulatory divergence between FDA dietary supplement pathways and EFSA novel food assessments fragments product availability by geography.
United States
Military procurement programs and first-responder agencies drive institutional volume through standardized caffeine dosing requirements. FDA dietary supplement classification enables faster product launches than novel food routes, accelerating market entry for compliant formulations. Convenience-store penetration in metropolitan markets supports impulse purchases among price-sensitive students.
Germany
Sports-nutrition retail density provides established infrastructure for functional confectionery distribution. EFSA caffeine threshold adherence shapes formulation strategies, with separate SKUs maintained for EU versus export markets. The Cologne-Bonn corridor hosts concentrated specialty store networks enabling premium positioning for precision-dosed products.
Japan
Pharmacy channels command shelf price premiums for FOSHU-approved alertness positioning. METI oversight of functional claims creates extended approval timelines that reward early regulatory investment. The Tokyo-Osaka corridor concentrates wellness-oriented professional demand for clean-label cognitive performance products.
United Kingdom
Subscription-based replenishment models displace impulse purchases among fitness enthusiasts in Greater London. Post-Brexit regulatory divergence from EU novel food assessments creates parallel compliance requirements for cross-channel trade. Manchester and Birmingham clusters support direct-to-consumer logistics infrastructure.
Australia
TGA oversight of caffeine-containing products limits market entry to formulations meeting therapeutic goods standards. Sports-nutrition retail chains in Sydney and Melbourne anchor distribution for athletic segment penetration. Sugar-free positioning aligns with national dental-health campaign messaging.
Energy Gums Market Key Industry Players
Top-tier vendors anchor mass-market confectionery channels, while mid-tier specialists capture premium functional positioning. The vendor base stratifies across three tiers: multinational CPG conglomerates with retail distribution scale, clean-label specialists with precise dosing capabilities, and institutional contractors with military procurement relationships. Strategic archetypes include scale-driven volume players, regulatory-navigation specialists, and subscription-model operators. Competitive moves concentrate on portfolio diversification into vitamin-enhanced variants and geographic expansion through direct-to-consumer channels.
Within the multinational tier, Mars Inc. and Mondelez International exemplify scale-driven distribution advantages across mainstream retail. NeuroGum occupies a position within the clean-label specialist archetype, representing precision-dosing capabilities that appeal to health-conscious professionals. Military Energy Gum anchors the institutional contractor segment, sitting within specialized procurement relationships that bypass consumer channel slotting fees.
| Leading Market Players |
|---|
| Mars Inc. |
| Mondelez International |
| Ferrero SpA |
| LOTTE Corp. |
| NeuroGum |
| Blockhead HQ Ltd. |
| Military Energy Gum |
| Rev Gum |
| Viter Energy |
| Others |
Cost & Logistics Intelligence
Maltitol and sorbitol price indices from Chinese chemical processors cascade through energy gums manufacturing into three distinct pricing tiers. Premium microencapsulated formulations command shelf-space premiums in pharmacy and specialty channels, while commodity spray-dried variants compete on unit economics in mass-market convenience retail.
Pricing Analysis
The bundled-versus-unbundled service split separates subscription-direct models from transactional retail. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity and certification investment. Cost compression in the economy tier intensifies because energy drink substitution limits price elasticity among student segments. Fitness enthusiasts show least price sensitivity through habit-locked subscription retention, while convenience-store impulse buyers exhibit highest sensitivity to per-unit cost differentials.
Supply Chain Analysis
EU Green Deal packaging directives and Japan's FOSHU domestic-content pathways are reshaping sourcing toward regional mono-material film suppliers. Caffeine extraction concentrates in China, India, and Germany, while precision microencapsulation equipment draws from Switzerland and Japan. Single-source vulnerability in Chinese sugar alcohol feedstock exposes margin compression during petrochemical price spikes. Distribution runs through German sports-nutrition specialty networks and United States direct-to-consumer logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy gums market functions as a stable compounder where buccal absorption technology sustains replacement demand against liquid energy formats.
For Market Incumbents: Anticipate regulatory divergence between FDA dietary supplement pathways and EFSA novel food assessments by maintaining parallel SKU strategies. Invest in precision microencapsulation capabilities to defend margin position against commodity spray-dried competition. Channel control through subscription-platform ownership reduces slotting-fee exposure in consolidated retail.
For New Entrants and Emerging Players: The price-point gap between premium FOSHU-approved pharmacy positioning and economy convenience-store tiers offers white-space entry. Target vitamins-enhanced convergence segments where wellness positioning commands shelf premiums. Deploy direct-to-subscription models with fitness-application integration to bypass established retail gatekeepers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier producers lack regulatory affairs scale to navigate EFSA caffeine threshold harmonization. Five-to-ten-year viability favors specialists with clean-label positioning and military procurement relationships. Watch for caffeine threshold harmonization announcements as inflection indicators for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Microencapsulation Investment | Enables 24-month shelf stability and bitterness control for premium positioning. |
| FOSHU Regulatory Pathway Navigation | Unlocks 40-60% pharmacy shelf price premiums in Japan's functional claims market. |
| Direct-to-Subscription Platform Launch | Bypasses slotting fees while capturing lifetime value through workout-app integration. |
| Dual-SKU Supply Chain Architecture | Maintains parallel formulations for EU and US regulatory divergence without reformulation delays. |
| Military Procurement Relationship Development | Secures institutional volume through standardized dosing requirements and buccal absorption speed. |
Research Approach
Bottom-up fitness enthusiast and professional demand modeling reconciled against top-down caffeine gum production tracking forms the analytical core. Primary interviews with brand managers, category buyers at sports-nutrition retailers, regulatory affairs specialists, and military procurement officers combined with secondary validation from FDA dietary supplement filings, EFSA novel food registers, Japan FOSHU approval databases, and Nielsen retail audit data. Triangulation between consumption occasion analysis and manufacturing capacity assessments ensures coverage consistency.
Input-output matrices map caffeine sourcing through formulation tiers to distribution channel economics across the projection horizon. Segmentation dimensions include product type, end-user archetype, distribution channel, and regional regulatory cluster. CAGRs derive from trend extrapolation of buccal absorption technology adoption and subscription-model penetration. Forecast inputs incorporate military procurement program sizing and wellness-positioning shelf-space allocation trends.
Caveats apply where caffeine threshold harmonization between North American and European regulators could materially shift the outlook. Forecasts reflect assumptions about buccal pharmacokinetics expertise availability and sugar alcohol feedstock price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Vitamins and Minerals Market