
 Microencapsulated Phytosterols Market | 2026-2036
Microencapsulated Phytosterols Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulated Phytosterols Market Foresight
China's expanding phytosterol extraction and microencapsulation capacity is reshaping supply availability for international nutraceutical buyers. BASF SE leverages its lipid chemistry expertise to sustain premium positioning in European functional food channels. Cargill anchors North American supply through its plant sterol derivative operations and broad ingredient distribution network. Vita-Solar Biotechnology Co., Ltd. differentiates via specialized botanical extraction capabilities serving Asia-Pacific cosmetic and pharmaceutical formulators.
Microencapsulated phytosterols consist of plant-derived sterol compounds shielded within protective wall materials such as gum arabic or modified food starch, typically achieving particle sizes between 10 and 100 micrometers to enhance stability and controlled release in aqueous food matrices. Their primary commercial purpose centers on delivering cholesterol-reduction benefits in processed foods and dietary supplements without compromising sensory attributes or shelf stability. Powder formulations dominate current manufacturing output due to superior handling characteristics and compatibility with dry-blend nutraceutical processes, while liquid microencapsulated suspensions represent the fastest-growing format as beverage fortification accelerates. Functional foods command the largest application share, though pharmaceutical-grade phytosterol encapsulation for prescription adjunct therapy generates the highest margin pool per kilogram.
EFSA novel food approvals and health claim substantiation requirements shape product entry timelines and labeling strategies across European markets. FDA GRAS notifications and FSMA preventive controls govern US commercialization pathways, with the USDA overseeing organic certification claims for plant sterol sourcing. China's NMPA and SAMR regulate functional food registrations and health food blue-hat approvals for domestic phytosterol products. Stakeholders must monitor evolving encapsulation patent landscapes and jurisdiction-specific purity thresholds to secure formulation freedom and market access.
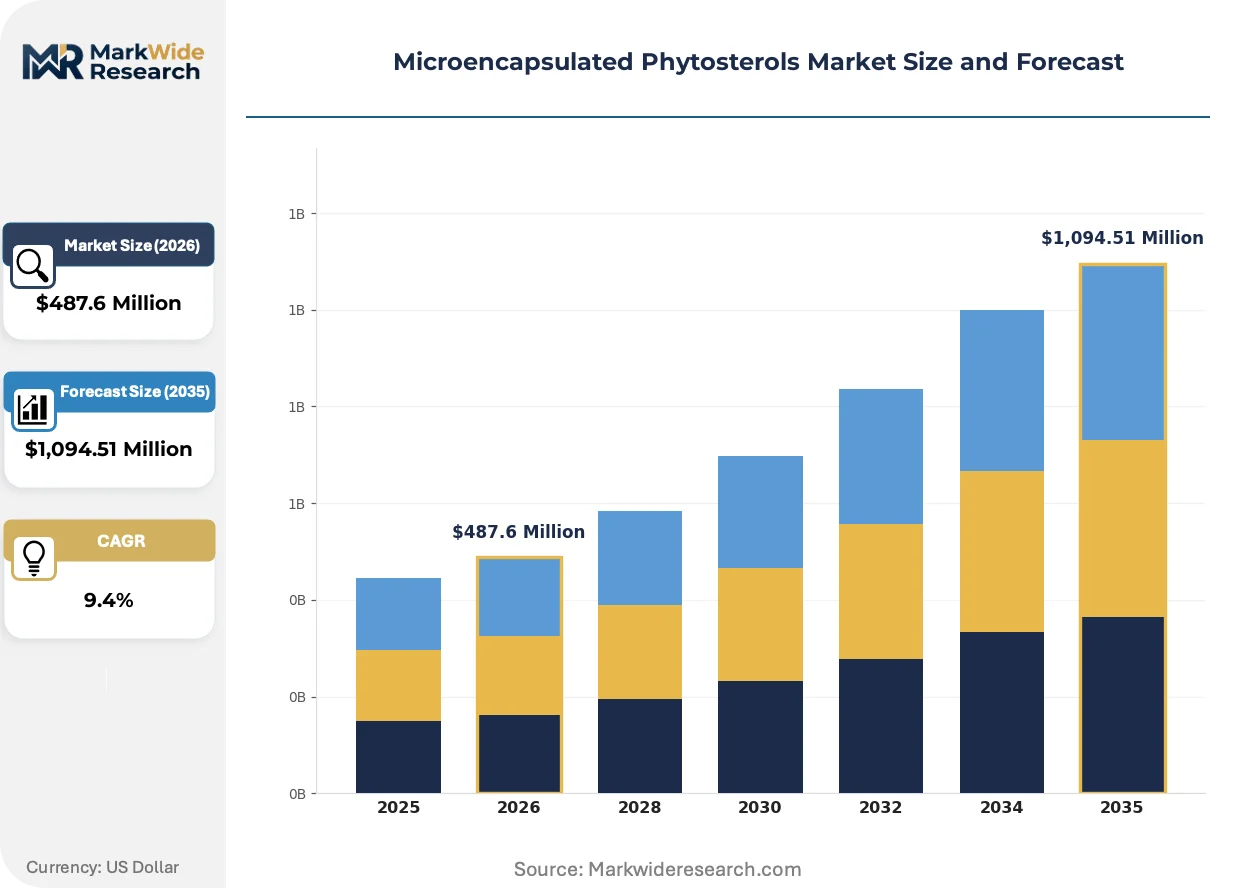
Market Dynamics
Modified starch matrix encapsulation is compressing production costs while EFSA health claim substantiation requirements are extending product entry timelines, creating a bifurcation between formulation-ready suppliers and R&D-lagged entrants.
Growth Catalysts
- EFSA Article 14 Health Claims:Validated cholesterol-reduction claims accelerate retail shelf placement for functional dairy applications in Germany and France.
- Aging demographics:Western European populations over 65 drive preventive cardiovascular nutrition procurement by institutional foodservice operators.
- Novel wall materials:Gum arabic and modified food starch matrices enhance aqueous stability, enabling beverage fortification formats previously unattainable.
Market Restraints
- Plant sterol raw material concentration:Tall oil and vegetable oil derivative supply chains cluster in Nordic and Southeast Asian extraction hubs, exposing buyers to weather-driven input volatility.
- EFSA novel food approval timelines:18-to-24-month safety assessment windows delay revenue recognition for innovative encapsulation geometries.
- Free phytosterol availability:Unencapsulated sterol esters at lower unit costs threaten substitution in price-sensitive private-label supplement channels.
Strategic Opportunities
- Pharmaceutical-grade encapsulation:Prescription adjunct therapy applications command premium margins above functional food baselines.
- Liquid suspension formats:Beverage fortification acceleration opens white space in ready-to-drink cholesterol management products.
- China functional food registration:NMPA blue-hat approval pathways for domestic phytosterol products create localized production incentives.
Industry Challenges
- Encapsulation patent landscapes:Freedom-to-operate assessments for modified starch and protein-walled geometries require specialized IP legal expenditure.
- Particle size standardization:10-to-100-micrometer specification adherence across batch-scale and continuous manufacturing demands capital-intensive process analytical technology deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulated Phytosterols Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powders, Capsules, Granules, Liquid Application: Nutraceuticals, Functional Foods, Cosmetics, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Consumers, Manufacturers, Healthcare Professionals, Researchers |
| Companies Covered | The Archer Daniels Midland Company, BASF SE, Cargill, Matrix Fine Sciences Pvt. Ltd., Raisio Plc, Vita-Solar Biotechnology Co., Ltd., COFCO Tech Bioengineering (Tianjin) Co., Ltd., Nutrartis, Pharmachem Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulated Phytosterols Market Shifts & Advancements
Encapsulation chemistry convergence with precision delivery systems is compressing the gap between nutraceutical and pharmaceutical performance standards, while regulatory data requirements harden.
Modified starch matrices with tunable release kinetics are rendering obsolete conventional spray-dried phytosterol preparations that suffered aqueous instability and sensory off-notes. Functional beverage formulators in Germany and France are adopting these systems within 18-month procurement cycles. The technology is rendering obsolete legacy powder-dominant manufacturing footprints that cannot accommodate liquid suspension outputs.
REACH registration requirements for novel encapsulation wall materials are extending chemical safety dossier preparation timelines for European entrants. Industrial consequence includes consolidation of formulation partnerships toward established polymer suppliers with existing substance registrations. Pharmaceutical-grade phytosterol encapsulators face the steepest compliance burden and are responding via dedicated regulatory affairs staffing.
Direct procurement relationships between functional food manufacturers and encapsulation technology licensors are displacing traditional ingredient distributor intermediaries. Dairy and beverage formulators in Western Europe are negotiating master service agreements for co-developed delivery systems rather than catalog purchases. This pattern is most visible in cholesterol-lowering yogurt and spreadable fat applications where sensory performance specifications are tightest.
Microencapsulated Phytosterols Market Segmentation
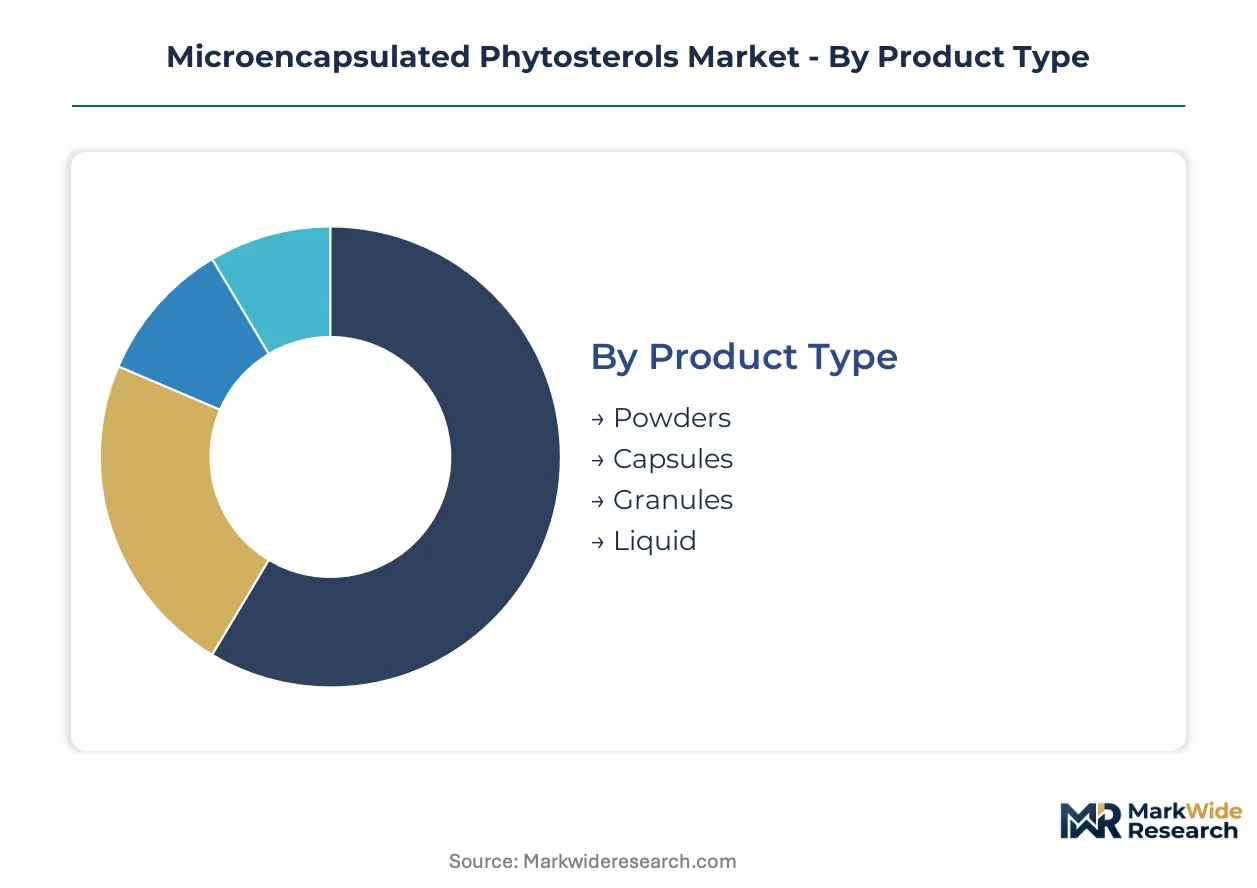
Microencapsulated phytosterol suppliers face divergent service requirements across product formats, with liquid suspensions demanding formulation support and powder customers prioritizing specification consistency. Segmentation reveals where technical assistance intensity correlates with margin capture.
Product Type:
After-sales service intensity varies sharply by physical state, with liquid formats requiring ongoing stability troubleshooting and powder customers focusing on batch-to-batch uniformity.
- Powders:Dry-blend microencapsulated phytosterols with particle sizes between 10 and 100 micrometers dominate current manufacturing output due to superior handling characteristics. German and French functional food manufacturers anchor procurement for cholesterol-lowering dairy applications where EFSA health claim substantiation drives specification rigor.
- Liquid:Aqueous microencapsulated suspensions represent the format expanding most quickly as beverage fortification accelerates. Western European dairy and beverage formulators negotiate master service agreements for co-developed delivery systems where sensory performance specifications are tightest.
- Capsules:Pre-dosed gelatin or vegetable-based shells containing microencapsulated phytosterols serve dietary supplement channels with standardized potency claims.
- Granules:Intermediate particle size formats bridge powder handling and liquid dissolution requirements for select pharmaceutical tableting operations.
Powders hold the largest share; momentum sits with liquid.
Application:
Margin structure separates nutraceutical commodity supply from pharmaceutical-grade encapsulation where prescription adjunct therapy commands premium positioning.
- Functional Foods:Processed food matrices including cholesterol-lowering yogurts and spreadable fats command the largest application share. EFSA Article 14 health claims accelerate retail shelf placement in Germany and France where aging populations drive preventive cardiovascular nutrition procurement.
- Pharmaceuticals:Prescription-grade encapsulation for adjunct therapy generates the highest margin pool per kilogram. REACH registration requirements for novel wall materials extend chemical safety dossier preparation timelines, consolidating formulation partnerships toward established polymer suppliers.
- Nutraceuticals:Dietary supplement applications face substitution pressure from unencapsulated sterol esters at lower unit costs in price-sensitive private-label channels.
- Cosmetics:Topical delivery systems leverage phytosterol anti-inflammatory properties for dermal formulations, with Asia-Pacific formulators driving specialized botanical extraction demand.
Functional foods anchor volume; pharmaceuticals concentrate value.
Distribution Channel:
Channel selection determines regulatory burden intensity, with pharmacies facing strictest purity documentation and online retail navigating varying jurisdiction-specific health claim restrictions.
- Supermarkets:Mass retail placement of functional foods with EFSA-approved cholesterol-reduction claims depends on validated shelf stability data and consumer education materials.
- Pharmacies:Pharmaceutical-grade products require batch-specific certificates of analysis and cold chain documentation where applicable.
- Health Stores:Specialty retail channels emphasize organic certification claims for plant sterol sourcing under USDA oversight.
- Online Retail:Direct-to-consumer channels face fragmented compliance across FDA GRAS notifications, EFSA novel food approvals, and China's NMPA blue-hat requirements.
Supermarkets capture mainstream penetration; pharmacies extract premium pricing.
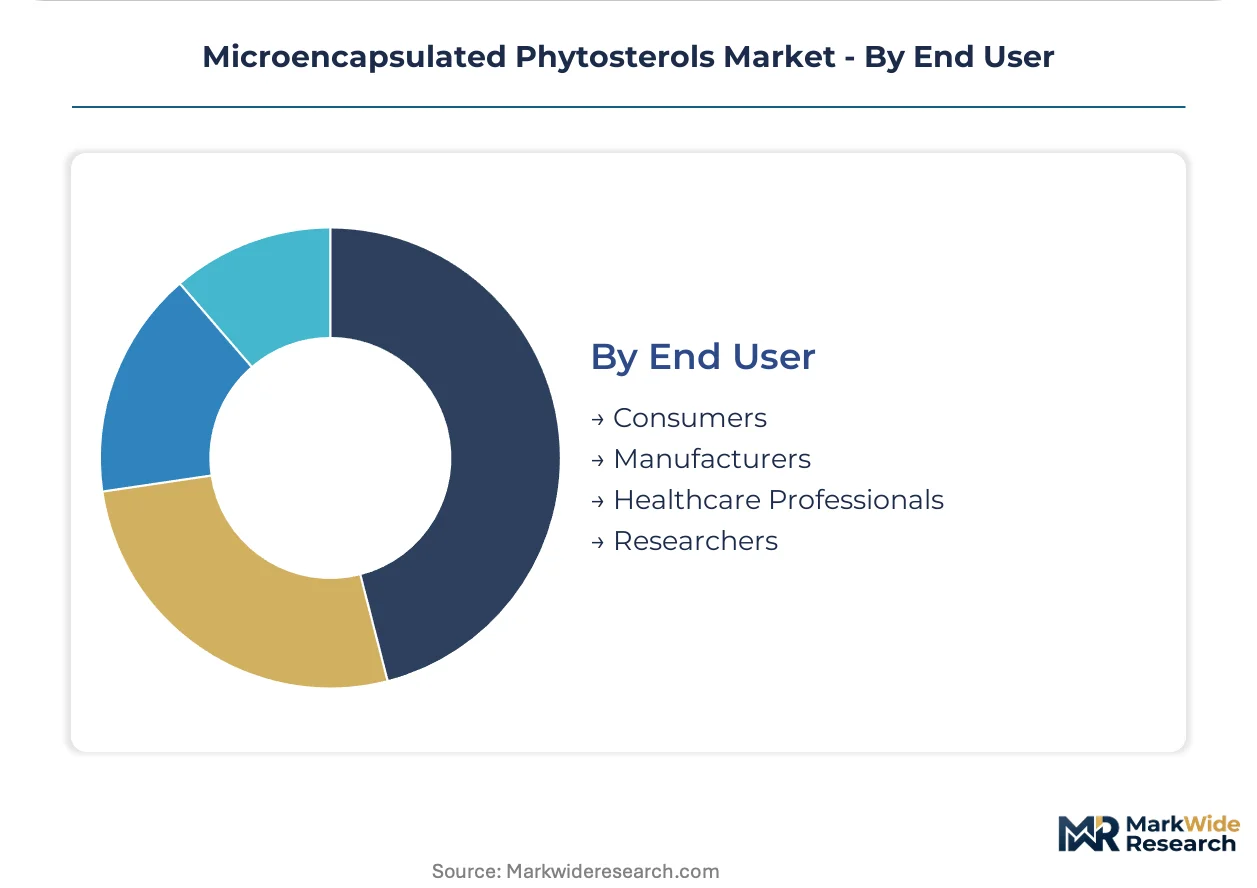
End User:
Procurement sophistication separates institutional buyers with dedicated regulatory affairs staffing from consumer self-selection where label comprehension limits adherence.
- Manufacturers:Functional food and beverage formulators drive specification development through direct procurement relationships with encapsulation technology licensors, displacing traditional ingredient distributor intermediaries.
- Healthcare Professionals:Clinical recommendation of prescription adjunct phytosterol therapy depends on cardiovascular outcome data and formulary inclusion status.
- Consumers:Self-directed purchasing decisions hinge on EFSA-approved health claim visibility and organic certification recognition.
- Researchers:Academic and clinical trial supply demands batch consistency documentation and novel encapsulation geometry samples for bioavailability studies.
Manufacturers concentrate procurement volume; healthcare professionals determine clinical legitimacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction and encapsulation capacity clusters in Nordic tall oil processing hubs and Chinese vegetable oil derivative centers, with formulation demand concentrating in Western European functional food corridors. Regulatory divergence across FDA, EFSA, and NMPA jurisdictions shapes regional entry strategies and local partnership requirements.
Germany
Functional dairy manufacturers in Bavaria and North Rhine-Westphalia anchor European procurement volumes for cholesterol-lowering applications. EFSA Article 14 health claim substantiation requirements accelerate specification rigor for retail shelf placement. Frankfurt and Hamburg host specialized encapsulation technology licensors negotiating direct master service agreements with dairy formulators.
China
Domestic phytosterol extraction capacity expansion in Jiangsu and Shandong provinces reshapes supply availability for Asia-Pacific nutraceutical buyers. NMPA blue-hat approval pathways and SAMR functional food registrations govern commercialization timelines for local manufacturers. Yangtze River Delta encapsulation specialists serve both domestic beverage fortification and export pharmaceutical-grade demand.
United States
Plant sterol derivative operations in the Midwest and Southeast supply North American functional food and dietary supplement channels. FDA GRAS notifications and FSMA preventive controls structure commercialization pathways, with USDA overseeing organic certification claims. Cargill's broad ingredient distribution network anchors supply chain reliability across multiple state-level manufacturing clusters.
France
Spreadable fat and yogurt formulators in Île-de-France and Auvergne-Rhône-Alpes drive preventive cardiovascular nutrition procurement. EFSA novel food approvals extend safety assessment windows for innovative encapsulation geometries. Lyon and Paris house regulatory affairs specialists navigating REACH registration requirements for modified starch matrix wall materials.
India
Nutraceutical contract manufacturers in Maharashtra and Gujarat source microencapsulated phytosterols for domestic supplement and functional food production. FSSAI functional food regulations and BIS quality standards shape import documentation requirements. Mumbai and Ahmedabad clusters concentrate formulation expertise for price-sensitive private-label channels facing substitution pressure from free phytosterol alternatives.
Microencapsulated Phytosterols Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and wall material supply. The vendor base stratifies across multinational chemical conglomerates with lipid chemistry platforms, mid-cap encapsulation technology licensors, and regional botanical extraction specialists. Three archetypes dominate: integrated nutrition platforms, specialized encapsulation service providers, and vertically oriented phytosterol extractors. Competitive dynamics center on direct procurement relationship formation and co-development agreements for beverage-specific delivery systems.
Among integrated nutrition platforms, BASF SE and Cargill exemplify scale-driven positioning through broad ingredient distribution networks and lipid chemistry expertise. Vita-Solar Biotechnology Co., Ltd. occupies a specialized tier serving Asia-Pacific cosmetic and pharmaceutical formulators with botanical extraction capabilities. Matrix Fine Sciences Pvt. Ltd. represents the mid-cap encapsulation specialist archetype, while The Archer Daniels Midland Company anchors agricultural-derivative supply chain integration.
| Leading Market Players |
|---|
| The Archer Daniels Midland Company |
| BASF SE |
| Cargill |
| Matrix Fine Sciences Pvt. Ltd. |
| Raisio Plc |
| Vita-Solar Biotechnology Co., Ltd. |
| COFCO Tech Bioengineering (Tianjin) Co., Ltd. |
| Nutrartis |
| Pharmachem Laboratories |
| Others |
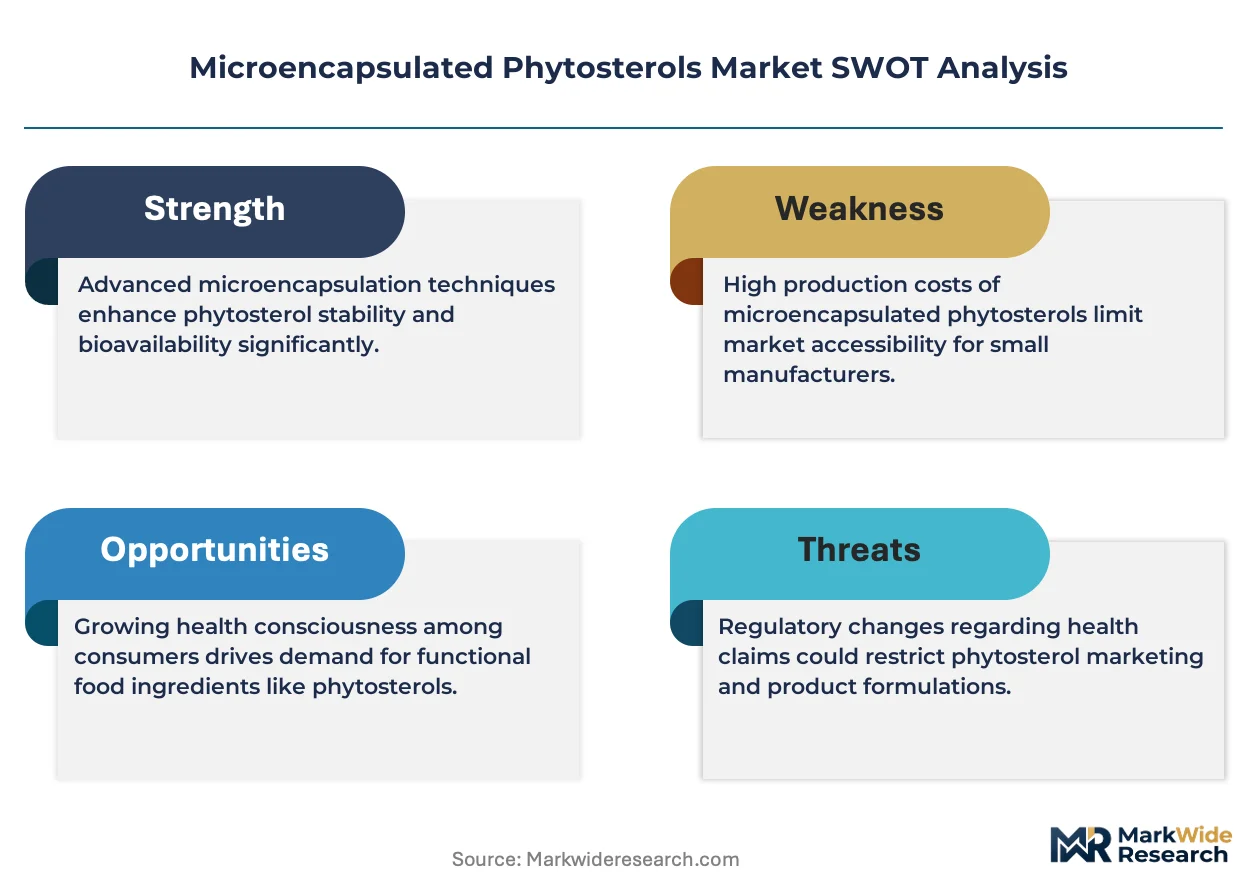
Supply & Pricing Matrix
Jiangsu province's phytosterol extraction capacity expansion is compressing input costs for encapsulation specialists while concentrating bargaining power among tall oil derivative processors in Nordic hubs. This geographic asymmetry between raw material concentration and formulation demand centers shapes margin distribution across the value chain.
Pricing Analysis
EFSA novel food approval requirements dictate the pricing tier structure across European commercialization pathways. Three-tier pricing structure across pharmaceutical-grade, functional food, and private-label nutraceutical levels separates premium prescription adjunct applications from commodity dietary supplement channels. Cost compression in powder formats is intensifying because Chinese extraction capacity is flooding intermediate markets with sterol derivatives. Private-label supplement manufacturers exhibit the highest price sensitivity, while pharmaceutical formulators prioritize batch consistency over unit economics.
Supply Chain Analysis
Extended payment terms from German and French dairy formulators are squeezing working capital for mid-cap encapsulation technology licensors. Raw material supply draws from Nordic tall oil processing, Chinese vegetable oil derivative extraction, and Indian botanical sterol operations. Critical dependencies include modified food starch matrices, gum arabic wall materials, and pharmaceutical-grade gelatin for capsule shells. Single-source vulnerability in Nordic tall oil supply exposes buyers to weather-driven harvest volatility. Distribution runs through direct master service agreements between encapsulation licensors and functional food manufacturers, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across beverage fortification formats, pharmaceutical-grade encapsulation, and cosmetic delivery systems creates multiple niche entry points as demand specialization outpaces supplier consolidation.
For Market Incumbents: Entrench market position through backward integration into modified starch matrix production and captive supply of pharmaceutical-grade wall materials. Free phytosterol substitution in price-sensitive supplement channels threatens volume retention in commodity tiers. Capacity addition in Yangtze River Delta clusters secures proximity to Asia-Pacific beverage fortification demand. For New Entrants and Emerging Players: Liquid suspension formats for ready-to-drink cholesterol management products represent the most penetrable entry point given technical service intensity requirements that deter established powder-centric suppliers. NMPA blue-hat approval consulting for domestic Chinese manufacturers offers specialized regulatory arbitrage. Co-development partnerships with encapsulation technology licensors provide faster formulation credibility than catalog ingredient sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EFSA health claim substantiation and REACH registration requirements are consolidating formulation partnerships toward established polymer suppliers with existing substance dossiers. Acquisition targets should display dedicated regulatory affairs staffing and existing master service agreements with dairy or beverage formulators. The signal to watch is direct procurement relationship formation displacing distributor intermediaries in Western European functional food corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wall Material Production | Captive supply of modified starch matrices insulates margin compression from polymer supplier consolidation. |
| Pharmaceutical-Grade Encapsulation Certification | REACH registration completion opens prescription adjunct therapy applications with premium margin capture. |
| Liquid Suspension Format Development | Beverage fortification acceleration creates technical differentiation against powder-dominant legacy footprints. |
| NMPA Blue-Hat Approval Consulting Services | Regulatory pathway expertise unlocks China domestic functional food production incentives. |
| Direct Master Service Agreements | Co-developed delivery systems with German and French dairy formulators displace distributor intermediaries. |
Research Methodology
The analysis maps extraction technology tiers, encapsulation format specifications, and application-grade requirements, each validated through regulatory affairs specialists, functional food formulators, and pharmaceutical procurement managers. Primary interviews with plant sterol derivative processors, modified starch matrix suppliers, and beverage fortification R&D directors combined with secondary validation from EFSA novel food registers, REACH substance dossiers, and NMPA blue-hat approval databases. Bottom-up volume modeling across particle size specifications and top-down value triangulation against encapsulation service pricing anchored forecast integrity.
Assumptions held EFSA health claim substantiation timelines and REACH registration requirements constant across the projection horizon, while varying Chinese extraction capacity expansion rates and beverage fortification adoption curves. Segmentation dimensions modeled include physical state, application grade, distribution channel regulatory burden, and end-user procurement sophistication. CAGRs derived from weighted average growth across format-specific demand curves, with sterol ester substitution elasticity and pharmaceutical-grade premium persistence as key industry-specific forecast inputs.
Practitioners should monitor NMPA policy shifts, EFSA novel food approval backlog changes, and modified starch matrix patent expiry schedules for early signals of competitive repositioning. Forecasts reflect documented assumptions; macroeconomic volatility in vegetable oil feedstock markets, regulatory deviation in health claim enforcement, or breakthrough encapsulation geometries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Global Lactase Market