
 Grass Fed Protein Market | 2026-2036
Grass Fed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Grass Fed Protein Market Foresight
The EU Green Deal is broadening the addressable market for verified grass-fed dairy and beef derivatives as European retailers enforce stricter provenance standards. Fonterra leverages its New Zealand pasture-based supply chain to sustain premium positioning in European ingredient channels. Glanbia Ingredients Ireland anchors its grass-fed whey portfolio around Ireland's year-round grazing climate, while Kerry Group competes through flavor-system integration that masks the sensory variability of grass-fed inputs.
Grass fed protein denotes protein isolates, concentrates, and whole-food products derived from cattle raised on pasture-based diets rather than grain-finishing systems, typically yielding higher conjugated linoleic acid and omega-3 fatty acid profiles. Powder formulations dominate ingredient trade flows due to shelf stability and blending flexibility in sports nutrition manufacturing. Protein bars capture the fastest-growing consumer touchpoint as convenience formats merge with clean-label positioning. Specialty stores and online retail together concentrate margin pools by preserving narrative control around sourcing stories that supermarkets dilute through assortment breadth.
USDA's Process Verified Program, Ireland's Bord Bia Grass Fed Standard, and Australia's Pasture Fed Cattle Assurance System collectively define the credentialing landscape that separates premium-tier products from commodity alternatives. These frameworks shape demand by limiting market access for uncertified suppliers and by forcing reformulation investments from brands seeking shelf placement at Whole Foods Market or equivalent premium channels. Stakeholders must monitor divergence between private certification schemes and emerging government-mandated definitions that could fragment labeling compliance costs across export destinations.
Market Dynamics
Pasture-certification mandates from European retailers and regenerative agriculture narratives in premium channels are compressing sourcing flexibility while amplifying price premiums for verified supply chains.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Mandatory sustainability disclosures across European retail channels are forcing brands to source verified grass-fed derivatives, expanding the addressable market for certified suppliers.
- Sports nutrition formulation demand:Clean-label protein powders and functional foods are pulling volume as manufacturers reformulate away from commodity whey toward pasture-certified alternatives.
- Australia's Pasture Fed Cattle Assurance System:Export-oriented Australian processors leverage this credential to access premium European and Asian ingredient channels that exclude uncertified competitors.
Market Restraints
- Seasonal pasture availability:Year-round grazing limitations in continental climates force reliance on conserved forages or supplemental grain, complicating certification compliance and input cost forecasting.
- Concentrated dairy processing geography:New Zealand and Ireland dominate grass-fed whey supply, creating geographic concentration risk for brands dependent on single-origin sourcing narratives.
- Grain-finishing cost advantage:Conventional feedlot operations in the United States and Brazil maintain lower production costs, pressuring price premiums for pasture-only systems.
Strategic Opportunities
- German retail channel expansion:Discounter and drugstore chains in Germany are adding grass-fed protein SKUs, opening mass-market penetration beyond specialty stores.
- Cellular agriculture convergence:Precision fermentation startups are exploring grass-fed growth media and lipid profiles to replicate pasture-raised nutritional signatures in cultivated proteins.
- USDA Process Verified Program expansion:Emerging modules for regenerative agriculture and carbon sequestration are creating new certification tiers that command additional shelf price premiums.
Industry Challenges
- Auditor capacity bottlenecks:Third-party certification bodies face backlogs for on-farm pasture verification, delaying supplier onboarding and product launch timelines.
- Legacy ERP integration:Batch-level traceability requirements for grass-fed claims force expensive upgrades to manufacturing execution systems at mid-sized co-packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass Fed Protein Market |
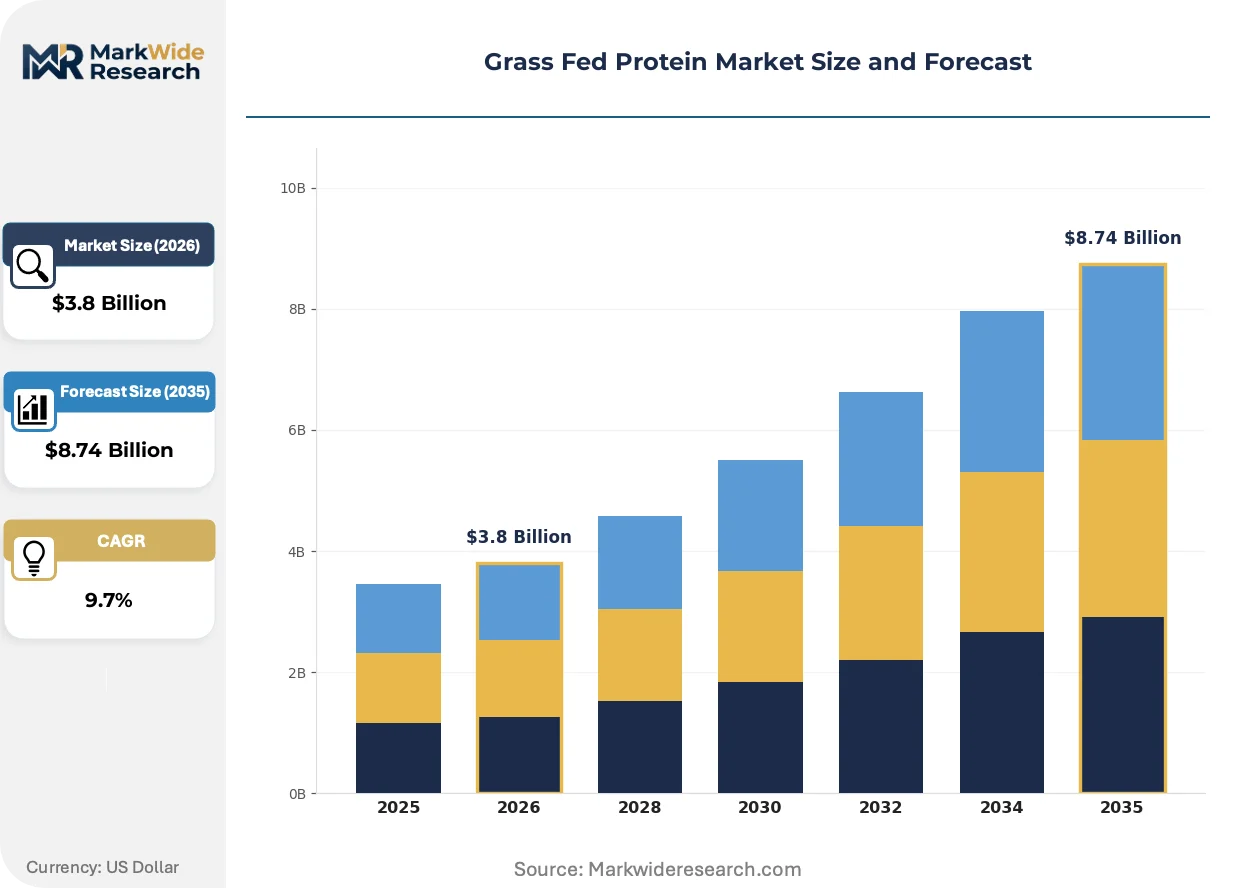
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powder, Beef Jerky, Protein Bars, Ready-to-Drink Shakes End User: Retail Consumers, Health Clubs, Nutritionists, Meal Delivery Services Form: Powder, Solid, Liquid, Capsule Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Fitness Centers |
| Companies Covered | ProMix Nutrition, NutraBio Labs, Glanbia Ingredients Ireland, Fonterra, Arla Foods Ingredients, Kerry Group, NOW Foods, Naked Nutrition, Swanson Health Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass Fed Protein Market Shifts & Advancements
Clean-label manufacturing and blockchain-enabled provenance tracking are compressing the gap between farm-level practices and consumer-facing transparency claims.
Near-infrared spectroscopy for rapid fatty acid profiling is electrifying quality control workflows at dairy processing facilities. Sports nutrition manufacturers in Germany and Australia are adopting inline testing to verify CLA and omega-3 content before batch release. This capability is electrifying the speed-to-market advantage for processors who can document nutritional differentiation in real time rather than awaiting laboratory confirmation.
REACH regulation updates in Europe are tightening residue limits for veterinary pharmaceuticals in dairy-derived ingredients. The European Chemicals Agency is requiring expanded substance dossiers for imported protein concentrates. Grass-fed suppliers from Ireland and New Zealand are accelerating supply chain audits to preempt compliance disruptions in their largest export market.
Direct-to-consumer subscription models are displacing traditional retail stocking agreements for specialty protein brands. Athletes and wellness consumers in the United States are purchasing recurring shipments through brand-owned channels, bypassing supermarket margin structures. This channel pivot is most pronounced in coastal metropolitan markets where consumers prioritize narrative control over immediate availability.
Grass Fed Protein Market Segmentation
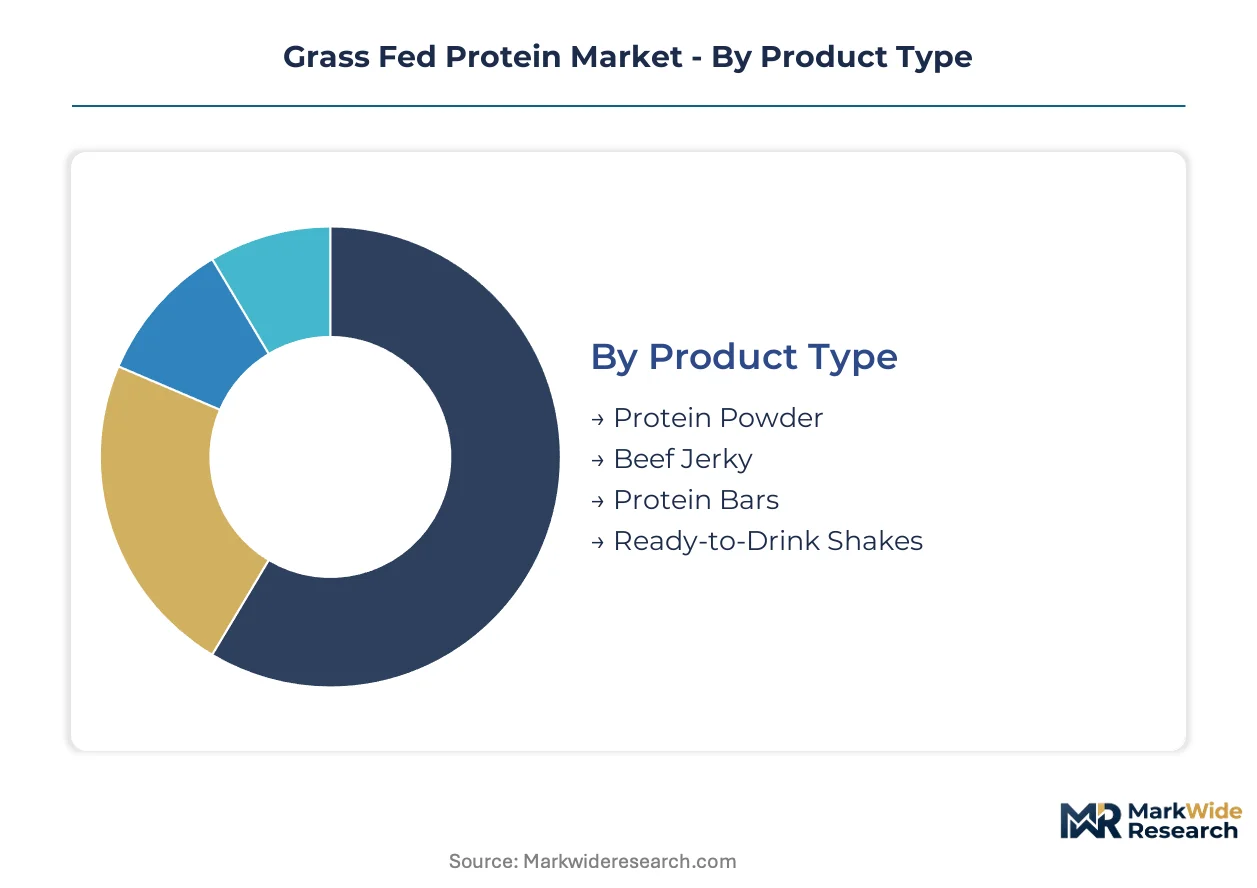
Segmentation in grass-fed protein reveals how certification premiums flow through distinct product formats and channel structures. Capital deployment varies sharply across powder processing infrastructure versus convenience-format manufacturing.
Product Type:
Protein powder production demands the heaviest upfront investment in spray-drying towers and membrane filtration systems, while bar and RTD lines require flexible packaging automation.
- Protein Powder:Spray-dried isolates and concentrates serve as the foundational input for sports nutrition formulation. German and Australian manufacturers dominate ingredient trade flows, leveraging year-round grazing credentials to secure placement in premium supplement channels.
- Protein Bars:Extrusion and cold-press manufacturing lines enable clean-label positioning with minimal processing claims. Convenience formats are gaining share fastest among urban professionals seeking portable nutrition solutions that bypass powder preparation.
- Beef Jerky:Whole-muscle processing with pasture-verified sourcing appeals to paleo and keto diet adherents. Irish and New Zealand processors control premium dried meat supply through integrated slaughter-to-package operations.
- Ready-to-Drink Shakes:Aseptic filling lines and refrigerated distribution networks constrain regional production scale. UHT stabilization enables ambient distribution but compromises the fresh-taste narrative that drives grass-fed premiums.
Protein powder absorbs the bulk of installed capacity; protein bars are expanding most quickly.
End User:
Customer archetypes range from price-sensitive mass consumers to institutional buyers with rigid procurement specifications.
- Retail Consumers:Individual purchasers respond to packaging narratives and third-party certifications at point of sale. Direct-to-subscription models in the United States bypass retail margin structures entirely.
- Meal Delivery Services:Prepared meal kit operators specify grass-fed protein inputs to differentiate premium subscription tiers. Procurement teams audit pasture-certification documentation as a condition of supplier onboarding.
- Health Clubs:Gym operators stock ready-to-consume formats for post-workout impulse purchases. On-site retail captures margin pools that external channels cannot access.
- Nutritionists:Registered dietitians recommend specific brands based on fatty acid profiling and CLA content documentation. Professional credibility depends on verified sourcing claims rather than marketing positioning.
Retail consumers generate the volume base; meal delivery services are climbing the fastest as subscription nutrition models mature.
Form:
Physical state determines shelf stability requirements and the complexity of cold-chain logistics.
- Powder:Dehydrated protein concentrates and isolates offer maximum formulation flexibility and ambient storage economics. Bulk ingredient trade flows concentrate through Rotterdam and Singapore distribution hubs.
- Solid:Bars, jerky, and encapsulated formats merge convenience with extended shelf life without refrigeration. Solid formats are gaining share fastest in travel and outdoor recreation channels.
- Liquid:RTD beverages require aseptic processing or cold-chain maintenance throughout distribution. Perishability limits geographic reach and compresses margin structures.
- Capsule:Encapsulated protein supplements serve clinical and precision nutrition applications with exact dosing requirements. Pharmaceutical-grade manufacturing standards elevate production costs above food-grade alternatives.
Powder commands the largest production footprint; solid formats are expanding most rapidly across convenience-oriented channels.
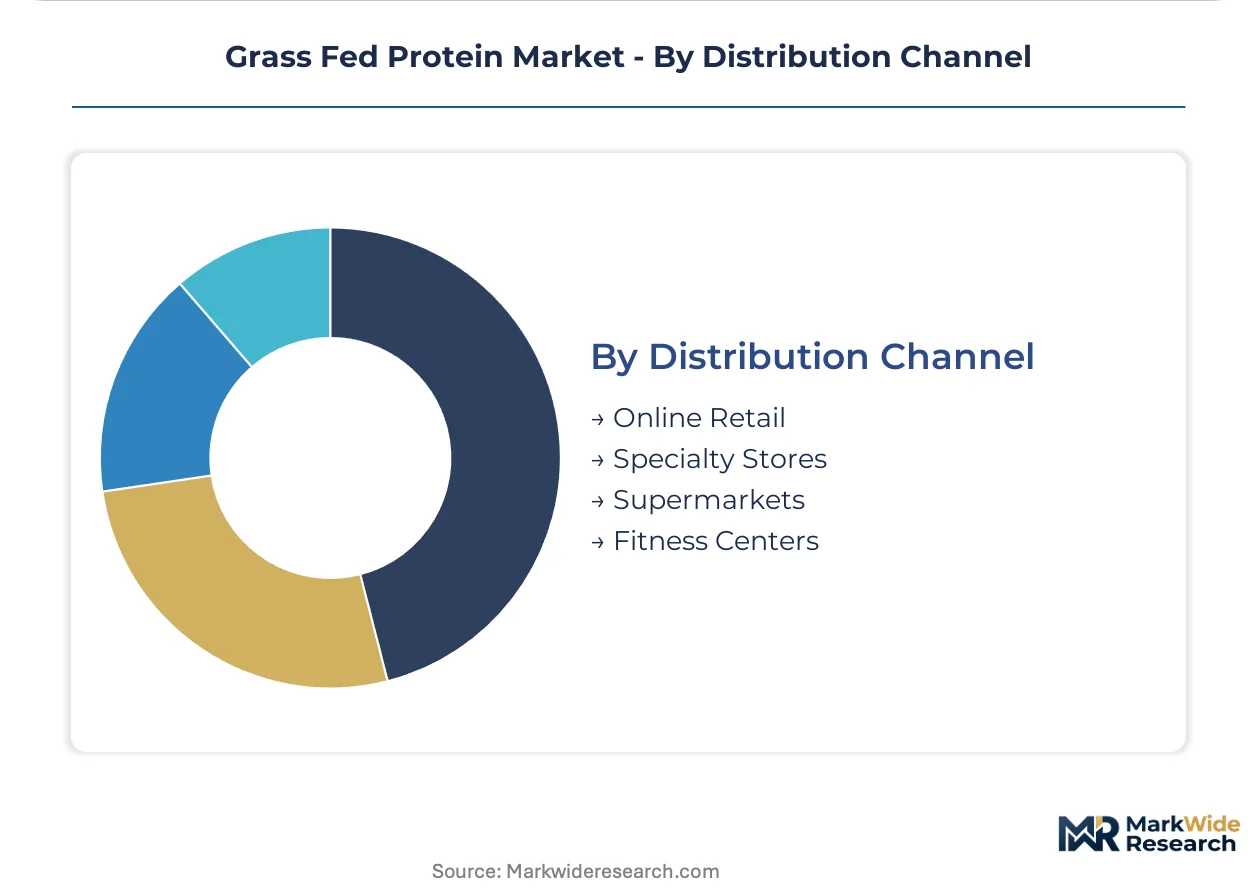
Distribution Channel:
Channel selection determines narrative control, margin retention, and the complexity of certification documentation required.
- Specialty Stores:Independent retailers and natural products chains preserve sourcing story integrity through educated staff and curated assortment. Whole Foods Market's pasture-certification mandates exclude uncertified competitors from shelf placement.
- Online Retail:Brand-owned direct channels and marketplace platforms enable subscription economics and customer data capture. Coastal metropolitan markets in the United States show highest penetration of recurring shipment models.
- Fitness Centers:On-site retail captures impulse consumption moments with minimal competitive comparison. Gym operators negotiate exclusive placement agreements for premium protein brands.
- Supermarkets:Mass retail channels dilute grass-fed narratives through assortment breadth and price-promotion intensity. Discounter chains in Germany are adding certified SKUs without premium shelf positioning.
Specialty stores retain the highest margin concentration; online retail is expanding most quickly as subscription models displace traditional stocking agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of grass-fed protein concentrates in New Zealand and Ireland outpaces domestic consumption, creating export-dependent supply chains that serve formulation demand in Germany, the United States, and Australia. This geographic split between pasture-rich origins and premium-channel destinations defines trade flows.
United States
Reformulation demand from sports nutrition brands pulls imported whey isolates through West Coast distribution hubs. USDA's Process Verified Program sets pasture-claim standards that exclude uncertified competitors from Whole Foods Market placement. Denver and Austin clusters host direct-to-consumer protein brands leveraging subscription economics to bypass retail margin structures.
Germany
Discounter and drugstore chains are expanding grass-fed SKU counts beyond specialty natural products channels. EU Green Deal farm-to-fork disclosure mandates force brands to document pasture-verified sourcing for shelf access. Cologne and Hamburg serve as formulation hubs where ingredient traders connect Irish and New Zealand supply with Central European manufacturing.
Australia
Export-oriented processors leverage the Pasture Fed Cattle Assurance System to access premium Asian and European ingredient channels. Year-round grazing climates in Victoria and New South Wales sustain consistent certification compliance that seasonal continental suppliers cannot match. Sydney and Melbourne anchor integrated slaughter-to-ingredient operations controlling dried meat and whey concentrate exports.
Ireland
Bord Bia Grass Fed Standard certification underpins premium positioning in European ingredient trade. The country's year-round grazing climate supports consistent supply of pasture-verified whey derivatives. Cork and Limerick processing clusters serve Glanbia Ingredients Ireland and Kerry Group manufacturing with integrated farm-to-factory traceability systems.
New Zealand
Fonterra's pasture-based supply chain sustains premium export positioning through verified grass-fed dairy derivatives. The country's grazing-dominant production system aligns with EU retailer sustainability mandates without reformulation requirements. Waikato and Canterbury dairy processing regions concentrate spray-drying capacity serving Asian and European sports nutrition formulators.
Grass Fed Protein Market Competitive Landscape
The competitive structure tilts toward integrated dairy processors with captive pasture supply. Processing concentration in Ireland and New Zealand creates geographic moats for verified ingredient suppliers. Three archetypes dominate: multinational dairy cooperatives with integrated farm networks, ingredient specialists leveraging national certification brands, and direct-to-consumer brands bypassing traditional retail. Capacity expansion and certification-tier diversification represent the dominant competitive moves as players respond to EU retailer mandate timelines.
Within the cooperative processor tier, Fonterra and Glanbia Ingredients Ireland exemplify supply-chain-integrated positioning that converts national grazing advantages into export market access. Kerry Group occupies a differentiated position through flavor-system capabilities that address sensory variability in grass-fed inputs. Among direct-to-consumer specialists, Naked Nutrition and ProMix Nutrition represent the subscription-channel archetype that captures margin pools through narrative control rather than retail distribution breadth.
| Leading Market Players |
|---|
| ProMix Nutrition |
| NutraBio Labs |
| Glanbia Ingredients Ireland |
| Fonterra |
| Arla Foods Ingredients |
| Kerry Group |
| NOW Foods |
| Naked Nutrition |
| Swanson Health Products |
| Others |
Supply & Pricing Matrix
Sovereign-backed dairy cooperatives in New Zealand and Ireland anchor supply-side ownership, converting national grazing advantages into pricing discipline that resists commodity whey volatility. Private-equity-rolled-up sports nutrition brands in the United States and Germany capture margin through subscription channels, bypassing retail price compression.
Pricing Analysis
Price erosion across economy-tier commodity whey traces to Brazilian and US grain-finishing cost advantages that undercut pasture-only systems. Three-tier pricing structure across premium certified, standard verified, and economy unverified levels stratifies by Bord Bia and USDA Process Verified certification tiers. Cost-down pressure on mid-tier products accelerates because German discounters are adding certified SKUs without premium shelf positioning. Meal delivery services show least price sensitivity due to procurement specifications that mandate documentation; mass retail consumers in supermarket channels exhibit highest sensitivity to per-gram protein cost.
Supply Chain Analysis
Returns of non-conforming batches to Irish and New Zealand processors for re-spray drying or alternative use in animal feed streams creates reverse-logistics complexity for expired or off-specification inventory. Geographic supply concentration centers on New Zealand, Ireland, and Australia, where year-round grazing climates sustain consistent certification compliance. Raw material dependencies draw from pasture land access, dairy cow herd inventories, and membrane filtration equipment. Single-source vulnerability looms as Fonterra and Glanbia Ingredients Ireland control dominant whey isolate capacity. Distribution runs through Rotterdam and Singapore ingredient hubs serving German and US formulation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over pasture-verified milk supply determines margin retention against grain-finishing commodity alternatives.
For Market Incumbents: Lock in multi-year pasture supply agreements with Irish and New Zealand dairy cooperatives before EU Green Deal disclosure mandates expand buyer competition. Defend against precision fermentation substitutes by accelerating CLA and omega-3 content verification through near-infrared spectroscopy deployment. Prioritize certification tier diversification under USDA Process Verified Program regenerative agriculture modules to capture additional shelf price premiums.
For New Entrants and Emerging Players: EU Green Deal farm-to-fork targets in Germany open a window for direct-to-consumer subscription brands that bypass established retail gatekeepers. Target underpenetrated meal delivery service procurement channels where sourcing documentation requirements exclude uncertified incumbents. Pursue white-label manufacturing partnerships with mid-sized German co-packers seeking certified ingredient inputs for discounter SKU expansion.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian processors with Pasture Fed Cattle Assurance System credentials and underutilized spray-drying capacity in Victoria. Long-term viability hinges on climate resilience of year-round grazing geographies versus seasonal continental suppliers. Monitor auditor capacity bottlenecks at third-party certification bodies as an inflection indicator for supply-constrained pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pasture Supply | Fonterra's captive dairy farm network eliminates third-party milk price volatility for whey isolate production. |
| Certification Tier Diversification | USDA Process Verified regenerative agriculture modules command premium placement at Whole Foods Market. |
| Direct-to-Consumer Channel Launch | Naked Nutrition's subscription model captures margin pools that supermarket distribution sacrifices to promotional intensity. |
| Inline Fatty Acid Verification Deployment | German manufacturers adopting near-infrared spectroscopy accelerate batch release speed versus laboratory confirmation delays. |
| Blockchain Provenance Tracking Integration | Kerry Group's flavor-system customers demand batch-level traceability that satisfies EU retailer sustainability mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dairy procurement directors at sports nutrition formulators, certification body auditors, and ingredient trading desk managers in Rotterdam and Singapore complemented secondary validation. Bottom-up triangulation against top-down trade flow estimates reconciled volume assumptions across powder, bar, and RTD product categories.
Data-stream reconciliation across supply-side capacity registers and demand-side procurement surveys shaped the analytical framework. Segmentation dimensions modeled include product format, certification tier, end-user archetype, and regional channel structure across the projection horizon. CAGRs derived from installed capacity expansion timelines and buyer mandate compliance deadlines incorporated pasture availability constraints and auditor capacity bottlenecks as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation replication of grass-fed lipid profiles would alter the outlook. Forecasts reflect assumptions around EU retailer mandate enforcement timelines and USDA certification module expansion. Practitioners should monitor ECHA REACH regulation updates for veterinary pharmaceutical residue limits and third-party certification body backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Sports Food Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Dysphagia Supplements Market