
 Phytonutrients Market | 2026-2036
Phytonutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Phytonutrients Market Outlook
The EU Green Deal is hardening sustainability benchmarks for bioactive ingredient sourcing across European food and nutraceutical supply chains. BASF SE leverages its integrated carotenoid production network to secure feedstock traceability from farm to formulation. Cargill Incorporated anchors its position through backward integration into specialty crop breeding programs. DSM-Firmenich differentiates via fermentation-derived phytonutrient platforms that reduce agricultural land dependency.
Phytonutrients are bioactive compounds synthesized by plants, including flavonoids, carotenoids, saponins, and alkaloids, typically extracted through solvent-based or supercritical CO2 methods and standardized to defined purity thresholds for commercial use. These compounds serve primarily as functional ingredients that confer antioxidant, anti-inflammatory, or colorant properties in finished goods. Carotenoids command the largest share of the product type landscape due to established use in food coloring and eye health formulations, while flavonoids represent the fastest-expanding category driven by cardiovascular health research. Within applications, dietary supplements capture accelerating demand as direct-to-consumer brands prioritize clinically substantiated dosages over commodity extracts.
EMA guidelines on health claim substantiation, FDA notification requirements for new dietary ingredients, and EFSA evaluations under the EU Nutrition and Health Claims Regulation collectively elevate the evidentiary bar for market entry. These frameworks compel manufacturers to invest in human clinical trials rather than relying on in vitro or observational data alone. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation redesign costs and delayed product launches.
Market Dynamics
EU Green Deal sustainability mandates are restructuring phytonutrient sourcing requirements, compelling manufacturers to abandon solvent-intensive extraction in favor of fermentation-derived and supercritical CO2 platforms that demonstrate full feedstock traceability.
Growth Catalysts
- Preventive Health Prioritization:Dietary supplement brands in Germany and the Netherlands are reformulating portfolios around clinically substantiated flavonoid dosages, creating pull-through demand for standardized extracts.
- REACH and EFSA Alignment:Convergence between chemical safety registration and health claim evaluation is streamlining multi-jurisdiction product development timelines for carotenoid suppliers.
- Fermentation Platform Maturation:Microbial production systems in Danish and Dutch biotech clusters are achieving parity yields with agricultural extraction for high-purity lutein and zeaxanthin.
Market Restraints
- Input Cost Volatility:Organic marigold and tomato paste feedstock prices fluctuate with Mediterranean climate patterns, compressing margins for carotenoid extractors dependent on seasonal harvests.
- Regulatory Friction:EFSA's 2023 tightened evidentiary standards for cardiovascular health claims require human intervention trials that add 18-24 months to substantiation timelines.
- Substitution Threat:Synthetic astaxanthin from petrochemical routes competes aggressively in aquaculture feed applications where colorant performance outweighs natural-origin premiums.
Strategic Opportunities
- Underpenetrated Applications:Sports nutrition and personalized nutrition platforms in France represent white space for saponin-based recovery formulations with anti-inflammatory positioning.
- Regulatory Tailwind:Italy's national recovery plan allocates biotechnology innovation funding toward domestic phytonutrient fermentation capacity expansion.
- Channel Innovation:Direct-to-consumer subscription models in Spain bypass traditional pharmaceutical wholesale markups, capturing margin previously lost to distribution intermediaries.
Industry Challenges
- Specialized Talent Scarcity:Phytochemistry and regulatory affairs professionals with dual expertise in EFSA dossier preparation and supercritical extraction engineering command premium compensation in Frankfurt and Hamburg clusters.
- Certification Timeline Compression:Organic and non-GMO verification processes for specialty crop supply chains create inventory holding periods that strain working capital for mid-scale extractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytonutrients Market |
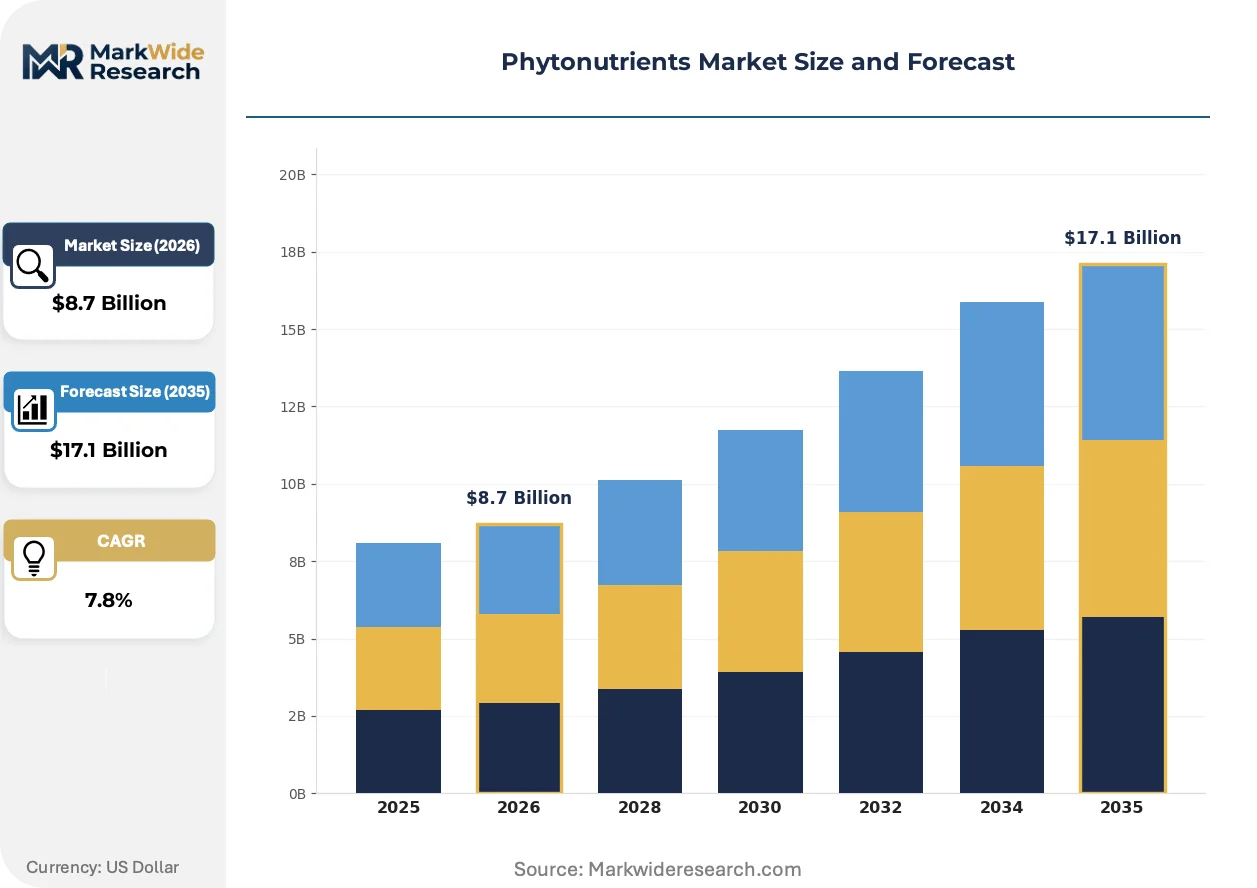
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavonoids, Carotenoids, Saponins, Alkaloids Application: Food & Beverage, Personal Care, Pharmaceuticals, Dietary Supplements Form: Liquid, Powder, Capsule, Tablet Source: Fruits, Vegetables, Herbs, Whole Grains |
| Companies Covered | BASF SE, Cargill Incorporated, Archer Daniels Midland Company, DSM-Firmenich, Kemin Industries, Kerry Group plc, FMC Corporation, Raisio Plc, Döhler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytonutrients Market Strategic Shifts
Fermentation-derived production platforms and AI-guided compound discovery are displacing conventional agricultural extraction as the dominant innovation vector across European phytonutrient supply chains.
Supercritical CO2 extraction systems with integrated in-line analytics are automating purity standardization for carotenoid concentrates, enabling real-time parameter adjustment that reduces batch rejection rates. German nutraceutical contract manufacturers are adopting these platforms at accelerating pace to meet EFSA substantiation requirements for eye health formulations. This automation is compressing quality control labor costs while tightening coefficient of variation on active compound specifications.
EFSA's 2023 guidance on bioactive compound characterization requires quantified metabolite profiling that exceeds previous botanical extract identification standards. The regulation forces reformulation of legacy flavonoid products that relied on marker compound claims rather than full-spectrum analysis. Italian and Spanish supplement brands are responding by consolidating supplier bases toward integrated producers with in-house analytical chemistry capabilities.
Ingredient buyers are consolidating procurement around suppliers with captive cultivation or fermentation capacity, displacing spot-market purchasing of commodity extracts. This concentration is most visible among German direct-to-consumer brands that now require batch-level carbon footprint documentation as a mandatory vendor qualification criterion. The shift is squeezing trading houses and toll processors without upstream asset control.
Phytonutrients Market Segmentation
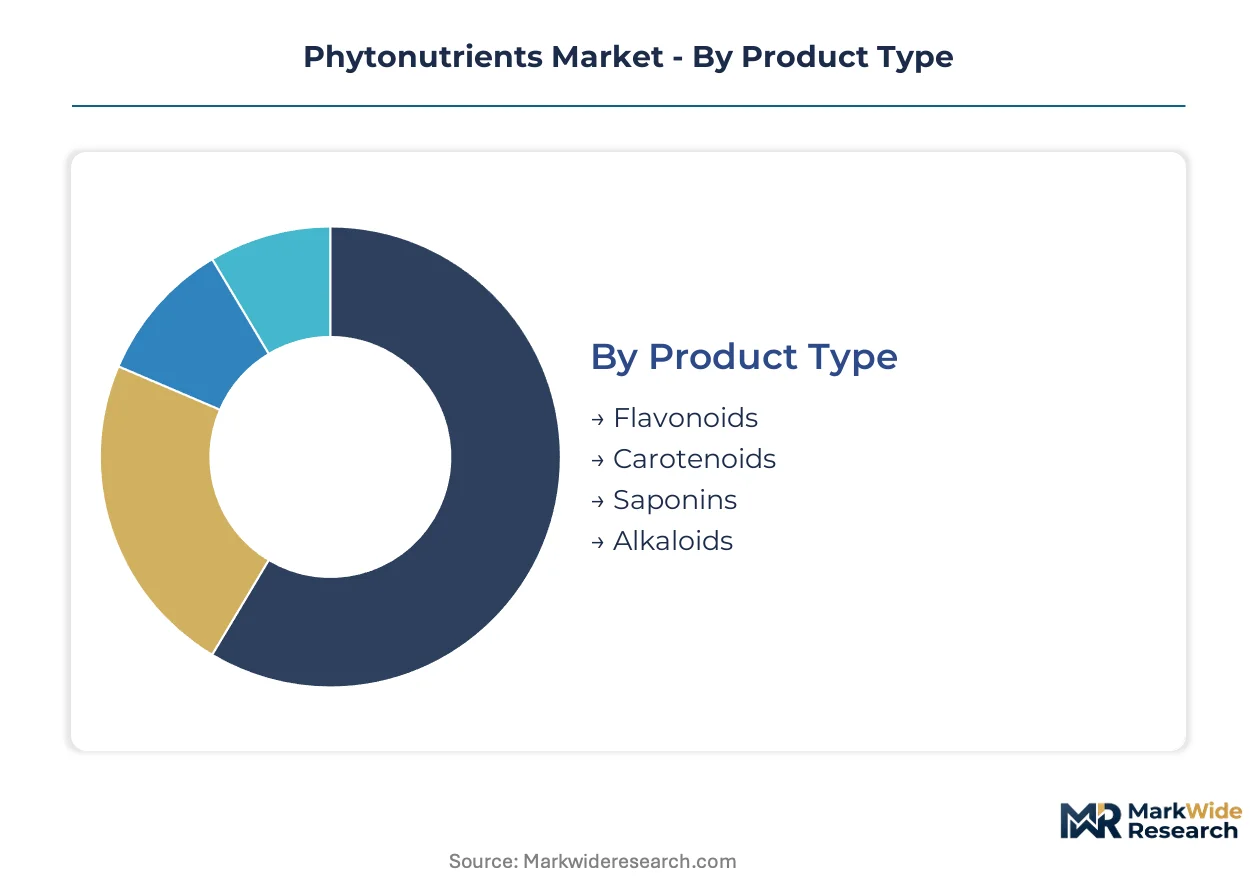
Phytonutrient suppliers configure production assets around molecular class characteristics and end-use purity requirements. Segmentation discipline separates fermentation-capable platforms from agricultural extraction networks, determining which manufacturers can serve substantiated health claim markets versus commodity colorant applications.
Product Type:
Capital intensity varies sharply across molecular classes, with fermentation-derived carotenoids demanding bioreactor infrastructure while flavonoid extraction leverages existing solvent recovery systems.
- Carotenoids:Beta-carotene, lutein, zeaxanthin, and astaxanthin dominate eye health formulations and aquaculture feed coloration. German direct-to-consumer brands consolidate procurement around suppliers with captive fermentation capacity in Hamburg and Frankfurt clusters. EFSA substantiation requirements for eye health claims favor high-purity concentrates with batch-level metabolite profiling.
- Flavonoids:Quercetin, catechin, and anthocyanin compounds serve cardiovascular and anti-inflammatory positioning. Dutch and German supplement manufacturers reformulate portfolios around clinically substantiated dosages, pulling demand toward standardized extracts rather than commodity botanical powders. This segment expands most quickly as human trial data accumulates for vascular function endpoints.
- Saponins:Glycoside compounds from legumes and herbs function as emulsifiers and recovery aids. Sports nutrition applications in France represent underpenetrated positioning for anti-inflammatory formulations.
- Alkaloids:Nitrogen-containing bioactives including caffeine and theobromine serve stimulant and metabolic applications. Regulatory scrutiny from EMA and national pharmacovigilance authorities constrains novel alkaloid introduction.
Most installed capacity flows through Carotenoids. Expansion is steepest in Flavonoids.
Application:
End-use channels diverge by evidentiary requirements, with pharmaceutical and supplement applications demanding clinical trial investment that food and beverage formulators bypass.
- Dietary Supplements:Capsule, tablet, and softgel delivery systems command premium pricing for substantiated health claims. Direct-to-consumer brands in Germany and Spain bypass traditional pharmaceutical wholesale markups, capturing margin through subscription models. EFSA's tightened cardiovascular claim standards force human intervention trials that favor integrated producers with in-house clinical capabilities.
- Food & Beverage:Natural colorants and antioxidant preservatives in functional drinks and fortified foods. Clean-label reformulation by major European retailers drives substitution of synthetic additives with carotenoid-based alternatives.
- Pharmaceuticals:Prescription and over-the-counter botanical drug applications requiring EMA marketing authorization. Alkaloid-based therapies face elevated pharmacovigilance requirements.
- Personal Care:Topical antioxidant and anti-aging formulations. Cosmetic claim regulation under EU Cosmetics Regulation limits therapeutic positioning without medicinal product registration.
Revenue concentration sits with Dietary Supplements. Volume throughput peaks in Food & Beverage.
Form:
Processing equipment specialization separates liquid extract concentrators from solid dosage form manufacturers, with powder handling dominating bulk ingredient trade.
- Powder:Spray-dried and standardized extracts for bulk ingredient distribution and encapsulation feedstock. German contract manufacturers prefer powder inputs for blending flexibility across capsule and tablet lines.
- Liquid:Oil-soluble carotenoid suspensions and ethanol-based tinctures for beverage fortification and softgel filling. Supercritical CO2 extraction yields liquid concentrates with superior oxidative stability.
- Capsule:Hard-shell gelatin and vegetarian capsules for direct-to-consumer supplement brands. Italian and Spanish brands consolidate supplier bases toward integrated producers with in-house analytical chemistry.
- Tablet:Compressed dosage forms requiring excipient compatibility and dissolution profiling. EFSA substantiation demands drive tablet standardization toward specified active compound release kinetics.
Ingredient trade flows predominantly through Powder. Finished goods growth concentrates in Capsule.
Source:
Raw material procurement geography determines carbon footprint documentation compliance and organic certification viability for EU Green Deal alignment.
- Vegetables:Marigold-derived lutein, tomato lycopene, and spinach-based carotenoids. Mediterranean climate volatility in organic marigold harvests compresses margins for seasonal-dependent extractors.
- Fruits:Citrus flavonoids, berry anthocyanins, and grape polyphenols. Italian and Spanish cultivation clusters supply standardized extracts with full traceability documentation.
- Herbs:Ginkgo biloba, green tea catechins, and milk thistle silymarin. Traditional herbal medicine frameworks in Germany create regulatory pathways distinct from novel food regulations.
- Whole Grains:Ferulic acid, lignans, and phenolic acids from wheat and oat bran. Fermentation platform maturation in Danish biotech clusters reduces agricultural land dependency for grain-derived compounds.
Current extraction infrastructure centers on Vegetables. Fermentation substitution advances fastest in Whole Grains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phytochemistry specialists cluster in German biotechnology hubs, Dutch fermentation centers, and Italian extraction zones, anchoring European phytonutrient production capacity and regulatory expertise concentration.
Germany
Direct-to-consumer supplement brands in Frankfurt and Hamburg drive reformulation demand around clinically substantiated flavonoid dosages. EFSA's tightened cardiovascular health claim standards under the EU Nutrition and Health Claims Regulation compel human intervention trial investment. The Hamburg-Frankfurt corridor hosts integrated producers with captive fermentation capacity and in-house analytical chemistry capabilities serving substantiated health claim markets.
Netherlands
Microbial production systems in Dutch biotech clusters achieve yield parity with agricultural extraction for high-purity lutein and zeaxanthin. REACH alignment with EFSA evaluation procedures streamlines multi-jurisdiction product development for carotenoid suppliers. Rotterdam-Antwerp logistics corridors enable carbon footprint documentation compliance for German and French ingredient buyers.
Italy
Italy's national recovery plan allocates biotechnology innovation funding toward domestic phytonutrient fermentation capacity expansion. EMA guidelines on botanical drug substantiation create distinct regulatory pathways for traditional herbal medicine frameworks. Italian cultivation clusters in Emilia-Romagna supply citrus flavonoids and berry anthocyanins with full traceability documentation for EU Green Deal alignment.
Spain
Direct-to-consumer subscription models in Madrid and Barcelona bypass traditional pharmaceutical wholesale markups, capturing margin previously lost to distribution intermediaries. Spanish supplement brands consolidate supplier bases toward integrated producers with batch-level carbon footprint documentation. Mediterranean climate volatility in organic marigold harvests compresses margins for seasonal-dependent extractors serving colorant markets.
France
Sports nutrition and personalized nutrition platforms in Paris and Lyon represent underpenetrated white space for saponin-based recovery formulations with anti-inflammatory positioning. ANSM pharmacovigilance requirements constrain novel alkaloid introduction for stimulant applications. French retailers drive clean-label reformulation, substituting synthetic additives with carotenoid-based alternatives in functional beverages.
Phytonutrients Market Competitive Environment
Capital-heavy producers compete with asset-light designers as integrated fermentation operators face specialty extraction houses. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive biotechnology platforms, mid-scale regional extractors with solvent recovery infrastructure, and niche contract manufacturers serving direct-to-consumer brands. Strategic archetypes include backward-integrated agricultural operators, fermentation technology licensors, and analytical chemistry service providers. Competitive moves concentrate on capacity expansion in Danish and Dutch biotech clusters and portfolio diversification toward sports nutrition applications.
Within the multinational chemical tier, BASF SE and DSM-Firmenich exemplify divergent sourcing strategies, with the former leveraging integrated carotenoid production networks and the latter differentiating via fermentation-derived platforms. Cargill Incorporated anchors the agricultural integration archetype through specialty crop breeding programs. These three entities represent the dominant competitive anchors shaping procurement consolidation patterns among German and Spanish direct-to-consumer brands.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Kemin Industries |
| Kerry Group plc |
| FMC Corporation |
| Raisio Plc |
| Döhler Group |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived production platforms are simultaneously compressing unit economics and redistributing supply concentration toward Dutch and Danish biotech clusters, enabling integrated producers to command premium pricing for EFSA-substantiated extracts while spot-market agricultural extractors face margin erosion from Mediterranean climate volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived carotenoids with batch-level metabolite profiling from solvent-extracted commodity grades and synthetic alternatives. Price differentiation hinges on EFSA substantiation status and organic certification tier, with German direct-to-consumer brands paying substantial premiums for documented traceability. Pricing pressure stems from synthetic astaxanthin competition in aquaculture feed applications where colorant performance outweighs natural-origin premiums. Contract manufacturers exhibit highest price sensitivity, while pharmaceutical-grade buyers prioritize specification consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German and Spanish supplement brands now mandate multi-supplier qualification with batch-level carbon footprint documentation, compressing procurement timelines for trading houses without upstream asset control. Geographic supply concentration centers on Germany, the Netherlands, and Italy, with Dutch fermentation platforms and Italian citrus cultivation clusters anchoring regional capacity. Raw material dependencies include organic marigold flowers, tomato paste feedstock, and microbial culture media. Single-source vulnerability runs through Mediterranean seasonal harvests for carotenoid extraction. Distribution runs through Rotterdam-Antwerp logistics corridors serving German and French ingredient buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA's tightened cardiovascular health claim standards under the EU Nutrition and Health Claims Regulation are accelerating demand for clinically substantiated extracts and consolidating procurement around integrated producers.
For Market Incumbents: Lock in supplier exclusivity with German direct-to-consumer brands by expanding captive fermentation capacity in Hamburg and Frankfurt clusters. Invest in in-house analytical chemistry capabilities to meet EFSA's quantified metabolite profiling requirements, defending margin position against commodity extractors lacking clinical trial infrastructure. Prioritize backward integration into specialty crop breeding programs to secure organic marigold and tomato feedstock traceability. For New Entrants and Emerging Players: Sports nutrition formulators in France represent an underserved buyer archetype with limited saponin-based recovery formulation options and minimal incumbent saturation. Target personalized nutrition platforms in Lyon seeking anti-inflammatory positioning with white-label manufacturing partnerships. Bypass traditional pharmaceutical wholesale channels through direct-to-consumer subscription infrastructure in Madrid and Barcelona. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional extractors with solvent recovery infrastructure because procurement consolidation among German and Spanish brands is displacing spot-market purchasing and squeezing asset-light trading houses. Focus acquisition screening on Italian and Spanish operators with established organic certification and citrus cultivation relationships. Watch fermentation yield parity announcements from Danish biotech clusters as the inflection signal for agricultural extraction obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Dutch biotech clusters achieving yield parity with agricultural extraction for high-purity lutein. |
| Backward Integration into Crop Breeding | Cargill Incorporated's specialty marigold programs secure organic feedstock traceability for EFSA compliance. |
| Direct-to-Consumer Channel Launch | Spanish subscription models bypass pharmaceutical wholesale markups and capture distribution margin. |
| Regulatory Dossier Investment | Human intervention trials for cardiovascular claims add 18-24 months but lock in premium pricing tiers. |
| Joint Venture in Analytical Chemistry | Italian supplement brands consolidate supplier bases toward integrated producers with in-house metabolite profiling. |
Study Parameters
Multiple input streams — structured interviews with phytochemistry specialists and regulatory affairs directors, procurement manager surveys at German supplement manufacturers, and validation against EFSA guidance documents — were reconciled through bottom-up and top-down triangulation. Secondary sources included customs trade data for carotenoid and flavonoid extract flows, SEC filings from multinational chemical conglomerates, and EU Nutrition and Health Claims Regulation evaluation records.
Data-stream reconciliation applied analytical frameworks across product type, application channel, form factor, and raw material source dimensions over the projection horizon. CAGRs were derived from segment-level volume and value trajectories, with fermentation platform maturation rates and EFSA substantiation timeline assumptions serving as key industry-specific forecast inputs.
Underlying measurement precision varies by segment; dietary supplements and fermentation-derived carotenoids carry tighter precision than commodity agricultural extracts due to more concentrated supplier bases and documented procurement patterns. Deviation in EFSA evidentiary standards or Mediterranean climate patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
Europe Diet Pills Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market