
 Plant Based Protein Supplements Market | 2026-2036
Plant Based Protein Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Protein Supplements Market Intelligence
Capital-intensity divergence between integrated ingredient processors and pure-brand marketers is redrawing competitive boundaries in plant protein supplements. Glanbia plc leverages its captive pea protein extraction infrastructure to secure margin control from crop to finished powder. NOW Foods sustains a differentiated position through vertically managed supply chains for organic hemp and chia seed inputs. Abbott Laboratories anchors its clinical nutrition credibility with hospital-grade formulation standards that smaller competitors struggle to replicate.
Plant based protein supplements comprise isolated or concentrated protein fractions derived from legumes, oilseeds, and pseudocereals, typically processed through wet extraction, enzymatic hydrolysis, or dry fractionation to achieve protein contents ranging from 60% to 90% by weight. These formulations serve primarily as functional nutrition inputs for muscle protein synthesis, satiety management, and clinical dietary intervention where dairy or egg allergens are contraindicated. Powder formats dominate current volume flows due to lower per-serving logistics costs and formulation flexibility for smoothies and baked goods, while ready-to-drink applications capture premium shelf space in convenience retail. Sports nutrition and meal replacement applications concentrate the highest margin pools, with functional foods representing an emerging but still price-sensitive growth corridor.
The FDA's Current Good Manufacturing Practice regulations for dietary supplements enforce identity testing and contaminant screening that elevates compliance costs for new entrants. EFSA novel food authorizations govern chia and hemp protein commercialization across European markets, creating asynchronous market access timelines. India's FSSAI has tightened protein content claim verification for imported supplement brands, reshaping export certification requirements. Stakeholders must monitor how divergent national enforcement intensities redistribute manufacturing investment and label claim strategies across regulatory jurisdictions.
Market Dynamics
Capital-intensity divergence between integrated ingredient processors and pure-brand marketers is redrawing competitive boundaries in plant protein supplements. Glanbia plc leverages its captive pea protein extraction infrastructure to secure margin control from crop to finished powder.
Growth Catalysts
- EFSA novel food authorizations:Streamlined pathways for chia and hemp protein commercialization accelerate European market entry timelines for compliant suppliers.
- University athletic programs:Sports nutrition departments now stock pea and rice protein isolates alongside traditional whey, normalizing plant-based recovery protocols among collegiate athletes.
- Wet extraction infrastructure:Industrial-scale enzymatic hydrolysis investments in Germany and Brazil reduce per-unit processing costs for 80%+ protein concentrates.
Market Restraints
- Yellow pea supply concentration:Canadian and Ukrainian crop regions dominate raw material sourcing, exposing processors to weather-driven price volatility and trade disruption.
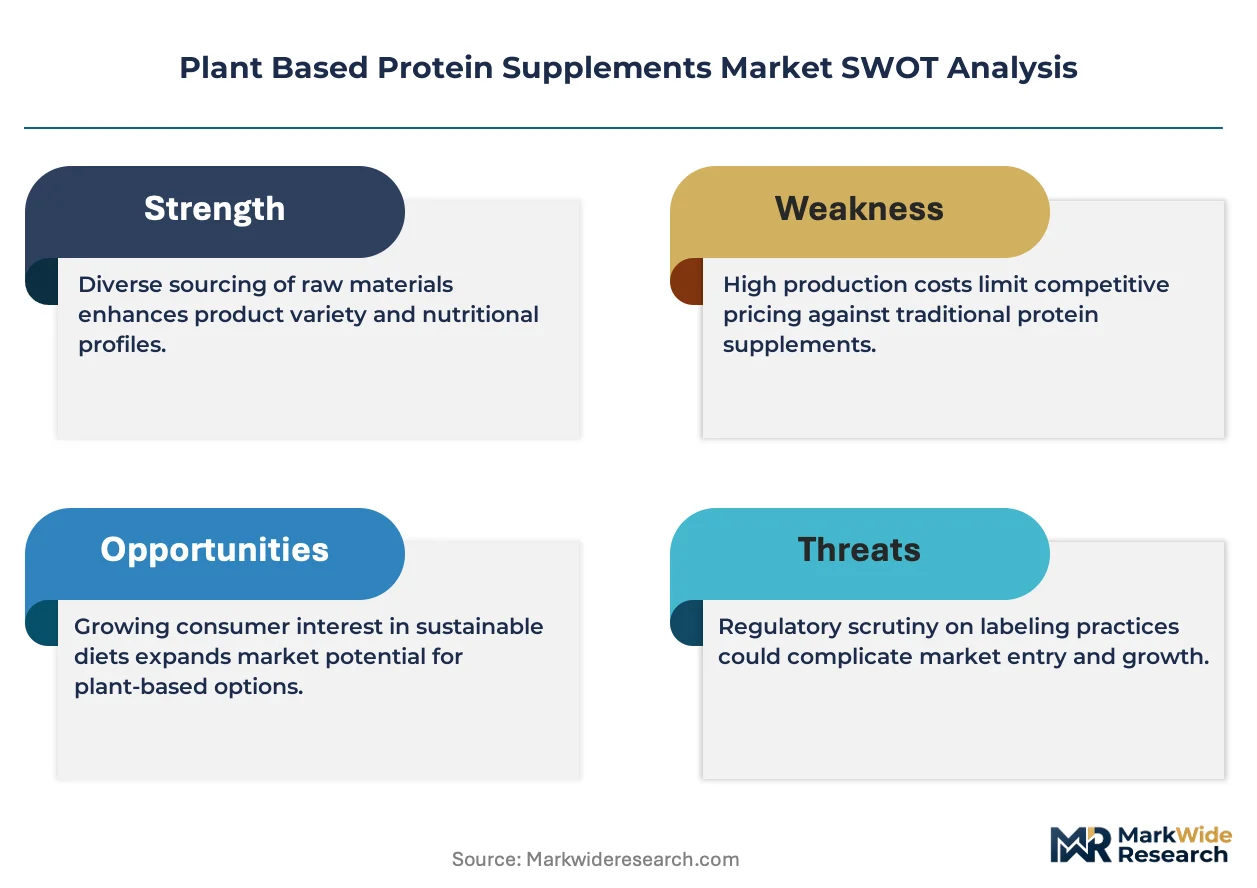
- FDA Current Good Manufacturing Practice compliance:Identity testing and contaminant screening mandates elevate fixed costs for new supplement entrants below viable scale thresholds.
- Whey protein substitution threat:Dairy-derived isolates retain cost advantages in mass-market sports nutrition, limiting plant-based penetration in price-sensitive retail tiers.
Strategic Opportunities
- South Korean functional food integration:Beauty-from-within and senior nutrition product lines underrepresent plant protein fortification relative to regional demand potential.
- Ready-to-drink channel expansion:Convenience retail and foodservice grab-and-go formats capture premium shelf space with higher per-liter margins than bulk powder.
- India FSSAI protein claim harmonization:Tightened verification standards for imported brands create first-mover advantage for domestic manufacturing investment and local certification.
Industry Challenges
- Formulation science talent scarcity:Protein functionality expertise spanning emulsion stability, flavor masking, and amino acid profiling remains concentrated among legacy dairy ingredient scientists.
- Organic certification timeline compression:Three-year transition periods for hemp and chia seed suppliers delay certified product launches and working capital recovery.
- Legacy ERP integration friction:Batch-level traceability requirements for FDA compliance strain older manufacturing execution systems without modular upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Protein Supplements Market |
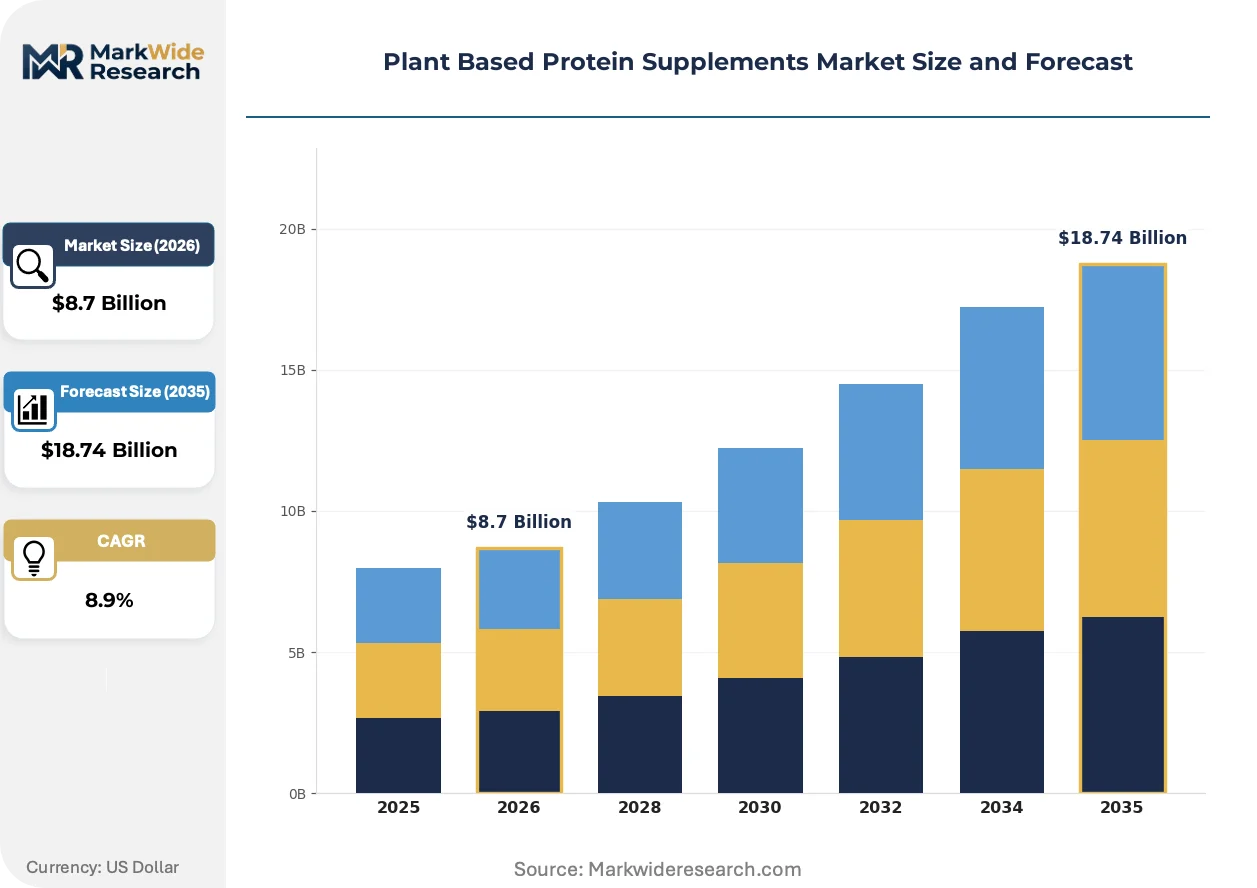
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Rice Protein, Hemp Protein, Soy Protein, Pumpkin Seed Protein, Chia Seed Protein Form: Powder, Ready-to-Drink, Bars, Capsules, Granules, Concentrates Application: Sports Nutrition, Weight Management, Meal Replacement, Clinical Nutrition, Functional Foods, Snack Enhancements End User: Athletes, Fitness Enthusiasts, Elderly, Dietitians, Wellness Centers, Organic Product Consumers |
| Companies Covered | Glanbia plc, Abbott Laboratories, NOW Foods, Danone S.A., IOVATE Health Sciences International, Inc., MusclePharm Corporation, Roquette Frères, Nestlé Health Science, AMCO Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Protein Supplements Market Strategic Shifts & Innovations
Fermentation-derived and precision-processed protein formats are compressing the functional gap between plant and animal-derived nutrition inputs. These advances reshape ingredient sourcing strategies and finished product positioning simultaneously.
Precision fermentation of single-cell proteins is supplanting conventional crop extraction for amino acid completeness in premium formulations. Sports nutrition brands targeting elite athlete segments now specify microbial biomass isolates with leucine profiles matching whey benchmarks. This technology is compressing the historical trade-off between plant origin and muscle protein synthesis efficacy.
REACH and CSRD disclosure requirements in Europe now mandate supply chain carbon intensity reporting for nutrition ingredient imports. Protein processors must document agricultural input emissions and processing energy footprints to maintain retail channel access. Organic and regenerative-certified suppliers capture preferential listing terms as downstream brands scramble for Scope 3 reduction credits.
Direct-to-consumer subscription models now displace brick-and-mortar supplement retail for recurring protein purchases. Millennial and Gen-Z buyers in urban United States clusters favor personalized flavor and protein source curation delivered on 30-day cycles. This channel shift forces legacy brands to rebuild fulfillment infrastructure around micro-fulfillment centers rather than wholesale pallet economics.
Plant Based Protein Supplements Market Segmentation
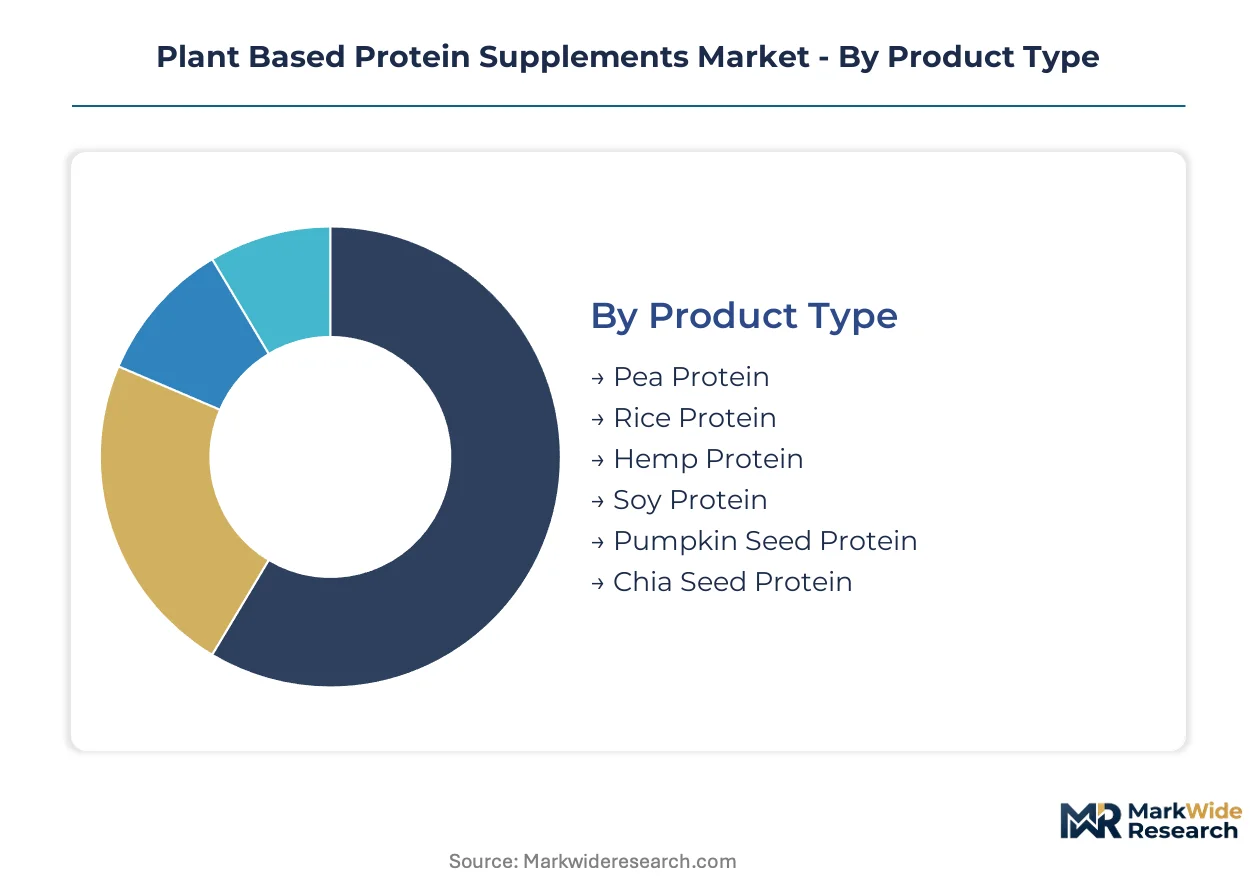
Plant protein supplements fragment across protein source, delivery format, use case, and buyer profile. Each dimension carries distinct margin structures and channel requirements that reshape competitive positioning.
Product Type:
Channel distribution varies sharply by protein source, with commodity-grade isolates flowing through mass retail and specialty concentrates commanding premium placement in sports nutrition.
- Pea Protein:Yellow split pea isolates achieve 80-85% protein content through wet extraction and membrane filtration. German and Brazilian processing facilities concentrate demand from sports nutrition brands seeking cost-competitive whey alternatives.
- Rice Protein:Brown rice protein hydrolysates deliver hypoallergenic amino acid profiles through enzymatic processing. South Korean functional food manufacturers drive import demand for beauty-from-within fortification applications.
- Hemp Protein:Cold-pressed hemp seed cake retains omega fatty acid fractions alongside 50-70% protein content. EFSA novel food authorization timelines constrain European market entry for non-Canadian suppliers.
- Soy Protein:Defatted soy flour concentrates remain the lowest-cost plant protein input for clinical nutrition formulations. India's FSSAI protein claim verification standards increasingly scrutinize soy-based import declarations.
- Pumpkin Seed Protein:Cucurbita pepo seed isolates offer zinc and magnesium mineral co-factors absent in legume alternatives. Organic certification requirements extend lead times for European retail listings.
- Chia Seed Protein:Salvia hispanica meal processing yields protein fractions with mucilage fiber retention. Supply concentration in Paraguay and Argentina exposes processors to South American crop volatility.
Pea protein dominates installed base. Rice protein is where expansion concentrates.
Form:
Cost tier stratification separates bulk commodity powders from convenience-positioned ready formats with per-serving premiums.
- Powder:Spray-dried isolates and concentrates in bulk canisters and single-serve sachets. Direct-to-consumer subscription channels displace brick-and-mortar wholesale for recurring powder purchases in United States urban clusters.
- Ready-to-Drink:Aseptically filled beverages with emulsion-stabilized protein suspensions. Convenience retail and foodservice grab-and-go formats capture shelf space with higher per-liter margins than bulk alternatives.
- Bars:Extruded or cold-pressed protein matrices with binding hydrocolloids. Meal replacement applications concentrate margin pools through premium positioning in airport and gym retail.
- Capsules:Encapsulated protein isolates for clinical nutrition compliance dosing. Hospital-grade formulation standards from Abbott Laboratories anchor credibility that smaller competitors struggle to replicate.
- Granules:Agglomerated protein particles for instant dissolution in hot beverages. Senior nutrition product lines in South Korea underrepresent granule fortification relative to regional demand potential.
- Concentrates:Lower-protein fraction products retaining more native fiber and lipid content. Organic hemp and chia seed concentrates from NOW Foods sustain differentiated positioning through vertically managed supply chains.
Powder formats anchor volume flows. Ready-to-drink applications are climbing the fastest.
Application:
Customer type and margin maturity diverge sharply between performance-oriented segments and price-sensitive functional food entrants.
- Sports Nutrition:Post-workout recovery formulations targeting muscle protein synthesis. University athletic programs in the United States now stock pea and rice isolates alongside traditional whey, normalizing plant-based protocols among collegiate athletes.
- Weight Management:Satiety-optimized protein loads in meal replacement and snack formats. Precision fermentation-derived proteins with leucine profiles matching whey benchmarks reshape efficacy claims in this segment.
- Meal Replacement:Complete macronutrient profiles with vitamin and mineral fortification. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and protein completeness.
- Clinical Nutrition:Hospital and long-term care facility feeding protocols for dairy-allergic patients. FDA Current Good Manufacturing Practice regulations enforce identity testing and contaminant screening that elevates compliance costs.
- Functional Foods:Protein fortification of conventional food products beyond dedicated supplements. Price sensitivity limits penetration as whey retains cost advantages in mass-market retail tiers.
- Snack Enhancements:Protein enrichment of chips, crackers, and baked goods. REACH and CSRD disclosure requirements mandate supply chain carbon intensity reporting for European retail channel access.
Sports nutrition commands premium positioning. Functional foods represent the steepest expansion trajectory.
End User:
Volume concentration and supply requirements split between institutional procurement and fragmented individual consumption.
- Athletes:Elite and competitive performers with performance-validated supplementation protocols. Microbial biomass isolates from precision fermentation now specify leucine benchmarks matching dairy-derived inputs.
- Fitness Enthusiasts:Recreational gym-goers and home workout practitioners. Millennial and Gen-Z buyers favor personalized flavor and protein source curation delivered on 30-day subscription cycles.
- Elderly:Sarcopenia prevention and protein adequacy for aging populations. Senior nutrition product lines in South Korea absorb disproportionate share of new product development investment.
- Dietitians:Clinical practitioners prescribing allergen-free protein interventions. Hospital-grade formulation standards anchor credibility requirements for institutional procurement.
- Wellness Centers:Spa, retreat, and holistic health facility retail operations. Organic and regenerative-certified suppliers capture preferential listing terms for Scope 3 reduction credits.
- Organic Product Consumers:Buyers prioritizing certified inputs and clean label declarations. Three-year transition periods for hemp and chia seed suppliers delay certified product launches and working capital recovery.
Fitness enthusiasts drive recurring purchase volumes. Elderly nutrition is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States buyers favor direct-to-consumer subscription powder formats, while South Korea and Germany concentrate investment in functional food integration and wet extraction infrastructure respectively.
United States
Millennial and Gen-Z fitness enthusiasts in urban clusters drive recurring subscription purchases of personalized protein curation. FDA Current Good Manufacturing Practice regulations enforce identity testing and contaminant screening that elevates compliance costs for new entrants. Greater Los Angeles and New York Metro host micro-fulfillment centers displacing brick-and-mortar wholesale economics.
Germany
Industrial-scale enzymatic hydrolysis investments reduce per-unit processing costs for 80%+ protein concentrates. REACH and CSRD disclosure requirements mandate supply chain carbon intensity reporting for nutrition ingredient imports. Processing facilities in North Rhine-Westphalia concentrate demand from sports nutrition brands seeking cost-competitive whey alternatives.
Brazil
Beauty-from-within and senior nutrition product lines absorb disproportionate share of new product development investment relative to regional demand potential. Wet extraction infrastructure expansion parallels German cost-reduction trajectories. São Paulo anchors import demand for chia and hemp protein fortification applications.
South Korea
Senior nutrition product lines and beauty-from-within formulations underrepresent plant protein fortification relative to regional demand potential. MFDS regulates functional food claims with standards distinct from Western supplement frameworks. Seoul Capital Area hosts disproportionate new product development investment in ready-to-drink and granule formats.
India
FSSAI tightened protein content claim verification for imported supplement brands, reshaping export certification requirements. Domestic manufacturing investment creates first-mover advantage for local certification compliance. Maharashtra and Gujarat concentrate clinical nutrition procurement for hospital-grade formulation standards.
Plant Based Protein Supplements Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in plant protein supplements. Glanbia plc leverages captive pea protein extraction infrastructure to secure margin control from crop to finished powder, while pure-brand marketers rely on toll processing arrangements. Three archetypes dominate: integrated ingredient processors with backward control over supply chains, vertically managed organic specialists, and clinical-grade formulators with hospital procurement relationships. Competitive moves concentrate on capacity expansion in wet extraction infrastructure and strategic partnerships for precision fermentation technology licensing.
Among integrated processors, Glanbia plc exemplifies the captive extraction archetype through its control of pea protein infrastructure from crop sourcing to finished isolate. NOW Foods occupies a differentiated position within the vertically managed organic specialist tier, anchoring supply chain credibility for hemp and chia seed inputs. Abbott Laboratories represents the clinical-grade formulator archetype, with hospital-grade formulation standards that smaller competitors struggle to replicate in institutional procurement channels.
| Leading Market Players |
|---|
| Glanbia plc |
| Abbott Laboratories |
| NOW Foods |
| Danone S.A. |
| IOVATE Health Sciences International, Inc. |
| MusclePharm Corporation |
| Roquette Frères |
| Nestlé Health Science |
| AMCO Proteins |
| Others |
Cost & Logistics Intelligence
EFSA novel food authorizations for chia and hemp protein gate both European market entry timelines and the premium pricing tiers that certified suppliers command over commodity-grade alternatives. This regulatory filter simultaneously constrains supply base qualification and enables price stratification by certification status.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated processors and institutional buyers, while spot purchasing persists for smaller brands lacking volume scale. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein completeness certification and organic status. Cost compression in economy-tier powder formats is intensifying because whey protein retains cost advantages in mass-market sports nutrition. Fitness enthusiasts exhibit highest price sensitivity among end-user segments, whereas clinical nutrition procurement shows lowest elasticity due to formulation compliance requirements.
Supply Chain Analysis
Inventory lead times for organic-certified hemp and chia extend 24-36 months due to mandatory three-year transition periods before harvest qualification. Raw material sourcing concentrates in Canada and Ukraine for yellow pea protein, with Brazil and Germany hosting wet extraction infrastructure for 80%+ protein concentrates. Supply chain risk centers on weather-driven crop volatility in Black Sea region pea production. Distribution runs through direct-to-consumer subscription channels displacing brick-and-mortar wholesale for recurring powder purchases in United States urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is compressing the functional performance gap between plant and animal-derived proteins, creating a regulatory and formulation inflection that rewards early capability investment.
For Market Incumbents: Fortify backward integration into captive pea protein extraction infrastructure to defend margin control against toll-processing competitors. Secure long-term offtake agreements with Canadian and Ukrainian crop suppliers to mitigate weather-driven price volatility exposure. Accelerate precision fermentation licensing partnerships before microbial biomass isolates achieve cost parity with crop-extracted alternatives.
For New Entrants and Emerging Players: Personalized flavor curation and 30-day subscription fulfillment represent service-layer gaps where legacy brands under-serve Millennial and Gen-Z fitness enthusiasts in United States urban clusters. Target South Korean senior nutrition and beauty-from-within product lines for plant protein fortification expansion. Deploy direct-to-consumer micro-fulfillment infrastructure to bypass wholesale channel barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation-derived protein formats, favoring scaled players with R&D amortization capacity. Over the analysis window, vertically managed organic specialists with hemp and chia supply chain control offer acquisition profiles with defensible certification moats. Monitor EFSA novel food authorization timelines as inflection indicators for European market access valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Microbial biomass isolates with leucine profiles matching whey benchmarks reshape efficacy claims. |
| Wet Extraction Capacity Expansion | German and Brazilian facilities reduce per-unit processing costs for 80%+ protein concentrates. |
| Direct-to-Consumer Subscription Launch | Millennial and Gen-Z buyers in Los Angeles and New York Metro favor personalized 30-day cycles. |
| Organic Certification Investment | Three-year transition periods for hemp and chia delay launches but secure premium retail listings. |
| Clinical Nutrition Partnership | Abbott Laboratories anchors hospital-grade credibility that smaller competitors struggle to replicate. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA dietary supplement filings, EFSA novel food authorization databases, and FSSAI protein claim standards. Conversations with sports nutrition formulators, clinical dietitians, procurement managers at university athletic programs, and supply chain directors at integrated ingredient processors informed demand-side validation. Bottom-up volume estimates triangulate against top-down category spending analysis.
Segmentation dimensions modeled span protein source, delivery format, application use case, and end-user profile across the projection horizon. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection timing and technology adoption curves. Forecast inputs incorporate wet extraction capacity buildout schedules and precision fermentation commercialization timelines.
Underlying assumptions cover sustained EFSA authorization streamlining and stable Canadian pea crop yields, with deviation risk concentrated in Black Sea region supply disruption and FDA enforcement intensity variation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Nutraceutical Flexible Packaging Market
Nutritional Supplements
Non-Fish Omega 3 Supplements Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Tongkat Ali Extract Market