
 Lactates Market | 2026-2036
Lactates Market Size, Share, and Industry Trends Forecast 2026-2036
Lactates Market Analysis
ISO 13485 certification for medical device-grade lactates is collapsing the supplier base to firms with validated pharmaceutical quality systems. Corbion leverages its backward integration into fermentation feedstocks to sustain cost leadership across European supply contracts. Galactic anchors its position through specialized calcium lactate production for clinical nutrition, while DSM competes on synthetic biology platforms that reduce batch-to-batch variability.
Lactates are salts and esters of lactic acid, typically produced through carbohydrate fermentation using Lactobacillus strains, with purity grades spanning food additive (E325-E327) to injectable USP/EP pharmacopeia standards; they function primarily as pH regulators, humectants, and mineral delivery vehicles across industrial formulations. Sodium lactate dominates food and beverage applications where its antimicrobial synergy with sodium diacetate preserves processed meat shelf life, while pharmaceutical-grade calcium lactate represents the fastest-expanding margin pool as dialysis and osteoporosis therapies drive specification upgrades. Personal care applications remain mature, with magnesium lactate occupying a niche in sensitive-skin formulations where electrolyte balance claims differentiate premium cosmetic positioning.
FDA 21 CFR Part 184 direct food additive rules and EFSA food enzyme evaluations shape product purity thresholds, while REACH registration requirements for lactic acid derivatives govern market access across European chemical supply chains. Stakeholders must monitor evolving pharmacopeia monograph revisions, as USP and EP alignment on heavy metal limits will determine which fermentation and purification investments retain competitive validity.
Market Dynamics
Pharmaceutical-grade lactate specifications are tightening under pharmacopeia harmonization, compressing the supplier base to fermentation specialists with validated quality systems and backward-integrated feedstock control.
Growth Catalysts
- Dialysis therapy expansion:Rising end-stage renal disease prevalence across aging populations is pulling pharmaceutical-grade calcium lactate into peritoneal dialysis solutions, with EMA MDR compliance requirements accelerating specification upgrades.
- EU F-Gas Regulation:Refrigerant phase-down mandates are redirecting industrial lactate demand toward pH-buffering applications in heat transfer fluids, creating new volume anchors for fermentation-derived salts.
- Processed meat preservation:Sodium lactate's antimicrobial synergy with sodium diacetate is displacing traditional curing agents in North American and European ready-to-eat protein categories, with USDA and EFSA food additive rulings reinforcing clean-label positioning.
Market Restraints
- Corn and sugar feedstock volatility:Lactic acid fermentation economics remain tethered to agricultural commodity cycles, with drought-induced price spikes in Brazilian and US Midwest corn belts compressing producer margins unpredictably.
- Pharmaceutical supply concentration:Injectable-grade lactate production clusters among EU-based fermentation specialists with ISO 13485 certification, creating single-source vulnerability for dialysis and IV solution formulators.
- Citrate substitution in food:Sodium citrate and potassium sorbate blends are capturing cost-sensitive meat preservation contracts, particularly in Latin American and Southeast Asian export processing zones.
Strategic Opportunities
- Clinical nutrition fortification:Magnesium and zinc lactate bioavailability advantages are opening pediatric and geriatric supplement formulations, with ANVISA and Health Canada novel food ingredient pathways enabling faster market entry than FDA GRAS timelines.
- Bioplastics feedstock pivot:Polylactic acid manufacturers are qualifying fermentation-grade lactic acid streams for polymerization, creating demand spillover for lactate salt coproducts in circular carbon accounting frameworks.
- Green chemistry procurement mandates:EU Green Deal sustainable chemistry incentives and US BioPreferred program specifications are tilting public and private procurement toward bio-based pH regulators, favoring fermentation-derived lactates over petrochemical alternatives.
Industry Challenges
- Pharmacopeia alignment complexity:Divergent USP and EP heavy metal limits and endotoxin testing protocols are forcing dual-validation investments, extending certification timelines for multi-regional suppliers.
- Fermentation scale-up bottlenecks:Pharmaceutical-grade production requires dedicated bioreactor trains with validated cleaning protocols, constraining capacity expansion speed for mid-tier producers.
- Quality system integration:Food additive producers seeking pharmaceutical certification face ISPE GMP guideline implementation costs that strain sub-$50M revenue operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactates Market |
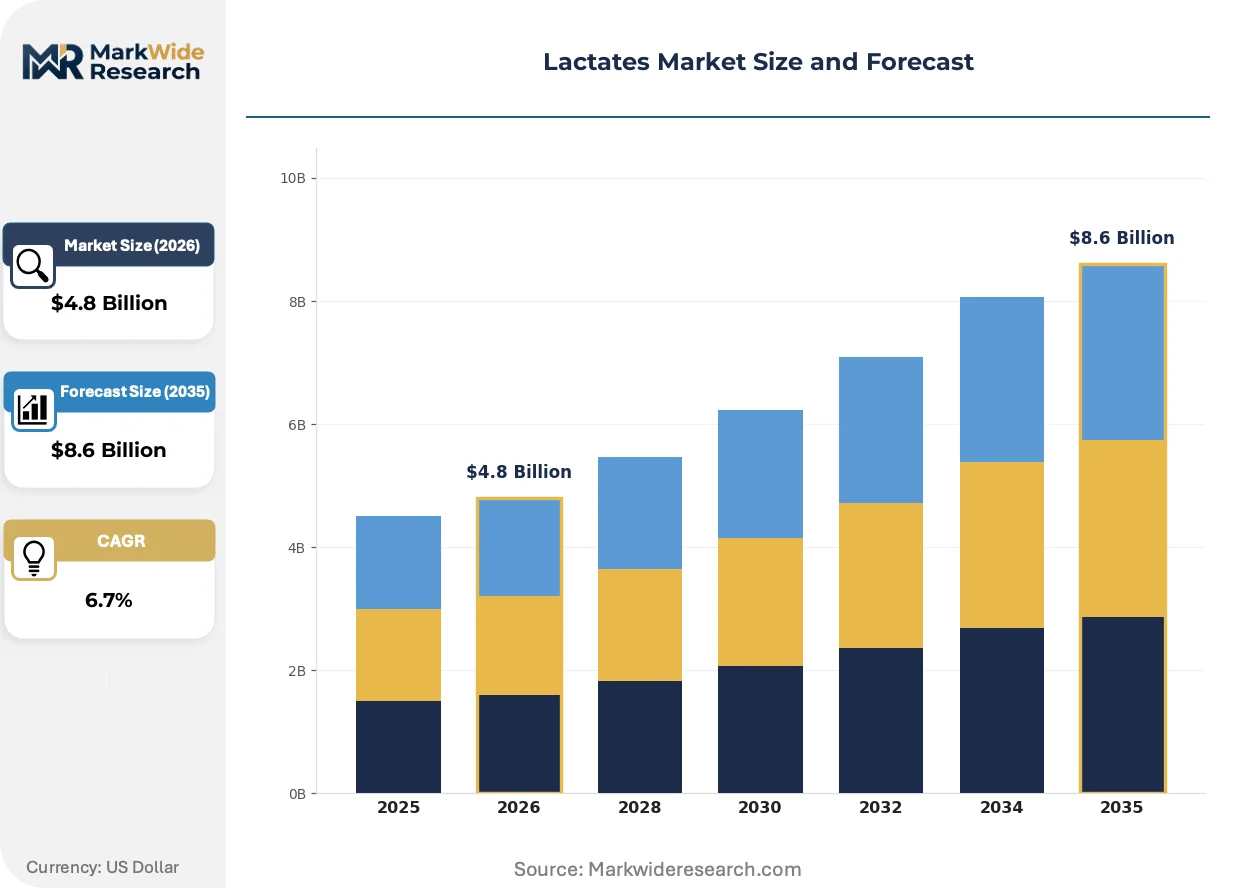
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Lactate, Potassium Lactate, Calcium Lactate, Magnesium Lactate Application: Food & Beverage, Pharmaceutical, Personal Care, Animal Feed End User: Food Manufacturers, Drug Developers, Cosmetic Companies, Livestock Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Corbion, Galactic, Henan Jindan Lactic Acid Technology Co., DSM, DuPont, Bayer AG, Abbott, FBC Industries, BSA Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactates Market Emerging Trajectories
Continuous processing technologies and synthetic biology platforms are reshaping lactate manufacturing economics, while regulatory pharmacopeia convergence and buyer consolidation are restructuring competitive access requirements.
Precision fermentation using CRISPR-optimized Lactobacillus strains is fragmenting traditional batch production paradigms. Synthetic biology specialists are engineering microbial chassis with enhanced lactate tolerance and reduced byproduct formation, enabling single-step conversion from lignocellulosic feedstocks. Pharmaceutical and bioplastics offtakers are piloting these platforms, compressing capital intensity thresholds for new market entrants and eroding the scale advantages of incumbent chemical synthesis operations.
REACH registration requirements for lactic acid derivatives are tightening purity documentation and supply chain transparency obligations. ECHA substance evaluation workflows are extending registration timelines for imported lactate salts, forcing non-EU producers to establish EU-based formulation or tolling partnerships. Medical device and pharmaceutical segments are most affected, with ISO 13485-certified suppliers capturing contract renewals from commodity-grade competitors unable to meet expanded safety data requirements.
Hospital procurement consortiums are consolidating IV solution and dialysis concentrate purchasing, shifting contract structures toward multi-year sole-source agreements with guaranteed volume commitments. Group purchasing organizations in Germany, France, and the United States are displacing fragmented distributor networks, favoring lactate suppliers with integrated logistics and regional warehousing capabilities. This concentration is most visible in German hospital networks, where central purchasing bodies now negotiate directly with fermentation producers for pharmaceutical-grade sodium and calcium lactate supply security.
Lactates Market Segmentation
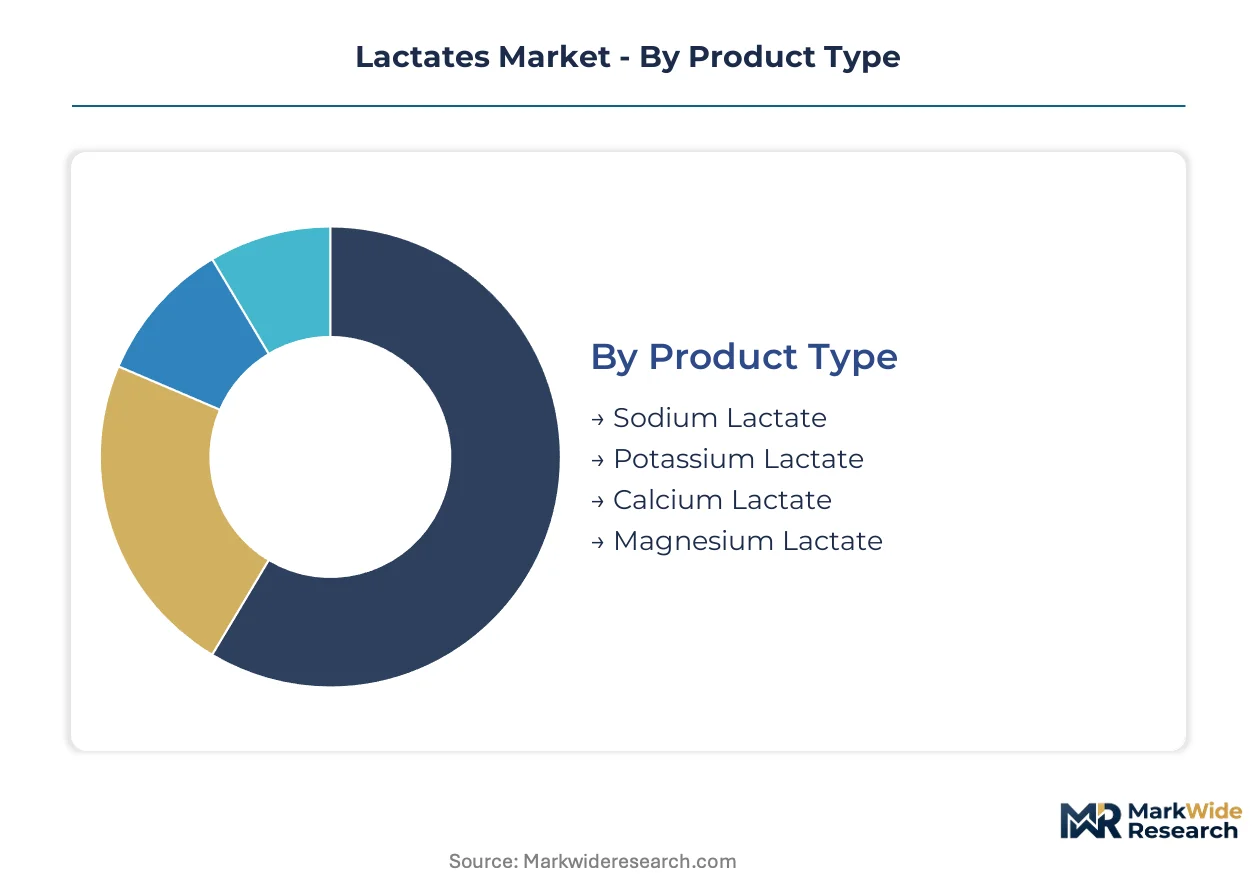
Lactate salts flow through distinct commercial channels governed by purity grades and regulatory certification. Product type determines whether fermentation batches route through food additive distributors or pharmaceutical direct sales contracts.
Product Type:
Sodium lactate and calcium lactate move primarily through direct sales channels to large formulators, while potassium and magnesium variants distribute more heavily through specialty chemical distributors serving mid-tier customers.
- Sodium Lactate:The most widely produced lactate salt, manufactured to FCC and USP/EP grades depending on end-use. Demand concentrates in North American processed meat operations where USDA labeling rules favor its clean-label antimicrobial positioning alongside sodium diacetate.
- Calcium Lactate:Higher-purity pharmaceutical grades dominate peritoneal dialysis and osteoporosis therapy formulations. Dialysis concentrate manufacturers in Germany and the United States are pulling supply through long-term direct procurement agreements with ISO 13485-certified fermentation specialists.
- Potassium Lactate:Functions as a sodium-reduction tool in low-sodium meat preservation, with EFSA and FDA GRAS pathways enabling rapid formulation adoption.
- Magnesium Lactate:Bioavailability advantages position this salt in clinical nutrition and sensitive-skin cosmetic segments, with ANVISA novel food ingredient status accelerating Brazilian market entry.
Sodium lactate dominates installed base. Calcium lactate is where expansion concentrates.
Application:
Application segments stratify sharply by margin structure, with pharmaceutical and personal care commanding premium pricing over commodity food and feed volumes.
- Food & Beverage:Preservation applications in ready-to-eat proteins represent the volume anchor, with sodium lactate antimicrobial synergy displacing traditional curing agents under EFSA and USDA clean-label directives.
- Pharmaceutical:Intravenous solutions and dialysis concentrates require injectable-grade lactates meeting USP and EP heavy metal limits. EMA MDR compliance is compressing the supplier base to firms with validated pharmaceutical quality systems.
- Personal Care:Magnesium lactate occupies a niche in electrolyte-balanced sensitive-skin formulations, though segment maturity limits volume growth.
- Animal Feed:Buffered acidification applications in poultry and swine nutrition operate on thinner margins, with procurement routing through agricultural supply cooperatives.
Food and beverage commands volume leadership. Pharmaceutical applications are climbing the fastest.
End User:
End user concentration patterns mirror certification requirements, with drug developers and food manufacturers consolidating procurement through distinct channel structures.
- Food Manufacturers:Large North American and European protein processors negotiate sodium lactate supply through direct contracts with fermentation producers, bypassing distributor markups at scale.
- Drug Developers:Dialysis solution formulators and IV concentrate manufacturers require ISO 13485-certified suppliers with validated endotoxin testing protocols, creating sole-source dependencies.
- Cosmetic Companies:Premium skincare brands source magnesium lactate through specialty chemical distributors serving smaller batch requirements.
- Livestock Producers:Feed-grade lactate procurement aggregates through agricultural cooperatives and regional feed compounders with limited quality system requirements.
Food manufacturers anchor volume throughput. Drug developers are where margin expansion concentrates.
Distribution Channel:
Channel selection correlates directly with batch size and certification tier, with pharmaceutical grades bypassing wholesale networks entirely.
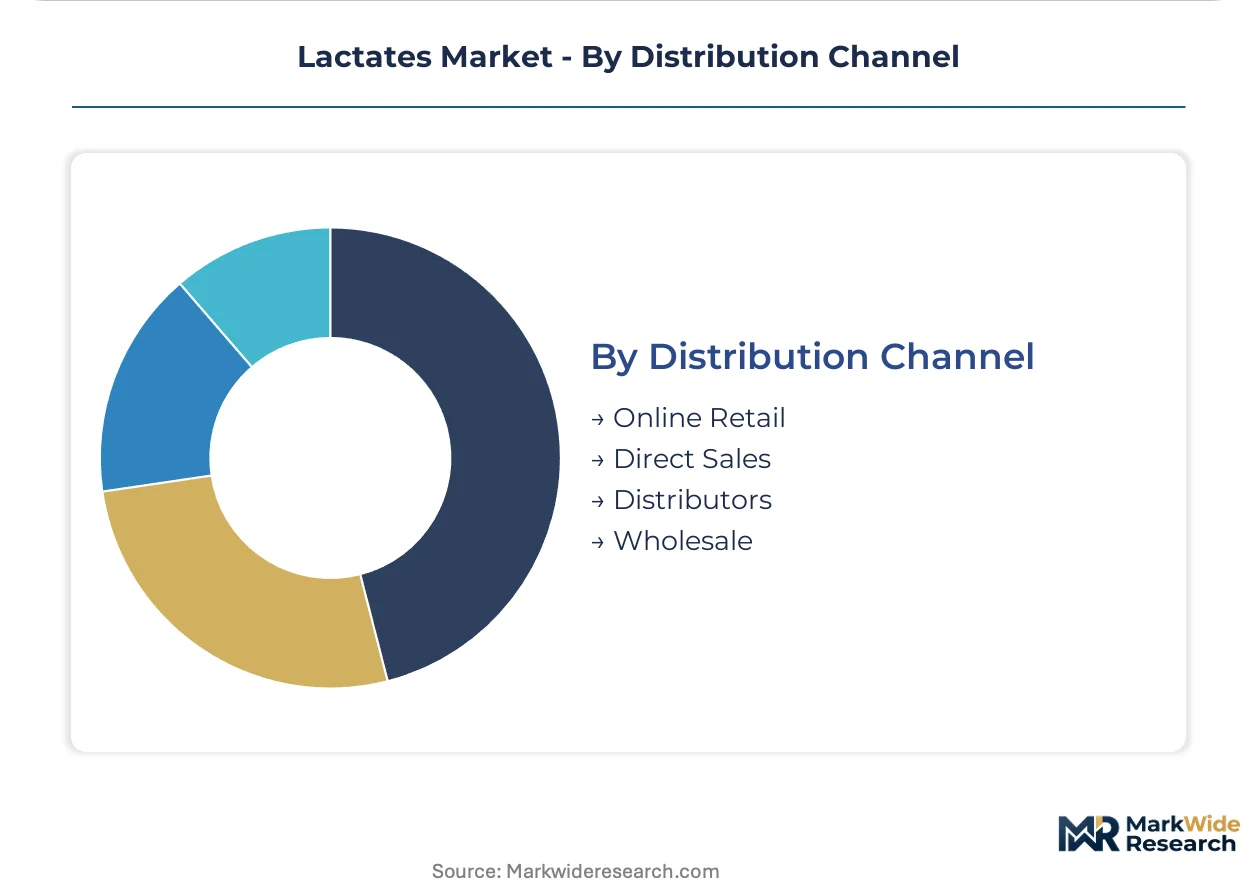
- Direct Sales:Pharmaceutical-grade lactates move exclusively through producer-direct contracts with dialysis concentrate and IV solution manufacturers, with German hospital purchasing consortiums now negotiating multi-year supply security agreements.
- Distributors:Specialty chemical distributors handle mid-volume food additive and personal care grades, with REACH registration documentation requirements filtering out non-EU suppliers without EU-based tolling partnerships.
- Online Retail:Laboratory and small-batch cosmetic ingredient sales operate through B2B platforms serving formulation R&D customers.
- Wholesale:Agricultural feed applications route through regional feed supply cooperatives with minimal quality system overhead.
Direct sales dominate value capture. Distributor channels are where mid-tier volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortiums in Germany and dialysis concentrate manufacturers in the United States anchor pharmaceutical-grade lactate demand, while food additive processors in China and Brazil drive fermentation-grade volume.
United States
Dialysis concentrate formulators and IV solution manufacturers pull pharmaceutical-grade calcium and sodium lactate through multi-year direct procurement agreements. FDA 21 CFR Part 184 food additive rules govern sodium lactate deployment in processed meat preservation. The Midwest corn belt supplies fermentation feedstock to regional producers, though drought volatility periodically compresses producer margins.
Germany
Hospital purchasing consortiums negotiate sole-source supply security agreements for injectable-grade lactates used in peritoneal dialysis solutions. EU F-Gas Regulation refrigerant phase-down mandates redirect industrial lactate demand toward pH-buffering heat transfer fluid applications. Corbion and Galactic maintain significant production infrastructure in the country, anchoring European pharmaceutical-grade supply.
China
Henan Jindan Lactic Acid Technology Co. and domestic fermentation specialists supply food-grade sodium lactate to processed meat export processors. SAMR food safety standards and GB quality specifications shape additive purity thresholds. Yangtze River Delta chemical clusters concentrate tolling partnerships for lactate salt derivatives serving pharmaceutical and personal care formulators.
Brazil
ANVISA novel food ingredient pathways accelerate magnesium and zinc lactate entry into pediatric and geriatric supplement formulations. Agricultural cooperatives aggregate feed-grade lactate procurement for poultry and swine nutrition applications. São Paulo-state food processors leverage sodium lactate antimicrobial synergy in ready-to-eat protein exports to North American and European markets.
India
FSSAI food additive regulations and CDSCO pharmaceutical standards govern lactate salt purity requirements across domestic formulation. Maharashtra and Gujarat chemical corridors host fermentation infrastructure serving regional food and pharmaceutical manufacturers. BIS certification requirements filter supplier access to institutional procurement channels for IV solution and clinical nutrition applications.
Lactates Market Vendor Landscape
Player mix skews toward fermentation specialists with backward-integrated feedstock control and validated pharmaceutical quality systems. The supplier base compresses at the injectable-grade tier where ISO 13485 certification creates entry barriers, while food-grade segments retain more fragmented participation. Three archetypes dominate: EU-based pharmaceutical-grade specialists, Asian fermentation-scale producers, and diversified nutrition ingredient platforms. Competitive moves concentrate on pharmacopeia certification investments and long-term supply security contracting with hospital purchasing consortiums.
Within the pharmaceutical-grade tier, Corbion and Galactic exemplify fermentation specialists leveraging European production infrastructure to capture dialysis and IV solution contracts. DSM occupies a position among diversified nutrition and health ingredient platforms competing on synthetic biology capabilities. Henan Jindan Lactic Acid Technology Co. represents Chinese fermentation-scale producers serving food additive and industrial pH regulator demand through cost-optimized operations.
| Leading Market Players |
|---|
| Corbion |
| Galactic |
| Henan Jindan Lactic Acid Technology Co. |
| DSM |
| DuPont |
| Bayer AG |
| Abbott |
| FBC Industries |
| BSA Food Ingredients |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day pharmaceutical-grade lactate lead times concentrate pricing power with ISO 13485-certified EU fermentation specialists, while food-grade spot markets absorb Midwest corn belt volatility through indexed contract structures. Inventory buffers at German hospital purchasing consortiums insulate dialysis concentrate formulators from feedstock price swings, yet compressed margins in meat preservation applications force sodium lactate buyers toward annual renegotiation cycles.
Pricing Analysis
Cost-plus contracts with corn futures indexation dominate sodium lactate procurement for North American processed meat processors, while pharmaceutical-grade calcium lactate moves through multi-year sole-source agreements with fixed escalators. Price differentiation hinges on USP/EP certification tier and endotoxin testing protocol stringency. Pricing pressure intensifies in food additive segments as Brazilian and Chinese fermentation capacity expands, compressing spot market premiums. Meat preservation formulators exhibit highest price sensitivity, whereas dialysis solution manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
EU F-Gas Regulation compliance bottlenecks constrain pharmaceutical-grade lactate throughput to dedicated bioreactor trains in Germany, the Netherlands, and Belgium. Fermentation economics rest on corn and sugar feedstock availability from the US Midwest and Brazilian agricultural belts. Single-source vulnerability concentrates in injectable-grade sodium lactate, where Corbion and Galactic control validated European capacity. Distribution runs through direct sales contracts for pharmaceutical grades and specialty chemical distributors for food and personal care tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern lactate market access, with pharmacopeia certification interoperability determining supplier viability across EU and US hospital procurement networks. Ecosystem consolidation around ISO 13485-validated quality systems is displacing commodity-grade participants from pharmaceutical value pools.
For Market Incumbents: Secure backward integration into lignocellulosic feedstock streams to buffer margin compression from agricultural commodity cycles. Expand dedicated bioreactor capacity in Germany ahead of EMA MDR compliance deadlines, locking in sole-source contracts with hospital purchasing consortiums before synthetic biology platforms achieve scale. For New Entrants and Emerging Players: Lead with precision fermentation capabilities targeting clinical nutrition fortification, where magnesium and zinc lactate bioavailability claims command premium positioning. ANVISA novel food ingredient pathways in Brazil offer faster regulatory entry than FDA GRAS timelines, enabling geographic beachhead before incumbents consolidate Latin American supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition ingredient platforms with underutilized pharmaceutical-grade fermentation assets. Five-to-ten-year viability favors synthetic biology specialists with CRISPR-optimized Lactobacillus chassis capable of lignocellulosic conversion. Monitor pharmacopeia harmonization progress on heavy metal limits as the inflection signal for which quality system investments retain competitive validity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captive corn and sugar supply insulates margins from drought-induced price spikes in Brazilian and US Midwest growing regions. |
| ISO 13485 Certification Investment | Pharmaceutical-grade validation opens sole-source contracts with German hospital purchasing consortiums for dialysis concentrate supply. |
| Precision Fermentation Scale-Up | CRISPR-optimized Lactobacillus strains reduce batch-to-batch variability and enable lignocellulosic feedstock conversion. |
| Long-term Supply Security Agreement | Multi-year contracts with US dialysis concentrate formulators lock in volume commitments ahead of EMA MDR compliance deadlines. |
| Green Chemistry Procurement Qualification | EU Green Deal and US BioPreferred program specifications favor bio-based lactates in public and private pH regulator tenders. |
Methodological Framework
The analysis maps pharmaceutical-grade, food additive, and industrial lactate tiers, each validated through fermentation plant managers, pharmaceutical procurement leads at dialysis concentrate formulators, and specialty chemical distribution partners. Primary interviews with hospital purchasing consortium contract managers and regulatory affairs directors at EU-based suppliers combined with FDA 21 CFR filings, EMA MDR submission databases, REACH registration documentation, and customs trade flow records. Bottom-up fermentation capacity modeling and top-down end-use demand triangulation anchored volume estimates.
Consistency checks against ACC and Cefic chemical industry benchmarks validated segment-level growth trajectories across the projection horizon. The analytical framework modeled lactate salt type, purity grade tier, end-use application, and regional regulatory cluster dimensions. CAGRs derived from installed base expansion rates and specification upgrade intensity, with corn futures volatility and pharmacopeia alignment timelines as key forecast sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement or accelerated USP/EP harmonization would require recalibration. Forecasts reflect documented assumptions on fermentation yield improvements and hospital procurement consolidation trajectories. Practitioners should keep alternative scenarios live as REACH substance evaluation workflows and synthetic biology platform scale-up timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Dietary Fiber Gummies Market