
 Calcium HMB Market | 2026-2036
Calcium HMB Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium HMB Market Insights
Asset-light contract manufacturing is reconfiguring competitive dynamics in calcium HMB production, allowing mid-sized brands to enter without capital-intensive fermentation facilities. TSI Group Ltd leverages its vertical integration from raw material sourcing to finished powder to sustain margin control. Glanbia Nutritionals anchors its position through global distribution networks spanning sports nutrition and clinical nutrition channels. Zhejiang Yiwan Biotech Co Ltd competes on cost-efficient fermentation scale within China's chemical manufacturing clusters.
Calcium HMB (beta-hydroxy-beta-methylbutyrate calcium salt, CAS 135236-72-5) is a metabolite of leucine produced through microbial fermentation or chemical synthesis, typically standardized to 99% purity for nutritional applications. The compound functions primarily to attenuate proteolysis in skeletal muscle during catabolic stress, serving sports nutrition, clinical rehabilitation, and sarcopenia management markets. Powder formulations dominate production volumes due to bulk ingredient economics and blending flexibility for finished product manufacturers. Sports nutrition applications lead absolute demand, while rehabilitation segments exhibit the fastest trajectory as clinical evidence accumulates for postsurgical recovery protocols. Capsule and tablet formats capture premium positioning among older adults seeking convenient dosing regimens.
US FDA New Dietary Ingredient notifications govern market entry for novel calcium HMB formulations, while China's National Health Commission establishes permitted usage levels and labeling requirements for domestic and exported products. The European Food Safety Authority's health claims framework constrains promotional language around muscle maintenance benefits, shaping product positioning strategies. Stakeholders must monitor evolving clinical trial data and regulatory precedents for structure-function claims across major jurisdictions to anticipate competitive repositioning.
Market Dynamics
Fermentation-based manufacturing scale-up in China's chemical clusters is compressing production economics and forcing Western suppliers to reposition around clinical-grade certification and finished-format innovation rather than bulk powder supply.
Growth Catalysts
- Sarcopenia management protocols:Post-surgical rehabilitation programs in Japan and Germany now incorporate calcium HMB for muscle preservation, expanding the clinical nutrition addressable base beyond sports applications.
- EFSA health claims framework:Approved muscle maintenance claims enable European brands to market directly to aging populations without pharmaceutical positioning, unlocking pharmacy and healthcare practitioner channels.
- Microbial fermentation optimization:Strain engineering advances are raising beta-hydroxy-beta-methylbutyrate yields per fermentation batch, lowering unit costs for calcium salt conversion.
Market Restraints
- Leucine feedstock volatility:Amino acid pricing fluctuations transmit directly to HMB production costs, squeezing margins for non-integrated manufacturers dependent on spot market purchases.
- Single-source fermentation capacity:Zhejiang province hosts disproportionate global beta-hydroxy-beta-methylbutyrate fermentation infrastructure, creating geographic concentration risk for supply continuity.
- Creatine substitution pressure:Established sports nutrition brands with sunk costs in creatine formulations resist adding calcium HMB SKUs despite superior clinical evidence for masters athletes.
Strategic Opportunities
- Clinical nutrition white space:Hospital formulary inclusion for post-ICU muscle wasting represents an underpenetrated channel with higher pricing tolerance than commodity sports powders.
- India's PLI scheme for fermentation:Production-linked incentives for active pharmaceutical ingredients and intermediates could attract contract manufacturing investment for export-oriented HMB supply.
- Capsule convenience formats:Single-serve stick packs and blister-packaged tablets address dosing compliance barriers among sarcopenic adults who reject scoop-and-shake powder preparation.
Industry Challenges
- FDA NDI notification timelines:Novel delivery system or purity-grade submissions face 75-180 day review windows that delay product launches and freeze marketing investment.
- Analytical method standardization:Inconsistent HPLC assay protocols across contract laboratories create batch release disputes between ingredient suppliers and finished goods manufacturers.
- Cross-functional talent scarcity:Fermentation engineering expertise with nutritional regulatory fluency commands premium compensation and retention difficulty in competitive biotech labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium HMB Market |
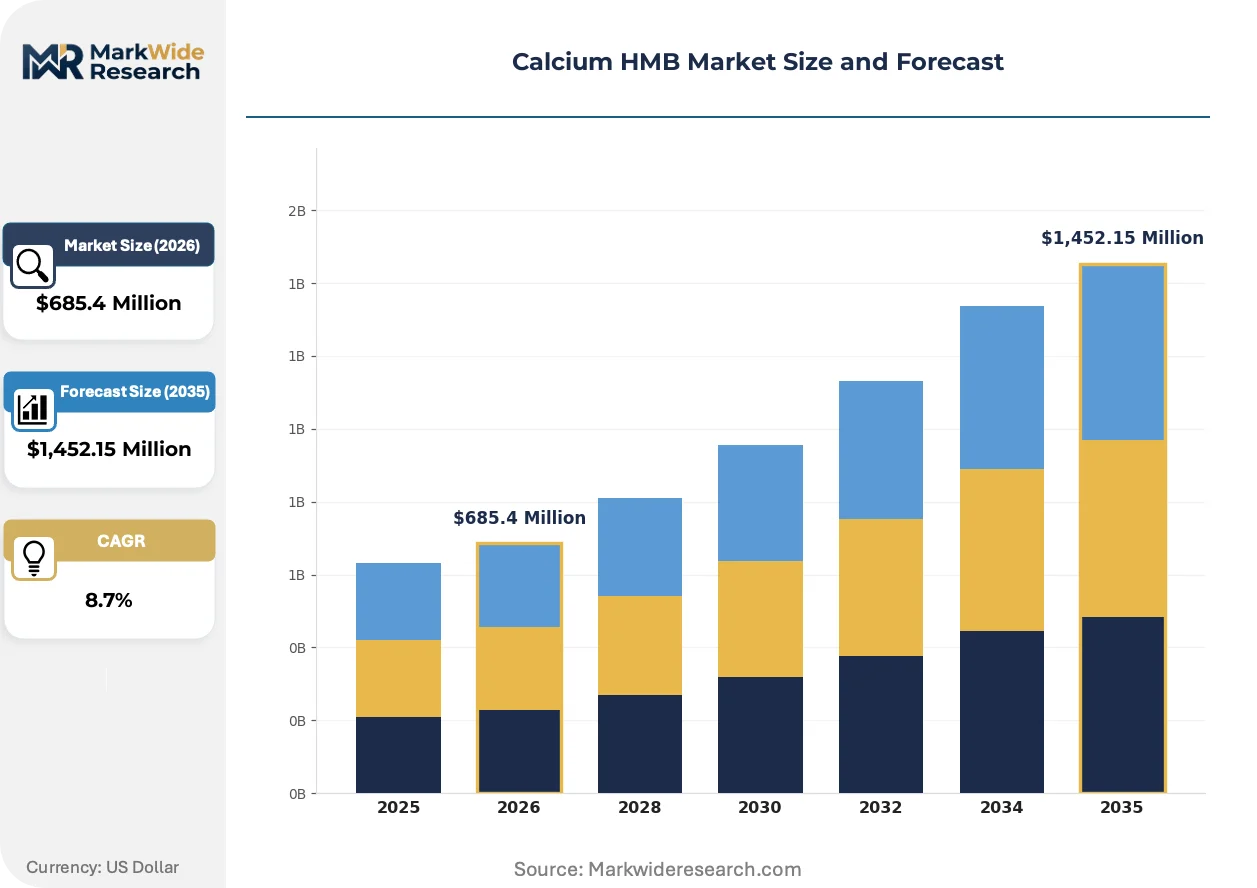
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsules, Tablets, Liquid Application: Sports Nutrition, Dietary Supplements, Muscle Preservation, Rehabilitation End User: Athletes, Bodybuilders, Older Adults, Health-Conscious Consumers Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | TSI Group Ltd, Metabolic Technologies Inc, Abbott Laboratories, Glanbia Nutritionals, Zhejiang Yiwan Biotech Co Ltd, Shijiazhuang Jirong Pharmaceutical Co Ltd, Xi'an Virgin Biotechnology, Lianyungang Shenghe Biotechnology, NutraScience Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium HMB Market Trends and Innovations
Continuous processing technologies and regulatory claim expansions are restructuring how calcium HMB moves from fermentation tanks to consumer packaging, with quality differentiation replacing commodity volume as the primary competitive lever.
Single-use bioreactor systems for microbial HMB production are collapsing capital barriers for mid-scale manufacturers who previously required stainless steel fermentation trains. European and North American entrants now deploy 2,000-5,000 liter disposable vessels for clinical-grade batches, compressing facility investment requirements by 40-60% versus traditional infrastructure. This distributed production model is collapsing the historical advantage of concentrated Asian fermentation capacity.
China's National Health Commission revised permitted usage levels for calcium HMB in foods for special dietary use during 2023, enabling domestic brands to fortify adult nutrition products at clinically relevant doses. The regulatory expansion triggered formulation investment across China's aging-care nutrition sector, with provincial health commissions accelerating local manufacturing license approvals. Exporters must now maintain dual compliance documentation for domestic Chinese and international pharmacopeial specifications.
Masters athletes over 55 now specify third-party NSF Certified for Sport or Informed Sport testing before accepting calcium HMB recommendations from coaches or healthcare providers. This certification-driven purchasing pattern elevates testing costs for brands but creates defensible shelf positioning against untested commodity imports. The behavior shift is most pronounced in Australia and the United Kingdom, where masters cycling and triathlon participation rates concentrate affluent, evidence-demanding consumers.
Calcium HMB Market Segmentation
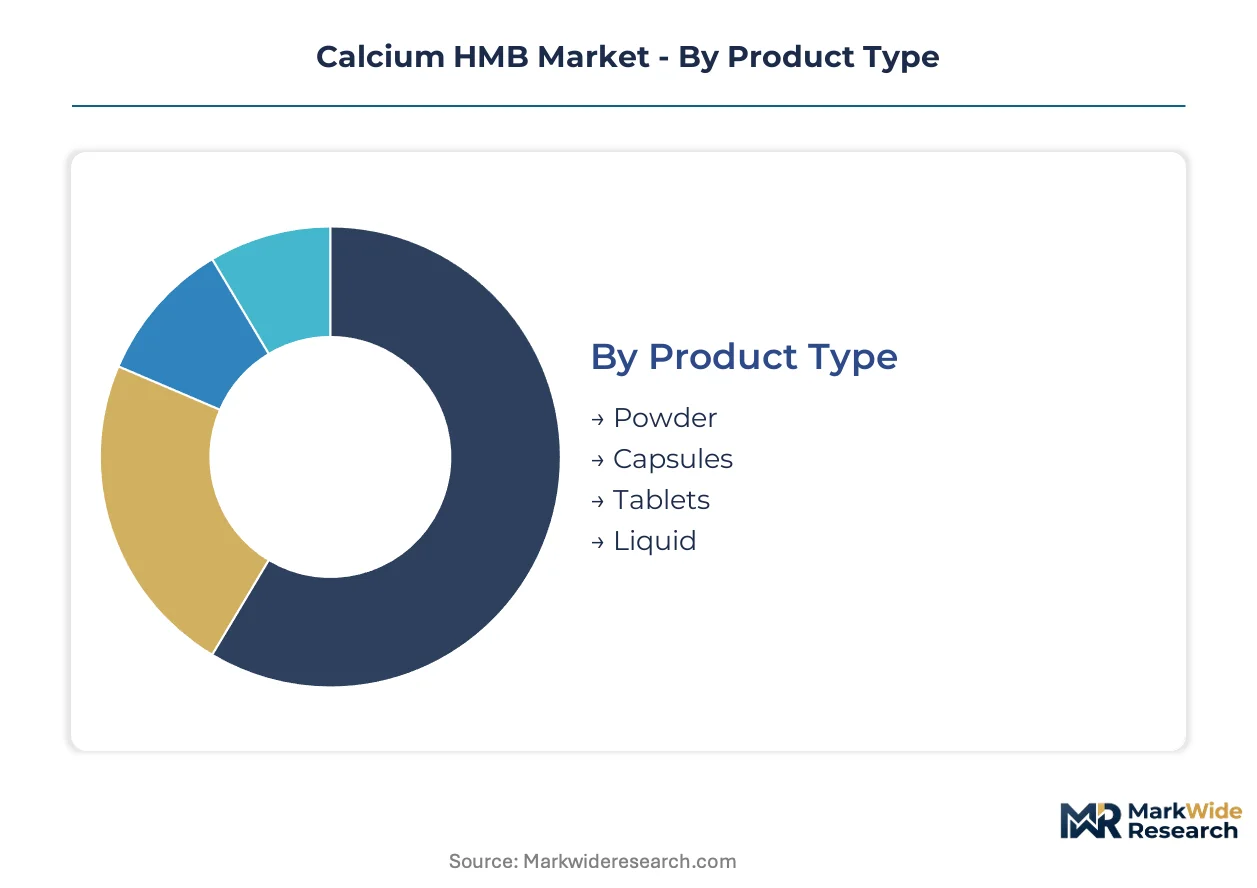
Calcium HMB manufacturers compete across four distinct dimensions that shape formulation priorities, channel economics, and regulatory compliance requirements. Understanding how product formats, applications, user profiles, and distribution pathways intersect determines resource allocation for ingredient suppliers and finished goods brands.
Product Type:
Cost tier differentiation separates commodity bulk supply from value-added delivery systems with dosing convenience premiums.
- Powder:Bulk ingredient economics dominate this segment, with 99% purity calcium HMB salt supplied in 25kg drums for blending into protein formulations. Contract manufacturers in China's Zhejiang province concentrate fermentation capacity here, serving sports nutrition brands with price-sensitive procurement.
- Capsules:Two-piece gelatin or vegetable cellulose shells encapsulate pre-measured 1,000mg doses, addressing compliance barriers among older adults who reject scoop-and-shake preparation. Japan's aging-care nutrition sector drives premium positioning for this format.
- Tablets:Direct compression or wet granulation processes bind calcium HMB with excipients into scored, film-coated doses. Pharmacy channel placement in Germany favors this format for sarcopenia management protocols.
- Liquid:Ready-to-drink suspensions or concentrated shots target immediate post-workout consumption windows. Australia's masters triathlon community shows concentrated demand for portable, no-mix formats.
Powder commands the established base. The steepest expansion runs through capsules.
Application:
Maturity gradients across use cases create divergent margin profiles and evidence requirements for health claims substantiation.
- Sports Nutrition:Protein powder fortification and standalone recovery supplements constitute the volume anchor, with TSI Group and Glanbia Nutritionals anchoring supply to gym-focused brands. EFSA-approved muscle maintenance claims now enable direct-to-consumer positioning without pharmaceutical framing.
- Dietary Supplements:General wellness formulations targeting active aging combine calcium HMB with vitamin D and protein for synergistic muscle support. US FDA New Dietary Ingredient notifications govern novel combination products entering this space.
- Muscle Preservation:Hospital formulary inclusion for post-ICU muscle wasting represents underpenetrated clinical nutrition with higher pricing tolerance than commodity sports powders.
- Rehabilitation:Post-surgical protocols in Japan and Germany now incorporate calcium HMB for muscle preservation during immobilization periods, expanding the addressable base beyond athletic applications.
Sports nutrition maintains the revenue core. Rehabilitation applications are climbing the fastest.
End User:
Customer type segmentation reveals divergent purchasing triggers, from performance optimization to medical necessity.
- Athletes:Masters competitors over 55 now demand third-party NSF Certified for Sport or Informed Sport testing before accepting recommendations, elevating quality assurance costs for brands targeting this cohort.
- Bodybuilders:Leucine metabolite positioning competes against established creatine formulations, with resistance to SKU expansion despite superior clinical evidence for lean mass retention during cutting phases.
- Older Adults:Sarcopenia management drives pharmacy and healthcare practitioner channel expansion, particularly where EFSA health claims enable direct muscle maintenance marketing.
- Health-Conscious Consumers:Preventive wellness positioning attracts premium pricing for convenience formats, with single-serve stick packs addressing compliance barriers among time-constrained professionals.
Athletes anchor current volume. Older adults represent the steepest upward trajectory.
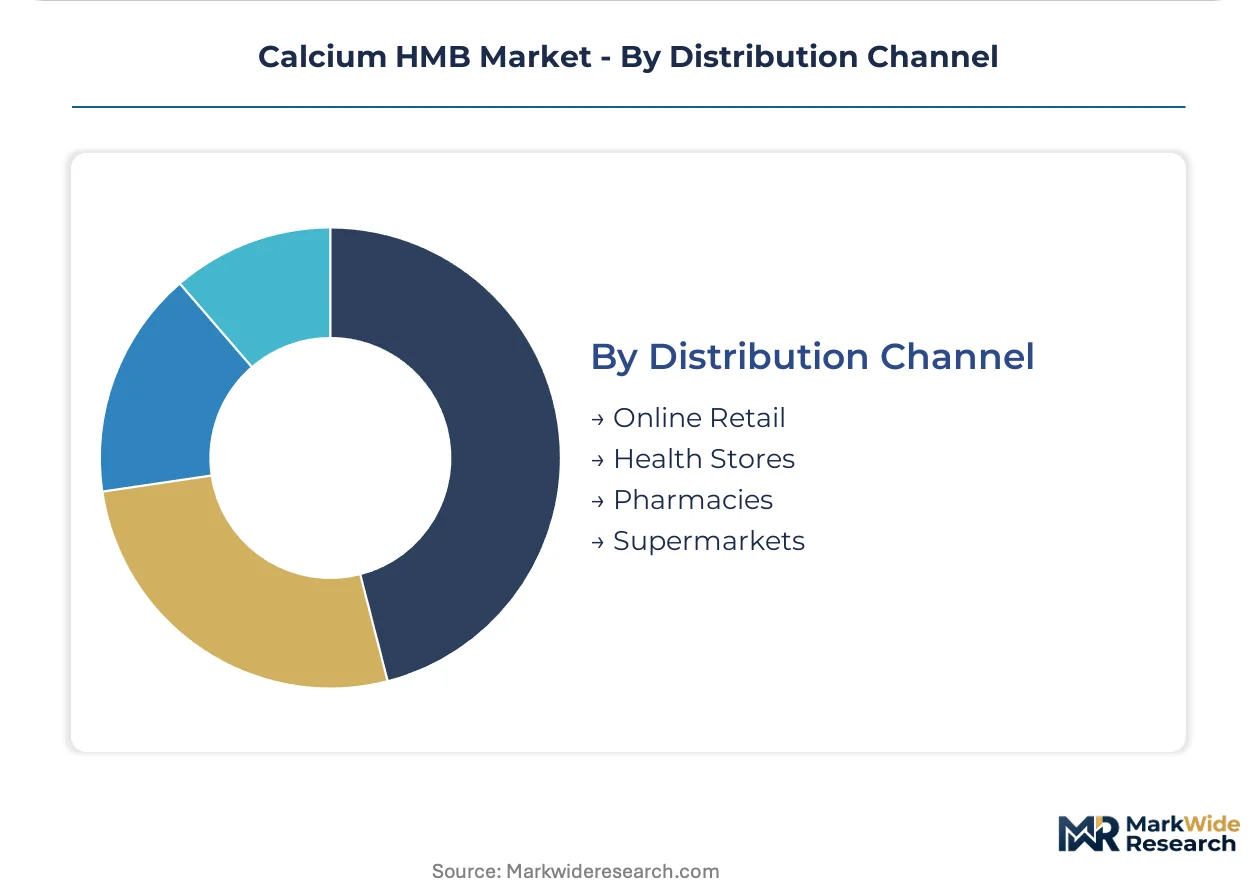
Distribution Channel:
Channel concentration shapes margin capture, with direct-to-consumer platforms compressing traditional retail economics.
- Online Retail:Amazon and specialized sports nutrition platforms dominate volume, with subscription models capturing recurring revenue and reducing customer acquisition costs for challenger brands.
- Health Stores:GNC and Vitamin Shoppe-type retailers provide tactile product evaluation and staff recommendation, though foot traffic erosion pressures this channel's growth outlook.
- Pharmacies:Boots in the UK and CVS in the US increasingly stock calcium HMB adjacent to orthopedic and geriatric care sections, enabled by EFSA and FDA structure-function claim frameworks.
- Supermarkets:Mass-market placement remains limited to combination protein products, with standalone calcium HMB SKUs rare outside China's domestic aging-care nutrition sector.
Online retail commands transaction volume. Pharmacy placement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation clusters extract cost premiums from Western brands, while US and European suppliers defend position through clinical-grade certification and finished-format innovation rather than bulk powder competition.
United States
Masters athletes over 55 now demand third-party NSF Certified for Sport testing before accepting calcium HMB recommendations from coaches or healthcare providers. The FDA's New Dietary Ingredient notification pathway governs market entry timelines for novel formulations, with 75-180 day review windows shaping product launch schedules. Greater Boston and San Diego biotech corridors host contract manufacturers deploying single-use bioreactor systems for clinical-grade batches.
China
Domestic manufacturers scale fermentation-based production of beta-hydroxy-beta-methylbutyrate calcium salts to serve both local aging-care nutrition demand and export markets. The National Health Commission revised permitted usage levels for calcium HMB in foods for special dietary use during 2023, enabling clinically relevant dosing in adult nutrition products. Zhejiang province's chemical manufacturing clusters concentrate disproportionate global fermentation infrastructure, creating geographic concentration risk for supply continuity.
Germany
Post-surgical rehabilitation programs now incorporate calcium HMB for muscle preservation during immobilization periods, expanding the clinical nutrition addressable base beyond athletic applications. EFSA's approved muscle maintenance claims enable direct-to-consumer positioning without pharmaceutical framing, unlocking pharmacy and healthcare practitioner channels. The Rhine-Ruhr industrial region anchors distribution logistics for European sports nutrition and clinical nutrition supply chains.
Japan
Sarcopenia management protocols drive pharmacy channel expansion for capsule-format calcium HMB targeting older adults who reject scoop-and-shake powder preparation. METI oversees industrial policy for fermentation-based ingredient manufacturing, with production-linked incentives attracting investment in microbial strain engineering. The Kanto region around Tokyo concentrates aging-care nutrition formulation and packaging operations for domestic and export markets.
Australia
Masters triathlon and cycling communities show concentrated demand for portable, no-mix liquid formats targeting immediate post-workout consumption windows. The TGA regulates therapeutic claims for muscle preservation products, with structure-function claim frameworks shaping promotional language strategies. Sydney and Melbourne host specialized sports nutrition platforms and subscription-model direct-to-consumer brands capturing recurring revenue.
Calcium HMB Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation and raw material supply. The vendor base organizes around three tiers: multinational nutrition conglomerates with global distribution networks, mid-sized contract manufacturers with asset-light fermentation capacity, and regional Chinese suppliers competing on cost-efficient scale. Strategic moves concentrate on backward integration into captive fermentation supply and geographic diversification of production to reduce Zhejiang concentration risk.
Among vertically integrated specialists, TSI Group Ltd exemplifies the archetype of raw-material-to-finished-powder control, while Glanbia Nutritionals anchors multinational network coverage across sports and clinical channels. Zhejiang Yiwan Biotech Co Ltd represents the cost-driven fermentation scale model within China's chemical clusters. These three patterns—integration, distribution breadth, and manufacturing scale—define competitive positioning across price-sensitive bulk supply and premium certified-product segments.
| Leading Market Players |
|---|
| TSI Group Ltd |
| Metabolic Technologies Inc |
| Abbott Laboratories |
| Glanbia Nutritionals |
| Zhejiang Yiwan Biotech Co Ltd |
| Shijiazhuang Jirong Pharmaceutical Co Ltd |
| Xi'an Virgin Biotechnology |
| Lianyungang Shenghe Biotechnology |
| NutraScience Labs |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's single-source fermentation concentration exposes Western brands to tariff escalation and supply interruption risks that compress bulk powder margins while widening certified-product premiums. This geographic chokepoint simultaneously forces pricing stratification across commodity, clinical-grade, and third-party-tested tiers and drives contract manufacturers toward asset-light single-use bioreactor systems that redistribute production geography.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for bulk powder procurement, with price differentiation resting on certification grade and volume scale. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport batches from pharmacopeial-grade and commodity fermentation outputs. Pricing pressure stems from Chinese manufacturers scaling fermentation capacity and compressing export quotes for 25kg drum supply. Sports nutrition brands exhibit highest price sensitivity, while hospital formulary procurement demonstrates lowest sensitivity due to clinical protocol adherence requirements.
Supply Chain Analysis
Leucine feedstock quality and microbial strain performance determine upstream cost structures for beta-hydroxy-beta-methylbutyrate calcium salt production. Supply concentrates in China, with secondary fermentation capacity emerging in India and contract manufacturing developing in the United States. Raw material dependencies center on pharmaceutical-grade leucine, fermentation nutrients, and calcium carbonate for salt conversion. Single-source vulnerability in Zhejiang chemical clusters creates geographic concentration risk for supply continuity. Distribution runs through ingredient suppliers to finished goods manufacturers, then through online retail and pharmacy channels to end consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium HMB market economics are shifting from commodity bulk supply toward platform-mediated quality verification, with third-party certification ecosystems and subscription-based direct-to-consumer channels reconfiguring how value is captured and defended.
For Market Incumbents: Pre-empt creatine substitution pressure by securing exclusive pharmacy formulary placements for post-surgical rehabilitation protocols in Germany and Japan. Deepen backward integration into captive leucine supply or strain engineering capabilities to insulate margins from feedstock volatility and Zhejiang concentration risk.
For New Entrants and Emerging Players: Establish a beachhead in India's production-linked incentive zones for fermentation-based active pharmaceutical ingredients and intermediates. Target hospital formulary inclusion for post-ICU muscle wasting as the most penetrable clinical segment, deploying single-use bioreactor systems to bypass capital barriers of traditional stainless steel infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with regulatory fluency across FDA, EFSA, and China's National Health Commission frameworks. Acquisition targets should demonstrate captive fermentation supply and finished-format innovation capabilities. Watch for India's PLI scheme attracting contract manufacturing investment as an inflection signal for supply chain diversification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Engineering | Captive microbial strain development at Metabolic Technologies insulates against leucine feedstock price transmission. |
| Third-Party Certification Program | NSF Certified for Sport positioning enables premium pricing among masters athletes in Australia and the United Kingdom. |
| Hospital Formulary Partnership | Post-surgical rehabilitation protocol inclusion in German pharmacy channels unlocks higher-margin clinical nutrition demand. |
| Single-Use Bioreactor Deployment | Disposable vessel systems in Greater Boston and San Diego corridors compress facility investment requirements for clinical-grade batches. |
| Regulatory Dual-Compliance Documentation | Simultaneous National Health Commission and pharmacopeial specification maintenance enables China domestic and export market access. |
Research Methodology
Desk research of FDA New Dietary Ingredient notifications, EFSA health claims registers, and China's National Health Commission permitted usage level revisions preceded structured interviews with fermentation engineering directors, sports nutrition brand procurement leads, hospital formulary committee members, and contract manufacturing executives. Secondary validation drew from customs trade data, SEC 10-K filings of listed nutrition conglomerates, and pharmacopeial specification databases. Bottom-up volume modeling triangulated against top-down market sizing across the projection horizon.
Assumptions held fixed include regulatory claim frameworks across major jurisdictions and microbial fermentation yield trajectories from current strain engineering advances; variables stress-tested encompass leucine feedstock pricing bands, tariff rate scenarios, and single-source supply disruption probabilities. The analytical framework segmented by product format, application use case, end-user archetype, and distribution channel, with CAGRs derived from adoption curve modeling and pricing tier trajectories. Industry-specific forecast inputs included masters athlete participation rates and hospital formulary inclusion timelines for sarcopenia management protocols.
Stress conditions across leucine commodity volatility, Zhejiang infrastructure concentration, and FDA NDI review timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor sensitivities. Cross-checking against hospital procurement database benchmarks and third-party certification enrollment trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market