
 Latin America Herbal Supplements Market | 2026-2036
Latin America Herbal Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Herbal Supplements Market Intelligence
Multi-source botanical sourcing is rebalancing toward vertically integrated supply chains across the Andes and Atlantic Forest biomes. Herbalife International of America Inc. anchors its Latin American operations through captive cultivation partnerships in Brazil. Himalaya Global Holdings Ltd. leverages Ayurvedic extraction protocols to differentiate in the capsules and powders segments. Amway International Inc. competes through direct-to-consumer channel control spanning Mexico City to Buenos Aires.
Latin America herbal supplements comprise standardized phytochemical preparations derived from native and imported botanicals, typically processed through solvent extraction, spray-drying, or cold-pressing to achieve defined marker compound concentrations for therapeutic or preventive use. The powders and capsules categories dominate volume due to shelf stability and dosing precision preferred by retail consumers, while tinctures command premium positioning among health practitioners seeking rapid bioavailability. Immune support applications lead absolute demand following sustained consumer prioritization of preventive health, though digestive health formulations sustain deeper margin pools through practitioner-directed channels requiring clinical substantiation.
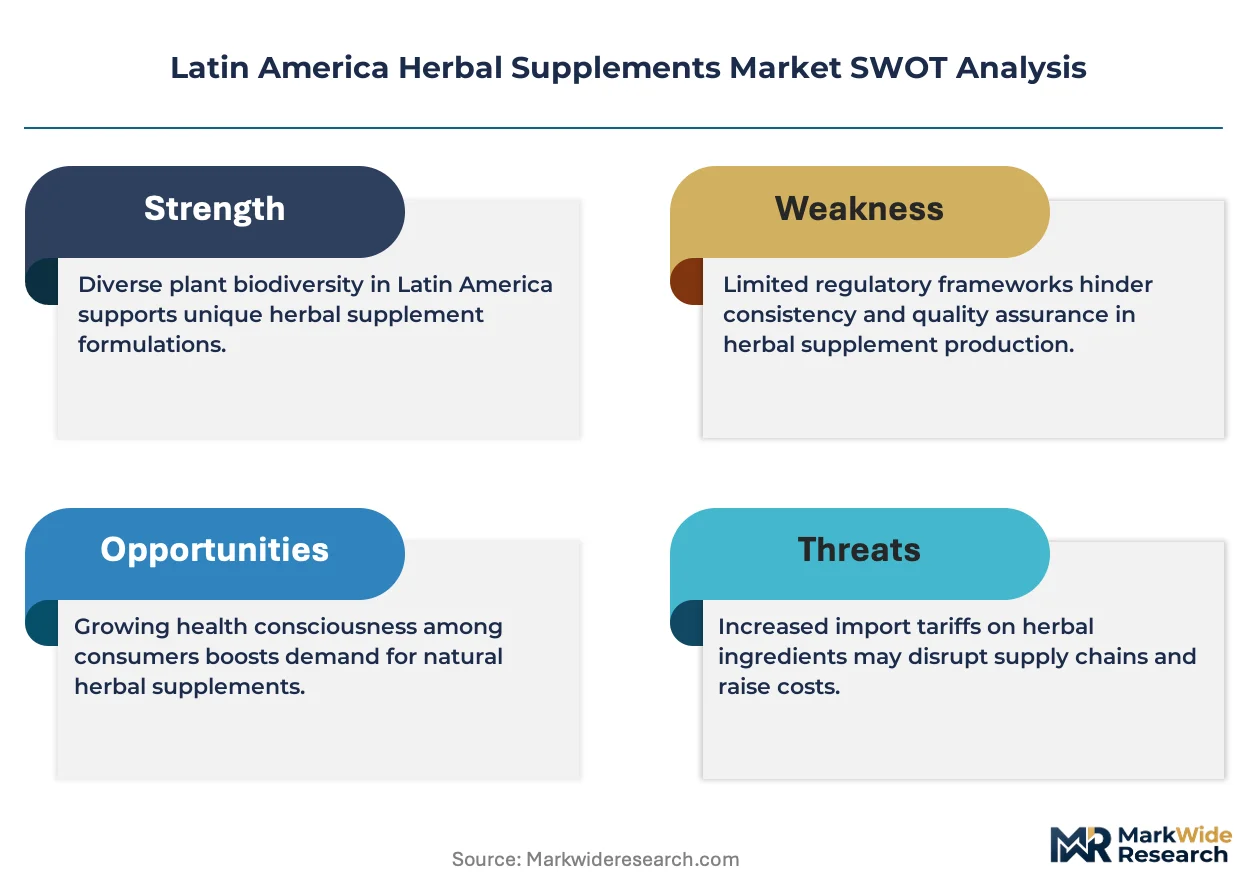
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce divergent purity and labeling standards that fragment registration costs and delay cross-border product launches. Brazil's updated supplement registry mandates heavy metal testing and botanical authentication through chromatographic fingerprinting, raising compliance barriers for imported raw materials. Stakeholders must monitor regulatory harmonization negotiations across Mercosur and the Pacific Alliance to anticipate whether unified standards will consolidate market access or preserve national technical barriers.
Market Dynamics
ANVISA's updated supplement registration pathways are compressing time-to-market for domestic Brazilian manufacturers while raising chromatographic fingerprinting barriers for imported raw materials, fundamentally restructuring competitive access.
Growth Catalysts
- Practitioner-directed digestive health channels:Clinical substantiation requirements create margin pools that reward manufacturers with in-house extraction protocols and Andean sourcing partnerships.
- COFEPRIS streamlined botanical registration:Mexico's national pharmaceutical regulator reduced documentation burdens for standardized extracts, accelerating cross-border launches from Brazilian suppliers.
- São Paulo distribution infrastructure:Southeastern Brazil's logistics clustering enables same-day replenishment to wellness centers, anchoring national adoption velocity.
Market Restraints
- Heavy metal testing mandates:ANVISA's updated supplement registry imposes atomic absorption spectroscopy costs that disproportionately burden small importers of Asian raw materials.
- Atlantic Forest biome concentration:Vertically integrated cultivation partnerships cluster in Brazil's coastal zones, exposing supply continuity to climate volatility and land-use restrictions.
- Substitution by synthetic nutraceuticals:Fermented L-theanine and lab-synthesized curcuminoids undercut price positioning of botanical extracts in mass-market capsules.
Strategic Opportunities
- Colombian practitioner channel underpenetration:INVIMA's pending harmonization with Pacific Alliance standards creates first-mover positioning for Brazilian exporters with existing chromatographic documentation.
- Ayurvedic-protocol convergence:Cold-pressing extraction methods from Indian pharmacopeias are merging with Andean maca processing, opening hybrid positioning in premium powders.
- Direct-to-clinic distribution:Bypassing pharmacy retail through nutritionist office dispensing captures margin compression from São Paulo's wholesale concentration.
Industry Challenges
- Chromatographic fingerprinting expertise scarcity:ANVISA's authentication requirements demand analytical chemists trained in HPLC-UV methods, a skill set concentrated in São Paulo and Porto Alegre laboratories.
- Multi-regulator compliance synchronization:Simultaneous navigation of ANVISA heavy metal rules, COFEPRIS stability testing, and INVIMA labeling formats fragments product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Herbal Supplements Market |
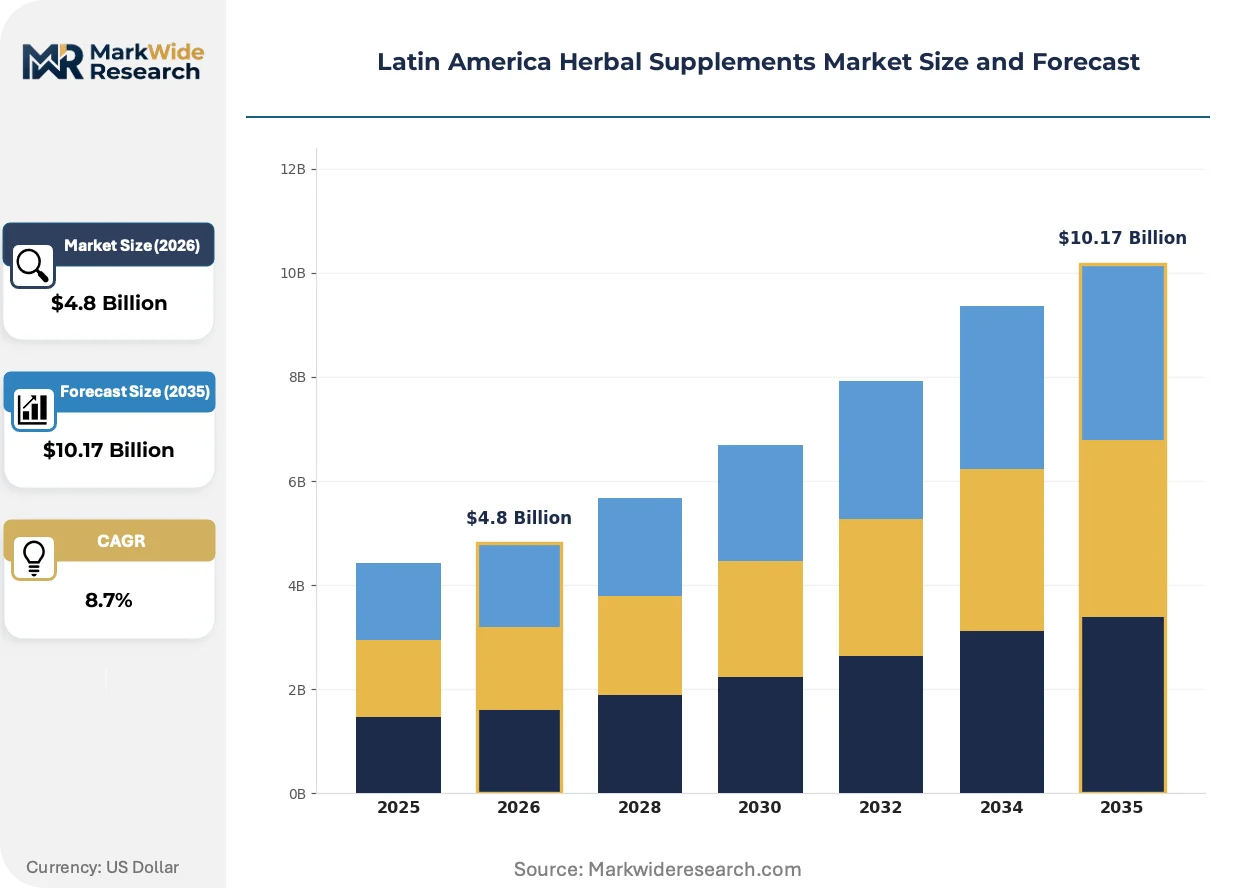
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powders, Teas, Tinctures End User: Retail Consumers, Health Practitioners, Pharmacies, Wellness Centers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Application: Weight Loss, Immune Support, Digestive Health, Vitality |
| Companies Covered | Amway International Inc., Herbalife International of America Inc., GNC Holdings Inc, Natulab Laboratório S/A, Now Health Group Inc., The Nature's Bounty Co., Sanofi SA, Himalaya Global Holdings Ltd., Bayer AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Herbal Supplements Market Strategic Shifts & Innovations
Extraction technology standardization and regulatory documentation automation are compressing the gap between artisanal botanical processing and pharmaceutical-grade manufacturing protocols across the region.
Spray-drying technology with in-line particle size monitoring is consolidating quality variance in powdered extracts. Mid-sized Brazilian processors deploy this equipment to meet ANVISA's batch-to-batch consistency mandates. The technology is consolidating formerly fragmented toll-manufacturing relationships into captive production networks.
COFEPRIS introduced blockchain-traceable botanical certificates for imports from non-Mercosur origins, effective across Mexican port-of-entry inspections. This creates documentation friction for Peruvian maca suppliers while benefiting Brazilian vertically integrated cultivators with existing chain-of-custody systems. Tincture manufacturers targeting Mexico City practitioner offices face the steepest compliance recalibration.
Wellness center procurement now demands certificate-of-analysis transparency prior to shelf placement, displacing traditional wholesale opacity. São Paulo's southeastern distribution hubs enforce this standard through buyer consortiums. Argentine wellness chains lag this shift, creating geographic asymmetry in supplier qualification intensity.
Latin America Herbal Supplements Market Segmentation
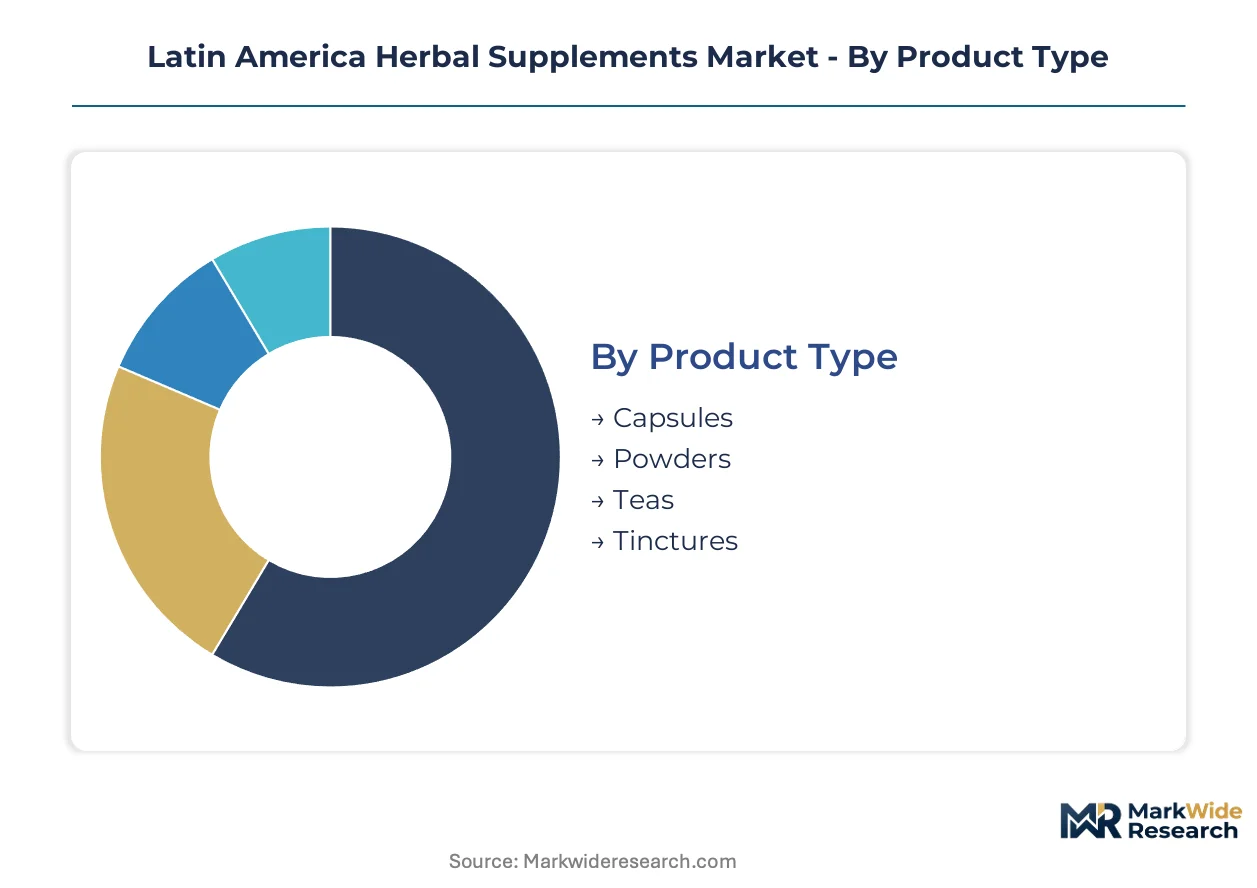
Segmentation in Latin America herbal supplements reveals how regulatory compliance costs and distribution infrastructure shape competitive access. Product form factors determine shelf stability requirements and registration pathways under ANVISA protocols. End-user channel preferences concentrate demand in São Paulo's wellness center clusters and Mexico City's practitioner networks.
Product Type:
Powders dominate absolute volume through cost-efficient production and bulk dispensing flexibility, while capsules capture premium positioning via dosing precision and retail shelf appeal.
- Capsules:Gelatin or vegetable-based shells containing standardized botanical powders with defined marker compound concentrations. São Paulo's distribution infrastructure favors this format for pharmacy retail channels requiring tamper-evident packaging and batch-level traceability documentation.
- Powders:Spray-dried or mechanically milled botanical preparations with particle size control for dissolution consistency. Wellness centers across Brazil's southeastern states specify this format for customized blending protocols and practitioner-directed dosing regimens.
- Teas:Whole-leaf or cut-and-sifted botanical materials in filter bags or loose preparation. Argentine retail consumers favor traditional yerba mate adjacents.
- Tinctures:Hydroalcoholic extracts with defined extraction ratios preserved in amber glass. Health practitioners in Mexico City premium channels specify rapid bioavailability applications.
Today's leader: Powders. Tomorrow's challenger: Capsules.
End User:
Channel control determines margin capture, with practitioner-directed sales commanding documentation premiums and retail mass-market emphasizing volume throughput.
- Wellness Centers:Facility-based dispensing integrating nutritional consultation with botanical protocol design. Brazil's southeastern clusters anchor national adoption velocity through same-day replenishment from São Paulo distribution hubs.
- Retail Consumers:Self-directed purchasers through pharmacy, supermarket, and online channels. Mexico's COFEPRIS streamlined registration accelerates cross-border product availability for standardized extract formats.
- Health Practitioners:Licensed nutritionists and integrative medicine clinicians prescribing condition-specific protocols. Colombian channels remain underpenetrated pending INVIMA harmonization with Pacific Alliance standards.
- Pharmacies:Regulated retail with pharmacist oversight and prescription-adjacent positioning. ANVISA heavy metal testing mandates raise compliance barriers for imported raw material suppliers.
Wellness centers command margin depth. Retail consumers deliver volume scale.
Distribution Channel:
Geographic reach versus relationship intensity defines channel economics, with digital platforms compressing information asymmetry and specialty retail preserving qualification premiums.
- Online Retail:Direct-to-consumer platforms with certificate-of-analysis transparency requirements. São Paulo buyer consortiums enforce documentation standards displacing traditional wholesale opacity.
- Specialty Stores:Health-focused retailers with trained staff and practitioner referral networks. Brazilian captive cultivation partnerships secure preferential shelf placement through chain-of-custody verification.
- Supermarkets:Mass-market retail with high-velocity turnover and price-sensitive positioning. Synthetic nutraceutical substitution pressures botanical extract margins in this channel.
- Health Food Shops:Independent retailers emphasizing organic certification and local sourcing narratives. Argentine chains lag São Paulo's transparency standards.
Specialty stores hold relationship value. Online retail captures expansion trajectory.
Application:
Preventive versus therapeutic positioning determines clinical substantiation requirements and corresponding margin architecture across regulatory jurisdictions.
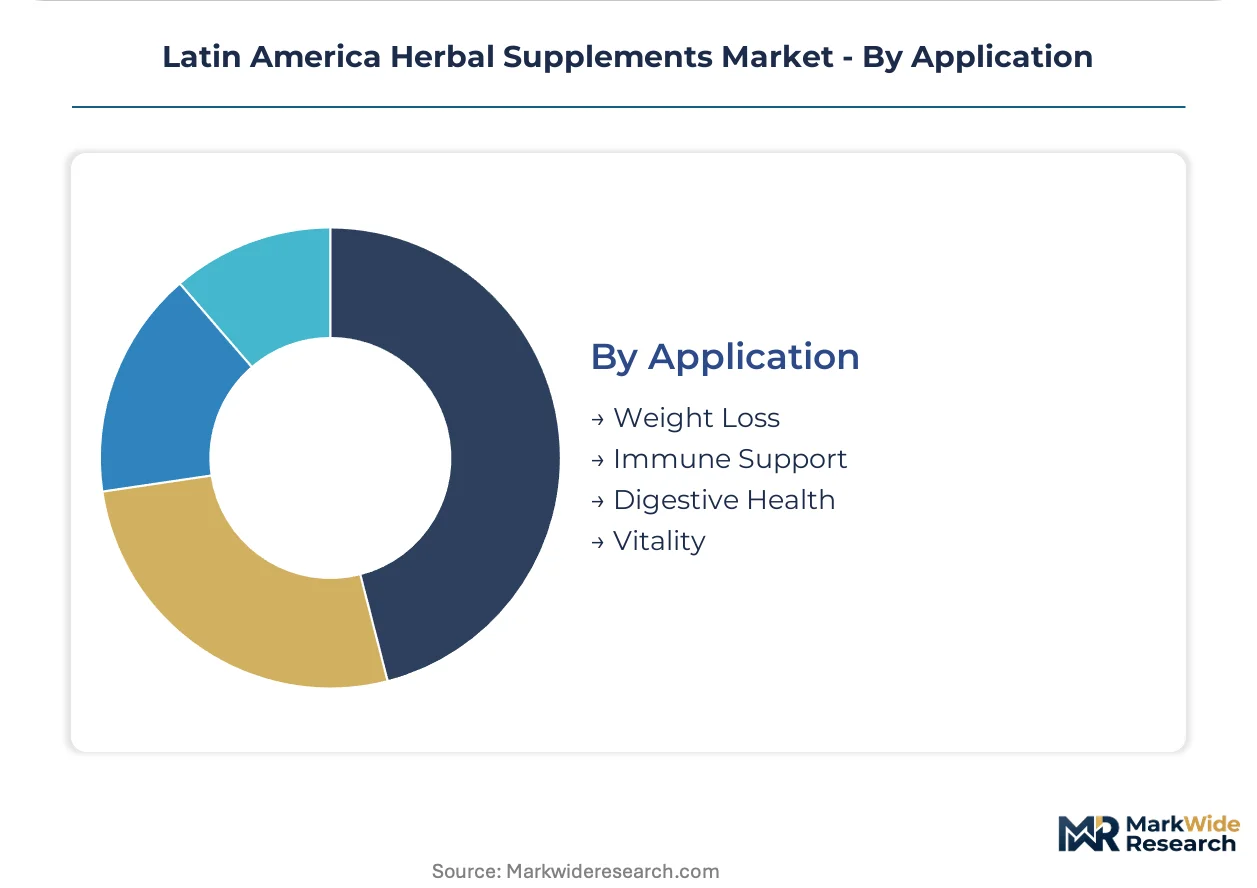
- Immune Support:Standardized preparations targeting cytokine modulation and pathogen resistance. Consumer prioritization of preventive health sustains absolute demand leadership across Brazil and Mexico retail channels.
- Digestive Health:Bitter botanicals and carminative formulations for gastrointestinal function. Practitioner-directed channels in Colombia and Chile reward manufacturers with in-house extraction protocols and deeper margin pools.
- Weight Loss:Thermogenic and appetite-modulating botanical combinations. Regulatory scrutiny varies across ANVISA, COFEPRIS, and INVIMA jurisdictions.
- Vitality:Adaptogenic and tonic preparations for energy and stress resilience. Ayurvedic-protocol convergence opens hybrid positioning in premium powder segments.
Immune support anchors volume. Digestive health secures margin depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions where chromatographic fingerprinting requirements remain less stringent than ANVISA's updated protocols, compressing time-to-market for domestic Brazilian manufacturers while elevating compliance costs for imported raw material suppliers.
Brazil
São Paulo's wellness center clusters anchor national adoption velocity through same-day replenishment from southeastern distribution hubs. ANVISA's heavy metal testing mandates and botanical authentication requirements raise barriers for Asian raw material importers while benefiting vertically integrated Atlantic Forest cultivators. Captive cultivation partnerships in Minas Gerais and Paraná secure preferential shelf placement through chain-of-custody verification.
Mexico
COFEPRIS streamlined botanical registration protocols accelerate cross-border launches from Brazilian suppliers targeting Mexico City practitioner offices. The national pharmaceutical regulator's blockchain-traceable certificate requirements for non-Mercosur imports create documentation friction for Peruvian maca suppliers. Tincture manufacturers face steepest compliance recalibration amid demand for rapid bioavailability formulations.
Colombia
INVIMA's pending harmonization with Pacific Alliance standards creates first-mover positioning for Brazilian exporters with existing chromatographic documentation. Practitioner-directed digestive health channels remain underpenetrated, rewarding manufacturers with in-house extraction protocols and Andean sourcing partnerships. Bogotá's logistics infrastructure lags São Paulo's same-day replenishment capabilities.
Argentina
Traditional yerba mate adjacents sustain retail consumer preference for whole-leaf and cut-and-sifted botanical preparations. Buenos Aires wellness chains lag São Paulo's certificate-of-analysis transparency standards, creating geographic asymmetry in supplier qualification intensity. Argentine health food shops emphasize organic certification narratives over pharmaceutical-grade manufacturing protocols.
Chile
Santiago's practitioner networks reward clinical substantiation requirements for digestive health formulations with deeper margin pools. The country's national pharmaceutical regulator enforces stability testing standards that fragment product development timelines for cross-border launches. Andean maca processing convergence with Ayurvedic cold-pressing methods opens hybrid positioning in premium powder segments.
Latin America Herbal Supplements Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-clinic distribution and Ayurvedic-protocol convergence. The vendor base stratifies across three maturity levels: multinational direct-sales organizations with captive cultivation networks, mid-sized Brazilian processors with spray-drying capabilities, and specialty importers navigating multi-regulator compliance. Strategic differentiation concentrates on backward integration into Atlantic Forest biomes and extraction technology standardization. Dominant competitive moves include geographic expansion through Pacific Alliance harmonization and portfolio diversification toward practitioner-directed channels.
Among multinational direct-sales organizations, Herbalife International of America Inc., Amway International Inc., and Himalaya Global Holdings Ltd. exemplify contrasting archetypes. Herbalife anchors Latin American operations through Brazilian captive cultivation partnerships. Amway competes through channel control spanning Mexico City to Buenos Aires. Himalaya leverages Ayurvedic extraction protocols to differentiate in capsules and powders segments. These three represent the strategic spectrum from upstream supply control to protocol-based positioning.
| Leading Market Players |
|---|
| Amway International Inc. |
| Herbalife International of America Inc. |
| GNC Holdings Inc |
| Natulab Laboratório S/A |
| Now Health Group Inc. |
| The Nature's Bounty Co. |
| Sanofi SA |
| Himalaya Global Holdings Ltd. |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap processors across Brazil's southeastern states anchor supply discipline through generational cultivation partnerships, translating Atlantic Forest biome control into pricing power that resists synthetic nutraceutical substitution in premium powder segments.
Pricing Analysis
Distributor margin compression runs through São Paulo's wellness center procurement consortia, which now enforce certificate-of-analysis transparency as a condition of shelf placement. Three-tier pricing structure across premium chromatographic-grade, standard spray-dried, and economy bulk formats separates practitioner-directed tinctures from mass-market capsules. Cost compression in economy tiers intensifies as lab-synthesized curcuminoids undercut botanical extracts in supermarket channels. Retail consumers through pharmacy and online platforms exhibit highest price sensitivity, while health practitioners in Mexico City premium networks accept documentation premiums for rapid bioavailability formulations.
Supply Chain Analysis
Regional distribution centers in São Paulo, Mexico City, and Bogotá form hub-and-spoke patterns that consolidate outbound logistics for wellness center replenishment. Raw material sourcing draws from Brazil's Atlantic Forest cultivators, Peruvian Andean maca processors, and Indian Ayurvedic cold-pressing specialists. Single-source vulnerability concentrates in chromatographic fingerprinting expertise, with HPLC-UV analytical chemists clustered in São Paulo and Porto Alegre laboratories. Downstream distribution feeds from captive cultivation partnerships through direct-to-clinic channels that bypass traditional pharmacy retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on spray-drying technology standardization compressing production variance, while practitioner-directed channels capture premium pricing through clinical substantiation requirements that mass-market formats cannot replicate.
For Market Incumbents: Anticipate regulatory harmonization across Mercosur and Pacific Alliance jurisdictions by pre-positioning chromatographic documentation for Colombian INVIMA alignment. Secure backward integration into Minas Gerais and Paraná cultivation zones before land-use restrictions tighten Atlantic Forest access. Channel control through nutritionist office dispensing defends margin pools against São Paulo wholesale concentration. For New Entrants and Emerging Players: Blockchain-traceable botanical certificates offer a technology-first wedge for Peruvian maca suppliers seeking COFEPRIS-compliant entry into Mexico City practitioner networks. Colombian digestive health channels remain the most penetrable white-space target pending INVIMA harmonization. Direct-to-clinic distribution bypassing pharmacy retail captures margin compression from established wholesale structures. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized Brazilian processors with spray-drying capabilities but lacking Pacific Alliance export documentation. Long-term viability across the analysis window favors acquisition targets with captive Atlantic Forest cultivation and in-house HPLC-UV analytical capacity. The signal to watch is INVIMA's final Pacific Alliance standard adoption timeline, which will trigger first-mover positioning for pre-qualified Brazilian exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatographic Documentation Investment | Pre-positions Brazilian exporters for Colombian INVIMA harmonization with Pacific Alliance standards. |
| Captive Cultivation Expansion | Secures Atlantic Forest biome access before land-use restrictions tighten supply continuity. |
| Direct-to-Clinic Distribution Launch | Bypasses São Paulo wholesale concentration to capture nutritionist-directed margin pools. |
| Spray-Drying Technology Upgrade | Meets ANVISA batch-to-batch consistency mandates while consolidating toll-manufacturing relationships. |
| Ayurvedic-Protocol Convergence | Opens hybrid positioning in premium powders through cold-pressing method integration with Andean processing. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ANVISA regulatory consultants, São Paulo wellness center procurement directors, Colombian nutritionist practitioners, and Brazilian spray-drying equipment operators with secondary validation through ANVISA supplement registry filings, COFEPRIS botanical registration protocols, customs trade data for maca and botanical extracts, and Pacific Alliance harmonization documentation. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Comparable-period anchoring linked historical ANVISA registration velocity to projected pathway streamlining effects across the modeling period. The analytical framework modeled segmentation dimensions including product form factor, end-user channel, application therapeutic versus preventive positioning, and regional regulatory cluster. CAGRs derived from regression analysis of adoption velocity in wellness center clusters and practitioner network penetration. Forecast inputs incorporated spray-drying capacity expansion timelines and chromatographic fingerprinting compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to INVIMA harmonization delays, Atlantic Forest climate volatility, and synthetic nutraceutical substitution rates in mass-market channels. Outputs reflect documented assumptions around regulatory pathway efficiency and cultivation partnership stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Policosanol Market