
 Omega-3 Concentrates Market | 2026-2036
Omega-3 Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Omega-3 Concentrates Market Analytics
The EU Green Deal is rebalancing raw material sourcing priorities across marine-derived omega-3 supply chains. dsm-firmenich leverages its algal fermentation platform to reduce wild-catch dependency. Croda International Plc anchors its position through pharmaceutical-grade lipid purification capabilities. Aker BioMarine competes via Antarctic krill traceability and Marine Stewardship Council certification.
Omega-3 concentrates are highly purified lipid extracts containing elevated levels of eicosapentaenoic acid and docosahexaenoic acid, typically achieved through molecular distillation or supercritical fluid extraction to reach concentrations exceeding 80% total omega-3 content. These concentrates serve pharmaceutical, nutraceutical, and functional food applications requiring precise dosing and enhanced bioavailability. Triglyceride concentrates command premium positioning due to superior absorption kinetics, while ethyl ester formats dominate bulk pharmaceutical contracting. Nutritional supplements absorb the largest volume share, though pharmaceutical applications capture disproportionate margin pools through prescription drug pathways.
FDA, EFSA, and the EU Green Deal collectively shape market access, with FDA drug master file requirements governing pharmaceutical-grade supply and EFSA health claims regulation directing consumer marketing boundaries. The EU Green Deal's sustainable fisheries mandates are tightening raw material traceability obligations for marine-sourced concentrates. Stakeholders must monitor algal oil scale-up economics and prescription drug pipeline conversions to assess long-term competitive positioning.
Market Dynamics
The EU Green Deal is forcing marine-sourced omega-3 supply chains toward algal fermentation platforms and traceability infrastructure, compressing wild-catch dependency while elevating capital requirements for domestication technologies.
Growth Catalysts
- Pharmaceutical-grade lipid purification:Prescription cardiovascular therapies in the United States require FDA drug master file-compliant concentrates, anchoring premium uptake through clinical validation pathways.
- EU Green Deal sustainable fisheries mandates:Regulatory pressure is accelerating investment in Antarctic krill traceability and Marine Stewardship Council certification as market access preconditions.
- Algal oil fermentation scale-up:Controlled-environment production is reducing seasonal biomass volatility and enabling year-round EPA/DHA output independent of oceanic conditions.
Market Restraints
- Wild-catch supply concentration:Peruvian anchovy and Antarctic krill fisheries face quota compression from warming waters and competing industrial demand for fishmeal.
- Ethyl ester absorption kinetics:Pharmaceutical bulk contracting favors cost-optimized ethyl ester formats despite inferior bioavailability versus triglyceride concentrates in nutraceutical applications.
- EFSA health claim boundaries:European consumer marketing faces strict evidentiary thresholds for cardiovascular benefit assertions, limiting direct-to-consumer positioning.
Strategic Opportunities
- Underpenetrated infant nutrition in India:FSSAI regulatory harmonization with CODEX standards is opening formulation pathways for DHA-enriched maternal and early childhood products.
- Cell-cultured marine lipid convergence:Integration of precision fermentation with algal strain engineering promises EPA/DHA titers exceeding 50% without wild biomass extraction.
- Direct-to-clinic distribution:Telehealth platforms in the United States are bypassing retail pharmacy intermediaries for prescription omega-3 therapies, capturing margin pool redistribution.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA drug master file compilation and cGMP facility qualification demand 18-36 month lead times, freezing working capital.
- Lipid oxidation control expertise:Concentrate stability engineering requires specialized formulation chemists scarce outside established pharmaceutical excipient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega-3 Concentrates Market |
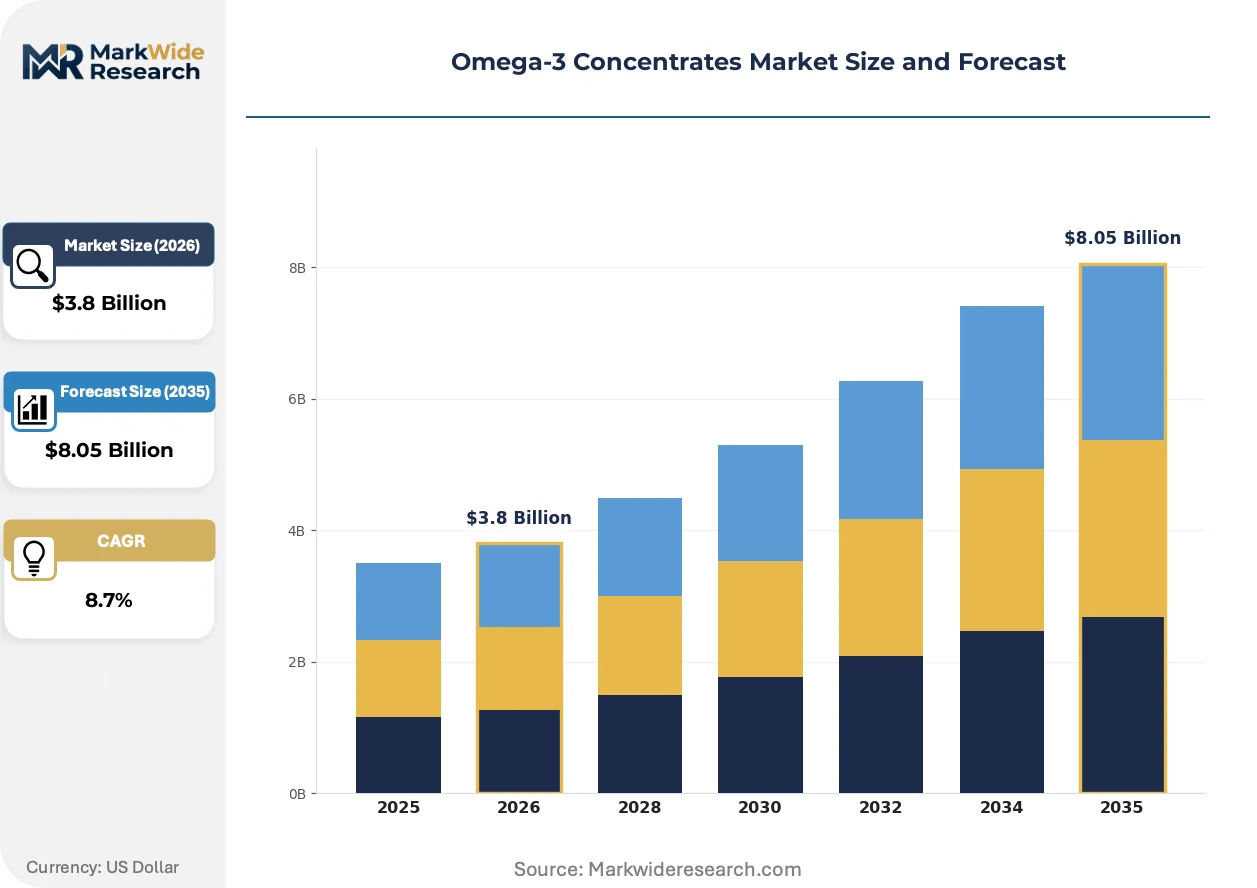
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Ester, Triglyceride, Free Fatty Acid, Concentrated Oil Application: Nutritional Supplements, Functional Foods, Pharmaceuticals, Animal Feed Source: Fish Oil, Algal Oil, Krill Oil, Omega-3 Fortified Foods Form: Softgels, Liquid, Powder, Capsules |
| Companies Covered | BASF SE, Cargill Incorporated, dsm-firmenich, Croda International Plc, Aker BioMarine, EPAX, Golden Omega, GC Rieber Oils, KD Pharma Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega-3 Concentrates Market Evolving Landscape
Algal fermentation platforms are decentralizing upstream supply architecture while regulatory traceability mandates and channel disintermediation reshape competitive boundaries across pharmaceutical and nutraceutical verticals.
Supercritical CO2 extraction is decentralizing concentrate production from coastal processing hubs to inland biomanufacturing facilities. Pharmaceutical formulators in Germany and the United States are adopting modular supercritical units for captive EPA/DHA purification, compressing toll-manufacturing dependency and enabling just-in-time API integration for prescription drug pipelines.
REACH and CSRD disclosure requirements are tightening substance traceability obligations for marine lipid importers into the European Union. Industrial consequence includes mandatory chain-of-custody documentation from catch to concentrate, with Norwegian and Spanish refiners investing in blockchain-verified provenance systems to maintain market access.
Hospital and clinic procurement of prescription omega-3 therapies is consolidating through group purchasing organizations in the United States, displacing fragmented wholesaler relationships. This concentration is compressing price negotiation cycles from annual to quarterly intervals while elevating formulary exclusivity premiums for FDA-approved drug pathways versus dietary supplement positioning.
Omega-3 Concentrates Market Segmentation
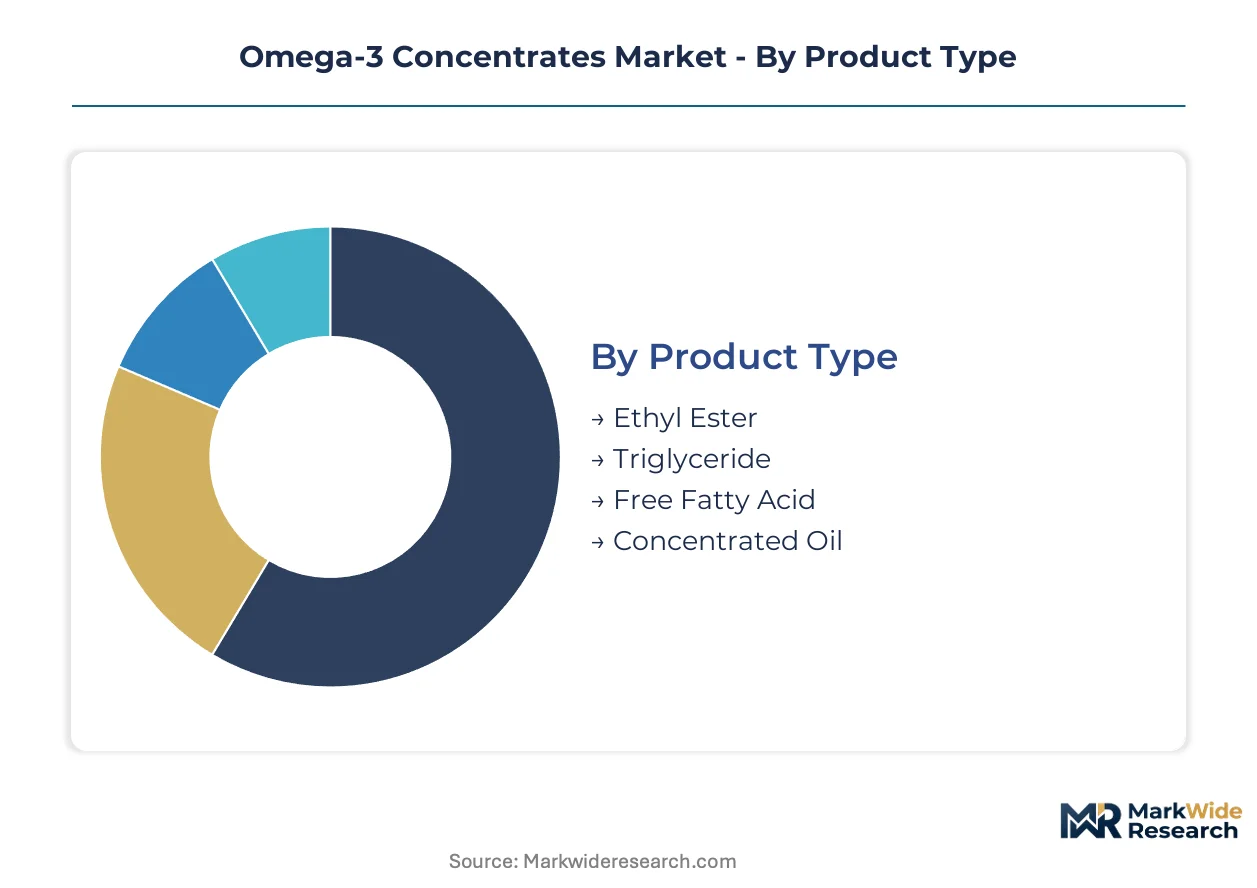
Omega-3 concentrate specifications diverge sharply across end-use requirements, with pharmaceutical formulators demanding exacting purity thresholds while nutraceutical buyers prioritize absorption kinetics. Source traceability and molecular format together determine supply chain eligibility for premium contracting tiers.
Product Type:
Supply concentration tilts toward ethyl ester infrastructure due to legacy pharmaceutical contracting scale, though triglyceride capacity is expanding fastest among new entrants.
- Ethyl Ester:Molecular distillation yields EPA/DHA concentrates exceeding 80% purity in cost-optimized formats suited to bulk API manufacturing. United States prescription cardiovascular therapies anchor demand through FDA drug master file pathways, though inferior bioavailability versus triglyceride formats constrains nutraceutical positioning.
- Triglyceride:Re-esterified formats deliver superior absorption kinetics through natural molecular configurations. Premium supplement brands in Germany and Japan concentrate procurement here, paying formulation premiums for clinical bioavailability validation.
- Free Fatty Acid:Non-esterified formats bypass digestive hydrolysis for rapid plasma uptake.
- Concentrated Oil:Standardized potency oils serve functional food fortification at intermediate purity thresholds.
Ethyl ester absorbs the bulk of installed capacity; triglyceride is expanding most quickly.
Application:
Cost tier separation runs deepest here, with pharmaceutical pathways commanding 3-5x manufacturing premiums over commodity supplement positioning.
- Nutritional Supplements:Volume-dominant segment absorbing concentrate output across softgel and liquid delivery formats. Direct-to-consumer channels in the United States and United Kingdom concentrate demand, with Amazon and specialized health platforms displacing traditional retail pharmacy distribution.
- Pharmaceuticals:Prescription omega-3 therapies require cGMP manufacturing, lipid oxidation control expertise, and FDA/EMA regulatory dossiers. Lovaza and Vascepa drug pathways anchor United States demand, with hospital procurement consolidating through group purchasing organizations.
- Functional Foods:Microencapsulation enables DHA fortification of dairy, infant formula, and bakery applications without sensory degradation.
- Animal Feed:Aquaculture and pet nutrition applications absorb lower-grade concentrates excluded from human consumption specifications.
Nutritional supplements dominate volume throughput; pharmaceuticals capture the steepest margin expansion trajectory.
Source:
Customer type preferences are splitting the supply base, with sustainability-conscious buyers migrating toward algal platforms while cost-sensitive formulators remain anchored to marine fisheries.
- Fish Oil:Peruvian anchovy and North Atlantic herring fisheries supply the majority of EPA/DHA raw material. Seasonal biomass volatility and quota compression from warming waters constrain supply security for long-term pharmaceutical contracts.
- Algal Oil:Controlled-environment fermentation eliminates wild-catch dependency and enables year-round DHA-dominant output. dsm-firmenich and Corbion are expanding capacity to serve infant formula and vegan supplement positioning.
- Krill Oil:Antarctic fisheries deliver phospholipid-bound omega-3s with superior cellular uptake kinetics.
- Omega-3 Fortified Foods:Finished consumer products with intrinsic EPA/DHA enrichment bypass concentrate intermediaries.
Fish oil retains the bulk of extraction infrastructure; algal oil is climbing the fastest among alternative platforms.
Form:
Maturity gradients separate established delivery formats from emerging powder applications targeting functional food integration.
- Softgels:Gelatin and plant-based capsule shells dominate supplement shelf presence with standardized dosing convenience. United States and Chinese contract manufacturers concentrate softgel capacity for global brand supply.
- Liquid:Pediatric and geriatric applications favor adjustable dosing without swallowing constraints.
- Powder:Microencapsulated and free-flowing formats enable dry-blend functional food fortification.
- Capsules:Two-piece hard shells serve niche vegetarian and enteric-coated positioning.
Softgels command the majority of packaging line investment; powder formats are gaining share fastest in food manufacturing channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors pharmaceutical-grade omega-3 concentrate demand through its cluster of prescription drug developers and FDA-aligned clinical research organizations.
United States
Hospital procurement consolidation through group purchasing organizations drives concentrate demand for prescription cardiovascular therapies. FDA drug master file requirements govern pharmaceutical-grade supply chains, elevating certification barriers for imported concentrates. The Boston-Cambridge corridor concentrates lipid oxidation control expertise among specialized pharmaceutical excipient suppliers serving prescription omega-3 drug pathways.
Germany
Modular supercritical CO2 extraction units enable captive EPA/DHA purification for prescription drug pipelines among pharmaceutical formulators. REACH and CSRD disclosure requirements tighten substance traceability obligations for marine lipid importers. The Hamburg-Bremen port complex concentrates Norwegian and Spanish refiner operations investing in blockchain-verified provenance systems.
China
Contract manufacturers concentrate softgel capacity for global brand supply across gelatin and plant-based capsule formats. NMPA alignment with international cGMP standards is opening pathways for domestic pharmaceutical-grade concentrate production. The Yangtze River Delta cluster anchors microencapsulation technology development for functional food fortification applications.
India
FSSAI regulatory harmonization with CODEX standards opens formulation pathways for DHA-enriched maternal and early childhood products. The central food safety regulator mandates quality benchmarks that align domestic production with export market requirements. Maharashtra's pharmaceutical manufacturing corridor concentrates infant nutrition contract manufacturing capacity serving Southeast Asian and Middle Eastern markets.
Norway
Antarctic krill traceability infrastructure and Marine Stewardship Council certification anchor premium positioning for sustainability-conscious buyers. The EU Green Deal's sustainable fisheries mandates compress wild-catch dependency while elevating capital requirements for domestication technologies. Bergen and Ålesund concentrate marine lipid refining capacity with integrated chain-of-custody documentation systems.
Omega-3 Concentrates Market Competitive Landscape
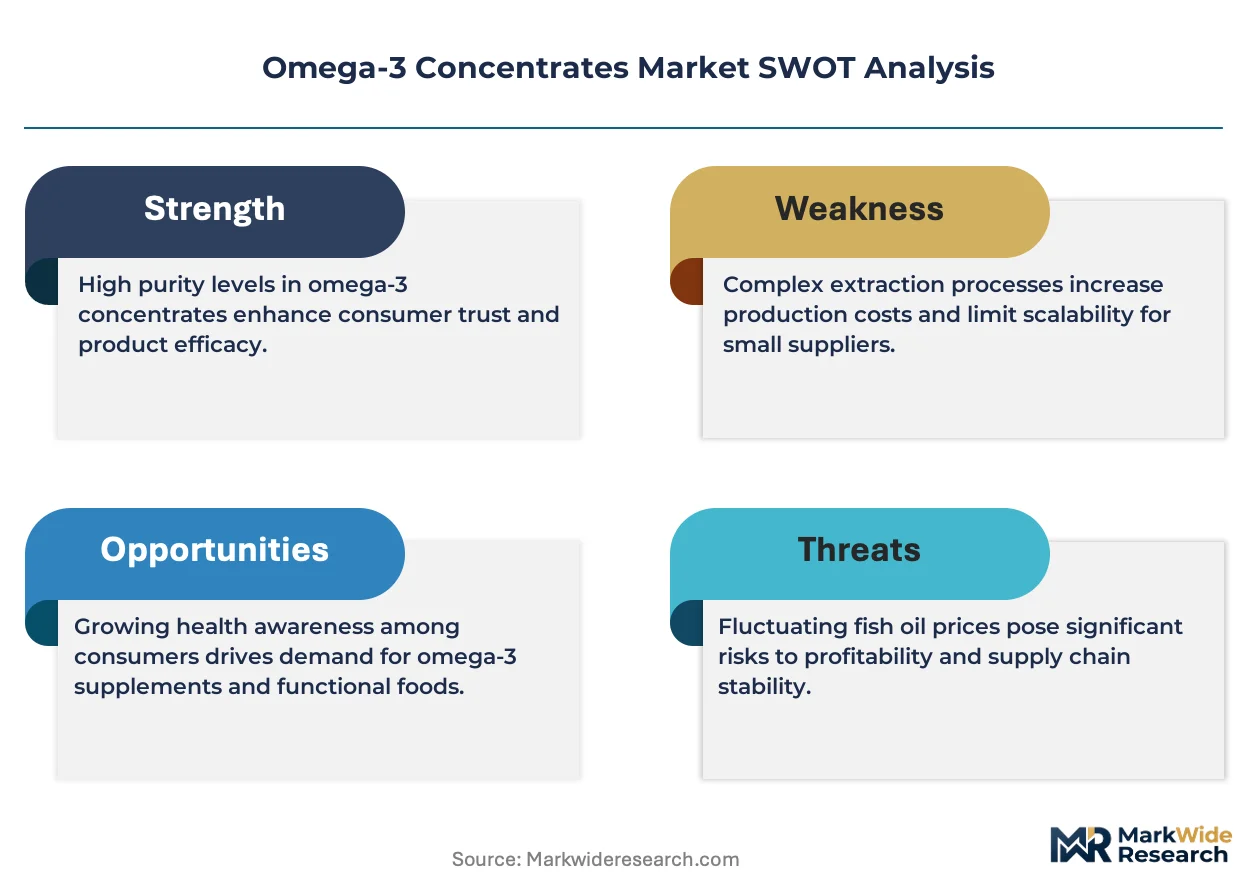
The competitive structure tilts toward vertically integrated specialists with pharmaceutical-grade certification capabilities. Three to five multinational chemical and nutrition conglomerates anchor supply through captive fermentation platforms and marine sourcing networks. Two strategic archetypes dominate: algal fermentation platform operators reducing wild-catch dependency, and marine lipid refiners with Antarctic traceability infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with toll-manufacturing relationships giving way to captive purification units.
Among European-based nutrition and chemical conglomerates, BASF SE, dsm-firmenich, and Croda International Plc exemplify divergent sourcing strategies. BASF SE represents the diversified chemical archetype with integrated lipid purification capabilities spanning multiple end-use segments. dsm-firmenich occupies a position within the algal fermentation platform tier, exemplifying controlled-environment production independent of oceanic biomass volatility. Croda International Plc anchors the pharmaceutical-grade lipid purification specialist archetype, with company naming conventions indicating UK-registered public limited company structure.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| dsm-firmenich |
| Croda International Plc |
| Aker BioMarine |
| EPAX |
| Golden Omega |
| GC Rieber Oils |
| KD Pharma Group |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation through United States group purchasing organizations anchors contract-based pricing for pharmaceutical-grade concentrates, with FDA drug master file certification tiers separating premium API supply from commodity nutraceutical positioning.
Pricing Analysis
Clinical outcome validation through prescription cardiovascular therapies anchors value-based pricing for pharmaceutical-grade concentrates. Three-tier pricing structure across premium triglyceride, standard ethyl ester, and economy bulk oil levels separates absorption-validated formats from cost-optimized API inputs. Cost compression in ethyl ester contracting intensifies as hospital procurement cycles compress from annual to quarterly intervals. Nutritional supplement distributors exhibit highest price sensitivity, while prescription drug developers prioritize bioavailability certification over unit cost.
Supply Chain Analysis
EPA/DHA raw material supply rests on Peruvian anchovy fisheries, Antarctic krill harvesting, and Norwegian marine lipid refining infrastructure. Wild-catch biomass volatility, algal fermentation feedstock, and supercritical CO2 extraction equipment constitute critical input dependencies. Single-source vulnerability concentrates in Peruvian anchovy quotas vulnerable to El Niño warming cycles. Distribution runs through pharmaceutical excipient suppliers for prescription pathways and direct-to-consumer platforms for supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around pharmaceutical-grade certification capabilities, with EU Green Deal traceability mandates forcing subscale wild-catch operators toward exit or acquisition.
For Market Incumbents: Lock in Antarctic krill traceability infrastructure and Marine Stewardship Council certification as non-negotiable market access preconditions. Secure algal fermentation capacity through strategic partnerships with dsm-firmenich or Corbion to reduce oceanic biomass dependency. Defensive consolidation of lipid oxidation control expertise in the Boston-Cambridge corridor protects margin pools from toll-manufacturing commoditization. For New Entrants and Emerging Players: Direct-to-clinic telehealth platforms in the United States represent the most penetrable channel bypassing retail pharmacy intermediaries. Target DHA-enriched maternal nutrition in India where FSSAI harmonization with CODEX standards opens formulation pathways ahead of domestic incumbent response. White-space capture requires algal strain engineering partnerships delivering EPA/DHA titers exceeding 50% without wild biomass extraction. For Investors and Strategic Acquirers: The window for entry favors algal fermentation platform operators with pharmaceutical-grade cGMP qualification capabilities. Long-term viability hinges on controlled-environment production independent of oceanic quota compression. Cell-cultured marine lipid convergence with precision fermentation serves as the critical inflection indicator for technology obsolescence risk in wild-catch dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Algal Fermentation Scale-Up | Controlled-environment EPA/DHA production eliminates Peruvian anchovy quota dependency for pharmaceutical supply security. |
| Pharmaceutical-Grade cGMP Qualification | FDA drug master file pathways capture 3-5x manufacturing premiums over commodity nutraceutical positioning. |
| Blockchain-Verified Provenance Systems | Norwegian and Spanish refiners deploy chain-of-custody documentation to satisfy EU Green Deal traceability mandates. |
| Direct-to-Clinic Distribution Partnerships | Telehealth platforms bypass retail pharmacy intermediaries to capture margin pool redistribution in prescription omega-3 therapies. |
| Supercritical CO2 Extraction Modularization | Inland biomanufacturing facilities decentralize concentrate production from coastal processing hubs for just-in-time API integration. |
Research Methodology
Independent corroboration across lipid oxidation control specialists, pharmaceutical formulators, and algal fermentation platform operators underwrites the qualitative findings. Primary interviews with FDA regulatory consultants, hospital GPO procurement managers, and infant nutrition contract manufacturers in Maharashtra combined with secondary validation from FDA drug master file databases, EFSA health claim registers, and EU Green Deal fisheries compliance documentation. Bottom-up concentrate volume modeling and top-down pharmaceutical API demand triangulation anchored the analytical framework.
Rate-of-change decomposition across the analysis window applied product type, application, source, and regional regulatory cluster segmentation dimensions. CAGRs derived from pharmaceutical prescription pipeline conversions, algal oil capacity expansion timelines, and nutraceutical channel shift velocities. Infant nutrition penetration rates in India and cell-cultured marine lipid technology readiness levels served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including specific El Niño cycle intensity impacts on Peruvian anchovy biomass, unannounced pharmaceutical M&A activity, and breakthrough algal strain engineering achievements. Forecasts reflect documented assumptions about regulatory harmonization timelines and cGMP facility qualification success rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market