
 US Nutraceuticals Market | 2026-2036
US Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
US Nutraceuticals Market Analytics
Clinical-grade potency tiers are redrawing competitive boundaries in the US nutraceuticals landscape. Abbott leverages its pharmaceutical heritage to anchor credibility in medical-channel distribution. Herbalife Nutrition Ltd. sustains its direct-selling infrastructure across Latinx-dense metro corridors. Danone differentiates through fermented-base platforms that bridge food and supplement classifications.
Nutraceuticals comprise bioactive compounds, standardized botanical extracts, and fortified matrices engineered to deliver measurable physiological benefits beyond basic nutrition. Manufacturing employs microencapsulation, cold-pressing, and bioavailability-enhancing delivery systems to preserve marker-compound stability through shelf life. Probiotics command premium positioning due to strain-specific clinical validation and refrigerated supply-chain requirements. Gummies occupy the fastest-expanding formulation slot as adult consumers reject pill fatigue. Online Retailers capture disproportionate growth velocity among distribution channels, though Pharmacies retain trust premiums for condition-specific regimens.
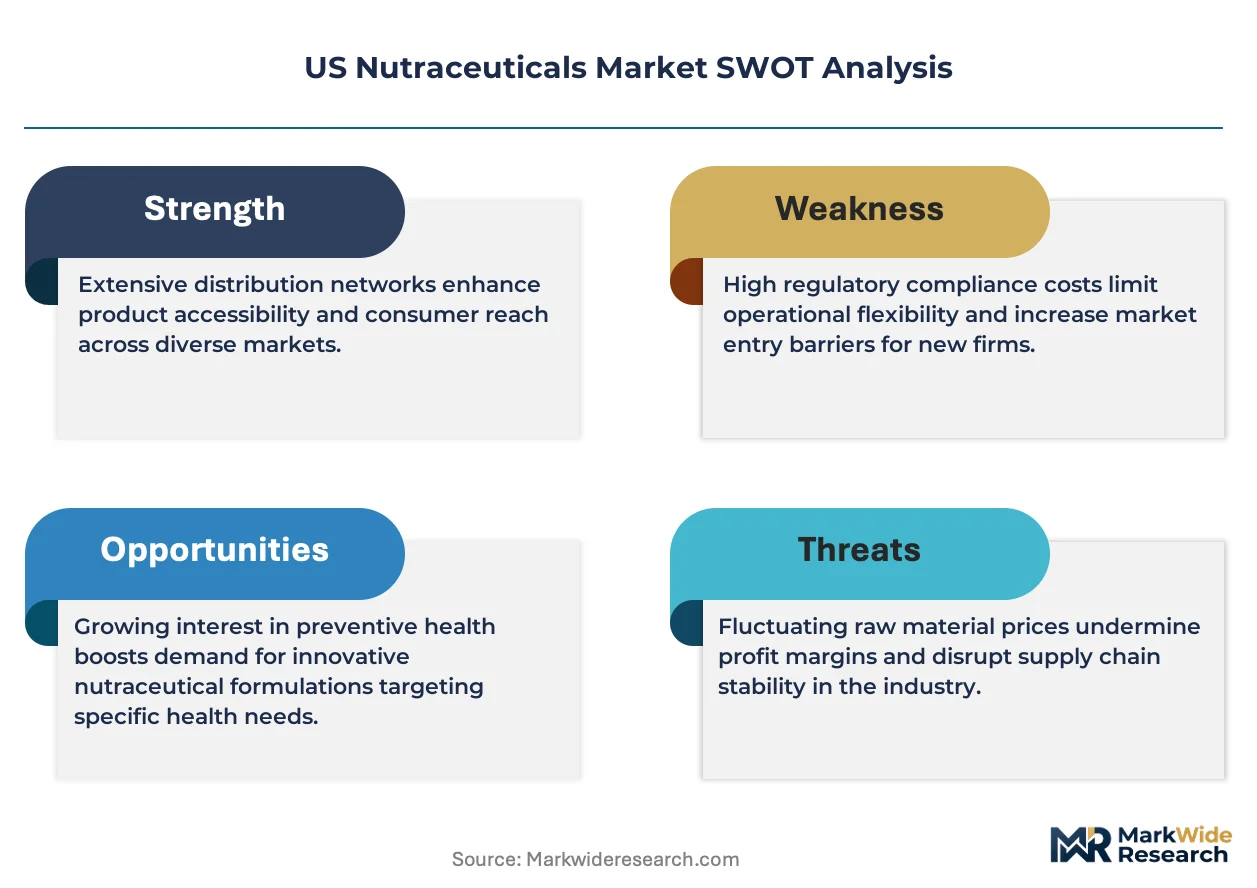
FDA's Current Good Manufacturing Practice enforcement and FTC substantiation standards shape label claims and advertising posture for domestic manufacturers. DSHEA's regulatory framework, combined with California's Proposition 65 chemical disclosure mandates, elevates compliance costs but also filters marginal operators from shelf access. Stakeholders must monitor NDI notification backlogs and state-level ingredient bans that could strand inventory or force reformulation cycles.
Market Dynamics
DSHEA enforcement shifts and FDA's NDI notification backlog are compressing formulation cycles while elevating compliance barriers for mid-tier manufacturers across California and the Northeast.
Growth Catalysts
- Probiotic strain validation:Clinical trials demonstrating gut-brain axis benefits are expanding applications beyond digestive health into mood and cognitive support categories.
- Sports nutrition adoption:Collegiate athletic programs across Texas, Florida, and Arizona are integrating personalized supplement protocols into performance training regimens.
- California Proposition 65 alignment:Early compliance with chemical disclosure mandates is opening shelf access in the state's functional food cluster for prepared manufacturers.
Market Restraints
- Botanical supply concentration:Ashwagandha and turmeric root sourcing depends on Indian agricultural output subject to monsoon variability and export duty fluctuations.
- Cold-chain infrastructure gaps:Refrigerated probiotic distribution requires capital investment that strains regional distributors in the Mountain West and rural Southeast.
- FTC substantiation standards:Advertising claim requirements are extending clinical trial timelines and raising barrier-to-entry costs for novel ingredient introductions.
Strategic Opportunities
- Southwest collegiate athletics:University sports medicine programs in Arizona and New Mexico represent underpenetrated channels for personalized nutrition protocols.
- Gummy format expansion:Adult rejection of pill fatigue is creating white space for condition-specific gummy formulations targeting sleep and stress management.
- IRA wellness incentives:Preventive health tax-advantaged accounts are redirecting household spending toward clinically validated supplement tiers.
Industry Challenges
- Microbiome assay integration:Personalized probiotic matching requires bioinformatics talent scarce among legacy supplement manufacturers.
- NDI notification timelines:FDA backlog is stranding pre-market inventory and forcing parallel formulation pipelines that compress R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Nutraceuticals Market |
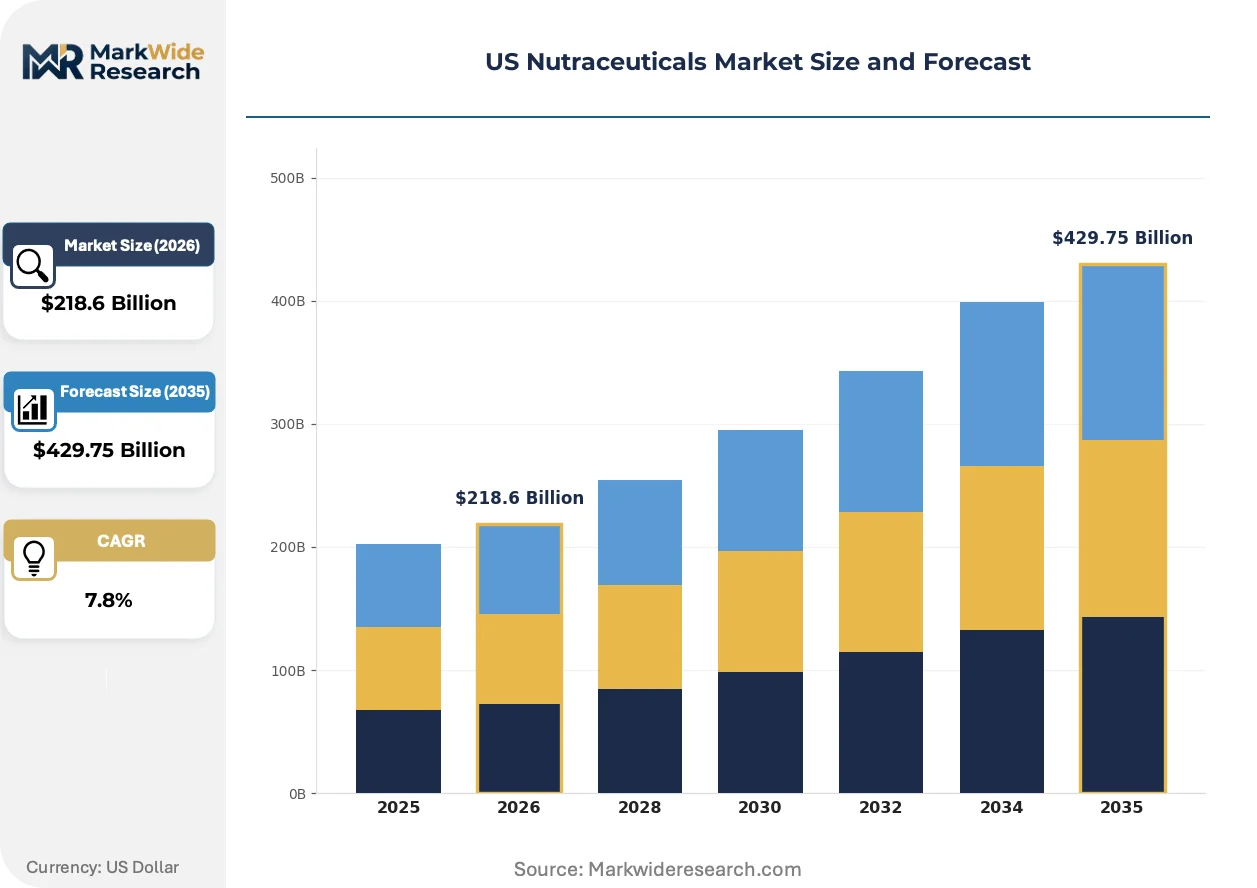
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $429.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Probiotics Distribution Channel: Online Retailers, Pharmacies, Supermarkets, Health Food Stores End User: Adults, Elderly, Athletes, Children Formulation: Pills, Powders, Liquids, Gummies |
| Companies Covered | Nestlé S.A., Abbott, General Mills Inc., Amway Corp., Herbalife Nutrition Ltd., PepsiCo Inc., Danone, The Kraft Heinz Company, The Hain Celestial Group, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Nutraceuticals Market Evolving Landscape
Delivery system innovation and regulatory disclosure requirements are compressing traditional formulation advantages while opening premium positioning for validated clinical tiers.
Liposomal encapsulation technology is improving bioavailability of fat-soluble vitamins and botanical actives through phospholipid bilayer protection. Functional food manufacturers in California's Bay Area and Los Angeles corridors are adopting these systems at accelerated pace for beverage and shot applications. Cold-pressed liposomal production is supplanting conventional tablet and softgel formats in the premium preventive health segment.
FDA's Current Good Manufacturing Practice enforcement is tightening identity testing requirements for botanical raw materials. Domestic contract manufacturers are consolidating supplier qualification programs and investing in in-house chromatography capabilities. The probiotic and enzyme categories face the steepest compliance cost escalation, driving mid-tier brands toward toll manufacturing partnerships.
Adult consumers are rejecting multi-pill regimens in favor of consolidated delivery formats that combine multiple actives. The gummy and effervescent tablet segments are capturing this behavioral pivot, particularly among urban professionals in the Northeast corridor. Online subscription models are displacing pharmacy and mass retail as the primary acquisition channel for repeat purchase categories.
US Nutraceuticals Market Segmentation
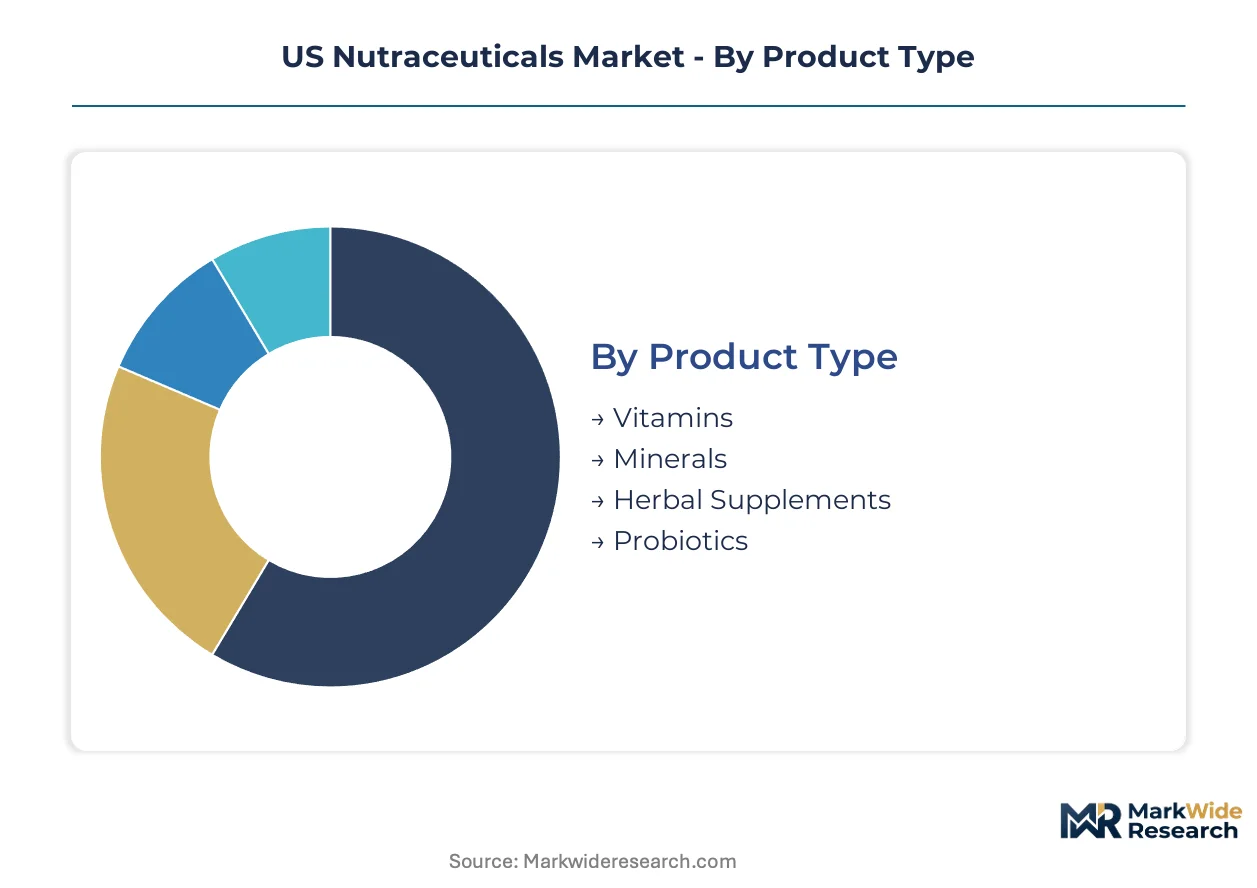
Nutraceutical segmentation in the US market reflects divergent compliance burdens and channel access requirements. Product classification determines FDA notification pathways, while distribution choice shapes substantiation standards and customer acquisition economics.
Product Type:
FDA's New Dietary Ingredient notification requirements and DSHEA enforcement intensity vary sharply across product categories, creating tiered barriers to shelf access.
- Probiotics:Strain-specific clinical validation and refrigerated supply-chain requirements command premium positioning. Demand concentrates in California's functional food cluster where consumers prioritize gut-brain axis benefits for mood and cognitive support.
- Herbal Supplements:Standardized botanical extracts with marker-compound stability requirements face escalating identity testing under Current Good Manufacturing Practice enforcement. Northeast preventive health corridors drive adoption of ashwagandha and turmeric formulations despite Indian agricultural sourcing concentration.
- Vitamins:Liposomal encapsulation technology is improving bioavailability of fat-soluble variants through phospholipid bilayer protection in Bay Area beverage applications.
- Minerals:Chelated forms and bioavailability-enhancing delivery systems preserve stability through shelf life in mass-market channels.
Probiotics handles the majority of throughput; Herbal Supplements is the fastest mover on share.
Distribution Channel:
Customer acquisition cost structures and repeat purchase mechanics differ fundamentally across channel architectures, with subscription economics displacing traditional retail.
- Online Retailers:Subscription models capture disproportionate growth velocity through personalized protocol algorithms and direct-to-consumer logistics. Urban professionals in the Northeast corridor favor consolidated delivery formats via this channel.
- Pharmacies:Trust premiums for condition-specific regimens persist despite share erosion, particularly for clinically validated tiers requiring pharmacist consultation.
- Health Food Stores:California's Proposition 65 alignment opens shelf access for prepared manufacturers in the state's functional food cluster.
- Supermarkets:Mass-market penetration of fortified matrices bridges food and supplement classifications in conventional grocery environments.
Online Retailers is expanding most quickly; Pharmacies retains the highest margin per transaction.
End User:
Physiological life-stage requirements and performance optimization goals segment demand into distinct formulation and dosing protocols.
- Athletes:Collegiate programs across Texas, Florida, and Arizona integrate personalized supplement protocols into performance training regimens. Southwest university sports medicine programs in Arizona and New Mexico represent underpenetrated channels.
- Adults:Rejection of multi-pill regimens drives gummy and effervescent tablet adoption among urban professionals seeking consolidated delivery formats.
- Elderly:IRA wellness incentives redirect household spending toward clinically validated supplement tiers for preventive health maintenance.
- Children:Palatability requirements and dosage precision needs constrain formulation options to gummy and liquid matrices.
Adults commands the largest absolute volume; Athletes is climbing the fastest on share.
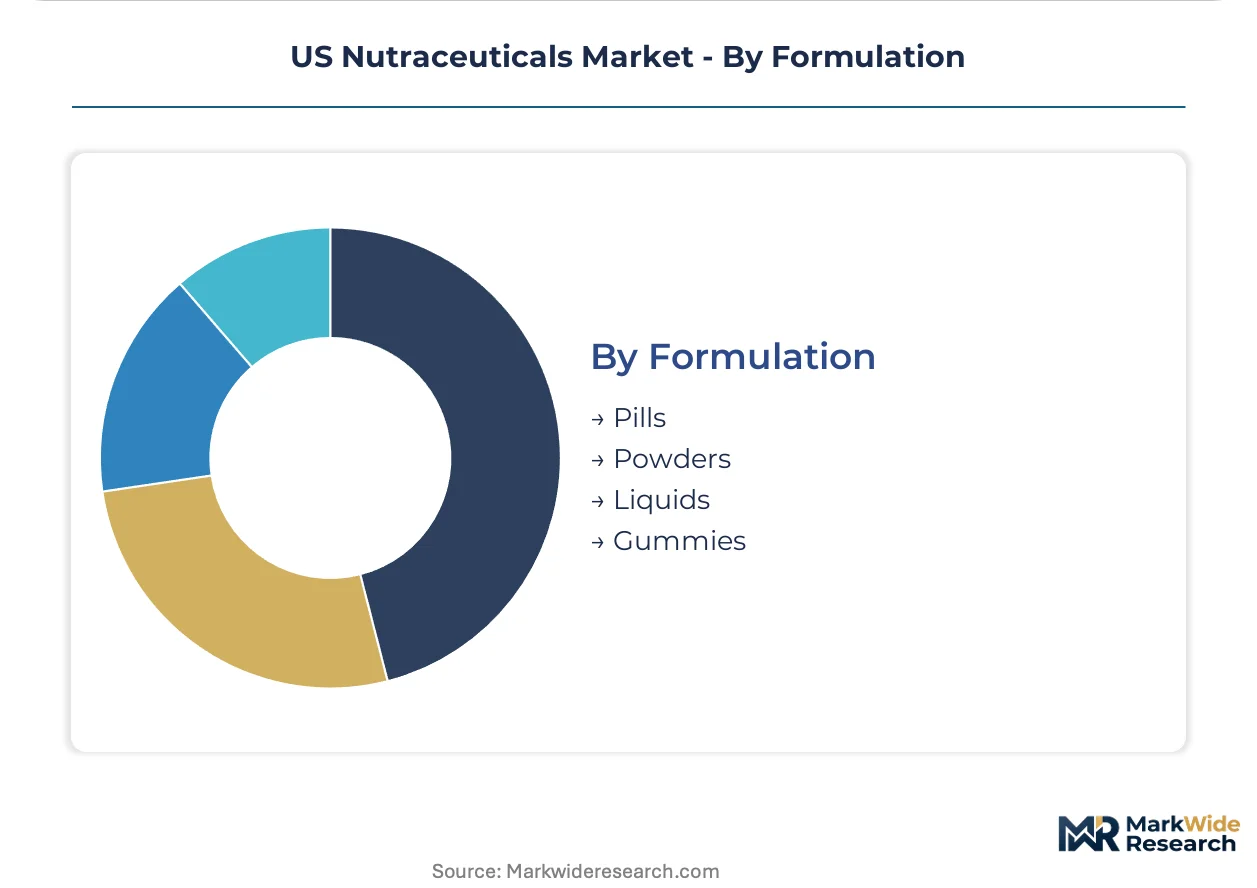
Formulation:
Manufacturing process selection determines marker-compound stability, bioavailability enhancement potential, and cold-chain infrastructure requirements.
- Gummies:Adult rejection of pill fatigue creates white space for condition-specific formulations targeting sleep and stress management. Cold-pressed production methods preserve active integrity in premium positioning.
- Pills:Microencapsulation technology maintains shelf stability for standardized botanical extracts in pharmacy and mass retail channels.
- Powders:Sports nutrition adoption favors bulk formats for collegiate and professional athletic program integration.
- Liquids:Liposomal encapsulation systems improve bioavailability for beverage and shot applications in California corridors.
Pills handles the majority of unit volume; Gummies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across US sub-regions. California consumers absorb premium pricing for clinical-grade probiotics and functional foods, while price-sensitive mass-market buyers in the Southeast and Mountain West drive volume through conventional retail channels.
California
Bay Area and Los Angeles corridors anchor the functional food cluster where liposomal encapsulation technology spreads through beverage applications. Proposition 65 chemical disclosure mandates filter marginal operators from shelf access, elevating compliance costs for prepared manufacturers. Cold-pressed production methods and refrigerated probiotic distribution concentrate in San Francisco-Oakland and Santa Monica sub-markets.
Texas
Collegiate athletic programs across Austin, Dallas-Fort Worth, and Houston integrate personalized supplement protocols into performance training regimens. University sports medicine departments drive sports nutrition adoption among student-athletes. Bulk powder formats and subscription-based delivery models penetrate the Dallas metro corridor fastest.
Northeast Corridor
Urban professionals in New York Metro and Greater Boston reject multi-pill regimens, consolidating demand into gummy and effervescent tablet formats. Preventive health corridors redirect household spending toward clinically validated supplement tiers through IRA wellness incentives. Online subscription models displace pharmacy channels for repeat purchase categories among this demographic.
Southeast
Florida and Georgia mass-market channels absorb conventional vitamin and mineral formulations at price points below national averages. Direct-selling infrastructure sustains penetration across Latinx-dense metro corridors in Miami-Dade and Atlanta. Cold-chain infrastructure gaps strain refrigerated probiotic distribution in rural markets.
Southwest
Arizona and New Mexico university sports medicine programs represent underpenetrated channels for personalized nutrition protocols. Phoenix and Tucson sub-markets show emerging demand for condition-specific gummy formulations targeting sleep and stress management. Collegiate athletics partnerships in this region lag Texas and Florida adoption curves.
US Nutraceuticals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US nutraceuticals landscape. Pharmaceutical heritage companies anchor medical-channel credibility through clinical-grade potency tiers, while direct-selling specialists sustain infrastructure across demographic-dense metro corridors. Fermented-base platforms and functional food matrices occupy a third archetype bridging food and supplement classifications. Competitive moves concentrate on portfolio diversification toward gummy formats and geographic expansion into underpenetrated collegiate athletics channels.
Among the named players, Abbott leverages pharmaceutical heritage to anchor credibility in medical-channel distribution. Herbalife Nutrition Ltd. sustains direct-selling infrastructure across Latinx-dense metro corridors. Danone differentiates through fermented-base platforms that bridge food and supplement classifications. These three exemplify distinct competitive archetypes rather than convergent strategies.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Abbott |
| General Mills Inc. |
| Amway Corp. |
| Herbalife Nutrition Ltd. |
| PepsiCo Inc. |
| Danone |
| The Kraft Heinz Company |
| The Hain Celestial Group, Inc. |
| Others |
Value Network & Pricing Analysis
Liposomal encapsulation technology replacing conventional tablet formats is redrawing procurement geography toward California cold-pressed production hubs while compressing margin structures for legacy manufacturers tethered to mass-market softgel economics.
Pricing Analysis
Subscription renewals and personalized protocol algorithms drive lifetime value capture across direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade probiotics with refrigerated distribution from conventional vitamin matrices and private-label commodity tiers. Pricing pressure stems from FTC substantiation requirements extending clinical trial timelines for novel botanical extracts. Mass-market buyers in the Southeast exhibit highest price sensitivity, while California functional food cluster consumers absorb premium positioning for validated strain-specific formulations.
Supply Chain Analysis
Inbound logistics costs through West Coast port corridors and container availability fluctuations on India-US trade lanes strain ashwagandha and turmeric root procurement timelines. Raw material sourcing draws from Indian agricultural output, Chinese fermentation substrate suppliers, and domestic microencapsulation equipment manufacturers. Single-source vulnerability concentrates in Indian monsoon-dependent botanical harvests. Distribution runs through refrigerated direct-to-consumer fulfillment centers for probiotic categories, with pharmacy and mass retail channels handling ambient-stable formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through online subscription platforms that aggregate demand across condition-specific regimens, fragmenting traditional pharmacy channel leverage.
For Market Incumbents: Shield market position by deepening strain-specific clinical validation pipelines and securing exclusive pharmacy distribution partnerships for medical-channel tiers. Cold-chain infrastructure investment in the Mountain West closes competitive gaps against emerging direct-to-consumer entrants. FDA Current Good Manufacturing Practice compliance certification filters marginal competitors from shelf access. For New Entrants and Emerging Players: California Proposition 65 pre-certification fast-tracks shelf access in the state's functional food cluster. Southwest collegiate athletics programs in Arizona and New Mexico represent the most penetrable channel for personalized nutrition protocols. Gummy format innovation targeting sleep and stress management categories bypasses incumbent pill-format dominance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors toll manufacturing specialists with chromatography capabilities and established FDA notification track records. Long-term viability hinges on bioinformatics talent acquisition for microbiome assay integration. Watch NDI notification backlog resolution velocity as the inflection signal for formulation cycle efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Gummy Format Expansion | Captures adult rejection of pill fatigue through condition-specific sleep and stress matrices. |
| Cold-Chain Infrastructure Buildout | Enables refrigerated probiotic distribution in Mountain West and rural Southeast corridors. |
| Clinical Validation Partnerships | Secures gut-brain axis trial data for mood and cognitive support positioning. |
| Direct-to-Consumer Subscription Launch | Displaces pharmacy channels through personalized protocol algorithms and repeat purchase economics. |
| Toll Manufacturing Acquisition | Consolidates mid-tier brands seeking chromatography capabilities and FDA compliance infrastructure. |
Research Methodology
A standing panel of supplement formulators, FDA regulatory affairs consultants, pharmacy category buyers, and cold-chain logistics directors provided ongoing calibration throughout the analysis. Primary interviews with contract manufacturing executives and functional food brand managers combined with secondary validation against FDA warning letter databases, FTC enforcement action records, and California Proposition 65 settlement filings. Bottom-up SKU-level demand modeling triangulated against top-down channel revenue estimates.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product classification, distribution channel architecture, physiological life-stage end user, and formulation technology type. CAGRs were derived from trend extrapolation of historical adoption curves adjusted for regulatory enforcement intensity and ingredient innovation cycles. Forecast inputs incorporated NDI notification pipeline velocity and collegiate athletics program expansion trajectories.
Underlying assumptions cover sustained IRA wellness incentive eligibility, stable Indian agricultural export policies, and continued FDA CGMP enforcement intensity, with deviation risk concentrated in botanical supply disruptions and state-level ingredient ban enactments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Vegan Protein Market