
 Energy ESO Market | 2026-2036
Energy ESO Market Size, Share, and Industry Trends Forecast 2026-2036
Energy ESO Market Intelligence
Cloud-native digital twin integration is tilting how energy engineering services are delivered across generation and grid projects. Altair Engineering leverages high-fidelity simulation software to anchor its position in physics-based modeling for turbine and grid asset optimization. Capgemini Engineering sustains competitive differentiation through embedded systems expertise that spans SCADA modernization and IoT-enabled predictive maintenance platforms.
Energy engineering services outsourcing encompasses technical consulting, design engineering, lifecycle asset management, and operational outsourcing delivered to power sector clients, typically governed by ISO 55000 asset management standards and IEC 61850 communication protocols for substation automation. The consulting segment dominates near-term revenue as utilities restructure grid investment plans around intermittent renewable portfolios. Renewable integration applications within the service stack represent the fastest-expanding margin pool, driven by inverter interoperability studies and hybrid storage coupling designs that independent power producers now require before financial close.
EMA's evolving medical device regulation framework does not govern this sector; instead, EU Green Deal national implementation plans and FERC Order 2222 in the United States reshape market access by mandating distributed resource participation in wholesale markets and tightening carbon accounting for imported electricity. Germany's KBA-equivalent energy regulator, the Bundesnetzagentur, enforces grid code compliance that determines which engineering service providers qualify for offshore connection tenders. Stakeholders must monitor how divergent cyber-physical security standards between European ENTSO-E codes and North American NERC CIP frameworks fragment service delivery models and certification requirements.
Market Dynamics
Cloud-native digital twin deployment is compressing engineering service delivery timelines across offshore wind and grid modernization programs, forcing traditional EPC firms to restructure talent models around software-physics integration.
Growth Catalysts
- EU Green Deal national implementation plans:Germany and Denmark accelerate offshore wind tendering that bundles engineering design with 25-year asset management contracts.
- Hybrid storage coupling designs:Independent power producers now mandate inverter interoperability studies before financial close, expanding the addressable service scope for systems integrators.
- FERC Order 2222:Distributed resource participation mandates in US wholesale markets require new grid connection engineering and cyber-physical security certification.
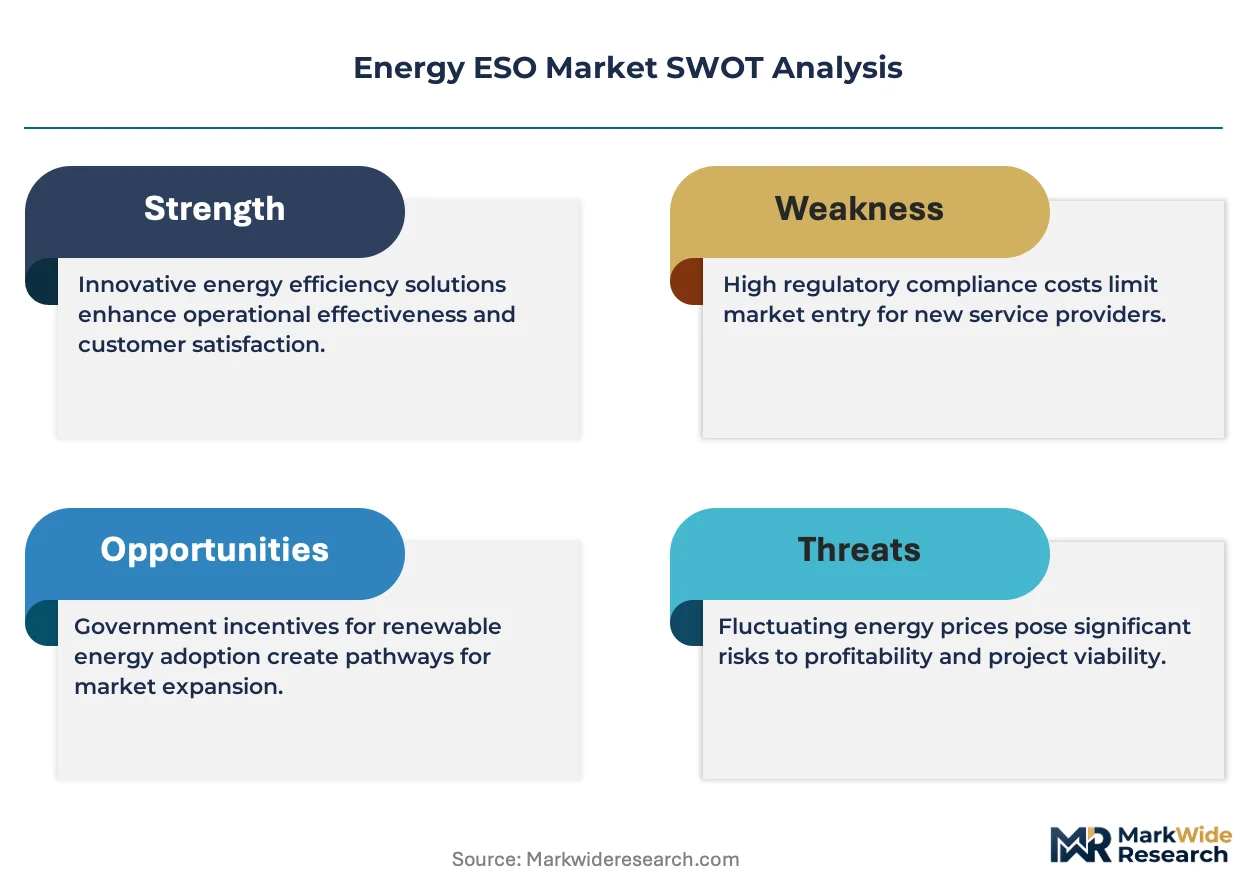
Market Restraints
- Specialized simulation software licensing costs:High-fidelity physics-based modeling tools carry recurring subscription burdens that squeeze mid-tier engineering consultancy margins.
- North Sea cluster supply concentration:Offshore wind engineering talent pools concentrate in Hamburg and Copenhagen, creating wage inflation and recruitment bottlenecks.
- IEC 61850 protocol fragmentation:Divergent substation automation implementations between ENTSO-E codes and utility-specific variants delay project commissioning.
Strategic Opportunities
- US distributed solar-plus-storage retrofits:IRA production tax credit extensions drive demand for repowering engineering services in California and Texas interconnection queues.
- SCADA modernization platforms:Convergence of edge computing with legacy control systems opens margin-rich upgrade cycles for embedded systems specialists.
- Carbon accounting for imported electricity:EU CBAM-equivalent mechanisms for power trade create compliance engineering demand at cross-border interconnectors.
Industry Challenges
- Physics-software hybrid talent scarcity:Grid simulation engineers with both power systems expertise and cloud architecture skills command premium compensation that erodes project profitability.
- NERC CIP-ENTSO-E dual certification timelines:Engineering service providers pursuing transatlantic contracts face 18-24 month compliance validation cycles.
- Legacy asset data migration:Brownfield offshore wind farms require manual digitization of decades-old maintenance records before predictive analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy ESO Market |
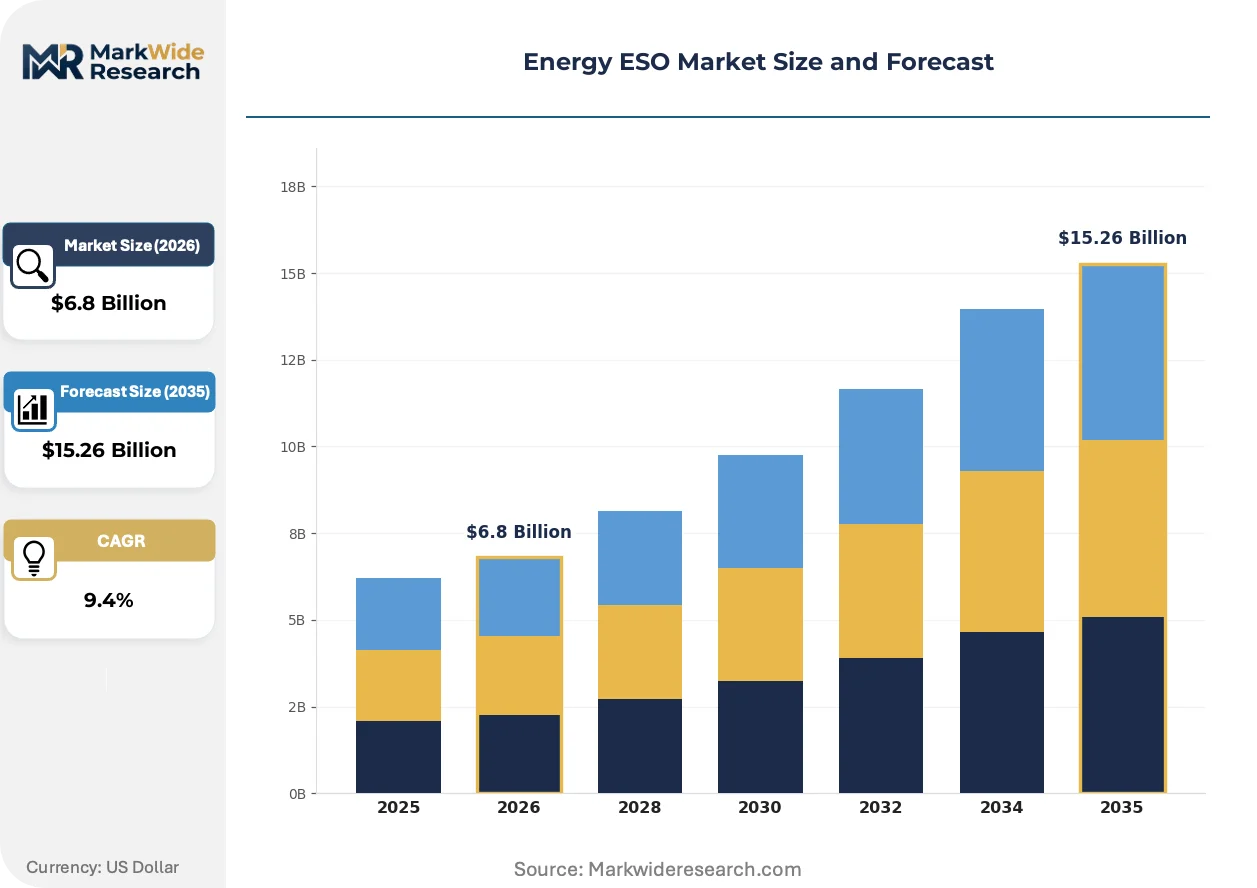
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Engineering, Asset Management, Outsourcing Application: Load Forecasting, Grid Management, Renewable Integration, Demand Response End User: Utilities, Independent Power Producers, Government, Industrial Users Installation: Onshore, Offshore, Distributed Generation, Centralized Generation |
| Companies Covered | Altair Engineering Inc., Alten Group, Capgemini Engineering, Jacobs Engineering, Cyient Limited, Luxoft Holding Inc., Assystem S.A., Quest Global Services Pte. Ltd., Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy ESO Market Strategic Shifts & Innovations
Service delivery models are pivoting from discrete project contracts toward continuous engineering subscriptions anchored by live asset data streams and automated performance optimization.
Digital twin platforms are hybridizing physics-based simulation with real-time SCADA feeds to enable predictive turbine maintenance. Offshore wind operators in the North Sea cluster now deploy these systems across entire lease areas rather than individual assets. The technology is compressing traditional inspection cycles from quarterly manual visits to continuous remote monitoring, displacing rope-access engineering hours with software-driven anomaly detection.
EU Green Deal implementation through national renewable auction designs now mandates integrated engineering and asset management service bundles. Germany's Bundesnetzagentur enforces this through grid code compliance requirements that disqualify standalone design-only bidders. Danish and Dutch tender authorities have replicated this structure, consolidating vendor relationships around full-lifecycle accountability.
Buyers now unbundle engineering specifications from construction execution, issuing separate RFPs for front-end design and EPC management. Independent power producers in competitive renewable auctions favor this model to retain intellectual property over optimized layouts. The pattern is most pronounced in German offshore wind rounds where developers internalize design risk while outsourcing fabrication oversight.
Energy ESO Market Segmentation
Energy ESO segmentation reveals starkly different contract lifecycles across service types, with consulting engagements turning over in 6-12 months while asset management agreements lock in 25-year horizons. Application segments show equally divergent renewal patterns as grid management contracts extend while demand response procurement cycles compress.
Service Type:
Consulting contracts cycle fastest at 6-18 months, while asset management agreements stretch across decades with embedded escalation clauses and performance guarantees.
- Consulting:Front-end technical advisory covering grid investment restructuring and renewable portfolio planning. German utilities Bundestag-mandated network development plans drive recurring procurement of transmission expansion studies. Consulting dominates installed base. Asset Management is where expansion concentrates.
- Engineering:Design engineering spans turbine layout optimization, substation automation specification, and HVDC converter station detailing. Danish offshore wind tendering bundles 25-year engineering accountability into connection agreements. Engineering dominates installed base. Consulting is where expansion concentrates.
- Asset Management:Lifecycle stewardship governed by ISO 55000 standards, encompassing predictive maintenance, spare parts logistics, and performance guarantee enforcement. North Sea cluster operators now mandate continuous engineering subscriptions rather than discrete inspection contracts.
- Outsourcing:Operational transfer of SCADA monitoring, control room staffing, and emergency response protocols. Independent power producers in Texas ERCOT and California CAISO markets favor outsourcing to meet NERC CIP compliance without captive cyber-physical security teams.
Consulting commands the largest share of current revenue. Asset Management is climbing the fastest as EU Green Deal tender designs mandate bundled lifecycle accountability.
Application:
Cost tier stratification separates high-investment grid infrastructure from software-driven optimization layers that require minimal capital deployment.
- Renewable Integration:Inverter interoperability studies, hybrid storage coupling designs, and grid code compliance validation for solar-wind-battery hybrids. German Bundesnetzagentur enforcement disqualifies projects lacking certified integration engineering. Renewable Integration dominates installed base. Demand Response is where expansion concentrates.
- Grid Management:Substation automation specification, protection coordination studies, and wide-area monitoring system deployment per IEC 61850 protocols. ENTSO-E network codes fragment implementation timelines across European transmission system operators.
- Load Forecasting:Probabilistic demand modeling integrating behind-the-meter solar, electric vehicle charging patterns, and industrial process electrification. Texas and California independent system operators now require 15-minute granularity in interconnection studies.
- Demand Response:Aggregation platform engineering, telemetry integration, and wholesale market bidding system design following FERC Order 2222 mandates. US distributed resource participation rules expand addressable engineering scope for demand-side technology providers.
Grid Management anchors the highest contract values. Demand Response is gaining share fastest as wholesale market reforms unlock new revenue streams.
End User:
Customer type determines procurement sophistication, with utilities favoring multi-year frameworks and independent power producers demanding milestone-based deliverables tied to financial close.
- Utilities:Vertically integrated network operators procuring integrated engineering and asset management under regulatory cost-recovery mechanisms. German transmission system operators TenneT and 50Hertz bundle North Sea connection engineering into regulated asset base calculations.
- Independent Power Producers:Competitive renewable developers requiring discrete design and EPC management RFPs to retain intellectual property over optimized layouts. Danish and German offshore wind auctions favor unbundled procurement to internalize layout risk.
- Government:National renewable auction authorities mandating service bundles through tender design rather than direct procurement. EU Green Deal national implementation plans reshape market access by tightening carbon accounting requirements.
- Industrial Users:Large electricity consumers seeking behind-the-meter engineering for captive solar-plus-storage and demand response participation. California and Texas industrial load centers drive retrofit engineering for IRA production tax credit eligibility.
Utilities command the longest contract tenures. Independent Power Producers are expanding most quickly as competitive auction volumes accelerate.
Installation:
Geographic concentration of engineering talent creates supply-side bottlenecks that segment pricing and availability.
- Offshore:Fixed-bottom and floating wind foundation design, array cable routing, and HVDC platform specification. Hamburg and Copenhagen engineering clusters concentrate specialized talent, creating wage inflation and recruitment bottlenecks for project developers.
- Onshore:Solar and wind farm civil works, electrical collection system design, and substation integration. US interconnection queue backlogs in ERCOT and CAISO stretch engineering delivery timelines to 24-36 months.
- Distributed Generation:Commercial and industrial rooftop solar, battery energy storage systems, and microgrid control architecture. FERC Order 2222 mandates drive grid connection engineering for aggregated distributed resources.
- Centralized Generation:Combined-cycle gas turbine repowering, nuclear life extension, and large-scale pumped hydro engineering. Brownfield asset data migration requirements delay predictive analytics deployment across decades-old maintenance records.
Onshore holds the largest project volume. Offshore is expanding most quickly as North Sea cluster developments accelerate tendering rounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering consultancies export integrated offshore wind design services to Danish and Dutch developers bidding into North Sea cluster auctions. This trade corridor concentrates specialized talent in Hamburg and Copenhagen while shaping procurement patterns across Northern Europe.
United States
Texas ERCOT and California CAISO interconnection queues drive demand for distributed resource grid connection engineering. FERC Order 2222 mandates wholesale market participation for aggregated solar-plus-storage assets. Houston and Austin engineering clusters specialize in NERC CIP compliance certification for independent power producers.
Germany
Offshore wind tendering bundles 25-year engineering accountability into grid connection agreements under Bundesnetzagentur enforcement. EU Green Deal national implementation plans tighten carbon accounting for imported electricity. Hamburg anchors the North Sea engineering cluster where wage inflation pressures project margins.
Denmark
Floating wind foundation design and HVDC platform specification attract specialized consultancies from across Northern Europe. National renewable auction designs replicate German tender structures mandating integrated service bundles. Copenhagen engineering pools concentrate physics-software hybrid talent for predictive maintenance platforms.
United Kingdom
Scotland's offshore wind leasing rounds require grid code compliance validation from engineering service providers. The country's net-zero targets accelerate demand for brownfield asset data migration and predictive analytics deployment. Aberdeen and Edinburgh clusters compete for North Sea project engineering mandates.
Netherlands
IJmuiden and Rotterdam harbor zones host engineering firms specializing in array cable routing and substation automation specification. Dutch tender authorities mandate integrated engineering and asset management bundles mirroring German structures. Cross-border interconnector projects create compliance engineering demand at Belgian and German tie-points.
Energy ESO Market Key Industry Players
On the supply side, the industry is consolidating around full-lifecycle accountability models that bundle front-end design with decades-long asset management obligations. Tier-one engineering conglomerates compete against specialized consultancies through differentiated technology stacks rather than price alone. Two strategic archetypes dominate: physics-based simulation specialists and embedded systems integrators. M&A activity targets SCADA modernization capabilities while strategic partnerships secure cloud-native digital twin deployment capacity.
Among US-based engineering conglomerates, Jacobs Engineering occupies a position exemplifying scale-driven EPC integration. French-origin specialists Assystem S.A. and Alten Group represent the European consultancy archetype with deep embedded systems heritage. Indian-origin technology services firms Wipro and Cyient Limited anchor the offshore delivery model for grid automation and predictive maintenance platforms.
| Leading Market Players |
|---|
| Altair Engineering Inc. |
| Alten Group |
| Capgemini Engineering |
| Jacobs Engineering |
| Cyient Limited |
| Luxoft Holding Inc. |
| Assystem S.A. |
| Quest Global Services Pte. Ltd. |
| Wipro |
| Others |
Cost & Logistics Intelligence
Hamburg and Copenhagen engineering clusters concentrate specialized offshore wind talent, creating wage inflation that propagates through project bids and compresses mid-tier consultancy margins. Bundesnetzagentur-mandated grid code compliance requirements force buyers toward bundled 25-year service contracts, shifting pricing power toward full-lifecycle providers.
Pricing Analysis
Legacy SCADA modernization services command premium rates against cloud-native digital twin deployments that undercut physics-based simulation pricing through subscription economics. Three-tier pricing structure across premium physics-engineering boutiques, standard systems integrators, and economy offshore delivery centers differentiates contract values. Cost compression in standard-tier engineering consultancy is intensifying because specialized simulation software licensing burdens erode project profitability. Independent power producers exhibit highest price sensitivity during competitive auction phases, while utilities under regulatory cost-recovery mechanisms absorb premium pricing for compliance-certain delivery.
Supply Chain Analysis
High-fidelity simulation software licensing draws from US and European technology vendors, while embedded systems engineering talent feeds from Indian and Eastern European delivery centers. Critical inputs span physics-based modeling platforms, IEC 61850 protocol stacks, and cloud-native data infrastructure. Single-source vulnerability concentrates in North Sea cluster engineering pools where Hamburg and Copenhagen wage inflation creates recruitment bottlenecks. Distribution runs through multi-year framework agreements with transmission system operators and discrete milestone-based contracts with independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy ESO markets approach a platform-economics inflection as cloud-native digital twin interoperability supplants discrete project contracting, driven by EU Green Deal national implementation plans mandating continuous asset data streams.
For Market Incumbents: Insulate core margins by acquiring SCADA modernization specialists before cloud-native entrants capture upgrade cycles, and deepen captive supply of physics-software hybrid talent through Hamburg and Copenhagen graduate pipeline partnerships. Altair Engineering and Capgemini Engineering demonstrate how embedded systems expertise anchors defensive positioning against pure-play digital twin vendors. For New Entrants and Emerging Players: Pursue US distributed solar-plus-storage retrofit engineering where IRA production tax credit extensions stretch interconnection queue timelines and incumbent capacity is committed to offshore wind. Texas ERCOT and California CAISO markets present penetrable white space for NERC CIP compliance-as-a-service offerings targeting independent power producers without captive cyber-physical security teams. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified engineering conglomerates seeking to divest non-core energy asset management units as EU Green Deal tender designs force full-lifecycle accountability investments. Engineering service providers with dual NERC CIP-ENTSO-E certification capabilities represent priority acquisition archetypes. Watch for Bundesnetzagentur grid code enforcement tightening as signal that compliance-engineering premiums are structural rather than cyclical.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Digital Twin Integration | Physics-based simulation vendors like Altair Engineering anchor turbine optimization through high-fidelity modeling platforms. |
| SCADA Modernization Platform Buildout | Capgemini Engineering leverages embedded systems heritage to capture edge computing convergence with legacy control infrastructure. |
| Dual Certification Capability Investment | Engineering providers pursuing transatlantic contracts compress 18-24 month NERC CIP-ENTSO-E validation timelines through dedicated compliance teams. |
| North Sea Talent Pipeline Partnerships | Hamburg and Copenhagen engineering clusters face recruitment bottlenecks that favor early university alliance formations. |
| Continuous Engineering Subscription Pivot | Offshore wind operators now mandate live data stream contracts displacing quarterly manual inspection procurement. |
Research Approach
Operator-level perspectives from utility planning officers, independent power producer project developers, EPC contractors, and grid operators anchored the qualitative base, triangulated against EIA data, IEA reports, FERC filings, and project development databases. Secondary validation drew from SEC filings of listed engineering conglomerates and ENTSO-E network code implementation tracking. Bottom-up project pipeline aggregation and top-down regulatory impact modeling converged on segment-level demand estimates.
Scenario-bracketing framed low-base-high demand trajectories across the projection horizon, with segmentation dimensions spanning service type, application, end user, and installation configuration. CAGRs derived from capacity-weighted project timelines and regulatory mandate enforcement schedules. Forecast inputs incorporated Bundesnetzagentur tender calendar pacing and FERC Order 2222 implementation variance across US independent system operators.
Sensitivities concentrate around EU Green Deal national implementation plan acceleration or delay, NERC CIP enforcement intensity fluctuations, and physics-software hybrid talent availability shocks. Forecasts reflect documented assumptions regarding regulatory mandate timelines and technology substitution rates. Cross-checking against IEA renewable capacity deployment benchmarks and FERC interconnection queue data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Thermostat Market
Energy Management
Microgrid Control System Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Industrial Energy Management System Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Power SCADA Market
Energy Management
Energy Management Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Connected Energy Market
Energy Management
Global Energy Consumption Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Energy Security Market