
 Power SCADA Market | 2026-2036
Power SCADA Market Size, Share, and Industry Trends Forecast 2026-2036
Power SCADA Market Analysis
A widening capability gap between integrated platform providers and point-solution vendors is unwinding competitive dynamics across the Power SCADA landscape. Siemens AG leverages its digital grid software stack to anchor large-scale transmission projects across European utilities. ABB Ltd. competes through its Ability platform, which specializes in substation automation and remote terminal unit integration. Honeywell International Inc. extends its industrial software footprint by controlling hybrid deployment architectures that blend on-premise reliability with cloud analytics.
Power SCADA denotes supervisory control and data acquisition systems engineered for electrical grid monitoring, typically integrating remote terminal units, programmable logic controllers, and human-machine interfaces operating across IEC 61850 and DNP3 communication protocols to enable real-time visualization and automated response for generation, transmission, and distribution networks. The technology dimension shows distributed control systems occupying mature margin pools in baseload fossil generation, while IoT integration represents the fastest-expanding segment as sensor proliferation and edge analytics reshape grid visibility. Within application categories, smart grids command premium pricing due to bidirectional communication requirements, though renewable energy installations generate disproportionate growth as wind and solar assets multiply across decentralized architectures.
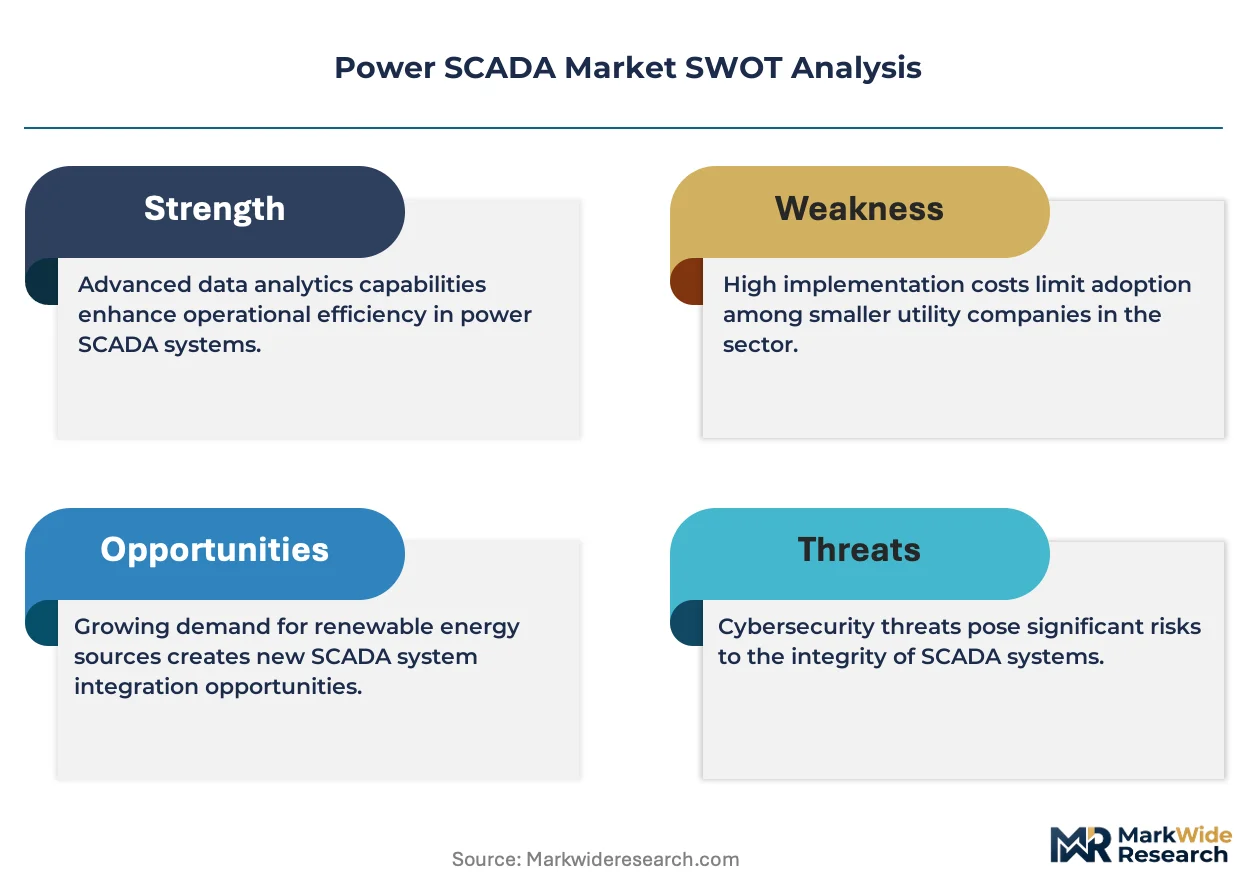
The Federal Energy Regulatory Commission enforces NERC CIP standards that mandate cybersecurity hardening for bulk electric system assets, compelling US utilities to replace aging SCADA infrastructure with encrypted, access-controlled platforms. In Europe, the EU Cybersecurity Act and IEC 62351 standards impose comparable product certification burdens on vendors seeking grid operator procurement eligibility. Stakeholders must weigh the capital requirements of cloud-native architectures against the operational continuity demands that still favor hybrid deployment models in critical infrastructure environments.
Market Dynamics
Grid operators face irreconcilable pressure between NERC CIP cybersecurity mandates and the operational continuity demands of legacy infrastructure. The resulting deployment friction is restructuring vendor relationships and procurement timelines across transmission and distribution utilities.
Growth Catalysts
- NERC CIP-013:Supply chain security standards in the United States compel utilities to replace aging remote terminal units with encrypted, access-controlled platforms.
- Distributed solar proliferation:Rooftop photovoltaic installations in Germany require bidirectional SCADA visibility to manage voltage fluctuation and reverse power flow.
- Edge computing architectures:Substation-hardened processors enable millisecond response times for fault isolation without cloud dependency.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries control advanced chip fabrication for industrial-grade programmable logic controllers, creating procurement bottlenecks.
- Copper and rare earth volatility:Magnet and wiring material costs swing unpredictably, compressing margins on hardware-heavy deployments.
- IEC 61850 Edition 2.1 compliance timelines:Certification delays in Europe extend sales cycles by six to eighteen months for non-compliant vendors.
Strategic Opportunities
- India grid modernization:The country's national power regulator mandates smart metering and distribution automation under the National Smart Grid Mission.
- Digital twin convergence:Physics-based simulation layered atop real-time SCADA data enables predictive maintenance for offshore wind farms.
- Subscription-based software licensing:Recurring revenue models displace perpetual licenses among municipal utilities with constrained capital budgets.
Industry Challenges
- Cybersecurity workforce scarcity:Industrial control system security expertise concentrates among defense contractors, forcing utilities into bidding wars for qualified engineers.
- Multi-protocol integration complexity:DNP3, IEC 61850, and proprietary legacy systems require costly middleware development for unified visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power SCADA Market |
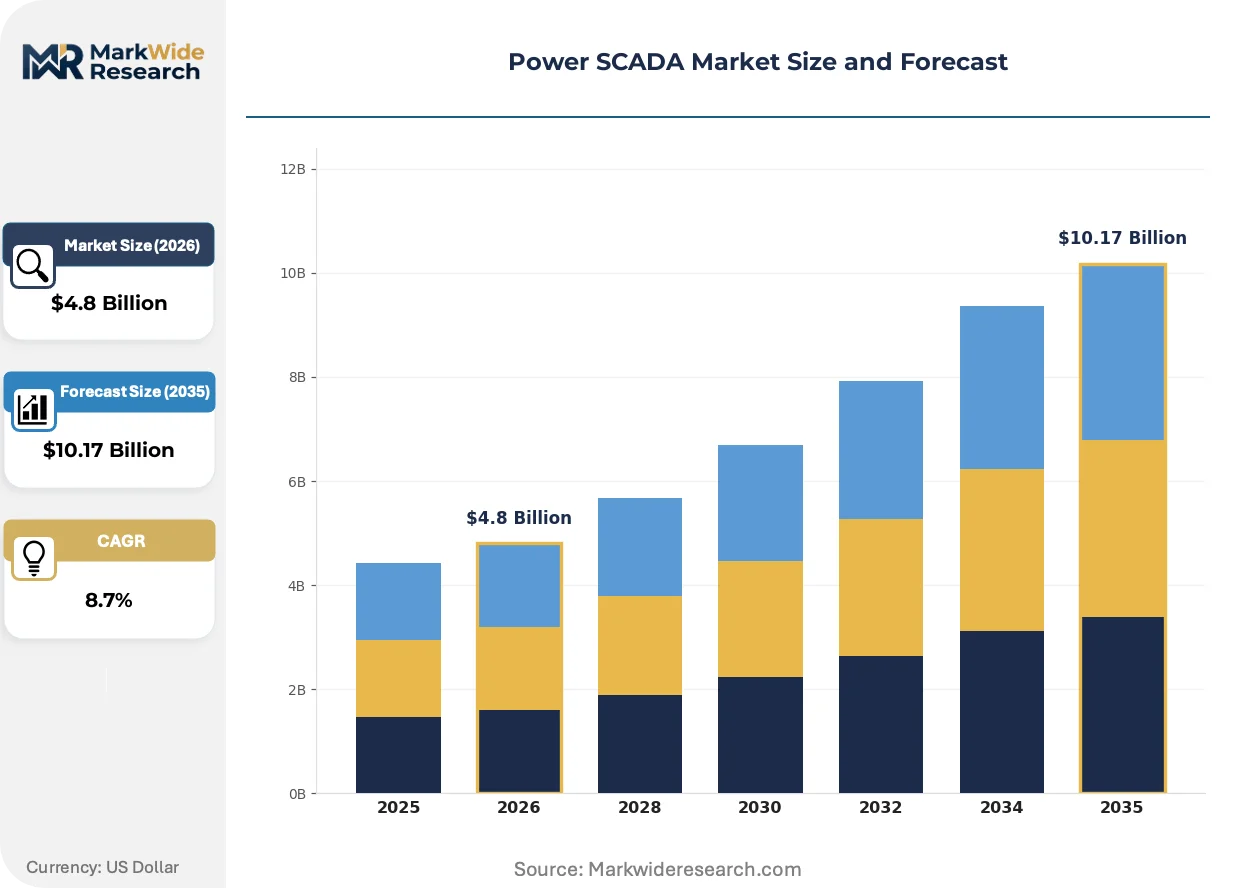
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Supervisory Control, Distributed Control, Remote Terminal Units, IoT Integration Application: Transmission Systems, Distribution Systems, Renewable Energy, Smart Grids End User: Utilities, Industrial Facilities, Renewable Installations, Commercial Buildings Deployment: On-premise, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Rockwell Automation Inc., Honeywell International Inc., Siemens AG, Yokogawa Electric Corporation, General Electric Company, ABB Ltd., Emerson Electric Co., Eaton Corporation plc, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power SCADA Market Emerging Trajectories
SCADA architecture is splitting between cloud-native analytics platforms and air-gapped operational technology networks. This divergence is fragmenting vendor roadmaps and forcing buyers into explicit trade-offs between innovation velocity and attack surface minimization.
Edge-native artificial intelligence is bifurcating the market for grid analytics. Machine learning inference engines deployed directly at substations enable real-time anomaly detection without latency penalties. European transmission system operators are piloting these architectures for predictive equipment failure identification. The technology is bifurcating procurement patterns, with large utilities favoring integrated platform stacks while smaller cooperatives adopt modular, best-of-breed sensor arrays.
The EU Cybersecurity Act and accompanying IEC 62351 certification requirements are hardening product development cycles for grid software vendors. Manufacturers must now submit to third-party security evaluation before procurement eligibility. German and French distribution system operators have accelerated replacement schedules to meet these deadlines, prioritizing certified platforms over lower-cost uncertified alternatives.
Utility procurement departments are unbundling hardware, software, and service contracts that historically shipped as integrated packages. Municipal and cooperative buyers now negotiate separate agreements for remote terminal units, human-machine interface licenses, and cybersecurity monitoring. This pattern is most pronounced in North American utilities facing rate-base scrutiny from public utility commissions, where capital expenditure transparency has become a regulatory priority.
Power SCADA Market Segmentation
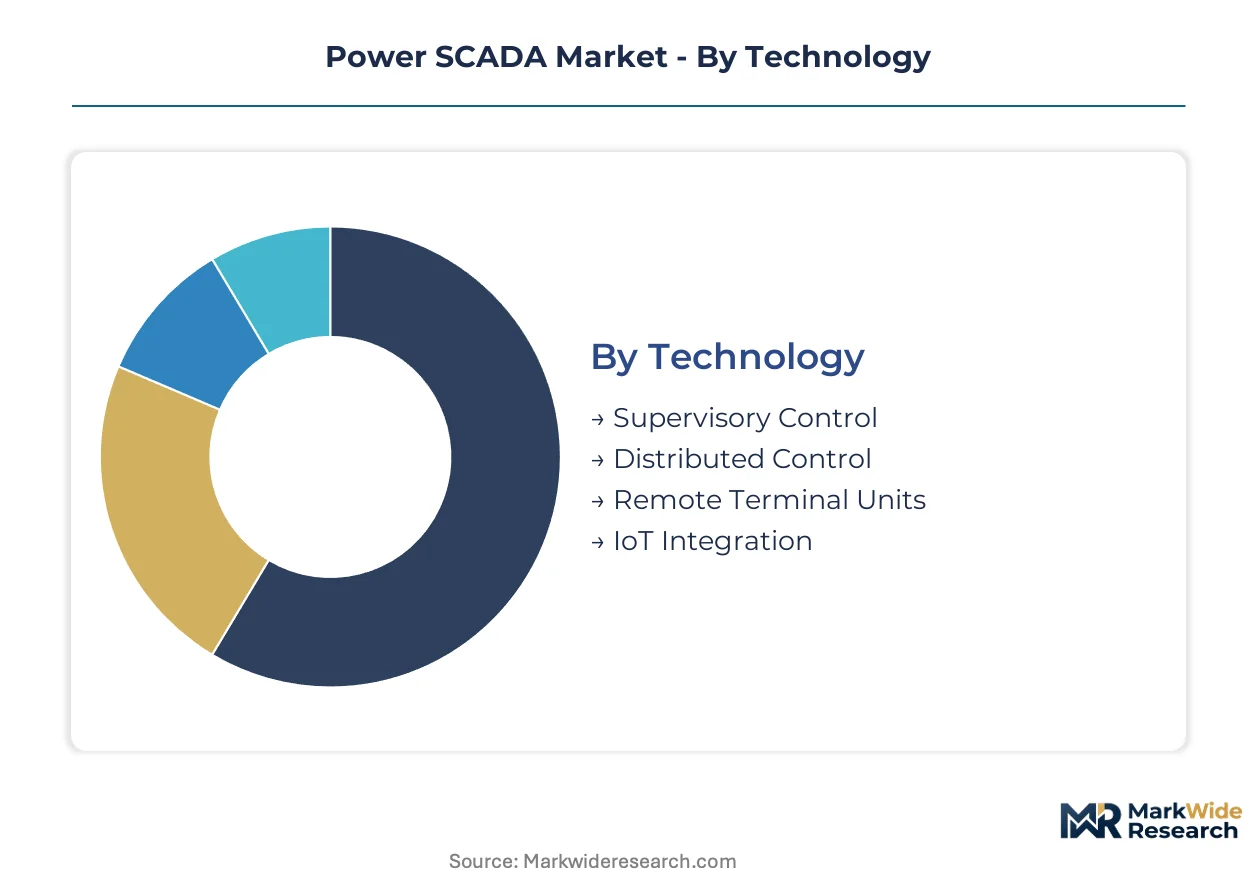
Segmentation in the Power SCADA Market reveals divergent margin structures across technology maturity curves. Procurement patterns fragment sharply between regulated utilities prioritizing compliance and commercial operators optimizing for cost efficiency.
Technology:
Margin pools concentrate in integrated platform stacks rather than discrete hardware components, with software-defined architectures commanding premium pricing over legacy equipment.
- IoT Integration:Sensor networks and edge analytics platforms enable granular asset visibility across distributed generation assets. Demand concentrates in Germany's Energiewetz modernization zones, where voltage fluctuation management requires bidirectional data flows from rooftop solar installations.
- Supervisory Control:Centralized command platforms integrate human-machine interfaces with programmable logic controllers for real-time grid visualization. North American utilities facing FERC-mandated cybersecurity hardening drive replacement cycles for encrypted, access-controlled architectures.
- Distributed Control:Mature margin pools persist in baseload fossil generation facilities requiring redundant control loops.
- Remote Terminal Units:Field-hardened communication endpoints bridge substation equipment to central control centers.
The dominant share belongs to Supervisory Control, while IoT Integration is closing the gap fastest.
Application:
Volume concentration follows grid investment cycles, with transmission infrastructure absorbing capital during expansion phases while distribution networks capture spend during modernization waves.
- Smart Grids:Bidirectional communication infrastructure enables real-time pricing signals and automated demand response. European distribution system operators under EU Cybersecurity Act deadlines prioritize certified platforms for advanced metering infrastructure deployments.
- Renewable Energy:Wind and solar asset management requires specialized SCADA protocols for inverter control and power forecasting. Offshore wind farms in the North Sea drive demand for predictive maintenance integration with digital twin simulations.
- Transmission Systems:High-voltage backbone networks rely on synchronized phasor measurement units for stability monitoring.
- Distribution Systems:Medium-voltage feeder automation reduces outage duration through fault isolation algorithms.
Smart Grids currently absorb the largest procurement budgets, though Renewable Energy applications are expanding most quickly.
End User:
Customer type determines contract structure, with municipal utilities favoring capital-intensive perpetual licenses and independent power producers preferring operational expenditure models.
- Utilities:Vertically integrated grid operators mandate IEC 61850 Edition 2.1 compliance for all new control system procurements. India's National Smart Grid Mission compels state electricity boards to accelerate distribution automation tenders.
- Renewable Installations:Wind farm operators and solar park developers require modular SCADA architectures that scale with asset portfolios. Procurement concentrates in utility-scale projects where financing structures favor subscription-based software licensing.
- Industrial Facilities:Cogeneration plants and manufacturing campuses integrate power management with process control systems.
- Commercial Buildings:Microgrid operators optimize behind-the-meter generation through building energy management interfaces.
Utilities retain the largest installed base, while Renewable Installations are gaining share fastest.
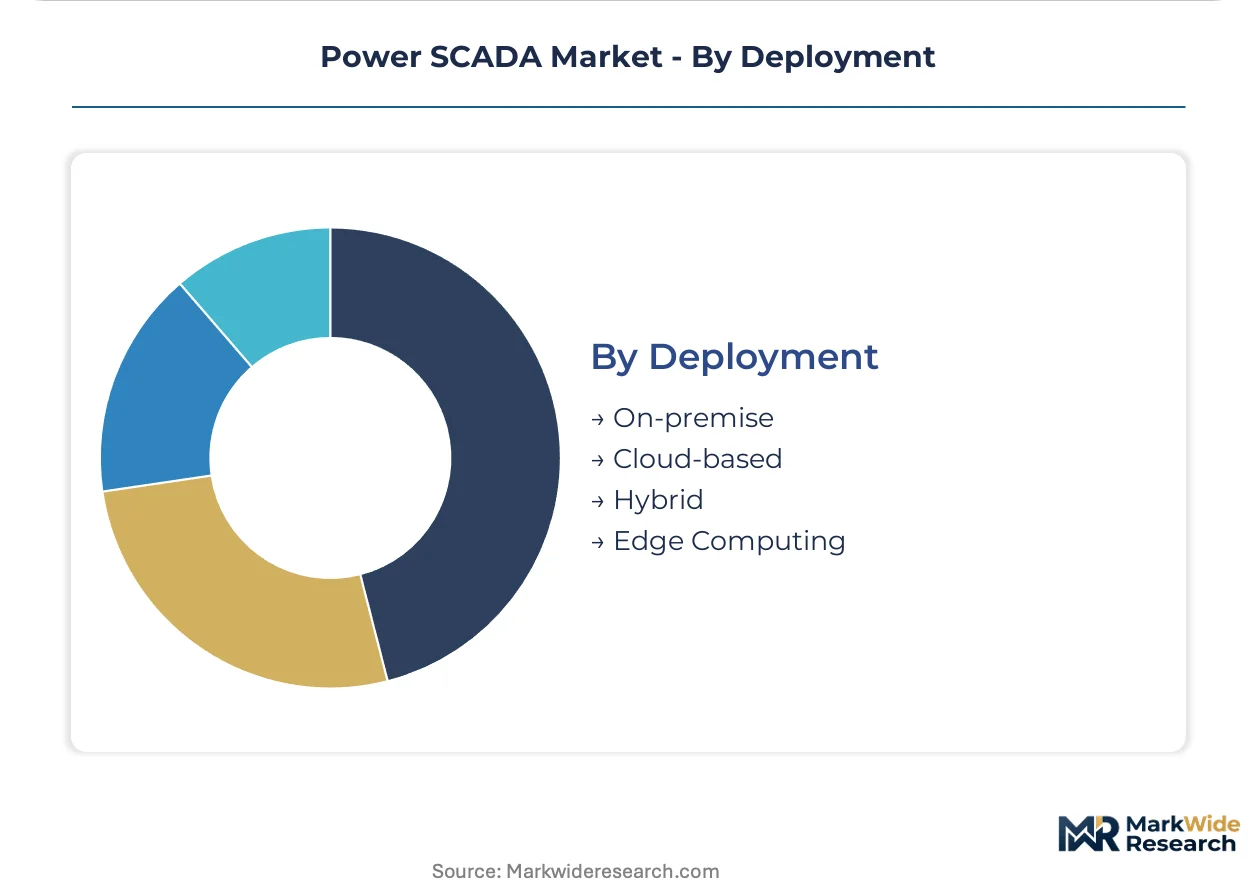
Deployment:
Architecture choice reflects risk tolerance trade-offs, with critical infrastructure operators accepting higher total cost of ownership for air-gapped security while commercial adopters prioritize cloud analytics velocity.
- Hybrid:Blended architectures combine on-premise operational continuity with cloud-based analytics for non-critical workloads. North American municipal utilities under public utility commission rate-base scrutiny favor this model for capital expenditure transparency.
- Edge Computing:Substation-hardened processors execute millisecond-response fault isolation without network dependency. European transmission system operators pilot these architectures for predictive equipment failure identification.
- On-premise:Air-gapped networks satisfy NERC CIP cybersecurity mandates for bulk electric system assets.
- Cloud-based:Fully hosted platforms appeal to smaller cooperatives with limited IT infrastructure.
Hybrid deployments command the dominant share, while Edge Computing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power SCADA equipment flows from German engineering centers and Japanese automation hubs toward infrastructure-hungry markets in India and the Middle East. Import dependency for industrial-grade processors shapes procurement timelines across developing grids. Regional regulatory divergence is fragmenting certification requirements and vendor qualification protocols.
United States
FERC-mandated NERC CIP-013 compliance drives wholesale replacement of unencrypted remote terminal units across investor-owned utilities. State regulators in Texas and California impose additional cybersecurity disclosure requirements for critical infrastructure operators. The PJM Interconnection territory concentrates deployment activity as transmission operators modernize synchronized phasor measurement infrastructure.
Germany
Energiewetz grid modernization mandates bidirectional SCADA visibility for 20 million distributed solar installations. BNetzA, the federal network agency, enforces IEC 61850 Edition 2.1 certification for all new control system procurements. The Ruhr industrial corridor hosts concentrated pilot programs for edge-native fault isolation algorithms at medium-voltage substations.
India
The Central Electricity Authority mandates smart metering and distribution automation under the National Smart Grid Mission across state electricity boards. CEA technical standards require indigenous cybersecurity certification for imported control systems. Maharashtra and Gujarat concentrate tender activity as distribution companies deploy feeder automation for rural electrification.
China
State Grid Corporation accelerates ultra-high-voltage transmission SCADA deployments to integrate remote renewable bases. MIIT cybersecurity regulations mandate domestic encryption standards for critical infrastructure control systems. The Yangtze River Delta cluster hosts indigenous PLC manufacturing capacity serving both domestic utilities and Belt and Road export markets.
Japan
METI grid resilience directives compel regional utilities to harden SCADA architectures against seismic and cyber disruptions. The Electricity Business Act amendments require enhanced operational technology monitoring for nuclear restart facilities. The Chubu region around Nagoya concentrates substation automation upgrades integrating earthquake-resistant remote terminal units.
Power SCADA Market Vendor Landscape
Concentration sits with diversified industrial conglomerates possessing integrated digital grid software stacks. The vendor landscape organizes around three strategic archetypes: European engineering conglomerates with transmission-scale project capabilities, North American industrial automation specialists with hybrid cloud architectures, and Japanese precision electronics manufacturers with substation-hardened hardware. Competitive dynamics center on strategic partnerships for edge computing integration and geographic expansion through localized certification compliance.
Among European-based engineering groups, Siemens AG and ABB Ltd. occupy positions exemplifying platform-centric competitive strategy. Honeywell International Inc. represents the North American industrial automation archetype with hybrid deployment architectures. These three entities anchor the competitive structure, with diversified conglomerates leveraging cross-divisional software integration against specialized vendors focused on discrete hardware components.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Siemens AG |
| Yokogawa Electric Corporation |
| General Electric Company |
| ABB Ltd. |
| Emerson Electric Co. |
| Eaton Corporation plc |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Ninety-day semiconductor lead times for industrial-grade programmable logic controllers tether pricing power to Taiwanese foundry capacity allocation, compressing margins for hardware-dependent deployments while amplifying premiums for software-defined architectures.
Pricing Analysis
Configured-to-order SCADA platforms command 40-60% premiums over standard catalog configurations due to IEC 61850 Edition 2.1 certification requirements and site-specific cybersecurity hardening. Subscription-based SaaS licensing is displacing perpetual licenses among municipal utilities with constrained capital budgets. Price differentiation hinges on cybersecurity certification tier and geographic delivery cost, with NERC CIP-compliant platforms capturing premium positioning. Cost compression in hardware-heavy segments intensifies due to copper and rare earth magnet volatility, while integrated platform vendors face lower price sensitivity from transmission-scale utilities.
Supply Chain Analysis
Port congestion on transpacific lanes and container availability constraints inflate inbound logistics costs for European utilities sourcing substation-hardened processors from East Asian manufacturing clusters. Supply concentrates in Taiwan for advanced industrial semiconductors, Germany for precision engineering components, and China for remote terminal unit assembly. The chain draws from copper wiring, rare earth magnets, and silicon carbide substrates. Single-source vulnerability in Taiwanese foundry capacity for automotive-grade chips creates structural procurement risk. Distribution runs through authorized system integrators and direct OEM relationships with national utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source SCADA frameworks and cloud-native industrial IoT platforms threaten incumbent pricing power, forcing established vendors to demonstrate substitution-resistant value through certification depth and operational continuity guarantees.
For Market Incumbents: Compound platform stickiness by embedding IEC 62351 security certification into core software stacks, raising switching costs for European distribution system operators facing compliance deadlines. Deepen backward integration into edge computing hardware to capture margin pools migrating from discrete RTU sales toward integrated substation automation. Prioritize hybrid deployment architectures that blend on-premise reliability with cloud analytics, defending against pure-play SaaS entrants targeting municipal utilities.
For New Entrants and Emerging Players: Lead with modular, best-of-breed sensor arrays targeting smaller North American electric cooperatives underserved by integrated platform vendors. White-space concentration sits in India's National Smart Grid Mission tender pipeline, where indigenous cybersecurity certification requirements favor local system integrators over foreign OEMs. Pursue subscription-based licensing models that align with cooperative capital constraints and public utility commission rate-base transparency demands.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because NERC CIP and EU Cybersecurity Act compliance burdens create durable moats around certified platform vendors. Target acquisition profiles center on edge-native AI specialists with substation-hardened inference engines, particularly those holding pilot contracts with European transmission system operators. The signal to watch is certification backlog duration—extended IEC 61850 Edition 2.1 approval timelines indicate vendor qualification bottlenecks that concentrate market share among incumbent engineering conglomerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Siemens AG leverages digital grid software stacks to anchor large-scale transmission projects across European utilities. |
| Certification Investment | Third-party IEC 62351 security evaluation submission secures procurement eligibility for German and French distribution system operators. |
| Hybrid Deployment Architecture | Honeywell International Inc. controls blended on-premise and cloud analytics models for municipal utilities under rate-base scrutiny. |
| Edge Computing Partnership | Substation-hardened processor integration enables millisecond-response fault isolation for European transmission pilots. |
| Geographic Expansion | Localized certification compliance in India under CEA technical standards opens National Smart Grid Mission tender access. |
Methodological Framework
The analysis maps supervisory control platforms, IoT integration architectures, and distributed control systems, each validated through utility planning officers, grid operators, EPC contractors, and industrial cybersecurity specialists. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA data, IEA grid modernization reports, and IEC standard documentation. Bottom-up segmentation sizing triangulated with top-down market aggregate checks ensures internal consistency.
Consistency checks validated volume and value outputs against external benchmarks including utility capital expenditure disclosures and vendor order backlog reports. The analytical framework models technology type, application category, end-user archetype, and deployment architecture across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles and forward regulatory mandate timelines incorporate renewable asset proliferation rates and cybersecurity compliance deadlines as industry-specific inputs.
Forecasts assume regulatory continuity in NERC CIP enforcement and EU Cybersecurity Act implementation; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as semiconductor supply concentration and rare earth commodity volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Heat Meter Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Brazil Energy Sector Market
Energy Management
Microgrid Control System Market
Energy Management
Energy Harvesting System Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Energy Security Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Energy Management Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Australia Energy-As-A-Service Market