
 Thermostat Market | 2026-2036
Thermostat Market Size, Share, and Industry Trends Forecast 2026-2036
Thermostat Market Analysis
Wi-Fi-enabled specification tiers is bifurcating the thermostat landscape into connected and legacy product lines. Honeywell International Inc. leverages its building automation heritage to sustain commercial channel dominance. ecobee Inc. specializes in voice-integrated residential platforms that compete against Alphabet Inc.'s Google Nest ecosystem.
A thermostat is an electromechanical or solid-state device that senses ambient temperature and actuates heating, ventilation, or air conditioning equipment to maintain a setpoint, typically operating within precision ranges of ±0.5°C to ±2°C depending on application grade. Smart thermostats incorporating machine learning algorithms and occupancy sensing now command the fastest expansion trajectory among product types, while programmable units retain cost-sensitive residential segments. Professional installation channels capture higher-margin commercial projects, whereas DIY wireless systems penetrate the retrofit residential base.
The U.S. Department of Energy's appliance efficiency standards and the EU F-Gas Regulation shape product design requirements across North America and Europe, with China's GB standards adding a third compliance layer for manufacturers targeting Asia-Pacific assembly. Stakeholders must monitor how building electrification mandates in multiple jurisdictions redefine thermostat integration with heat pump systems and grid-responsive demand management protocols.
Market Dynamics
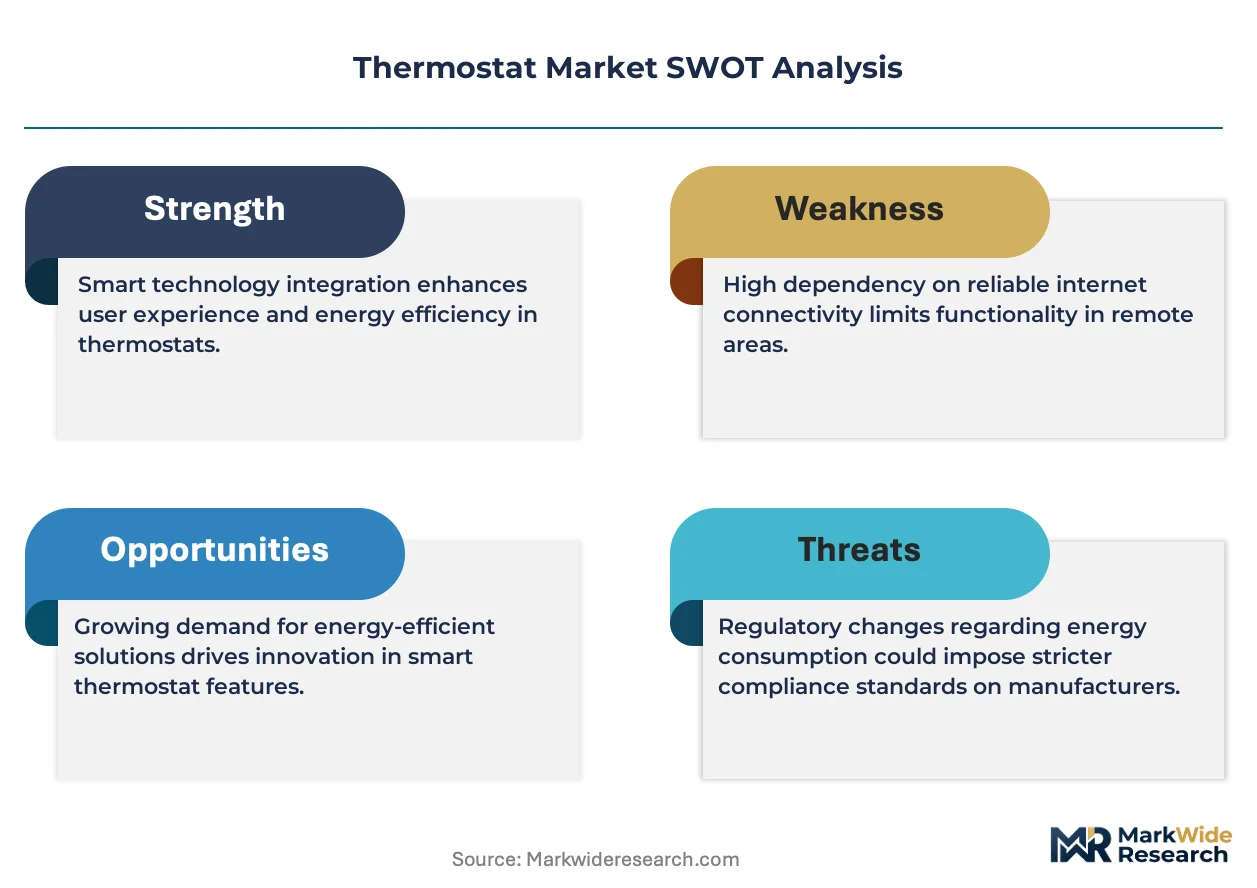
The thermostat market is experiencing fundamental restructuring as building electrification mandates force tighter integration between climate control systems and heat pump infrastructure, compressing legacy standalone product lifecycles.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants accelerates heat pump deployment across European residential retrofits, expanding addressable thermostat demand for compressor-driven systems.
- Machine learning occupancy sensing:Algorithmic temperature prediction reduces HVAC runtime by 10-15% in field deployments, creating measurable utility bill savings that justify premium hardware procurement.
- China's smart city construction:Municipal building automation mandates in tier-one urban centers generate concentrated demand for networked climate management infrastructure.
Market Restraints
- Semiconductor supply concentration:Wi-Fi and Bluetooth module fabrication concentrates in Taiwan and South Korea, exposing thermostat manufacturers to foundry allocation volatility.
- Copper and lithium price volatility:Battery-backed thermostat designs face input cost pressure from commodity swings in electrochemical storage materials.
- Legacy HVAC incompatibility:Two-wire furnace control systems in 40 million US homes lack the common wire required for smart thermostat power, forcing expensive electrical upgrades.
Strategic Opportunities
- Grid-responsive demand management:FERC Order 2222 enables aggregated thermostat fleets to bid into wholesale electricity markets, creating recurring software revenue streams.
- India's Bureau of Energy Efficiency appliance labeling:Mandatory efficiency ratings for room air conditioners will extend to thermostats, favoring certified connected products in price-sensitive segments.
- Voice-integrated residential platforms:Convergence of natural language processing with HVAC control creates differentiation in premium home automation ecosystems.
Industry Challenges
- Embedded systems firmware security:IoT thermostat vulnerabilities require continuous patching cycles that strain OTA update infrastructure and customer support bandwidth.
- Multi-protocol integration complexity:Simultaneous support for Matter, Zigbee, Z-Wave, and proprietary HVAC bus standards fragments engineering resources and extends certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermostat Market |
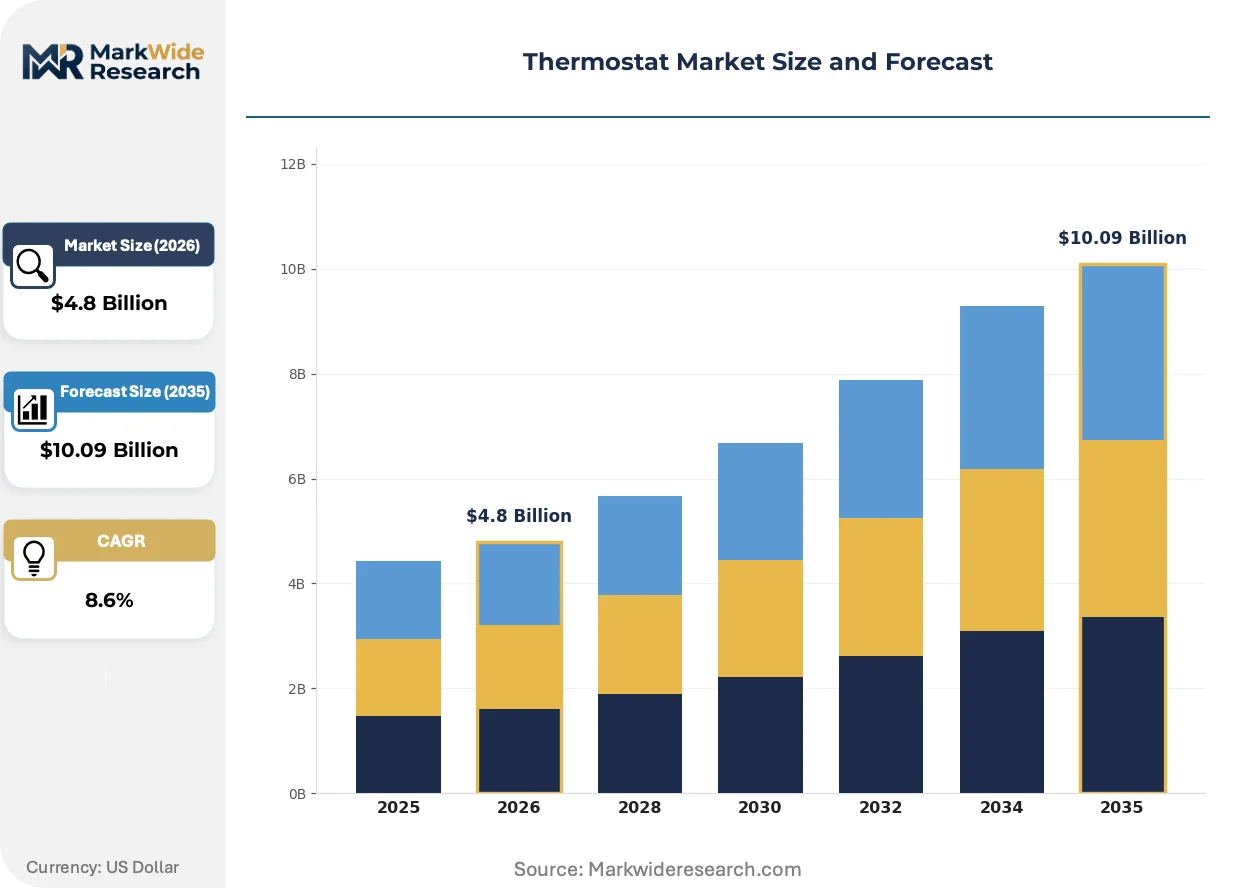
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostat, Focusing Thermostat, Programmable Thermostat, Non-Programmable Thermostat Installation Type: DIY Installation, Professional Installation, Wireless Systems, Wired Systems End User: Residential Users, Commercial Establishments, Industrial Facilities, Educational Institutions Control Technology: Wi-Fi Enabled, Z-Wave Compatibility, Zigbee Technology, Bluetooth Connectivity |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., ecobee Inc., Carrier Corporation, Alphabet Inc. (Google Nest), Resideo Technologies Inc., Lennox International Inc., Johnson Controls, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermostat Market Emerging Trajectories
Wi-Fi specification tiers are fragmenting the thermostat landscape into distinct performance classes. Manufacturers now face architectural choices between cloud-dependent processing and edge-based autonomy.
Geofencing and presence inference algorithms are fragmenting residential thermostat functionality away from fixed scheduling toward adaptive behavioral prediction. Multi-family housing operators in Germany and the Netherlands deploy these systems to reduce common-area heating costs. The technology compresses margins on basic programmable units while expanding service attach rates for predictive maintenance subscriptions.
The EU F-Gas Regulation's 2030 phase-down targets force refrigerant transitions that alter thermostat setpoint logic for heat pump optimization. Equipment manufacturers must redesign defrost cycle coordination and auxiliary heat lockout parameters. Residential installers in Nordic countries face the steepest learning curves as air-to-water systems displace gas boilers.
Utility rebate programs now bundle thermostat procurement with weatherization audits, compressing traditional retail channel volumes. This procurement consolidation favors direct OEM relationships with municipal energy providers. California's SGIP and New York's NYSERDA programs demonstrate how regulated incentive structures reshape distribution economics away from big-box retail.
Thermostat Market Segmentation
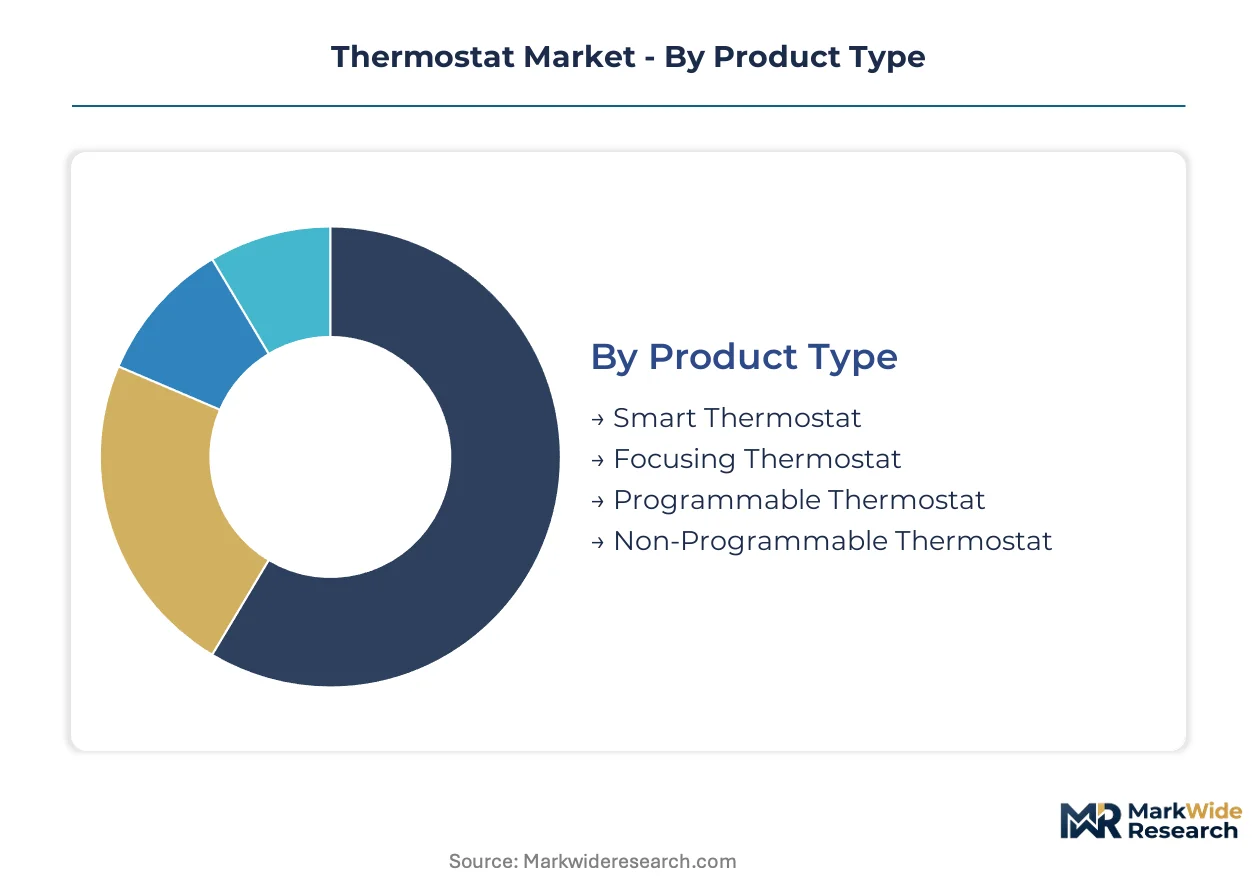
Thermostat segmentation reflects divergent substitution pressures across the technology spectrum. Smart platforms displace legacy electromechanical units in premium residential retrofits, while basic non-programmable devices retain footholds in cost-constrained replacement cycles and rental housing stock.
Product Type:
Smart thermostats face the steepest substitution threat from voice-integrated home automation ecosystems, while programmable and non-programmable units compete primarily on upfront hardware cost against connected alternatives.
- Smart Thermostat:Solid-state devices incorporate machine learning occupancy sensing and geofencing algorithms that reduce HVAC runtime through predictive temperature management. Demand concentrates in Germany's building retrofit sector and China's tier-one smart city construction pipeline, driven by utility rebate bundling with weatherization audits.
- Programmable Thermostat:Microcontroller-based units execute fixed weekly schedules without cloud connectivity or adaptive algorithms. Cost-sensitive residential segments in multi-family housing and rental properties sustain procurement volumes where landlord capital constraints block smart hardware upgrades.
- Focusing Thermostat:Specialized units direct conditioned air to occupied zones through damper control integration. Commercial applications in open-plan offices and hospitality lobbies drive specification.
- Non-Programmable Thermostat:Electromechanical bimetallic strip or basic digital setpoint devices without scheduling capability. Replacement demand in legacy HVAC systems with two-wire furnace controls dominates volume.
Non-programmable thermostats anchor the volume base while smart thermostats gain share at the steepest rate.
Installation Type:
Cost tier stratification separates premium professional channel deployment from mass-market DIY penetration, with wireless architectures commanding hardware premiums over wired retrofit compatibility.
- Professional Installation:Licensed technicians execute electrical upgrades including common wire installation and heat pump coordination. Commercial projects and heat pump retrofits in Nordic countries require certified labor for defrost cycle parameter configuration.
- DIY Installation:Battery-powered or power-stealing wireless designs enable consumer self-deployment without electrical permits. US big-box retail and direct-to-consumer channels capture residential replacement cycles.
- Wireless Systems:Radio-frequency or battery-backed architectures eliminate dedicated low-voltage wiring runs. New construction and deep energy retrofits favor specification.
- Wired Systems:Traditional 24VAC or millivolt control circuits with dedicated common wire power. Legacy HVAC infrastructure in 40 million US homes constrains smart thermostat adoption without electrical upgrades.
DIY wireless systems expand fastest in residential retrofits while professional wired installations retain commercial project dominance.
End User:
Application-specific performance requirements fragment procurement criteria, with industrial-grade precision demands diverging sharply from residential comfort optimization.
- Residential Users:Single-family homeowners and multi-family tenants prioritize utility bill reduction and smartphone remote access. ENERGY STAR certification and municipal rebate programs shape purchase decisions in California and New York.
- Commercial Establishments:Office buildings, retail chains, and hospitality operators demand centralized building management system integration. Honeywell's commercial channel heritage sustains specification dominance in this segment.
- Industrial Facilities:Manufacturing plants and warehouses require ±0.5°C precision for process control and cold chain integrity. Harsh environment ratings and vibration resistance differentiate procurement.
- Educational Institutions:K-12 districts and university campuses balance occupancy-driven scheduling with capital budget constraints. Deferred maintenance backlogs favor lowest-first-cost programmable units over smart platforms.
Residential users generate the highest unit volumes while commercial establishments deliver the strongest margin contribution per installation.
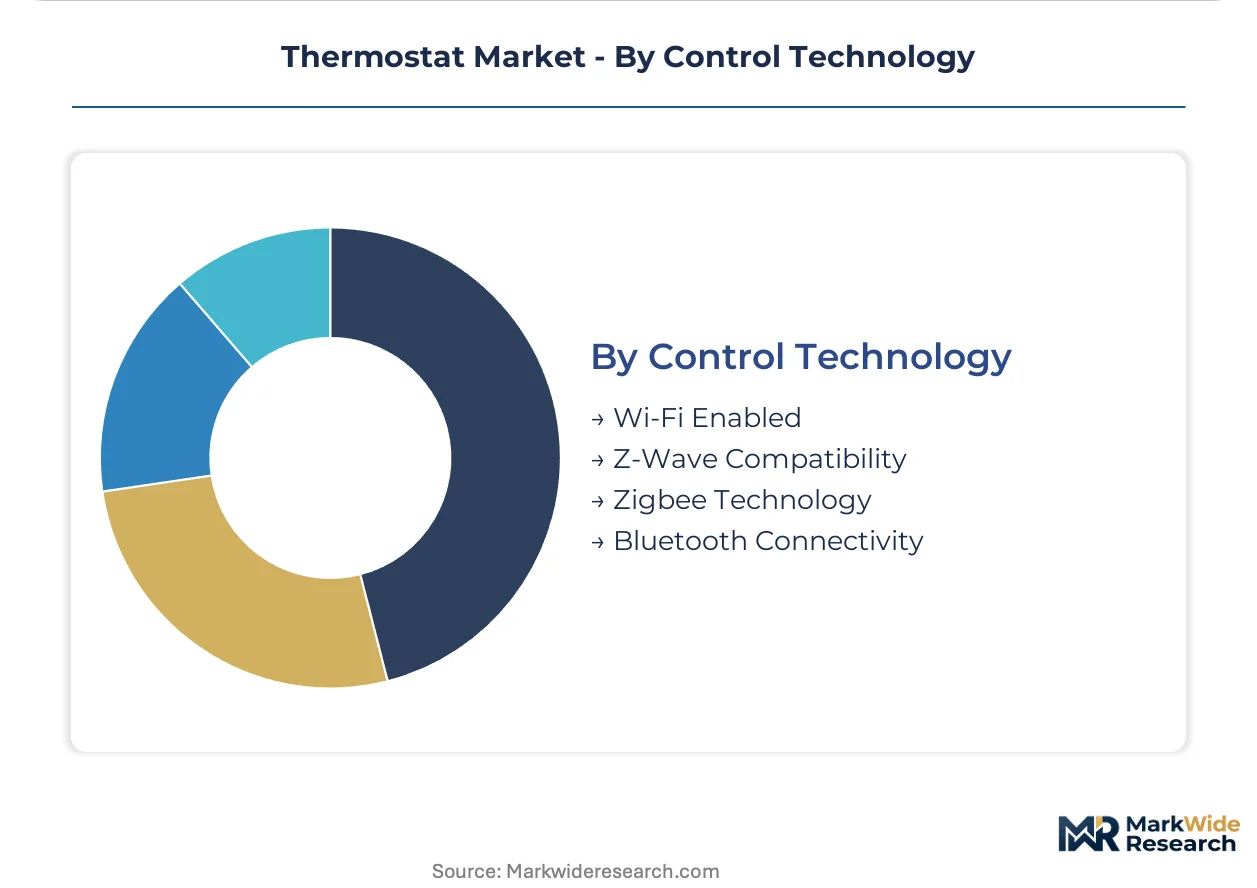
Control Technology:
Protocol proliferation creates engineering fragmentation, with Matter standardization attempting to consolidate previously incompatible wireless ecosystems.
- Wi-Fi Enabled:Direct cloud connectivity enables smartphone control without hub infrastructure. Semiconductor supply concentration in Taiwan and South Korea exposes manufacturers to foundry allocation volatility.
- Zigbee Technology:Mesh networking protocol optimized for low-power battery operation in multi-device smart home ecosystems. Thread border router integration extends interoperability.
- Z-Wave Compatibility:Sub-GHz proprietary mesh standard with strong presence in security-focused home automation installations. Regional frequency variations complicate global SKU strategy.
- Bluetooth Connectivity:Point-to-point local control for initial device setup and firmware updates. Limited range constrains standalone deployment without Wi-Fi backhaul.
Wi-Fi enabled devices command the largest installed base while Zigbee technology climbs fastest through Matter standardization momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese and South Korean foundries supply the semiconductor modules that power connected thermostat architectures, concentrating upstream component availability in East Asian manufacturing clusters. This supply geography shapes finished goods assembly location decisions and exposes downstream brands to foundry allocation volatility.
United States
Heat pump retrofits and building electrification mandates drive hardware refresh cycles across 40 million homes with legacy two-wire furnace controls. FERC Order 2222 enables aggregated thermostat fleets to bid into wholesale electricity markets, creating software revenue opportunities. California's SGIP and New York's NYSERDA rebate programs concentrate demand in coastal metropolitan corridors.
Germany
The EU F-Gas Regulation's hydrofluorocarbon phasedown accelerates air-to-water heat pump deployment in residential retrofits, expanding addressable thermostat demand for compressor-optimized systems. Municipal building automation mandates in tier-one urban centers generate concentrated procurement volumes. Installers in Nordic-adjacent regions face steep learning curves as defrost cycle coordination requirements intensify.
China
Smart city construction pipelines in tier-one municipalities generate demand for networked climate management infrastructure. GB standards compliance adds a third regulatory layer for manufacturers targeting domestic assembly. The Yangtze River Delta and Pearl River Delta clusters concentrate both foundry supply and finished goods production capacity.
India
The Bureau of Energy Efficiency's appliance labeling program for room air conditioners will extend to thermostats, favoring certified connected products in price-sensitive segments. Multi-family housing operators deploy occupancy-sensing systems to reduce common-area heating costs. Maharashtra and Gujarat industrial corridors anchor domestic assembly expansion.
United Kingdom
Building retrofit incentives and landlord energy efficiency regulations drive replacement demand in rental housing stock. The North Sea energy transition compresses gas boiler lifecycles, expanding heat pump-compatible thermostat specifications. London metropolitan area procurement concentrates volumes for professional installation channels.
Thermostat Market Vendor Landscape
Concentration sits with diversified industrial conglomerates that leverage building automation heritage across commercial project channels. The vendor base spans three strategic tiers: heritage HVAC controls specialists, consumer electronics platforms with voice integration capabilities, and regional electrical component fabricators. Competitive positioning hardens around direct OEM relationships with municipal energy providers and utility rebate program bundling. M&A activity targets predictive maintenance software capabilities and grid-responsive demand management protocols.
Within the heritage controls tier, Honeywell International Inc. and Emerson Electric Co. anchor commercial channel specification through building management system integration expertise. ecobee Inc. occupies a position among voice-integrated residential platform specialists competing against connected home ecosystems. Johnson Controls and Schneider Electric SE represent the diversified industrial conglomerate archetype with cross-portfolio climate control offerings.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| ecobee Inc. |
| Carrier Corporation |
| Alphabet Inc. (Google Nest) |
| Resideo Technologies Inc. |
| Lennox International Inc. |
| Johnson Controls |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Copper-to-aluminum conductor substitution in Wi-Fi module substrates simultaneously shifts procurement geography toward Southeast Asian rolling mills and compresses material cost premiums across connected thermostat tiers. This input transition reshapes foundry contract negotiations while forcing OEMs to recalibrate thermal performance warranties against conductivity trade-offs.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across compressor-optimized thermostat portfolios. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified smart platforms from basic programmable units and legacy electromechanical replacements. Price differentiation stems from certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because landlord capital constraints in rental housing block hardware upgrades. Multi-family housing operators exhibit highest price sensitivity; commercial building management system integrators show least.
Supply Chain Analysis
Container availability fluctuations on the Taiwan Strait-Japan trade lane expose thermostat manufacturers to inbound logistics cost volatility. Semiconductor module fabrication concentrates in Taiwan and South Korea, with final assembly clustering in China's Yangtze River Delta. Battery cell supply draws from South Korean and Japanese electrochemical producers. Single-source vulnerability in Wi-Fi and Bluetooth chipset allocation represents the dominant structural risk. Distribution runs through municipal utility rebate programs and big-box retail channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermostat market is exiting a semiconductor shortage trough as foundry capacity normalization enables order book rebuilding. Heat pump retrofit mandates across Germany and the United States provide the cyclical demand anchor.
For Market Incumbents: Compound channel control through direct OEM relationships with municipal energy providers facing FERC Order 2222 compliance deadlines. Deepen backward integration into predictive maintenance software capabilities to capture recurring revenue streams. Defend against voice-integrated residential platform specialists by accelerating Matter standardization certification timelines. For New Entrants and Emerging Players: Differentiate on grid-responsive demand management protocols to access wholesale electricity market participation revenue. Target India's Bureau of Energy Efficiency certification pipeline as the most penetrable regulatory pathway. Pursue white-label manufacturing partnerships with established HVAC controls heritage brands lacking in-house connectivity expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building automation software platforms seeking hardware integration. Five-to-ten-year viability hinges on heat pump adoption curves and electrification mandate durability. Monitor FERC Order 2222 implementation velocity across US independent system operators as the inflection indicator for software revenue multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Standardization Certification | Interoperability investment unlocks access to Apple, Google, and Amazon smart home ecosystems. |
| Grid-Responsive Firmware Development | FERC Order 2222 compliance enables aggregated thermostat fleets to bid into wholesale electricity markets. |
| Heat Pump Optimization Algorithm Licensing | EU F-Gas Regulation phasedown creates addressable demand for defrost cycle coordination intellectual property. |
| Utility Rebate Program Direct Partnership | California SGIP and New York NYSERDA bundling consolidates procurement away from retail channels. |
| Predictive Maintenance Platform Acquisition | Service attach rate expansion compresses hardware margin dependence in commercial project channels. |
Methodological Framework
Initial hypotheses were tested against primary input from HVAC controls product managers, municipal utility rebate program administrators, residential installation contractors, and commercial building management system integrators and refined through secondary validation against SEC 10-K filings, ENERGY STAR certification databases, FERC demand response filings, and EU ETS registry data. Bottom-up unit shipment estimates triangulated against top-down construction spend allocations.
Variance decomposition across product type, installation channel, end-use application, control technology protocol, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from logistic adoption curve modeling against electrification mandate timelines. Heat pump deployment trajectories and semiconductor foundry allocation schedules served as industry-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained foundry capacity expansion, stable copper and lithium commodity regimes, or uninterrupted regulatory incentive continuity would require recalibration. Forecasts reflect documented assumptions regarding building electrification policy durability and HVAC replacement cycle elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Brazil Energy Sector Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Solar Panel Monitoring System Market
Energy Management
Global Utility Asset Management Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Demand Response Management System Market
Energy Management
Power SCADA Market
Energy Management
Industrial Energy Management System Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market