
 South America Oil and Gas Hoses and Coupling Market | 2026-2036
South America Oil and Gas Hoses and Coupling Market Size, Share, and Industry Trends Forecast 2026-2036
South America Oil and Gas Hoses and Coupling Market Insights
Offshore drilling contractors is bifurcating from onshore service providers as the dominant buyer archetype across the continent. Continental AG leverages its deepwater hose portfolio to anchor supply relationships with Brazilian pre-salt operators. Gates Corporation sustains competitive pressure through specialized high-pressure hydraulic assemblies purpose-built for subsea environments. Trelleborg AB differentiates via advanced polymer composite technologies that resist hydrogen sulfide degradation in sour gas applications.
Oil and gas hoses and couplings constitute engineered flexible conduit systems, typically reinforced with steel wire braids or spiral windings and rated for pressures exceeding 10,000 psi, designed to convey drilling mud, crude oil, natural gas, and hydraulic fluids under extreme temperature and pressure cycles in hydrocarbon extraction and transport operations. Hydraulic hoses dominate current procurement volumes given their ubiquity in blowout preventer systems and top-drive drilling units, while composite hoses represent the fastest-expanding category as operators seek reduced weight and corrosion resistance for floating production installations. Stainless steel couplings command premium positioning due to fatigue-life requirements in subsea riser connections, whereas rubber-lined industrial hoses serve mature onshore pipeline maintenance segments with thinner margin pools.
Brazil's ANP mandates equipment certification for pre-salt operations, while Argentina's national hydrocarbon regulator enforces pressure-equipment standards aligned with IRAM norms, and Peru's OEFA imposes environmental compliance on upstream fluid-handling infrastructure. These frameworks collectively elevate product testing burdens and restrict market access to suppliers with demonstrated local certification capabilities. Stakeholders must monitor evolving national content requirements that increasingly condition offshore lease awards on localized hose assembly and testing infrastructure.
Market Dynamics
Brazil's ANP certification tightening for pre-salt equipment is compressing supplier qualification timelines while elevating technical barriers, forcing procurement officers to consolidate vendor relationships around certified composite hose specialists.
Growth Catalysts
- Pre-salt basin expansion:Petrobras and international operators are commissioning floating production storage and offloading vessels that require kilometer-length high-pressure riser assemblies.
- Vaca Muerta shale development:Argentina's unconventional hydrocarbon push demands fracturing hose fleets rated for 15,000 psi cyclic pressure in sour gas conditions.
- ANP Resolution 743:Brazil's updated deepwater equipment standards mandate third-party witnessed burst testing, eliminating uncertified suppliers from pre-salt tenders.
Market Restraints
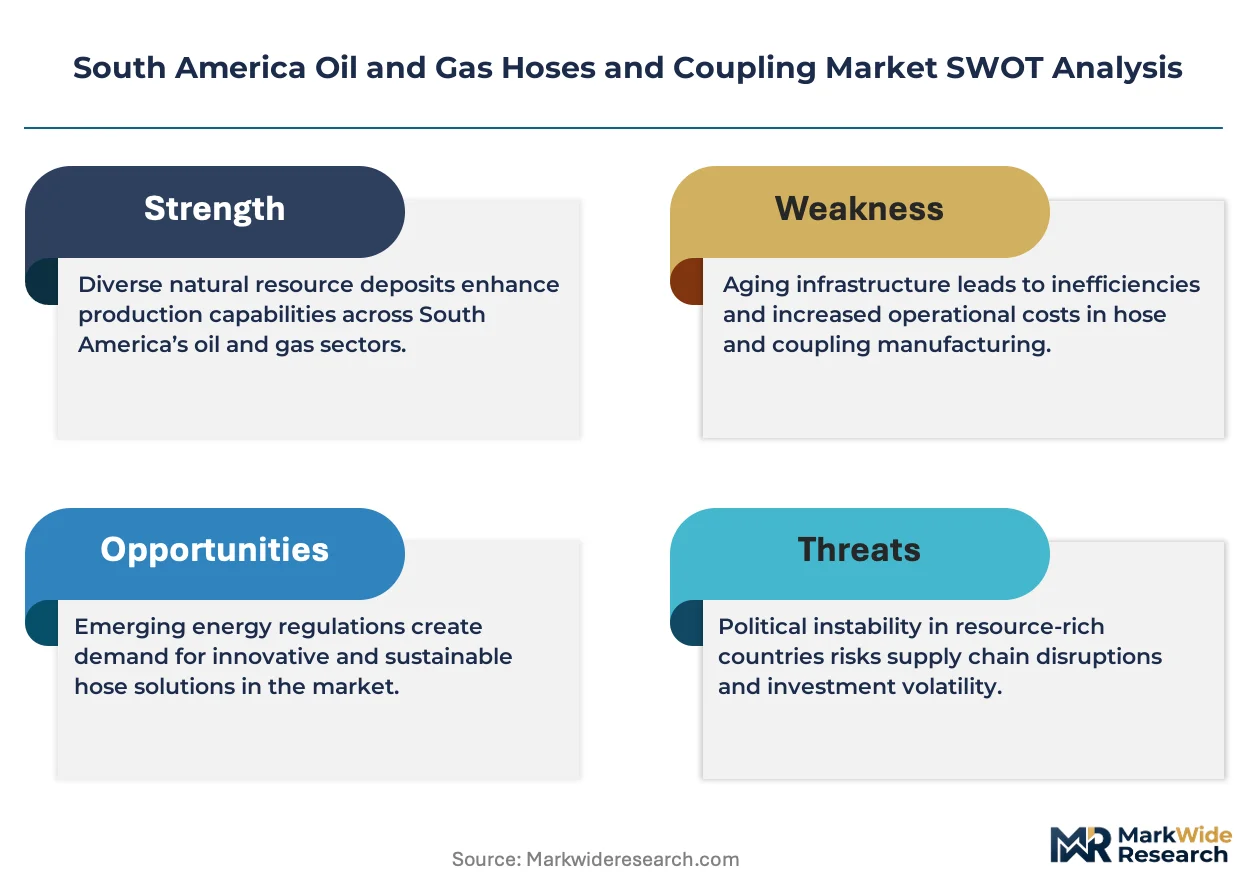
- Specialty polymer supply concentration:Hydrogenated nitrile butadiene rubber feedstock for sour service hoses sources primarily from German and Japanese chemical producers, exposing assemblers to currency fluctuation risk.
- Deepwater testing infrastructure scarcity:Only three facilities in South America can simulate 3,000-meter water column pressure for prototype validation, creating bottlenecks for new product qualification.
- Steel wire reinforcement cost volatility:High-tensile alloy wire for spiral-wound hoses tracks nickel and molybdenum commodity indexes, compressing assembler margins during price spikes.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil and partners are developing subsea tieback architectures that favor lightweight thermoplastic composite hoses over traditional steel-catenary risers.
- Colombia's offshore licensing round:ANH regulatory incentives for Caribbean deepwater blocks will require new hose assembly and testing infrastructure in Barranquilla.
- Digital twin integration:Convergence of fiber-optic condition monitoring with composite hose manufacturing enables predictive replacement scheduling for subsea jumpers.
Industry Challenges
- Subsea polymer engineering talent scarcity:Fewer than two hundred engineers across South America possess combined expertise in elastomer chemistry and 10,000-foot hydrostatic pressure engineering.
- Legacy equipment interoperability:New API 7K-certified hoses must interface with decade-old iron roughneck systems in Argentina's mature Neuquén fields, requiring custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Oil and Gas Hoses and Coupling Market |
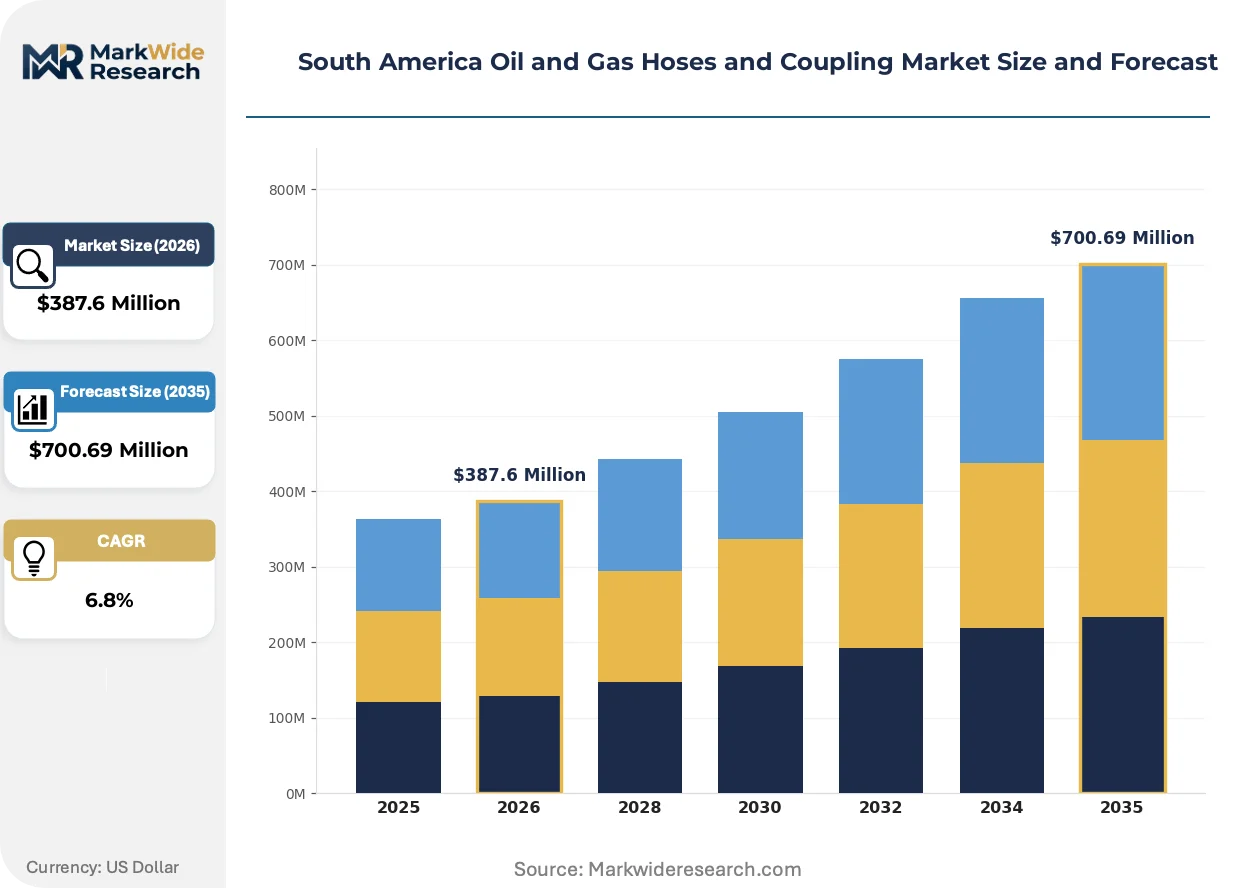
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Hoses, Industrial Hoses, Composite Hoses, Couplings Application: Offshore Operations, Onshore Operations, Tanker Services, Transportation Material: Rubber, PVC, Stainless Steel, Thermoplastic End User: Drilling Companies, Service Providers, Oil Refineries, Equipment Manufacturers |
| Companies Covered | Continental AG, Gates Corporation, Eaton Corporation Plc, Trelleborg AB, ParkerHannifin Corporation, Bosch Rexroth AG, Manuli Hydraulics, Kuriyama Holdings Corporation, Alfagomma, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Oil and Gas Hoses and Coupling Market Trends and Innovations
Material science breakthroughs and regulatory digitization are compressing product development cycles while fragmenting traditional supply relationships around specialized certification capabilities.
Carbon fiber-reinforced thermoplastic composite risers are miniaturizing wall thickness requirements for deepwater floating production systems. Brazilian pre-salt operators are specifying these assemblies for lazy-wave riser configurations in water depths exceeding 2,000 meters. The technology is miniaturizing installation vessel requirements, enabling smaller contractor fleets to bid on previously capital-intensive subsea infrastructure packages.
ANP's electronic certification portal implementation is digitifying equipment traceability for pre-salt operations. Manufacturers must now upload burst test video documentation and material batch records to a centralized database accessible to operator procurement teams. This regulatory shift most affects mid-tier hose assemblers lacking document management systems, forcing partnerships with IT-enabled certification consultants.
Integrated service contracts are consolidating procurement authority among Brazilian offshore drilling contractors. Previously fragmented purchasing across rig maintenance, subsea installation, and platform operations is centralizing under fleet-wide technical managers who negotiate multi-year hose supply agreements with volume-tiered pricing. This behavioral shift concentrates most visibly among Petrobras-contracted drillship operators in the Santos Basin.
South America Oil and Gas Hoses and Coupling Market Segmentation
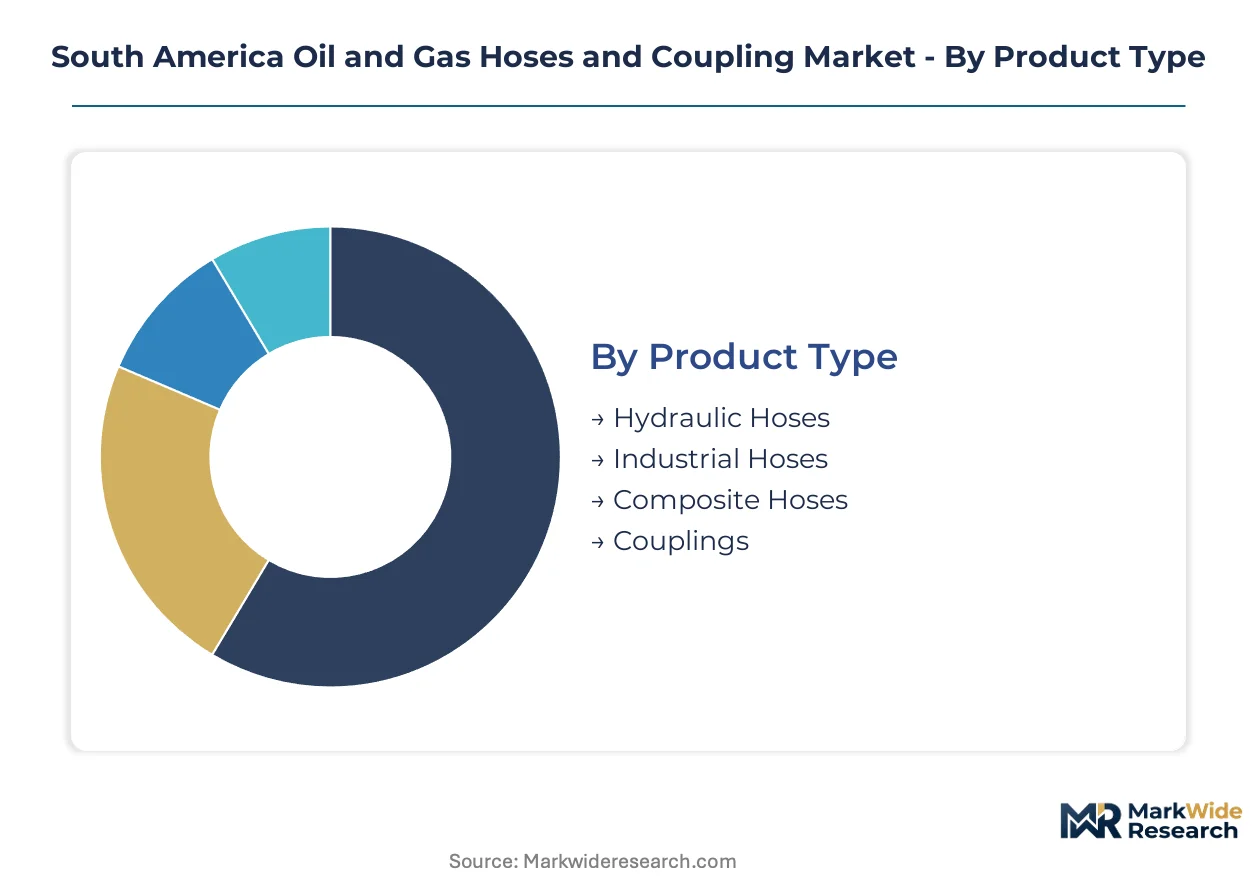
Segmentation in South America's oil and gas hoses market reveals distinct procurement patterns across Brazil's pre-salt offshore cluster versus Argentina's onshore shale operations. Understanding these splits enables suppliers to align certification investments and inventory positioning with actual demand concentration.
Product Type:
Domestic assembly capacity concentrates in Brazil's southeastern industrial corridor, while composite hose imports serve specialized deepwater applications.
- Hydraulic Hoses:Steel-wire-reinforced elastomeric conduits rated for 5,000-10,000 psi cyclic pressure dominate blowout preventer and top-drive systems. Demand concentrates among Petrobras-contracted drillship operators in the Santos Basin, where ANP-mandated burst testing elevates procurement standards.
- Composite Hoses:Multi-layer polymer-and-fabric barrier constructions with corrosion-resistant thermoplastic liners address sour gas and subsea weight constraints. Brazilian pre-salt FPSO projects specify these for lazy-wave riser configurations in 2,000-meter water depths.
- Industrial Hoses:Rubber-lined suction and discharge assemblies serve mature pipeline maintenance and tank farm operations.
- Couplings:Stainless steel and alloy cam-and-groove or hammer-union fittings provide pressure-rated connection points.
Hydraulic hoses command the established base. The steepest expansion runs through composite hoses.
Application:
Cost tiering separates capital-intensive subsea infrastructure from maintenance-driven onshore replacement cycles.
- Offshore Operations:Subsea riser assemblies, platform jumper hoses, and FPSO transfer systems require API 7K certification and third-party witnessed testing. Brazil's pre-salt basin accounts for the dominant share of high-pressure composite procurement.
- Onshore Operations:Drilling rig circulation systems, wellhead manifolds, and fracturing fleets operate under IRAM pressure-equipment norms in Argentina and ANP-aligned standards in Brazil. Vaca Muerta's 15,000 psi fracturing specifications drive sour-service hose demand.
- Tanker Services:Marine loading arm hoses and ship-to-shore transfer assemblies handle crude and refined product movement.
- Transportation:Tank truck and railcar hose assemblies for midstream logistics and terminal operations.
Offshore operations absorb the premium tier. Onshore operations deliver volume scale.
Material:
Supply concentration for hydrogenated nitrile feedstock shapes margin structures across elastomer-dependent segments.
- Rubber:Nitrile, neoprene, and hydrogenated nitrile butadiene compounds provide elasticity and abrasion resistance for hydraulic and industrial hoses. Sour service formulations for Vaca Muerta's H2S-rich gas depend on specialized German and Japanese chemical supply.
- Thermoplastic:Nylon and polyethylene barrier layers in composite constructions reduce weight and eliminate corrosion for deepwater risers. Brazilian operators specify these for floating production systems where steel catenary alternatives prove cost-prohibitive.
- Stainless Steel:316L and duplex alloy couplings and reinforcement wires deliver fatigue resistance.
- PVC:Limited to low-pressure utility and secondary containment applications.
Rubber formulations anchor the installed base. Thermoplastic composites are climbing the fastest.
End User:
Customer type determines contract structure, with integrated fleet managers consolidating procurement formerly fragmented across maintenance departments.
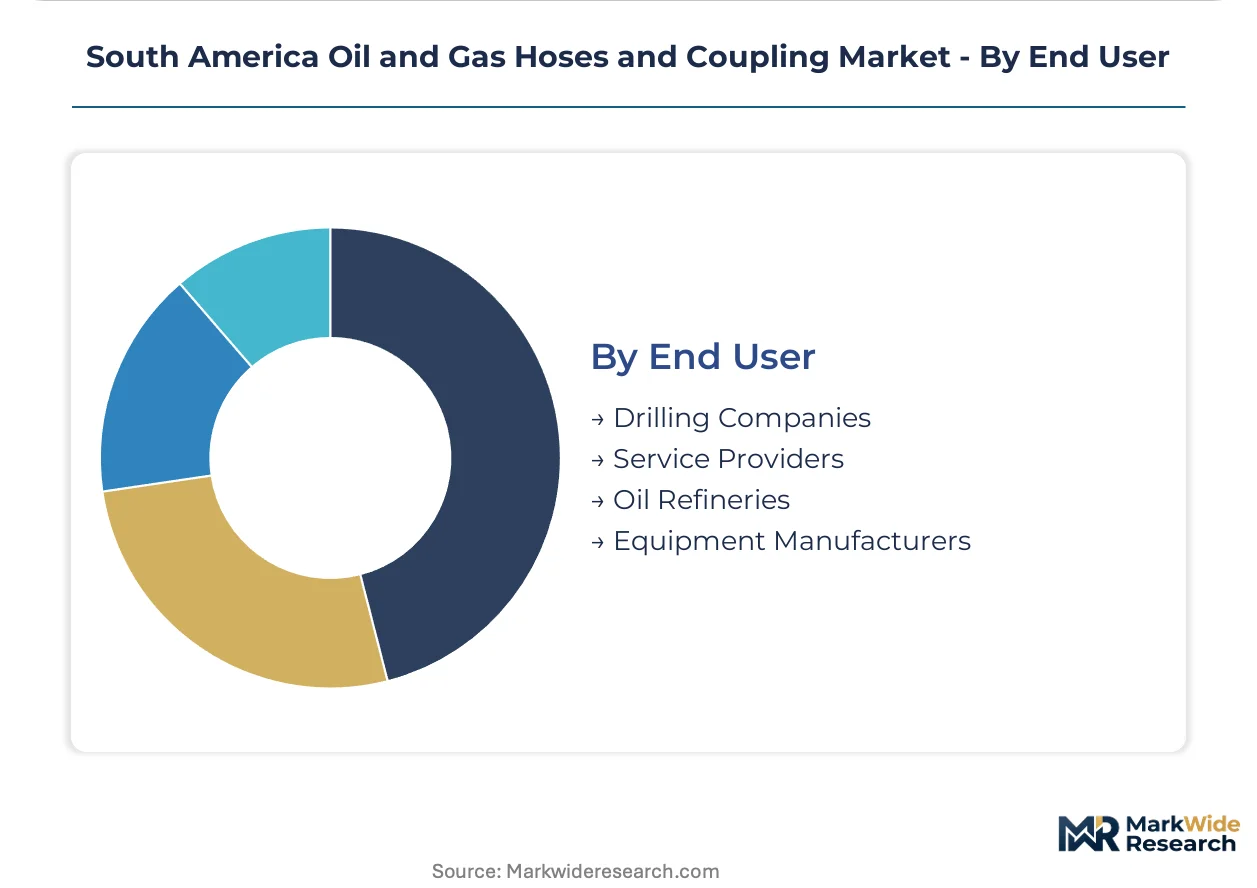
- Drilling Companies:Offshore contractors operating Petrobras-chartered drillships negotiate multi-year hose supply agreements with volume-tiered pricing. Integrated service contracts now centralize procurement authority under fleet technical managers.
- Service Providers:Hydraulic fracturing and well intervention specialists in Argentina's Neuquén Basin require rapid hose fleet turnover under 15,000 psi cyclic loading.
- Oil Refineries:Maintenance-driven procurement for process unit hose replacement and turnaround inventory.
- Equipment Manufacturers:OEM bundling of hoses with blowout preventers, top drives, and well control packages.
Drilling companies concentrate premium spend. Service providers generate replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports high-pressure composite hose assemblies to Guyana's offshore developments, while Argentine fracturing equipment flows north to service Colombia's unconventional pilot programs. This trade pattern concentrates procurement authority in São Paulo and Buenos Aires technical offices.
Brazil
Petrobras-chartered drillships in the Santos Basin drive demand for API 7K-certified hydraulic assemblies rated above 10,000 psi. ANP Resolution 743 mandates third-party witnessed burst testing for all pre-salt equipment, compressing supplier qualification timelines. São Paulo's southeastern industrial corridor hosts the continent's dominant hose assembly and testing infrastructure.
Argentina
Vaca Muerta shale operators require 15,000 psi fracturing hose fleets engineered for hydrogen sulfide degradation in sour gas conditions. The national hydrocarbon regulator enforces IRAM-aligned pressure-equipment standards that elevate technical barriers for imported assemblies. Neuquén Basin service providers generate rapid replacement cycles for elastomeric fracturing hoses under cyclic loading stress.
Guyana
ExxonMobil-led subsea tieback architectures favor lightweight thermoplastic composite hoses over steel-catenary risers in the Stabroek Block developments. The country's petroleum regulator applies equipment standards adapted from Brazilian ANP precedents given shared basin geology. Georgetown serves as the logistics coordination hub for floating production storage and offloading vessel hose procurement.
Colombia
ANH regulatory incentives for Caribbean deepwater licensing rounds will require new hose assembly infrastructure in Barranquilla. The national hydrocarbon agency conditions offshore lease awards on demonstrated local testing capabilities for high-pressure riser systems. Barranquilla's port industrial zone is positioning to capture Brazilian pre-salt engineering expertise through joint venture arrangements.
Peru
OEFA environmental compliance requirements impose upstream fluid-handling infrastructure standards that elevate procurement documentation burdens. Offshore licensing activity in the Talara Basin is pulling Argentine fracturing hose specialists northward to service unconventional pilot programs. Lima-based procurement offices coordinate continental supply relationships for Pacific coast drilling contractors.
South America Oil and Gas Hoses and Coupling Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The supplier base organizes around three tiers: diversified industrial conglomerates with full API certification portfolios, hydraulic-focused mid-caps with regional assembly presence, and polymer composite specialists serving sour service niches. Competitive positioning hinges on ANP pre-qualification status and deepwater testing facility partnerships rather than price alone. Consolidation pressure is accelerating as fleet-wide technical managers reduce vendor counts under integrated service contracts.
Within the diversified industrial tier, Continental AG and Gates Corporation exemplify archetypes that anchor supply relationships through comprehensive certification coverage. Trelleborg AB occupies a specialist position representing advanced polymer composite capabilities for hydrogen sulfide-resistant applications. These three entities collectively illustrate the competitive spectrum from scale-driven full-line suppliers to technology-focused niche players, with each archetype commanding distinct procurement channels among Brazilian pre-salt operators and Argentine shale service providers.
| Leading Market Players |
|---|
| Continental AG |
| Gates Corporation |
| Eaton Corporation Plc |
| Trelleborg AB |
| ParkerHannifin Corporation |
| Bosch Rexroth AG |
| Manuli Hydraulics |
| Kuriyama Holdings Corporation |
| Alfagomma |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber-reinforced thermoplastic composites displacing steel-catenary risers are redrawing procurement geography toward São Paulo assembly corridors while compressing per-meter pricing premiums that previously justified deepwater steel infrastructure. This substitution dynamic concentrates margin pressure on legacy spiral-wound hose assemblers tethered to nickel-indexed steel wire costs.
Pricing Analysis
The technology-generation pricing gap separates API 7K-certified composite risers for pre-salt FPSOs from legacy hydraulic assemblies and next-generation fiber-optic-integrated smart hoses. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and witnessed testing documentation rather than material cost alone. Cost compression in standard-grade hydraulic hoses is intensifying because Petrobras fleet managers are consolidating procurement under integrated service contracts. Argentine fracturing contractors exhibit highest price sensitivity due to rapid hose turnover cycles, while Brazilian deepwater operators prioritize fatigue-life performance over unit cost.
Supply Chain Analysis
Inventory lead times for hydrogenated nitrile butadiene rubber extend to six months given sole-source dependencies on German and Japanese chemical producers. Manufacturing concentrates in Brazil, Germany, and the United States for high-pressure assembly capacity, while raw material feedstocks draw from East Asian polymer specialists and European specialty chemical producers. Single-source vulnerability in HNBR supply exposes margin structures to currency fluctuation risk. Distribution runs through São Paulo technical offices serving Petrobras-contracted drillships and Buenos Aires procurement hubs for Vaca Muerta operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fewer than two hundred engineers across South America possess combined expertise in elastomer chemistry and deepwater pressure engineering, creating a bottleneck that constrains supplier expansion regardless of capital availability.
For Market Incumbents: Consolidate ANP pre-qualification status through exclusive partnerships with the continent's three deepwater testing facilities, locking out uncertified competitors from Santos Basin tenders. Deepen backward integration into hydrogenated nitrile compounding to offset Japanese and German feedstock pricing volatility. Anchor fleet-wide technical manager relationships before procurement authority centralizes further under integrated service contracts. For New Entrants and Emerging Players: ANP certification fast-track through joint ventures with established Brazilian assemblers offers the most penetrable entry path for composite hose specialists lacking local testing infrastructure. Target Colombia's Caribbean deepwater licensing round before Barranquilla assembly capacity matures. Lead with thermoplastic composite riser offerings for Guyana-Suriname basin tieback architectures where ExxonMobil specifications favor lightweight alternatives. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated specialists with captive polymer engineering capabilities and ANP-blessed testing partnerships. Acquisition candidates should demonstrate five-to-ten-year viability through multi-year Petrobras supply agreements rather than spot-market exposure. Watch ANP Resolution 743 enforcement intensity as the inflection signal—tightening certification timelines will accelerate vendor rationalization and create distressed exit opportunities for mid-tier assemblers lacking document management systems.| Strategic Initiative | Industry Significance |
|---|---|
| Deepwater Testing Facility Partnership | ANP-mandated witnessed burst testing compresses qualification timelines to three certified South American facilities. |
| Hydrogenated Nitrile Backward Integration | Captive HNBR compounding insulates margin structures from German and Japanese chemical producer currency exposure. |
| Fiber-Optic Condition Monitoring Integration | Smart composite hoses enable predictive replacement scheduling for subsea jumpers in Petrobras pre-salt operations. |
| Barranquilla Assembly Infrastructure Buildout | ANH regulatory incentives for Caribbean deepwater blocks require localized high-pressure riser testing capabilities. |
| Multi-Year Fleet Supply Agreement | Integrated service contracts centralize procurement authority under Petrobras-contracted drillship technical managers. |
Research Methodology
The analysis maps hydraulic hose assemblies, composite riser systems, industrial suction-discharge lines, and stainless steel coupling categories, each validated through procurement directors at offshore drilling contractors, fleet technical managers, ANP certification specialists, and polymer engineering leads. Primary interviews with these stakeholders combined with secondary validation through ANP regulatory filings, API certification databases, Petrobras procurement disclosures, and customs trade records. Bottom-up unit economics triangulated against top-down sector sizing across product type, application, material, and end-user dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across pressure rating tiers, water depth specifications, sour service requirements, and regional regulatory clusters. CAGRs were derived from installed base replacement cycles, pre-salt FPSO commissioning schedules, and Vaca Muerta fracturing fleet expansion trajectories. Forecast inputs incorporated ANP Resolution 743 implementation pace, Guyana-Suriname basin development timelines, and hydrogenated nitrile butadiene rubber supply elasticity.
Decision-makers should treat outputs as directional under assumptions of sustained pre-salt capital commitment and ANP certification tightening; material deviation in Petrobras investment intensity or regulatory enforcement pace would warrant model refresh. Specific risk factors include specialty polymer supply disruption, deepwater testing facility bottlenecks, and currency volatility in HNBR feedstock sourcing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Distributed Fiber Optic Sensor in Oil & Gas Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market