
 Fixed Series Compensation Market | 2026-2036
Fixed Series Compensation Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Series Compensation Market Analysis
IEC 61954 certification for thyristor-controlled series compensation is bifurcating the vendor landscape into qualified system integrators and component-restricted challengers. Siemens leverages its factory-certified valve testing infrastructure to sustain large-project eligibility across multiple continents. Hitachi Energy Ltd. anchors its position through proprietary platform-mounted capacitor bank designs that reduce substation footprint. Mitsubishi Electric Power Products Inc. differentiates via integrated gate commutated thyristor modules rated for 550 kV class installations.
Fixed series compensation denotes the insertion of capacitor banks in series with transmission lines to offset inductive reactance, typically employing metalized polypropylene film capacitors with 10-20 kVAR individual unit ratings and forced air or liquid dielectric cooling systems. The technology primarily enables utilities to increase thermal loading limits on existing corridors without right-of-way expansion. Base salary structures dominate utility procurement budgets where long-term maintenance contracts bundle compensation hardware with decade-spanning service agreements. Stock options and performance-linked instruments capture attention among independent power producers seeking to align vendor incentives with plant availability targets.
India's Central Electricity Authority enforces CEA Technical Standards for Connectivity that mandate dynamic stability studies before series compensation deployment, while China's National Energy Administration coordinates GB/T 15544 short-circuit calculation compliance for ultra-high-voltage projects. IEC 61954 and IEEE 824 together define valve stress testing protocols that determine which manufacturers qualify for utility pre-qualification lists. Stakeholders must track evolving grid code harmonization between regional transmission organizations and national regulators as FACTS deployment scales beyond traditional voltage support applications into inertia emulation services.
Market Dynamics
Ultra-high-voltage transmission buildouts across East Asia are compressing procurement cycles for series compensation hardware, forcing vendors to pre-certify valve platforms before project tenders release.
Growth Catalysts
- India's Green Energy Corridors:The Central Electricity Authority mandates series compensation for renewable evacuation routes exceeding 500 km, creating dedicated procurement streams for FACTS integrators.
- GB/T 15544 Compliance:China's National Energy Administration requires short-circuit withstand validation for all 550 kV class installations, filtering supplier pools to pre-qualified system houses.
- Metalized Polypropylene Film:Advances in self-healing dielectric films extend capacitor bank service intervals beyond 15 years, reducing lifecycle cost premiums for utility buyers.
Market Restraints
- IGCT Module Supply Concentration:Integrated gate commutated thyristor production clusters in Japan and Germany create single-source vulnerabilities for 550 kV class valve assemblies.
- IEC 61954 Certification Timelines:Factory valve stress testing protocols demand 18-24 month validation cycles, freezing challengers from large-project eligibility.
- GIS-Integrated Substations:Gas-insulated switchgear manufacturers bundle passive compensation into compact footprints, threatening standalone FSC unit demand in urban corridors.
Strategic Opportunities
- Inertia Emulation Services:Grid codes in Australia and the UK now recognize series compensation for synthetic inertia provision, opening ancillary revenue streams beyond traditional voltage support.
- Platform-Mounted Capacitor Banks:Skid-based designs reduce civil works by 40% at remote substations, penetrating mining and oil sands electrification projects in Canada and Chile.
- CEA Dynamic Stability Mandates:India's requirement for real-time simulation studies before commissioning creates bundled consulting opportunities for system integrators with in-house modeling capabilities.
Industry Challenges
- Valve Testing Engineer Scarcity:Factory-certified technicians capable of IEC 61954 protocol execution command premium wages, constraining Siemens and Hitachi Energy expansion timelines.
- Legacy Relay Integration:Electromechanical protection systems at 1980s-era substations require protocol converters for digital capacitor bank monitoring, complicating retrofit scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Series Compensation Market |
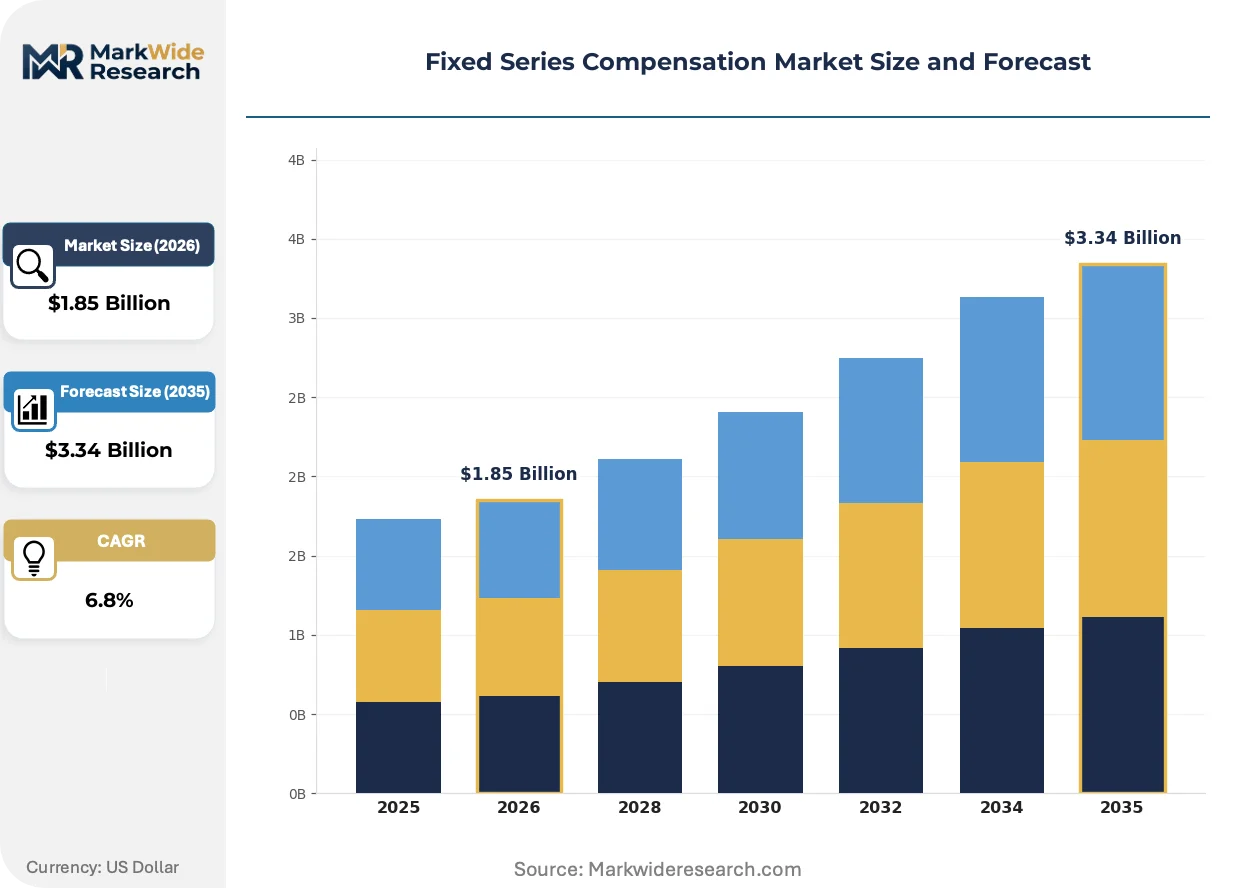
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Compensation Type: Base Salary, Bonuses, Commissions, Stock Options Industry Sector: Healthcare, Technology, Manufacturing, Finance Employee Level: Executive, Manager, Senior Staff, Entry-Level Performance Metric: Revenue Growth, Profit Margins, Customer Acquisition, Market Share |
| Companies Covered | Siemens, Infineon Technologies AG, General Electric Grid Solution, Hyosung Corporation, L&T Electrical & Automation, Hitachi Energy Ltd., Mitsubishi Electric Power Products Inc., ABB, Rongxin Power Electronic Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Series Compensation Market Emerging Trajectories
Distributed series compensation architectures are displacing centralized bank configurations, enabling utilities to stage investments along corridor extensions rather than front-loading entire substation overhauls.
Thyristor-controlled series compensation is fragmenting the traditional fixed-series market by offering incremental reactance modulation without full converter station costs. State grid operators in China deploy TCSC modules at 1000 kV UHVDC tie points to damp subsynchronous oscillations from distant wind farms. The technology compresses pricing power for pure FSC vendors while expanding total addressable spend on hybrid compensation schemes.
EU F-Gas Regulation phase-down schedules are accelerating dielectric fluid substitution in liquid-cooled capacitor banks, compelling manufacturers to validate synthetic ester formulations for 20-year thermal aging profiles. German transmission system operators now specify biodegradable coolants in pre-qualification documents. The mandate reshapes material sourcing for European projects while creating certification headroom for Asian suppliers with established ester supply chains.
Utility procurement departments are unbundling decade-spanning service agreements from hardware contracts, treating maintenance as competitive rebid terrain separate from initial capacitor bank supply. Independent power producers in India and Brazil drive this bifurcation, seeking to align vendor incentives with plant availability targets through performance-linked instruments rather than bundled base-salary structures. The shift compresses incumbent margins on aftermarket revenue while opening entry points for specialized service firms.
Fixed Series Compensation Market Segmentation
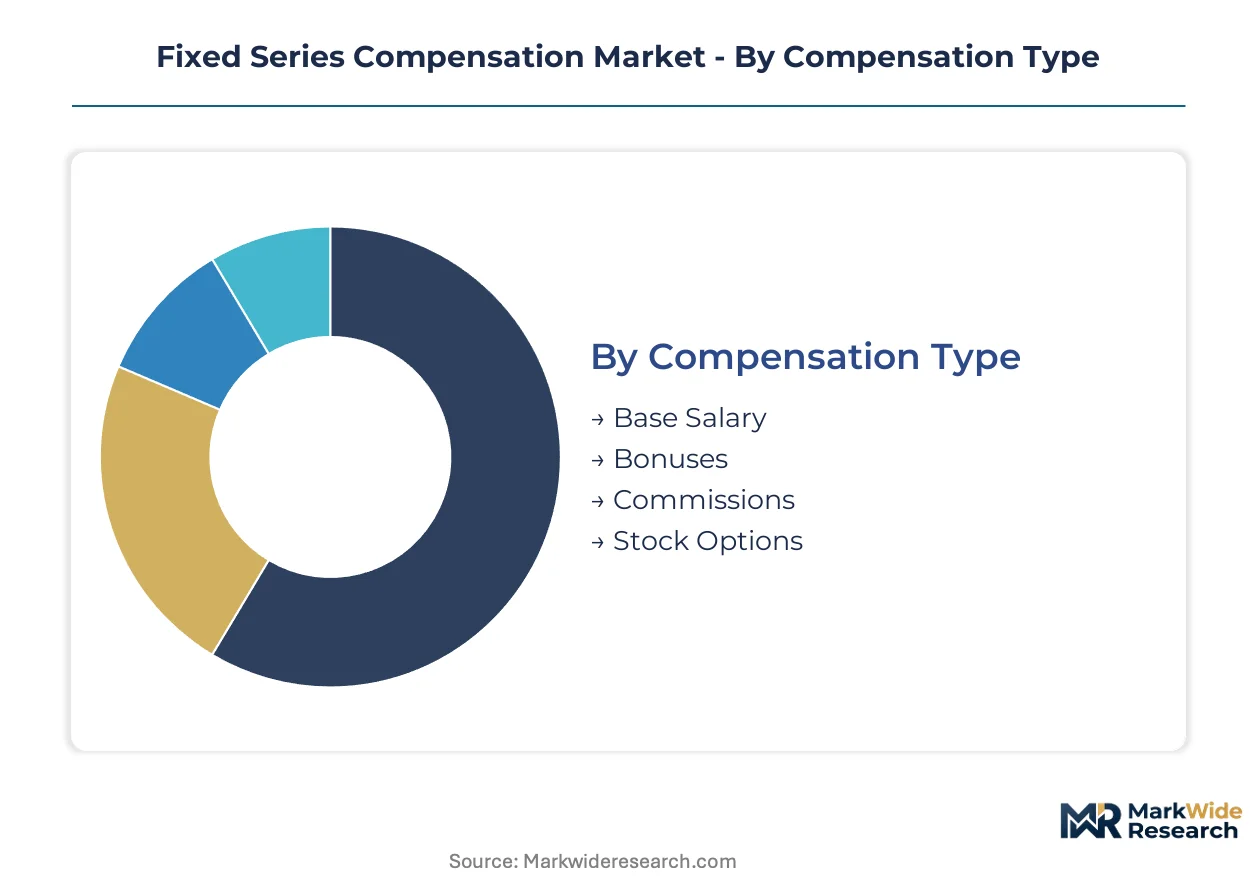
Fixed series compensation hardware flows through distinct procurement channels depending on buyer sophistication and project scale. Understanding these pathway differences reveals where margin concentrates and which vendor capabilities unlock access.
Compensation Type:
Base salary structures dominate utility procurement through bundled decade-spanning service agreements, while performance-linked instruments capture independent power producers seeking plant availability alignment.
- Base Salary:Predominant in state-owned utility frameworks where long-term maintenance contracts bundle capacitor bank hardware with civil works and commissioning. India's Central Electricity Authority mandates this structure for green energy corridor projects exceeding 500 km.
- Bonuses:Performance-triggered payments appear in Australia's inertia emulation service contracts, where grid operators tie vendor compensation to synthetic inertia delivery metrics during frequency events.
- Commissions:Independent system integrators in Brazil and Chile earn placement fees for platform-mounted capacitor bank specifications at remote mining electrification sites.
- Stock Options:Rare in pure hardware procurement; emerging among hybrid compensation scheme developers in China's UHVDC tie point projects where TCSC vendors accept equity stakes in project SPVs.
By volume, base salary structures lead. By growth pace, stock options are climbing the fastest as project finance structures evolve.
Industry Sector:
Cost tier differentiation separates sectors by technical complexity tolerance and certification burden.
- Healthcare:Hospital campus microgrids in Germany specify FSC units with synthetic ester coolants to meet EU F-Gas phase-down schedules; procurement emphasizes 20-year thermal aging validation over upfront capital minimization.
- Technology:Hyperscale data center operators in Virginia and Ireland demand platform-mounted banks for 500 kV interconnection points, prioritizing skid-based civil work reduction and rapid deployment timelines.
- Manufacturing:Steel and aluminum smelters in China's Shandong province anchor demand for 550 kV class installations with GB/T 15544 short-circuit withstand validation.
- Finance:Investment banks structure project finance for FACTS installations, treating vendor compensation instruments as risk allocation tools rather than operational procurement.
Manufacturing absorbs the highest unit volumes. Technology sector procurement is expanding most quickly.
Employee Level:
Customer type determines specification authority and technical evaluation depth.
- Executive:Grid operator C-suite procurement committees in Japan and Germany approve ultra-high-voltage series compensation investments exceeding 100 million USD equivalent, delegating technical evaluation to in-house engineering divisions.
- Manager:Regional transmission organization planning departments in Texas and California conduct dynamic stability studies before series compensation deployment, per emerging North American grid code harmonization.
- Senior Staff:Substation engineering teams specify capacitor bank configurations, with India's CEA Technical Standards for Connectivity mandating their sign-off on real-time simulation validation.
- Entry-Level:Procurement coordinators handle routine maintenance contract renewals for existing installations, typically rebidding service agreements separately from hardware supply.
Manager-level specifications dominate current procurement volume. Executive-level direct involvement is gaining share fastest as project scale increases.
Performance Metric:
Application context dictates which metrics govern vendor selection and compensation triggers.
- Revenue Growth:Private transmission developers in Brazil and Chile prioritize corridor thermal loading expansion to maximize tariff revenue, specifying FSC units that enable 30-40 percent capacity increases without right-of-way expansion.
- Profit Margins:Merchant transmission operators in Texas evaluate series compensation through congestion rent optimization models, selecting compensation levels that maximize nodal price differential capture.
- Customer Acquisition:Rural electrification agencies in India's Rajasthan and Gujarat states deploy platform-mounted banks to extend 765 kV backbone reach into renewable-rich regions, treating connection volume as primary success metric.
- Market Share:State Grid Corporation of China's procurement of TCSC modules at 1000 kV UHVDC tie points targets subsynchronous oscillation damping to maintain renewable evacuation leadership against regional competitors.
Revenue growth metrics anchor the largest installed base. Customer acquisition metrics are expanding most quickly as electrification programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid modernization mandates from China's National Energy Administration and India's Central Electricity Authority are compressing procurement cycles for series compensation hardware across Asia. Ultra-high-voltage transmission corridors in East Asia and renewable evacuation routes in South Asia dominate investment flows.
China
State Grid Corporation deploys TCSC modules at 1000 kV UHVDC tie points to damp subsynchronous oscillations from distant wind farms. The National Energy Administration enforces GB/T 15544 short-circuit calculation compliance for all 550 kV class installations. Manufacturing clusters in Shandong province supply capacitor banks with metalized polypropylene film dielectrics to domestic grid operators.
India
The Central Electricity Authority mandates series compensation for renewable evacuation routes exceeding 500 km through its Green Energy Corridors program. CEA Technical Standards for Connectivity require dynamic stability studies before commissioning. Gujarat and Rajasthan states anchor demand for platform-mounted banks extending 765 kV backbone reach into solar-rich western regions.
United States
Merchant transmission operators in Texas evaluate series compensation through congestion rent optimization models. FERC Order 1000 compliance drives independent transmission developer procurement of FACTS hardware. Virginia data center clusters specify platform-mounted banks for 500 kV interconnection points, prioritizing rapid deployment timelines.
Germany
Transmission system operators specify biodegradable synthetic ester coolants in pre-qualification documents under EU F-Gas Regulation phase-down schedules. Industrial microgrids at chemical complexes in North Rhine-Westphalia deploy FSC units with 20-year thermal aging validation. Bavarian substation engineering firms conduct IEC 61954 valve stress testing for continental grid projects.
Brazil
Private transmission developers prioritize corridor thermal loading expansion to maximize tariff revenue in the national grid auction system. Independent system integrators earn placement fees for platform-mounted capacitor bank specifications at remote mining electrification sites in Minas Gerais. The national electricity regulator ANEEL mandates stability studies for series compensation deployment in the north-south transmission backbone.
Fixed Series Compensation Market Vendor Landscape
Player mix skews toward diversified electrical equipment conglomerates with factory-certified valve testing infrastructure. The vendor landscape bifurcates into qualified system integrators holding IEC 61954 certification and component-restricted challengers frozen from large-project eligibility. Strategic archetypes include integrated platform manufacturers, specialized capacitor bank fabricators, and power electronics module suppliers. Competitive moves concentrate on pre-certification of valve platforms before project tender release and geographic expansion through local system integrator partnerships.
Among diversified electrical equipment conglomerates, Siemens, Hitachi Energy Ltd., and Mitsubishi Electric Power Products Inc. exemplify the qualified system integrator archetype. Siemens leverages its factory-certified valve testing infrastructure to sustain large-project eligibility across multiple continents. Hitachi Energy Ltd. anchors its position through proprietary platform-mounted designs that reduce substation footprint. Mitsubishi Electric Power Products Inc. occupies a position within the premium-tier segment via integrated gate commutated thyristor modules rated for 550 kV class installations.
| Leading Market Players |
|---|
| Siemens |
| Infineon Technologies AG |
| General Electric Grid Solution |
| Hyosung Corporation |
| L&T Electrical & Automation |
| Hitachi Energy Ltd. |
| Mitsubishi Electric Power Products Inc. |
| ABB |
| Rongxin Power Electronic Co. |
| Others |
Supply Flow & Price Mechanics
Factory-certified valve testing infrastructure concentration in Germany and Japan creates scale economies that elevate price floors for IEC 61954-qualified system integrators while squeezing component-restricted challengers from large-project eligibility. Metalized polypropylene film capacitor production clusters in China's Shandong province and integrated gate commutated thyristor module fabrication in Japan further compress margin flexibility through input-side bottlenecks.
Pricing Analysis
Certification level creates the primary spread between premium-tier and economy-tier offerings, with IEC 61954 valve stress testing qualification separating qualified system integrators from component-restricted suppliers. Project-based pricing dominates utility procurement through bundled hardware-service agreements, while independent power producers drive unbundling that treats maintenance as competitive rebid terrain. Cost compression in the mid-tier intensifies because TCSC modules fragment traditional FSC demand with incremental reactance modulation at lower capital intensity. State-owned utilities exhibit lowest price sensitivity due to decade-spanning service agreement preferences, whereas merchant transmission operators in Texas and Brazil prioritize congestion rent optimization that elevates capital efficiency scrutiny.
Supply Chain Analysis
Strategic stockpiling of IGCT modules and synthetic ester coolants prevails among European and East Asian system integrators facing 18-24 month IEC 61954 certification timelines and EU F-Gas Regulation phase-down schedules. Manufacturing concentrates in China for metalized polypropylene film capacitors, Japan for integrated gate commutated thyristor modules, and Germany for factory-certified valve testing equipment. Raw material dependencies include self-healing dielectric films, liquid dielectric coolants, and high-voltage thyristor assemblies. Single-source vulnerability in IGCT module supply from Japan and Germany creates structural risk for 550 kV class valve assemblies. Distribution runs through direct utility procurement channels for large-scale projects and independent system integrator partnerships for remote mining and industrial electrification sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fixed series compensation market operates as a regulatory entrenchment story where IEC 61954 certification creates switching costs that freeze challengers from utility pre-qualification lists for 18-24 month validation cycles.
For Market Incumbents: Shield large-project eligibility through accelerated pre-certification of valve platforms before tender release, compressing procurement cycles that China's National Energy Administration and India's Central Electricity Authority are tightening. Deepen backward integration into metalized polypropylene film capacitor production to offset IGCT module supply concentration risks from Japanese and German single sources. Expand factory-certified technician training programs to address valve testing engineer scarcity that constrains expansion timelines. For New Entrants and Emerging Players: Anchor in platform-mounted capacitor bank specifications for remote mining electrification projects in Canada, Chile, and Brazil where civil work reduction commands premium positioning outside utility pre-qualification barriers. Target independent power producers in India and Brazil driving maintenance contract unbundling, where performance-linked instruments create entry points absent bundled decade-spanning service agreement requirements. Pursue skid-based design partnerships with specialized service firms to bypass IEC 61954 certification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified electrical equipment conglomerates with captive valve testing infrastructure and established utility pre-qualification status across multiple continents. Long-term viability hinges on regulatory entrenchment durability as grid codes in Australia and the UK recognize series compensation for synthetic inertia provision, expanding ancillary revenue streams. Acquisition target archetype: specialized capacitor bank fabricators with platform-mounted designs and synthetic ester coolant validation. The signal to watch is harmonization between regional transmission organizations and national regulators on FACTS deployment standards.| Strategic Initiative | Industry Significance |
|---|---|
| Valve Platform Pre-Certification | Secures large-project eligibility before China's NEA and India's CEA tender releases compress procurement cycles. |
| Backward Integration into Capacitor Films | Captures metalized polypropylene film supply chains concentrated in Shandong province to offset IGCT module bottlenecks. |
| Synthetic Ester Coolant Validation | Meets EU F-Gas Regulation phase-down mandates that German transmission operators now embed in pre-qualification documents. |
| Platform-Mounted Bank Partnerships | Penetrates remote mining electrification in Minas Gerais and Canadian oil sands where civil work reduction commands premium positioning. |
| Inertia Emulation Service Development | Captures ancillary revenue streams as Australian and UK grid codes recognize series compensation for synthetic inertia provision. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with utility planning officers, IPP project developers, EPC contractors, grid operators, and FACTS system integrators. Secondary validation drew from FERC filings, EIA transmission project databases, IEA grid modernization reports, and national regulator technical standards including India's CEA Technical Standards for Connectivity and China's GB/T 15544. Bottom-up capacity and procurement pipeline analysis was triangulated against top-down grid investment forecasts.
Across the projection horizon, the analytical framework modeled segmentation dimensions including compensation type, industry sector, employee level specification authority, and performance metric application context. CAGRs were derived from corridor-level investment tracking and vendor order book analysis. Industry-specific forecast inputs included ultra-high-voltage transmission buildout timelines from State Grid Corporation and renewable evacuation route mandates from India's Green Energy Corridors program.
Material uncertainties — regulatory harmonization shifts, IGCT module supply disruptions, and TCSC technology substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and grid code evolution trajectories. Revision becomes warranted when IEC 61954 validation cycle compression or F-Gas Regulation acceleration crosses thresholds that restructure vendor qualification dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Natural Gas Refueling Infrastructure Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Digital Substation Market