
 Energy Management Market | 2026-2036
Energy Management Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Management Market Analysis
ISO 50001 certification is bifurcating the competitive landscape into qualified integrators and commodity suppliers. Schneider Electric leverages its EcoStruxure platform to anchor large-scale industrial deployments across Europe and Asia. Siemens sustains technology leadership through its digital twin capabilities in grid-edge optimization. Honeywell International competes on building automation convergence, extending its installed base into energy-as-a-service contracts.
Energy management encompasses the systematic monitoring, control, and optimization of energy consumption across generation, distribution, and end-use points, typically employing sub-metering hardware with 0.5% accuracy class and software platforms processing 10,000+ data points per facility. Its primary purpose is reducing operational expenditure while maintaining production throughput and regulatory compliance. Software and services segments capture the dominant margin pools as recurring revenue models displace one-time hardware sales. Cloud-based installation types represent the fastest-growing architecture as utilities prioritize scalable analytics over capital-intensive on-premise infrastructure. Demand response applications mature in North American markets while renewable integration drives greenfield deployment in emerging economies.
The EU Green Deal and EPA efficiency standards shape product roadmaps by mandating minimum performance thresholds for building systems and industrial equipment. FERC Order 2222 in the United States unlocks distributed energy resource participation in wholesale markets, directly expanding addressable demand for aggregation software. NHTSA corporate average fuel economy rules indirectly pressure automotive suppliers to adopt facility-level energy tracking. Stakeholders must monitor how cybersecurity frameworks from NERC CIP and IEC 62351 evolve alongside connectivity requirements, as compliance costs could reshape vendor economics faster than technology substitution.
Market Dynamics
Cloud-native energy management architectures are compressing deployment timelines from 18 months to under 90 days, forcing incumbent vendors to restructure professional services margins and accelerate API-first platform development.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation now participates in US wholesale markets, expanding software demand among independent power producers and commercial aggregators.
- Sub-metering hardware:0.5% accuracy class devices enable granular load disaggregation, unlocking demand response revenue streams for industrial facilities in Germany and Japan.
- EU Green Deal retrofit mandates:Commercial building stock across France, Italy, and Spain faces accelerated efficiency upgrade cycles, driving recurring software subscription growth.
Market Restraints
- Semiconductor input volatility:Power management ICs and precision analog sensors face 12-18 month lead times, constraining sub-metering hardware production scaling.
- Cybersecurity compliance costs:NERC CIP and IEC 62351 framework evolution imposes recurring certification burdens that reshape vendor economics faster than technology substitution.
- Legacy SCADA substitution resistance:Industrial facilities in heavy process industries exhibit extended replacement cycles for grid-edge control systems due to operational continuity requirements.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives and CEA grid code revisions create greenfield deployment potential for integrated optimization platforms in steel and cement sectors.
- Digital twin convergence:Physics-based modeling fused with real-time meter data enables predictive maintenance applications previously requiring separate CAPEX allocations.
- Energy-as-a-service channel innovation:Third-party ownership models bypass customer balance sheet constraints, accelerating adoption among mid-market commercial building operators.
Industry Challenges
- ISO 50001 lead auditor scarcity:Qualified certification personnel concentration in Western Europe creates implementation bottlenecks for multinational industrial deployments.
- Multi-protocol integration complexity:BACnet, Modbus, and proprietary OEM data streams require custom middleware development, extending project timelines and eroding margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Management Market |
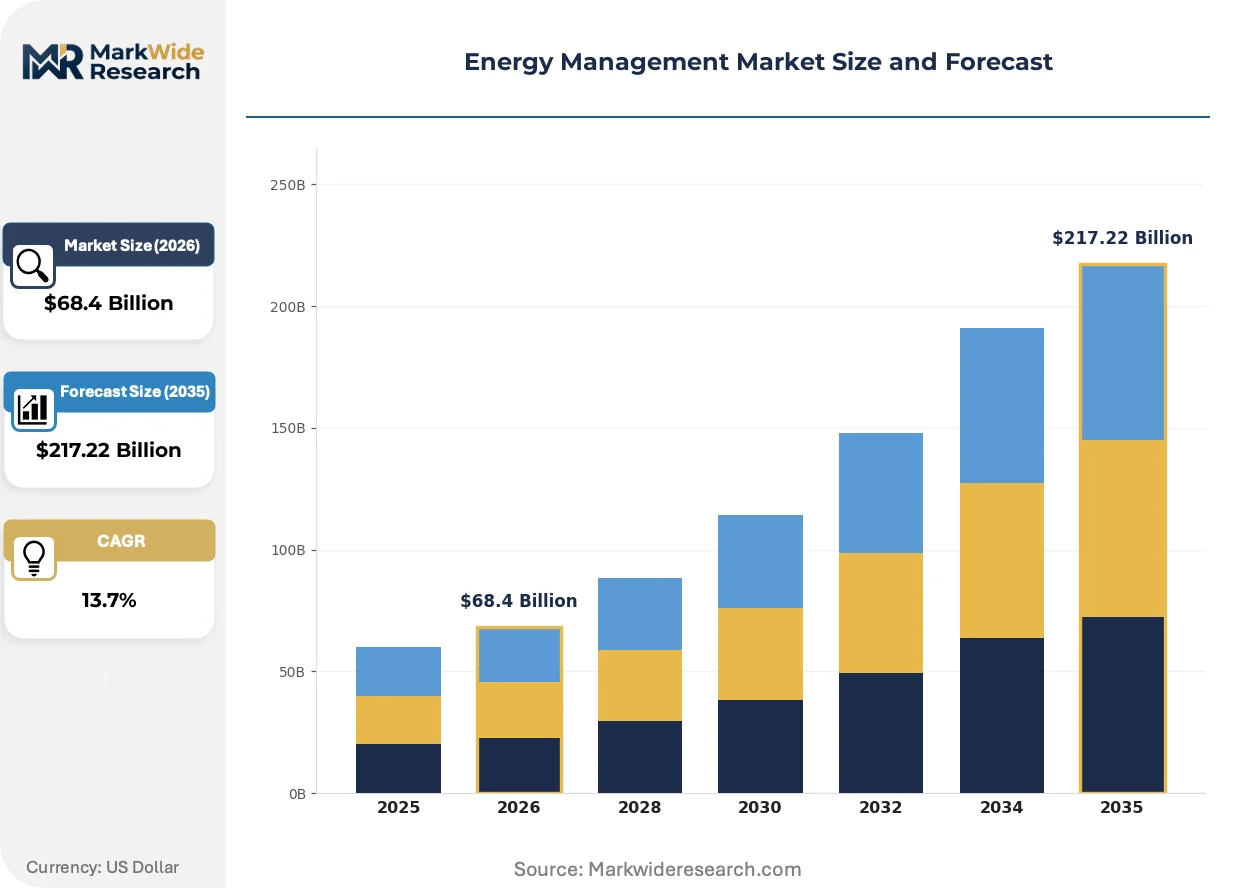
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $217.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Application: Smart Grids, Renewable Integration, Building Management, Demand Response End User: Utilities, Commercial, Industrial, Residential Installation Type: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | Schneider Electric, Siemens, General Electric, Honeywell International, ABB, Emerson Electric, Johnson Controls International, IBM Corporation, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Management Market Emerging Trajectories
Edge computing architectures are redistributing analytics workloads away from centralized cloud instances, creating new competitive battlegrounds around latency-sensitive control applications and data sovereignty compliance.
Containerized microservices deployment is supplanting monolithic energy management software stacks. Large industrial facilities in Germany and Texas are adopting Kubernetes-orchestrated workloads to enable modular scaling of analytics modules. This architecture is supplanting traditional perpetual-license deployment models with consumption-based pricing structures.
CSRD sustainability disclosure mandates in the European Union now require granular energy consumption attribution across Scope 1, 2, and 3 boundaries. Industrial reporting obligations are forcing software vendors to enhance emissions calculation engines and audit trail functionality. Automotive suppliers and chemical processors face the steepest compliance curves, driving premium pricing for certified reporting modules.
Building operators are consolidating vendor relationships around integrated platform providers rather than point-solution specialists. Procurement teams at university campuses and hospital systems now require single-pane visibility across HVAC, lighting, and EV charging infrastructure. This concentration pattern is most visible in California and New York, where utility incentive programs favor comprehensive retrofit approaches over incremental upgrades.
Energy Management Market Segmentation
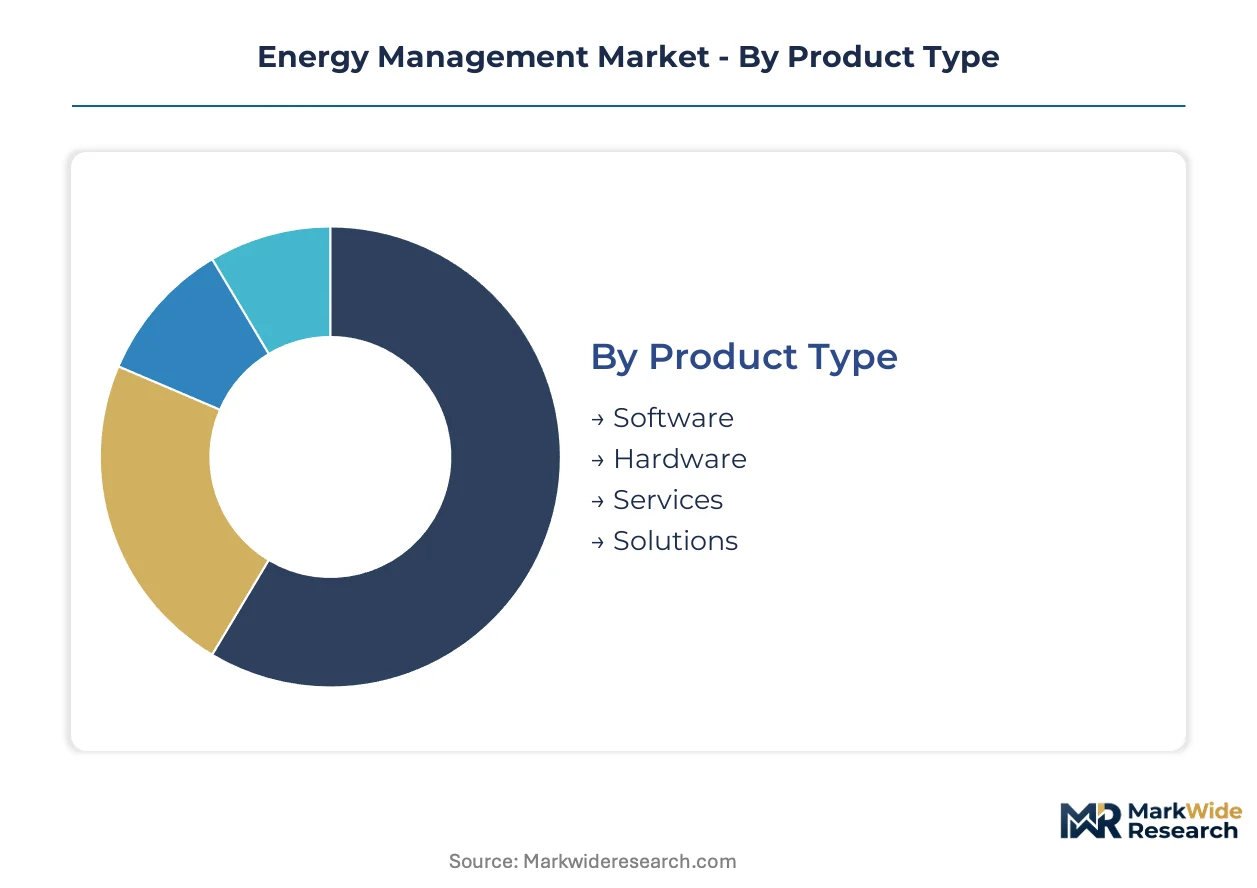
Segmentation in energy management reveals how technology deployment patterns diverge across infrastructure maturity levels and regulatory environments. Product architecture choices directly determine margin capture and customer lifetime value in this market.
Product Type:
Software and services segments dominate export revenue from US and European vendors, while hardware production concentrates in East Asian manufacturing clusters serving domestic retrofit markets.
- Software:Cloud-native platforms process 10,000+ facility data points with sub-second latency for grid-edge optimization. German industrial facilities and Texas oil refineries drive subscription demand for predictive analytics modules. ISO 50001 certification requirements force mid-market customers toward certified software vendors.
- Hardware:Sub-metering devices with 0.5% accuracy class enable granular load disaggregation for demand response programs. Japanese automotive suppliers and South Korean semiconductor fabs anchor precision hardware procurement. Semiconductor input volatility constrains production scaling.
- Services:Professional implementation and certification support.
- Solutions:Integrated platform bundles combining software, hardware, and ongoing optimization.
Software holds the largest share; momentum sits with Solutions as procurement teams consolidate vendor relationships.
Application:
Cost tier differentiation separates utility-scale deployments with seven-figure budgets from building-level retrofits under $500,000.
- Smart Grids:Real-time distribution network optimization with AMI integration and volt-VAR control. California IOUs and Texas ERCOT operators drive deployment. FERC Order 2222 expands aggregation software demand.
- Renewable Integration:Forecasting and curtailment management for variable generation assets. Indian solar parks and Brazilian wind complexes require greenfield control platforms. Grid code revisions in emerging markets accelerate procurement.
- Building Management:HVAC and lighting convergence for commercial efficiency.
- Demand Response:Load flexibility programs for wholesale market participation.
Smart Grids commands the dominant investment pool; Renewable Integration climbs fastest as capacity additions accelerate in India and Brazil.
End User:
Volume concentration sits with Industrial customers running 24/7 process loads, while Commercial segments generate superior recurring revenue per installed meter point.
- Utilities:Transmission and distribution operators managing millions of endpoints. German grid operators and California IOUs deploy enterprise-scale platforms. Cybersecurity compliance costs reshape vendor selection criteria.
- Commercial:Office buildings, retail chains, and healthcare facilities pursuing efficiency retrofits. French hospital systems and New York university campuses consolidate around single-pane visibility platforms. CSRD disclosure mandates force emissions calculation upgrades.
- Industrial:Heavy process facilities with continuous production requirements.
- Residential:Single-family and multi-unit building energy optimization.
Utilities holds the largest share; momentum sits with Commercial as EU Green Deal retrofit mandates accelerate software subscription growth.
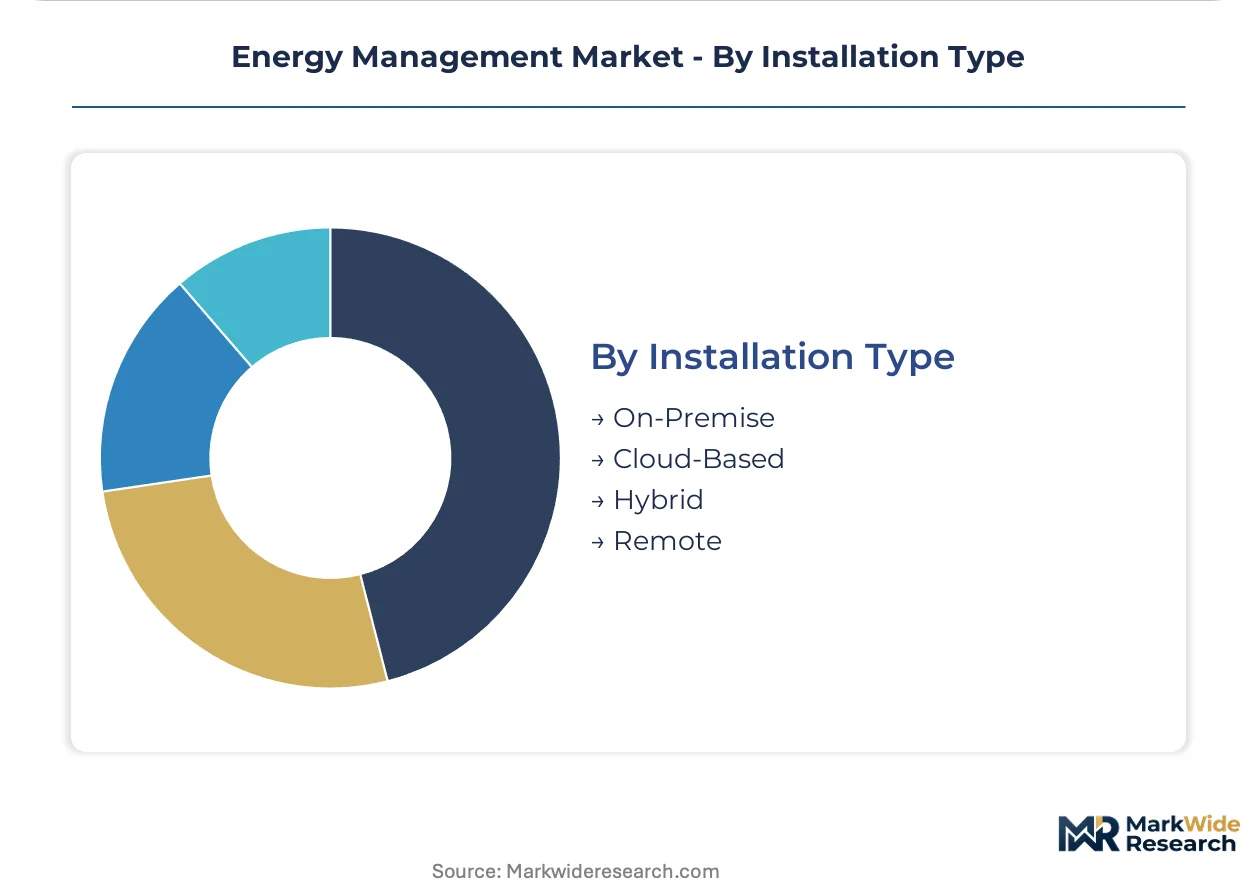
Installation Type:
Customer type determines architecture preference—regulated utilities favor hybrid deployments for data sovereignty, while mid-market commercial operators bypass on-premise capital entirely.
- Cloud-Based:Scalable analytics with API-first integration and consumption-based pricing. US independent power producers and German municipal utilities prioritize deployment speed over capital control. Containerized microservices enable modular scaling.
- Hybrid:Edge computing for latency-sensitive control with cloud aggregation for enterprise visibility. Texas industrial microgrids and Japanese automotive plants require local control loops. Data sovereignty compliance drives European adoption.
- On-Premise:Capital-intensive infrastructure for critical control systems.
- Remote:Managed service delivery with minimal on-site footprint.
Cloud-Based holds the largest share; momentum sits with Hybrid as edge computing redistributes analytics workloads for latency-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale grid operators and heavy industrial facilities anchor procurement concentration across mature markets, with regulatory compliance timelines dicting deployment velocity. Cloud-native architectures find strongest traction among German municipal utilities and Texas independent power producers prioritizing deployment speed.
United States
Texas ERCOT operators and California investor-owned utilities drive demand for distributed energy resource aggregation platforms. FERC Order 2222 unlocks wholesale market participation for commercial aggregators, expanding software addressability. Houston and Austin industrial microgrids deploy hybrid edge-cloud architectures for latency-sensitive control applications.
Germany
Automotive suppliers in Baden-Württemberg and chemical processors in North Rhine-Westphalia anchor precision sub-metering procurement. EU Green Deal retrofit mandates accelerate commercial building stock upgrades in Munich and Frankfurt. ISO 50001 certification requirements concentrate qualified integrator relationships around Stuttgart industrial clusters.
Japan
Semiconductor fabs in Kyushu and automotive plants in Nagoya sustain demand for 0.5% accuracy class hardware. METI efficiency standards and grid code revisions mandate facility-level energy tracking for large industrial consumers. Osaka and Yokohama commercial districts consolidate around single-pane visibility platforms.
India
Steel and cement sectors in the Delhi-Mumbai Industrial Corridor drive greenfield deployment for integrated optimization platforms. CEA grid code revisions and PLI scheme incentives accelerate procurement timelines. Gujarat and Maharashtra industrial zones represent the steepest compliance curves for new capacity additions.
Brazil
Wind complexes in the Northeast and solar parks in Minas Gerais require forecasting and curtailment management platforms. Grid code revisions for variable generation integration expand addressable demand for control software. São Paulo commercial building operators consolidate vendor relationships around comprehensive retrofit approaches.
Energy Management Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with installed base advantages in building automation and grid-edge control. Concentration sits with European and North American vendors holding certification relationships for ISO 50001 implementation. Three archetypes dominate: platform-anchored integrators leveraging ecosystem partnerships, hardware-specialized manufacturers defending precision sensor margins, and energy-as-a-service operators bypassing customer capital constraints. Competitive moves center on API-first platform restructuring and professional services margin compression to match 90-day deployment timelines.
Within the platform-anchored tier, Schneider Electric, Siemens, and Honeywell International exemplify divergent specialization vectors. The French conglomerate occupies a position anchored in industrial deployment scale across European and Asian markets. The German engineering group exemplifies technology leadership through digital twin capabilities in grid-edge optimization. The US diversified manufacturer represents building automation convergence, extending installed base relationships into recurring service contracts. Each sits within distinct ecosystem partnerships that shape customer acquisition economics.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| General Electric |
| Honeywell International |
| ABB |
| Emerson Electric |
| Johnson Controls International |
| IBM Corporation |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month lead times for power management ICs and precision analog sensors concentrate pricing power among East Asian semiconductor foundries serving German and Japanese industrial buyers, compressing margins for sub-metering hardware vendors unable to pass through input cost volatility.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate hardware procurement, while software vendors deploy three-tier pricing structure across premium, standard, and economy levels tied to ISO 50001 certification status and data point volume tiers. Price differentiation rests on accuracy class certification and cloud deployment architecture, with 0.5% accuracy class devices commanding substantial premiums over commodity 1.0% alternatives. Pricing pressure stems from containerized microservices enabling consumption-based SaaS models that undercut perpetual-license incumbents. Mid-market commercial building operators exhibit highest price sensitivity, while utility-scale grid operators prioritize cybersecurity compliance over unit economics.
Supply Chain Analysis
Strategic stockpiling of precision analog components characterizes vendor inventory strategy, contrasting with just-in-time preferences among software platform providers. Hardware production concentrates in Taiwan, South Korea, and Japan, drawing from silicon wafers, rare-earth magnets, and specialized sensor substrates. Single-source vulnerability around advanced power management ICs creates supply chain risk as foundry capacity allocation favors automotive and consumer electronics. Distribution runs through certified system integrators and energy-as-a-service operators rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: ISO 50001 certification requirements and NERC CIP compliance frameworks create switching costs that protect incumbent relationships across multi-year deployment cycles.
For Market Incumbents: Fortify ecosystem partnerships with Kubernetes-orchestrated platform providers to accelerate 90-day deployment timelines against API-first challengers. Deepen backward integration into edge computing hardware to defend margin position as semiconductor input volatility persists. Prioritize certification investment in CSRD emissions calculation engines to capture premium pricing from European automotive suppliers facing steepest disclosure mandates.
For New Entrants and Emerging Players: ISO 50001 lead auditor fast-track programs unlock implementation bottleneck relief for multinational industrial deployments spanning Germany and Japan. White-space concentration sits with mid-market commercial building operators in India and Brazil bypassing legacy SCADA infrastructure entirely. Target energy-as-a-service channel partnerships to bypass customer balance sheet constraints and accelerate recurring revenue capture.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core energy software assets amid platform consolidation pressures. Long-term viability favors vendors with demonstrated FERC Order 2222 aggregation software deployments and established utility relationships. Monitor CEA grid code revision implementation velocity in India as inflection indicator for greenfield platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Restructuring | Schneider Electric and Siemens accelerate deployment timelines to under 90 days for Texas ERCOT operators. |
| Edge Computing Hardware Integration | Hybrid architectures address latency-sensitive control requirements in Japanese automotive microgrids. |
| ISO 50001 Certification Expansion | Qualified integrator relationships concentrate around Stuttgart and Baden-Württemberg industrial clusters. |
| Energy-as-a-Service Channel Development | Third-party ownership models bypass capital constraints among New York university campuses. |
| CSRD Compliance Module Investment | Emissions calculation engines capture premium pricing from French hospital systems facing disclosure mandates. |
Methodological Framework
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions driving this analysis. Primary interviews with energy management software vendors and certified system integrators combined with secondary validation from FERC filings, EIA data, IEA reports, and project development databases. Bottom-up triangulation across facility-level deployment data and top-down reconciliation against utility capex disclosures anchored volume estimates.
Segmentation dimensions modeled span product architecture, application category, end-user type, and installation topology across the projection horizon. CAGRs derive from regression analysis of historic deployment velocity against regulatory compliance timelines and infrastructure investment cycles. Forecast inputs incorporate grid code revision schedules, PLI scheme incentive trajectories, and semiconductor lead-time normalization assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued cloud migration preferences; material deviation would warrant model refresh. Specific risk factors include NERC CIP framework evolution accelerating compliance cost burdens, and legacy SCADA substitution resistance extending replacement cycles beyond modeled assumptions. Revision becomes warranted when India PLI scheme disbursement velocity crosses thresholds indicating accelerated greenfield procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Global Utility Asset Management Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Energy ESO Market
Energy Management
Global Energy Consumption Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Brazil Energy Sector Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Microgrid Control System Market
Energy Management
Electric Sub-Meter Market
Energy Management
Industrial Energy Management System Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
Energy Harvesting System Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market