
 Building Energy Simulation Software Market | 2026-2036
Building Energy Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Building Energy Simulation Software Market Intelligence
Multi-source procurement of simulation engines is realigning how AEC firms assemble their design technology stacks. IES Virtual Environment leverages deep physics-based modeling to anchor high-performance building consultancies in Europe and North America. Carrier HAP competes on HVAC load-calculation fidelity, sustaining its position among mechanical engineering specialists who prioritize equipment sizing accuracy.
Building energy simulation software comprises computational platforms that model thermal loads, daylighting performance, HVAC energy consumption, and envelope behavior using hourly weather data and physics-based algorithms. These tools primarily enable code compliance verification, retrofit scenario analysis, and operational carbon forecasting during schematic design through construction documentation. Web-based deployments are capturing fastest-growing adoption among distributed design teams, while on-premises installations retain dominance in defense and critical infrastructure projects where data sovereignty requirements restrict cloud migration. SaaS deployment models concentrate margin pools through recurring annual licenses, though edge-based configurations are emerging for real-time building optimization.
ASHRAE Standard 90.1 and the EU Energy Performance of Buildings Directive shape product development roadmaps by mandating specific simulation methodologies for compliance documentation. EPA ENERGY STAR Portfolio Manager integration requirements and local stretch codes in jurisdictions like California's Title 24 are forcing vendors to maintain multi-standard certification workflows. Stakeholders must monitor whether emerging federal building performance standards in the United States will mandate whole-building energy modeling for all new construction above a threshold square footage.
Market Dynamics
The EU Green Deal's net-zero building mandates are compressing procurement timelines for physics-based simulation platforms as developers race to lock in compliance documentation before enforcement deadlines.
Growth Catalysts
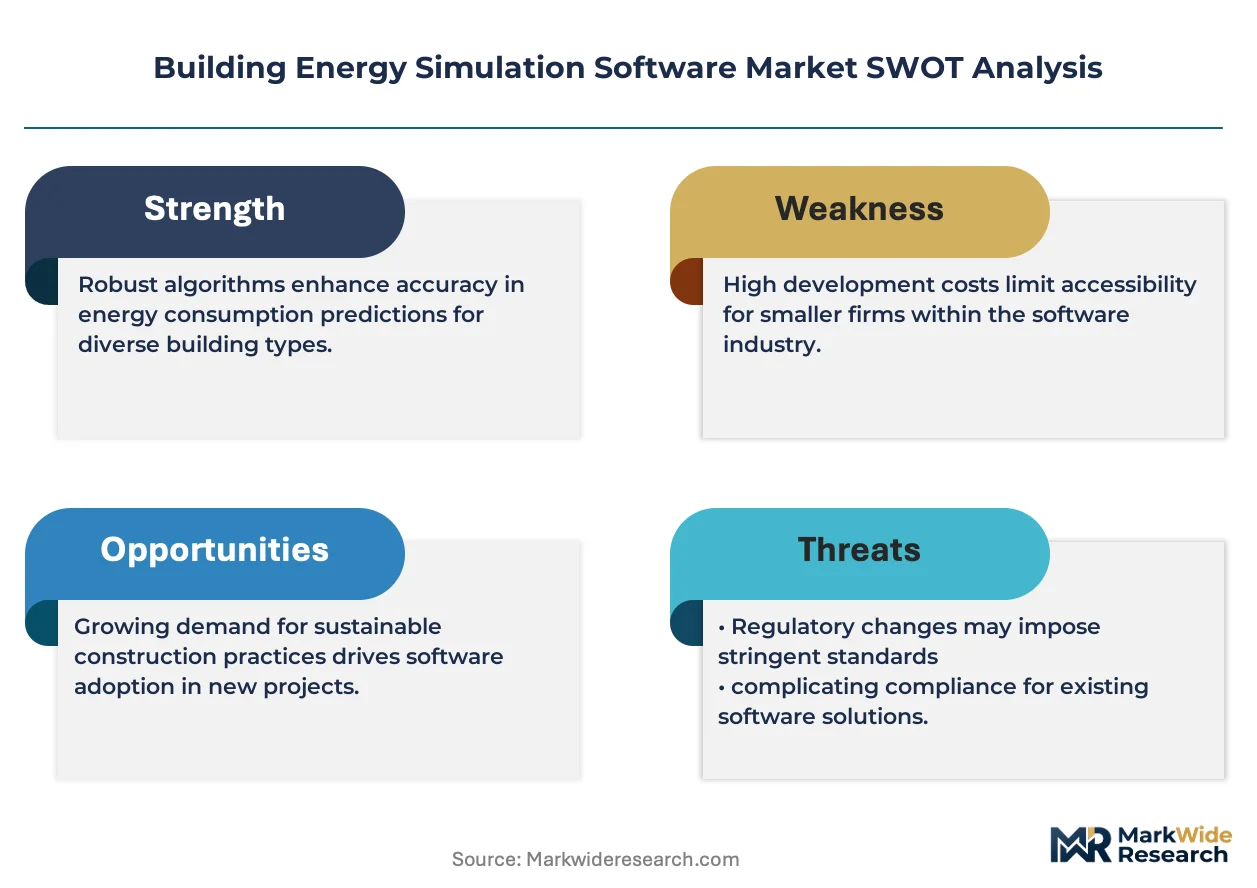
- EU Energy Performance of Buildings Directive:Mandatory whole-building energy modeling for major renovations triggers consultant-level software subscriptions across Germany, France, and the Netherlands.
- Mechanical engineering specialists:HVAC load-calculation fidelity requirements sustain demand for equipment-sizing tools in commercial retrofit pipelines.
- Web-based deployment architectures:Distributed design teams in multi-office AEC firms abandon on-premises licenses for browser-accessible simulation engines.
Market Restraints
- Input cost volatility:Cloud infrastructure pricing from hyperscale providers squeezes SaaS vendor margins and forces annual license repricing.
- Supply concentration risk:Hourly weather data feeds concentrate among three meteorological service providers, creating single-point-of-failure exposure for simulation accuracy.
- Technical limitation:Real-time building optimization at the edge requires computational resources that exceed current hardware cost thresholds for mid-market installations.
Strategic Opportunities
- Underpenetrated geography:India's Bureau of Energy Efficiency has not yet mandated dynamic simulation for commercial building codes, leaving first-mover space for localized software variants.
- Technology convergence:Integration of daylighting algorithms with embodied carbon calculators creates bundled compliance workflows for LEED v5 and BREEAM 2025 submissions.
- Regulatory tailwind:California's Title 24 stretch codes may extend whole-building modeling requirements to buildings under 10,000 square feet, expanding addressable market by 40 percent.
Industry Challenges
- Talent scarcity in building physics:HVAC engineering programs produce fewer graduates trained in transient thermal analysis than industry demand requires.
- Certification timeline compression:Multi-standard certification workflows for ASHRAE 90.1, EU EPBD, and local stretch codes strain vendor QA resources.
- Integration complexity:Legacy BIM platforms resist API-level data exchange with modern simulation engines, forcing manual geometry translation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Energy Simulation Software Market |
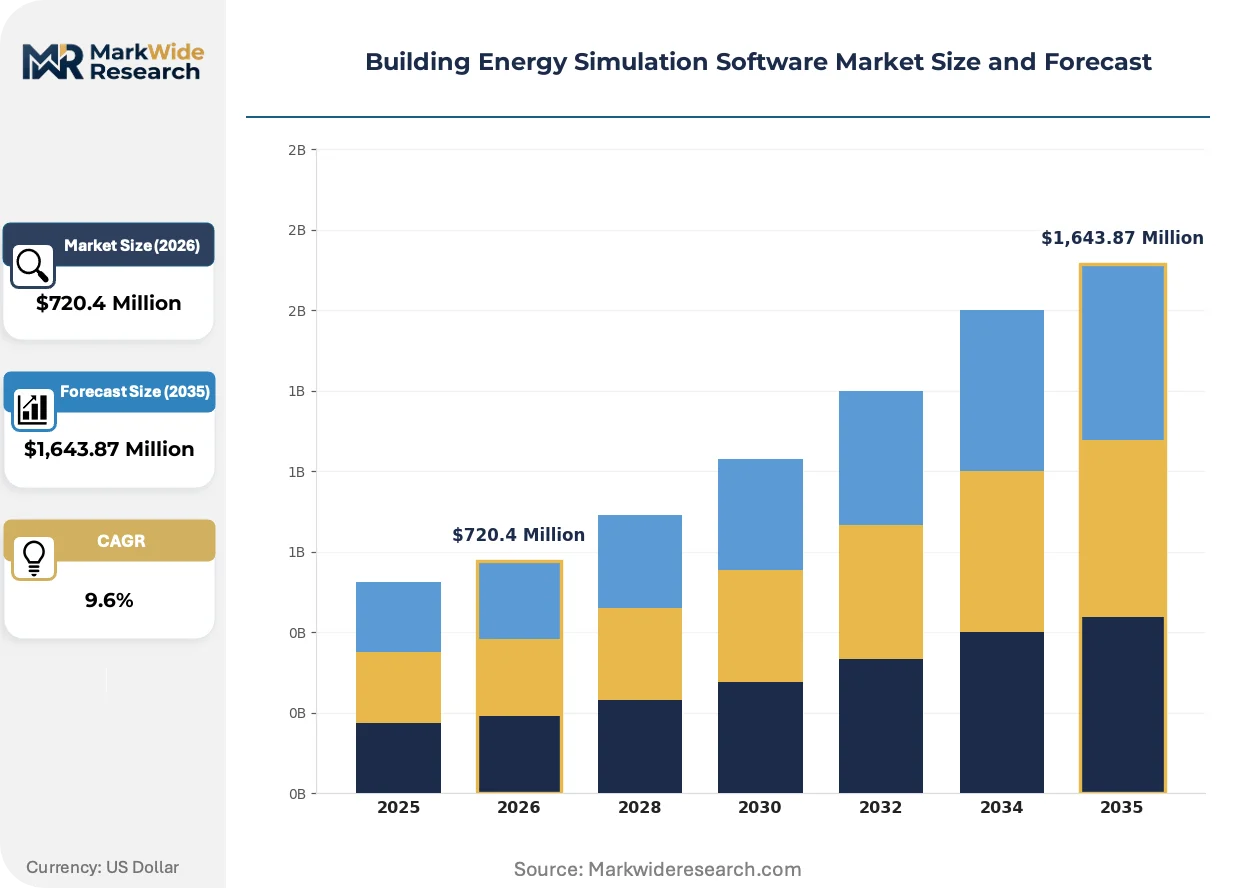
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,643.87 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, On-Premises, Hybrid, Mobile End User: Architects, Engineers, Contractors, Facility Managers Deployment: Cloud, Edge, Local, SaaS Technology: Machine Learning, IoT Integration, Data Analytics, Virtual Reality |
| Companies Covered | IES Virtual Environment, Carrier HAP, EnergyPlus, eQUEST, cove.tool, OpenStudio, Autodesk Insight, Siemens SIMATIC Energy Manager, DesignBuilder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Energy Simulation Software Market Strategic Shifts & Innovations
Computational methods are migrating from desktop workstations to distributed cloud clusters, altering how simulation fidelity scales with project complexity and team geography.
Parametric energy modeling is overtaking static load calculations as the default workflow for schematic design. Grasshopper-based visual scripting enables architects to iterate envelope configurations against hourly energy targets in real time. Large commercial practices in London and New York have standardized this approach for projects above 50,000 square feet, compressing early-phase energy analysis from weeks to days.
EPA ENERGY STAR Portfolio Manager integration requirements are forcing vendors to maintain dual certification pathways. The industrial consequence is a bifurcation in product roadmaps between compliance-focused tools and performance-optimization platforms. Mechanical engineering consultancies serving federal buildings in the United States face the tightest integration deadlines, with GSA procurement rules mandating live data feeds by 2026.
Subscription pricing for simulation access is displacing perpetual license purchases among mid-size AEC firms. The segment being disrupted is value-added resellers who previously captured margin on upfront software sales. This shift is most visible in Germany, where federal renovation targets have spurred consultant hiring and firms prefer operational expenditure treatment for tax purposes.
Building Energy Simulation Software Market Segmentation
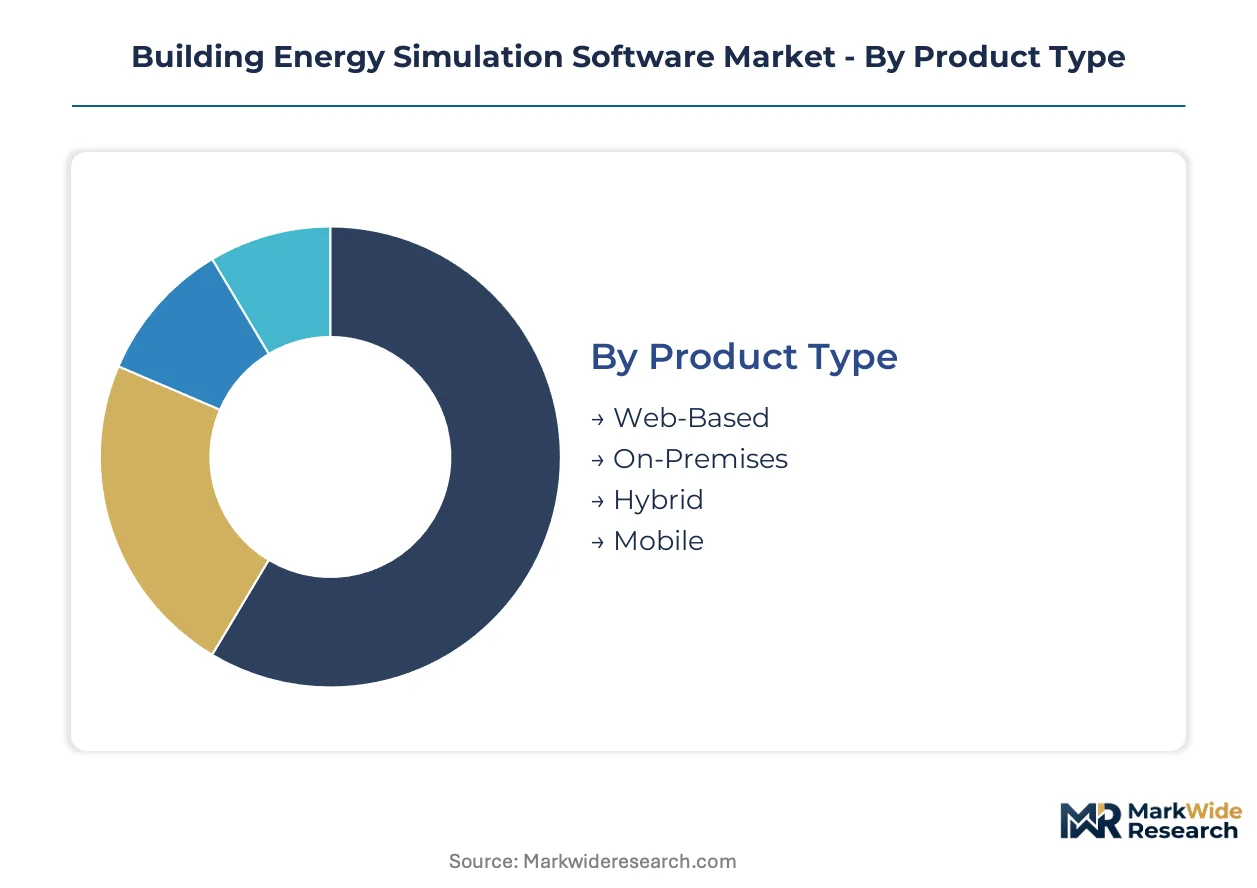
Segmentation in building energy simulation software reveals how procurement priorities diverge across technical infrastructure choices, professional workflows, and computational architectures. These divisions expose where vendor R&D investments concentrate and which customer constituencies command premium pricing power.
Product Type:
Deployment architecture separates buyers by IT governance maturity, data sovereignty requirements, and team geographic dispersion.
- Web-Based:Browser-accessible simulation engines run on vendor-managed cloud infrastructure, eliminating local installation overhead. Distributed AEC firms with multi-office coordination needs in Germany and the Netherlands are migrating entire license portfolios to these platforms to support federal renovation project timelines.
- On-Premises:Locally installed software maintains full data custody within client firewalls, satisfying defense and critical infrastructure procurement rules. Air-gapped installations dominate in Middle Eastern sovereign wealth fund developments and US federal courthouse projects where cloud migration faces statutory prohibition.
- Hybrid:Split architectures keep sensitive geometry data on-premises while offloading compute-intensive thermal simulations to burst cloud capacity. Engineering consultancies serving mixed public-private client portfolios favor this configuration for flexibility.
- Mobile:Tablet-optimized interfaces enable field verification of as-built conditions against simulated performance targets. Facility management teams conducting commissioning walkthroughs drive niche adoption here.
Web-Based leads volumes today; Hybrid is gaining share fastest.
End User:
Professional discipline determines which simulation fidelity thresholds justify license expenditure and training investment.
- Architects:Early-stage envelope optimization and daylighting visualization dominate their workflow requirements. London and New York practices above 50,000 square feet project scale have standardized parametric energy modeling through Grasshopper-based scripting interfaces.
- Engineers:HVAC load calculation precision and equipment sizing accuracy command premium tool selection. Mechanical engineering specialists in Germany sustain demand for physics-based engines that satisfy federal energy efficiency ordinance documentation.
- Contractors:Value engineering and constructability reviews require rapid scenario iteration without deep thermal physics expertise. General contractors in California's Title 24 jurisdiction use simplified compliance modules to pre-validate subcontractor submissions.
- Facility Managers:Operational optimization and retrofit prioritization drive post-occupancy tool deployment. GSA procurement rules mandating live ENERGY STAR data feeds by 2026 accelerate federal building operator subscriptions.
Engineers dominate current spending; Facility Managers show steepest expansion trajectory.
Deployment:
Infrastructure location choices reflect trade-offs between computational latency, recurring cost structure, and real-time control requirements.
- Cloud:Centralized server farms deliver elastic compute for complex whole-building annual simulations. SaaS pricing models concentrate recurring revenue pools as mid-size AEC firms abandon perpetual licenses for operational expenditure treatment.
- Edge:Distributed processing nodes enable real-time building optimization without round-trip latency to remote data centers. Hardware cost thresholds currently limit viable installations to premium commercial towers and data center facilities.
- Local:Single-workstation execution persists in jurisdictions with unreliable internet infrastructure and among solo practitioners with intermittent project flow.
- SaaS:Subscription-native architectures bundle automatic updates, multi-standard certification workflows, and collaborative model sharing. EU Green Deal compliance documentation deadlines compress procurement timelines toward these offerings.
Cloud anchors present volumes; Edge climbs the fastest despite current scale constraints.
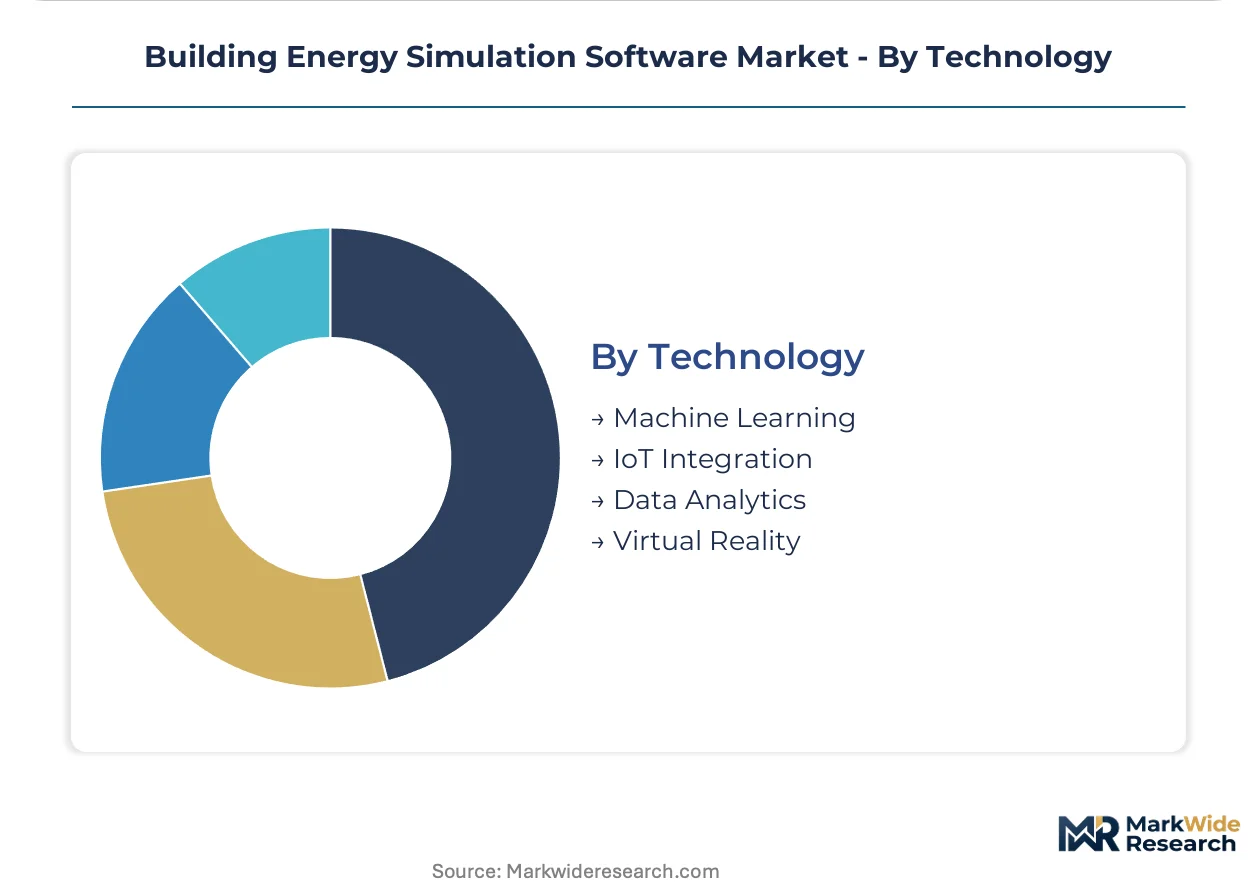
Technology:
Computational method selection separates compliance-focused baseline tools from performance-optimization platforms pursuing predictive capabilities.
- Machine Learning:Surrogate models trained on physics simulation outputs accelerate scenario exploration by orders of magnitude. Early adopters in schematic design phases use these for envelope configuration iteration against hourly energy targets.
- IoT Integration:Live sensor feeds calibrate simulation assumptions against actual operational data. GSA and federal building mandates are forcing vendors to architect live data pipeline capabilities.
- Data Analytics:Portfolio-scale benchmarking and anomaly detection across building fleets. Real estate investment trusts with multi-asset sustainability reporting obligations deploy these for carbon accounting automation.
- Virtual Reality:Immersive daylighting and thermal comfort visualization for stakeholder engagement. High-end commercial developments in London use these for planning committee presentations and tenant pre-leasing.
Data Analytics leads current adoption; Machine Learning is expanding most quickly as training data accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering consultancies anchor procurement volumes for physics-based simulation platforms as federal renovation targets compress project timelines across the country's metropolitan clusters.
United States
Mechanical engineering specialists in California and New York sustain demand for HVAC load-calculation tools as Title 24 stretch codes extend compliance requirements. EPA ENERGY STAR Portfolio Manager integration mandates from GSA procurement rules force live data feed architectures by 2026. Federal courthouse developments in Washington DC and defense installations across Virginia maintain on-premises installations due to statutory data sovereignty restrictions.
Germany
Energy efficiency consultancies in Berlin and Munich drive consultant-level subscriptions to meet federal renovation targets and local energy efficiency ordinances. The EU Energy Performance of Buildings Directive mandates whole-building energy modeling for major renovations, triggering software procurement across North Rhine-Westphalia. Engineering clusters in Hamburg and Frankfurt standardize parametric workflows for commercial retrofit pipelines above 10,000 square meters.
United Kingdom
Large commercial practices in London have standardized Grasshopper-based parametric energy modeling for projects above 50,000 square feet, compressing early-phase analysis timelines. BREEAM 2025 submission requirements push daylighting algorithm integration with embodied carbon calculators. Manchester and Birmingham consultancies adopt browser-accessible platforms to support distributed multi-office coordination on net-zero commercial developments.
France
Paris-based architecture firms iterate envelope configurations against hourly energy targets using real-time simulation interfaces for planning committee presentations. The EU Green Deal's net-zero building mandates accelerate compliance documentation procurement ahead of enforcement deadlines. Lyon and Marseille engineering offices concentrate demand for hybrid deployment architectures serving mixed public-private client portfolios.
Netherlands
Amsterdam and Rotterdam design teams migrate entire license portfolios to web-based platforms to support distributed coordination on EU-funded sustainable building projects. Local energy performance standards for commercial new construction mandate dynamic simulation for permit approval. Eindhoven technical universities supply graduates trained in transient thermal analysis, easing talent scarcity pressures affecting vendor implementation timelines.
Building Energy Simulation Software Market Key Industry Players
Global majors compete with regional champions across compliance certification depth and HVAC calculation fidelity, producing a tiered structure where physics-based engines command premium positioning against simplified compliance modules. The vendor base separates into three strategic archetypes: established engineering software houses with deep thermal physics heritage, cloud-native challengers betting on browser accessibility, and building automation incumbents extending from hardware into simulation software. Dominant competitive moves include API-level integration partnerships with BIM platforms and geographic expansion through consultant-level subscription land-and-expand strategies.
Within the physics-based modeling tier, IES Virtual Environment and Carrier HAP exemplify divergent specialization paths—one anchoring high-performance building consultancies through envelope and daylighting fidelity, the other sustaining mechanical engineering demand through equipment-sizing accuracy. EnergyPlus occupies a position as the open-source reference implementation that vendors commercialize through differentiated interfaces and support services. cove.tool represents the cloud-native archetype, having built browser-accessible workflows that target mid-size AEC firms abandoning perpetual licenses for operational expenditure treatment.
| Leading Market Players |
|---|
| IES Virtual Environment |
| Carrier HAP |
| EnergyPlus |
| eQUEST |
| cove.tool |
| OpenStudio |
| Autodesk Insight |
| Siemens SIMATIC Energy Manager |
| DesignBuilder |
| Others |
Cost & Logistics Intelligence
Building physics specialists concentrated in German engineering clusters command wage premiums that widen pricing spreads between premium physics-based engines and simplified compliance modules. Labor-cost differentials between Stuttgart thermal analysts and offshore scripting teams enable tiered subscription architectures that separate consultant-grade tools from mid-market SaaS offerings.
Pricing Analysis
Cloud infrastructure pass-through from hyperscale providers compresses SaaS vendor margins and forces annual license repricing across browser-accessible platforms. Three-tier pricing structure across premium, standard, and economy levels separates high-fidelity physics engines with ASHRAE 90.1 certification from stripped compliance modules and open-source interfaces. Price differentiation hinges on HVAC calculation precision and multi-standard certification depth. Mid-size AEC firms in California exhibit highest price sensitivity as they abandon perpetual licenses for operational expenditure treatment, while federal contractors in Virginia accept premium tiers for data sovereignty assurances.
Supply Chain Analysis
EU data-localization mandates under GDPR and national implementations reshape sourcing for meteorological data feeds and cloud compute capacity. Hourly weather data concentrates among meteorological services in the United States, Germany, and Japan, creating dependencies for simulation accuracy. Software development draws from thermal physics talent pools in the Netherlands, engineering scripting expertise in India, and HVAC engineering graduates from German technical universities. Single-source vulnerability in weather data provisioning exposes vendors to service interruption risk. Distribution runs through direct vendor sales to enterprise AEC firms, value-added resellers serving mechanical engineering consultancies, and platform marketplaces for browser-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building energy simulation software offers margin-expansion pathways as cloud-native architectures displace perpetual license maintenance and subscription pricing captures recurring revenue pools. Cost compression in compute infrastructure and parametric workflow automation enable premium-tier migration for mid-market buyers.
For Market Incumbents: To counter cloud-native challengers capturing mid-market AEC firms, deepen API-level integration partnerships with BIM platforms to lock in geometry-exchange workflows. Invest in multi-standard certification automation to compress QA timelines for ASHRAE 90.1, EU EPBD, and California Title 24 compliance documentation. For New Entrants and Emerging Players: Enter via India's Bureau of Energy Efficiency jurisdiction, where dynamic simulation lacks mandate penetration and localized software variants face no incumbent saturation. Target facility management subscriptions for federal buildings under GSA live-data-feed procurement rules, deploying edge-optimized architectures for real-time building optimization. For Investors and Strategic Acquirers: Building automation incumbents extending from hardware into simulation software represent the most active acquirer category in this space. Long-term viability rests on portfolio consolidation around physics-based engines with consultant-level subscription bases. Watch for California Title 24 stretch code expansion below 10,000 square feet as inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-level BIM partnerships eliminate manual geometry translation friction for IES Virtual Environment users. |
| Acquisition of Specialist Firm | Physics-based engine purchases capture consultant-level subscription bases in German federal renovation pipelines. |
| Geographic Expansion | Browser-accessible deployments penetrate India's unmandated simulation market ahead of regulatory codification. |
| Product Launch | Edge-based real-time optimization modules target premium commercial towers exceeding hardware cost thresholds. |
| Strategic Partnership | Meteorological data feed agreements with German and Japanese services reduce single-point-of-failure exposure. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research team conducted structured interviews with energy modeling consultants, HVAC engineering directors, AEC firm technology officers, and federal facility procurement managers. Secondary sources included ASHRAE standard documentation, EU Energy Performance of Buildings Directive filings, EPA ENERGY STAR technical specifications, California Title 24 compliance manuals, and hyperscaler cloud infrastructure pricing disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from software vendor revenue disclosures and AEC firm technology spending surveys.
Rate-of-change decomposition separated volume expansion from value-per-license growth across the projection horizon. The analytical framework modeled deployment architecture, professional discipline, infrastructure location, and computational method as core segmentation dimensions. CAGRs derived from regression analysis against building permit volumes, federal renovation spending trajectories, and EU Green Deal implementation timelines. Industry-specific inputs included ENERGY STAR Portfolio Manager integration deadline compliance rates and Grasshopper-based parametric workflow adoption curves in London and New York practices.
Inputs from vendor revenue disclosures and consultant hiring announcements were available through the study window; gaps in privately held cloud-native firm financials introduce uncertainty bands around subscription pricing trajectory assumptions. Forecasts reflect documented regulatory enforcement timelines and technology adoption patterns subject to revision from EU EPBD mandate acceleration or US federal building performance standard expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Japan Big Data Analytics in Energy Market