
 European Building Energy Management Systems Market | 2026-2036
European Building Energy Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
European Building Energy Management Systems Market Foresight
Multi-source procurement of BEMS software modules is realigning how European facility managers assemble vendor portfolios. Siemens AG leverages its building automation heritage to sustain dominance in integrated hardware-software bundles across German industrial complexes. Schneider Electric SE competes through specialized edge-computing controllers that anchor its position in French commercial real estate retrofits.
European Building Energy Management Systems encompass networked platforms that monitor, control, and optimize HVAC, lighting, and electrical loads through real-time data acquisition and automated setpoint adjustment. These systems typically operate via BACnet or Modbus protocols, processing inputs from wireless sensor arrays to reduce aggregate energy consumption in multi-zone facilities. Software solutions command the dominant margin pool as recurring licensing models displace perpetual deployments, while cloud-based architectures represent the fastest-expanding deployment category by eliminating on-site server maintenance burdens. Hardware segments remain structurally mature, with sensor commoditization compressing unit economics even as volume expands across industrial end-user installations.
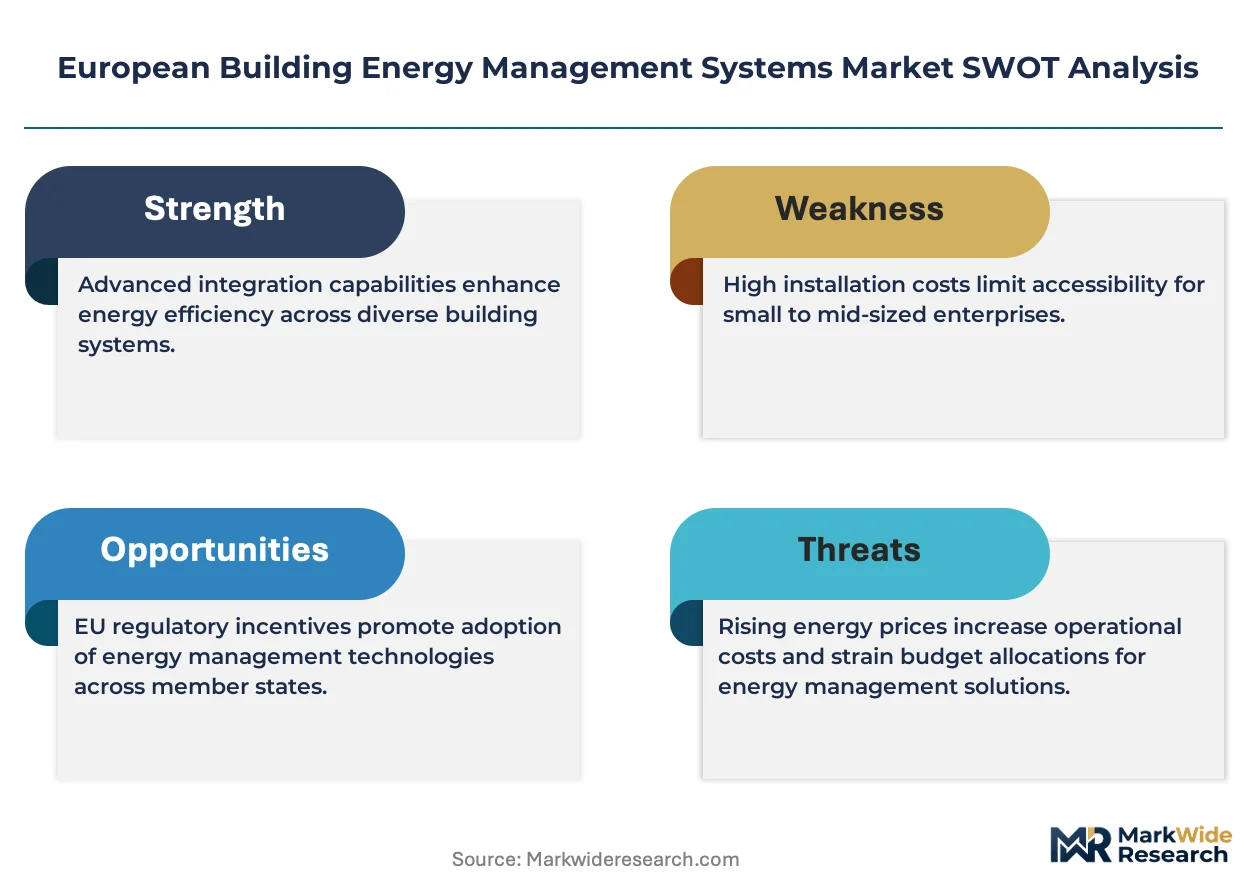
The EU Green Deal's building renovation targets, enforced through national transpositions of the Energy Performance of Buildings Directive, compel member states to mandate smart metering infrastructure in large commercial structures. ECHA's evolving restrictions on refrigerants under the F-Gas Regulation further shape BEMS specification requirements for HVAC-linked platforms. Stakeholders must monitor how the EU AI Act's risk classification protocols apply to autonomous building control algorithms, as compliance costs could reshape vendor competitive dynamics and procurement criteria across the continent.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing deployment timelines for networked energy platforms across European commercial real estate. Facility operators face binding efficiency targets that require immediate sensor infrastructure upgrades and predictive control system integration.
Growth Catalysts
- F-Gas Regulation refrigerant phase-down:HVAC-linked BEMS deployments accelerate as facility managers retrofit systems to monitor alternative refrigerant performance and leak detection.
- Netherlands district heating networks:Amsterdam's municipal retrofit programs generate concentrated procurement of integrated thermal management platforms with real-time load balancing.
- Cloud-native architectures:Recurring SaaS licensing models displace perpetual software deployments, reducing upfront capital barriers for mid-sized facility operators.
Market Restraints
- Sensor commoditization:Hardware margin compression intensifies as Asian manufacturers flood European markets with low-cost wireless temperature and occupancy sensors.
- Legacy BACnet integration costs:Pre-2010 building automation systems require expensive protocol bridging equipment to connect with modern IP-based analytics platforms.
- Cybersecurity certification delays:EU Cybersecurity Act conformity assessments for networked building systems extend vendor time-to-market by 8-14 months.
Strategic Opportunities
- Polish commercial real estate:Warsaw and Krakow office construction booms create first-mover advantages for BEMS vendors establishing localized service partnerships.
- AI Act risk classification:Autonomous HVAC control algorithms face new compliance categories that favor established vendors with documented algorithmic governance frameworks.
- Edge-computing convergence:On-premise inference engines combined with cloud analytics enable sub-second setpoint adjustments for industrial process cooling applications.
Industry Challenges
- Interoperability skill scarcity:Facility engineering teams lack expertise bridging Modbus, BACnet, and proprietary IoT protocols in mixed-vendor environments.
- CSRD data architecture:Corporate sustainability reporting requirements demand granular energy consumption tracking that exceeds current BEMS metering densities in older buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Building Energy Management Systems Market |
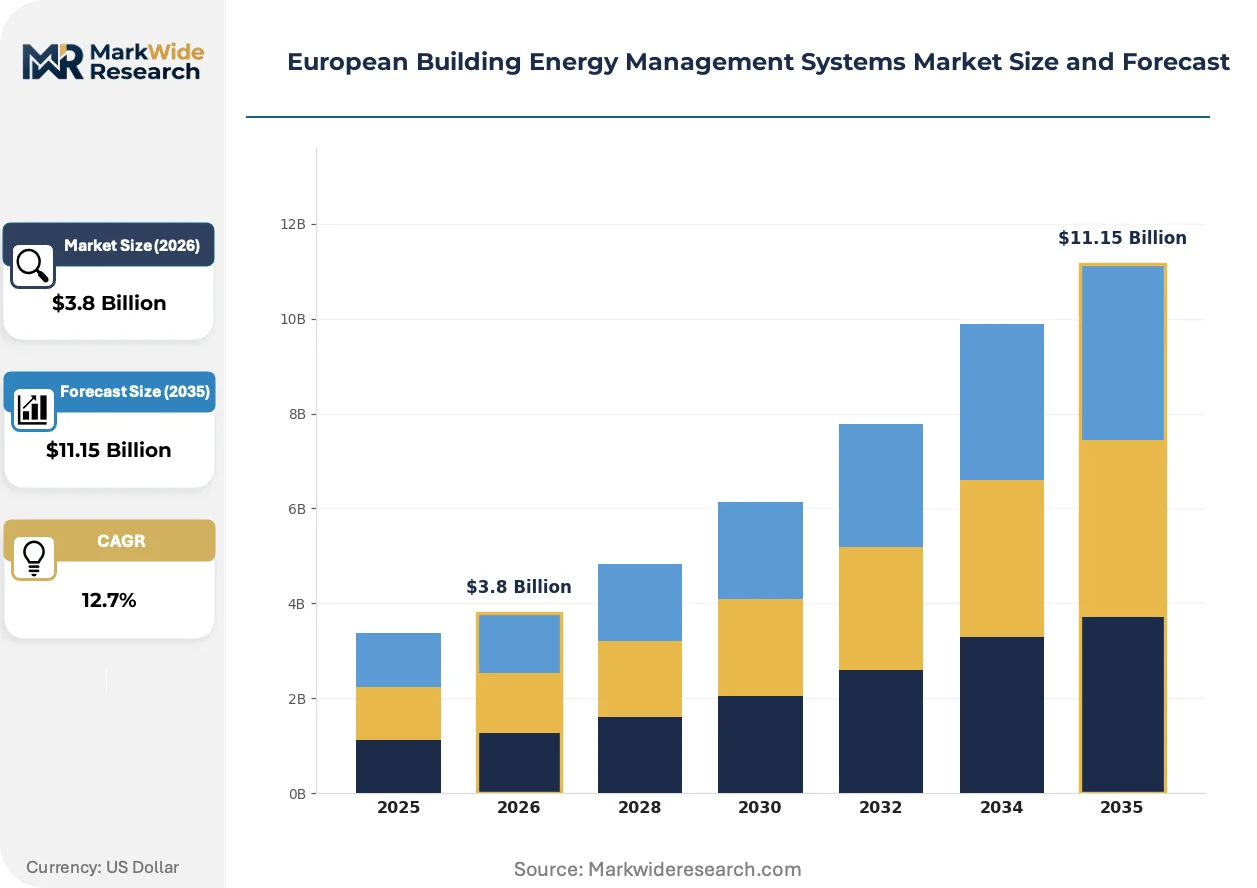
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Controls End User: Residential, Commercial, Industrial, Government Deployment: On-Premise, Cloud-Based, Hybrid, Co-Location Technology: IoT, AI, Data Analytics, Machine Learning |
| Companies Covered | Johnson Controls International Plc, Rockwell Automation, Siemens AG, Priva Holding BV, Kieback&Peter GmbH & Co. KG, Schneider Electric SE, ABB Ltd, Bosch, Honeywell International Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Building Energy Management Systems Market Shifts & Advancements
Digital twin technology is compressing commissioning cycles for complex multi-zone facilities. Three interconnected developments are restructuring how European operators specify, deploy, and monetize building energy management infrastructure.
Digital twin platforms are overtaking traditional simulation-based design workflows. These virtual replicas integrate real-time sensor feeds with physics-based HVAC performance models. German industrial facility operators deploy them to pre-validate control sequences before physical commissioning. The technology is overtaking rule-based energy optimization by enabling continuous model-predictive control that adapts to occupancy pattern shifts without manual recalibration.
CSRD corporate sustainability reporting mandates reshape procurement criteria for listed real estate investment trusts. The directive requires granular Scope 1 and 2 emissions disclosure that legacy metering infrastructure cannot support. French commercial landlords now specify BEMS with sub-circuit monitoring capabilities as standard lease compliance infrastructure. Implementation timelines compress as property managers face audit-ready data requirements from fiscal year 2025.
Facility management outsourcing contracts unbundle energy optimization from traditional hard services. Dutch and Danish commercial property investors now procure BEMS analytics as standalone performance-guaranteed subscriptions. This purchasing pattern concentrates vendor selection authority with centralized procurement functions rather than distributed site engineering teams. The shift is most visible in Rotterdam's port logistics facilities and Copenhagen's Nordic office portfolios.
European Building Energy Management Systems Market Segmentation
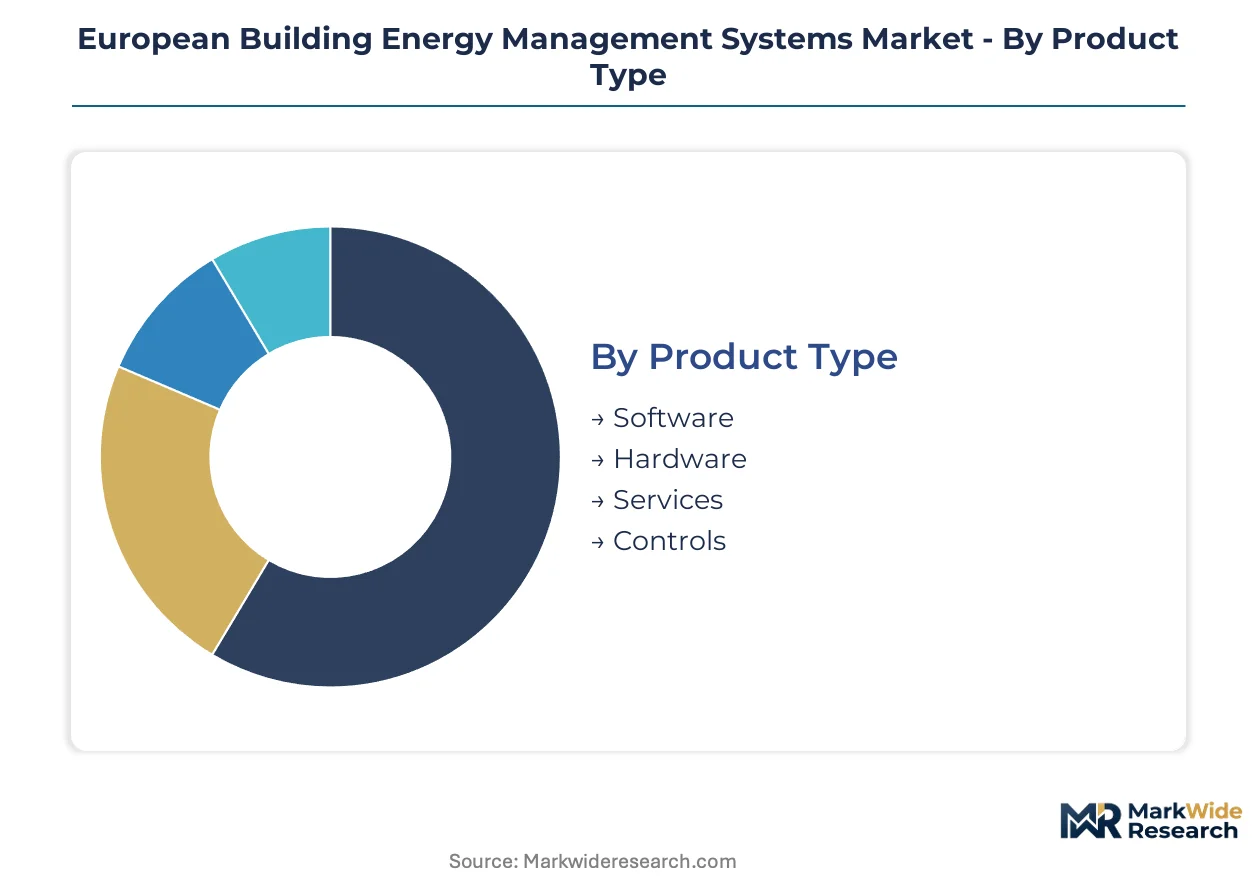
European facility operators select BEMS components through divergent procurement lenses. Software licensing models, deployment architectures, and end-use regulatory exposure each reshape vendor selection criteria and contract structures across the continent.
Product Type:
Facility managers weight capital intensity against recurring operational expenditure when selecting product categories.
- Software:Cloud-native platforms with subscription licensing dominate procurement in French and Dutch commercial real estate. CSRD disclosure mandates drive demand for granular analytics modules that automate Scope 1 and 2 emissions reporting.
- Hardware:Wireless sensor arrays and edge-computing controllers anchor German industrial deployments. BACnet/IP protocol compatibility determines interoperability with legacy building automation systems in pre-2010 structures.
- Services:Performance-guaranteed energy optimization contracts unbundle from traditional facility management in Danish and Dutch outsourcing arrangements.
- Controls:Programmable logic controllers and direct digital control systems integrate HVAC, lighting, and electrical load management in multi-zone facilities.
Software leads on scale; controls lead on momentum as EU Green Deal retrofit deadlines compress deployment timelines.
End User:
Regulatory exposure intensity varies sharply across building ownership structures.
- Commercial:Real estate investment trusts in France and the Netherlands face binding CSRD disclosure requirements. Sub-circuit metering capabilities now appear as standard lease compliance infrastructure.
- Industrial:German manufacturing complexes deploy model-predictive control for process cooling optimization. ECHA F-Gas Regulation refrigerant phase-down mandates accelerate HVAC-linked BEMS retrofits.
- Government:Public procurement frameworks across EU member states mandate smart metering infrastructure in large administrative buildings under EPBD transpositions.
- Residential:Multi-family housing associations in Amsterdam's district heating zones pilot integrated thermal management platforms with real-time load balancing.
Commercial installations dominate current revenue; industrial deployments gain share fastest as process cooling applications expand.
Deployment:
IT governance preferences and data sovereignty concerns reshape architecture selection.
- Cloud-Based:SaaS licensing eliminates on-site server maintenance burdens for mid-sized facility operators. Dutch and Danish property investors procure analytics as standalone performance-guaranteed subscriptions.
- Hybrid:On-premise inference engines combined with cloud analytics enable sub-second setpoint adjustments. German industrial operators favor this architecture for autonomous HVAC control under EU AI Act risk classification protocols.
- On-Premise:Legacy installations persist in facilities with stringent cybersecurity requirements or limited connectivity reliability.
- Co-Location:Third-party data center hosting addresses data residency requirements for cross-border real estate portfolios.
Cloud-based architectures command volume leadership; hybrid deployments show steepest expansion trajectory as edge-computing converges with centralized analytics.
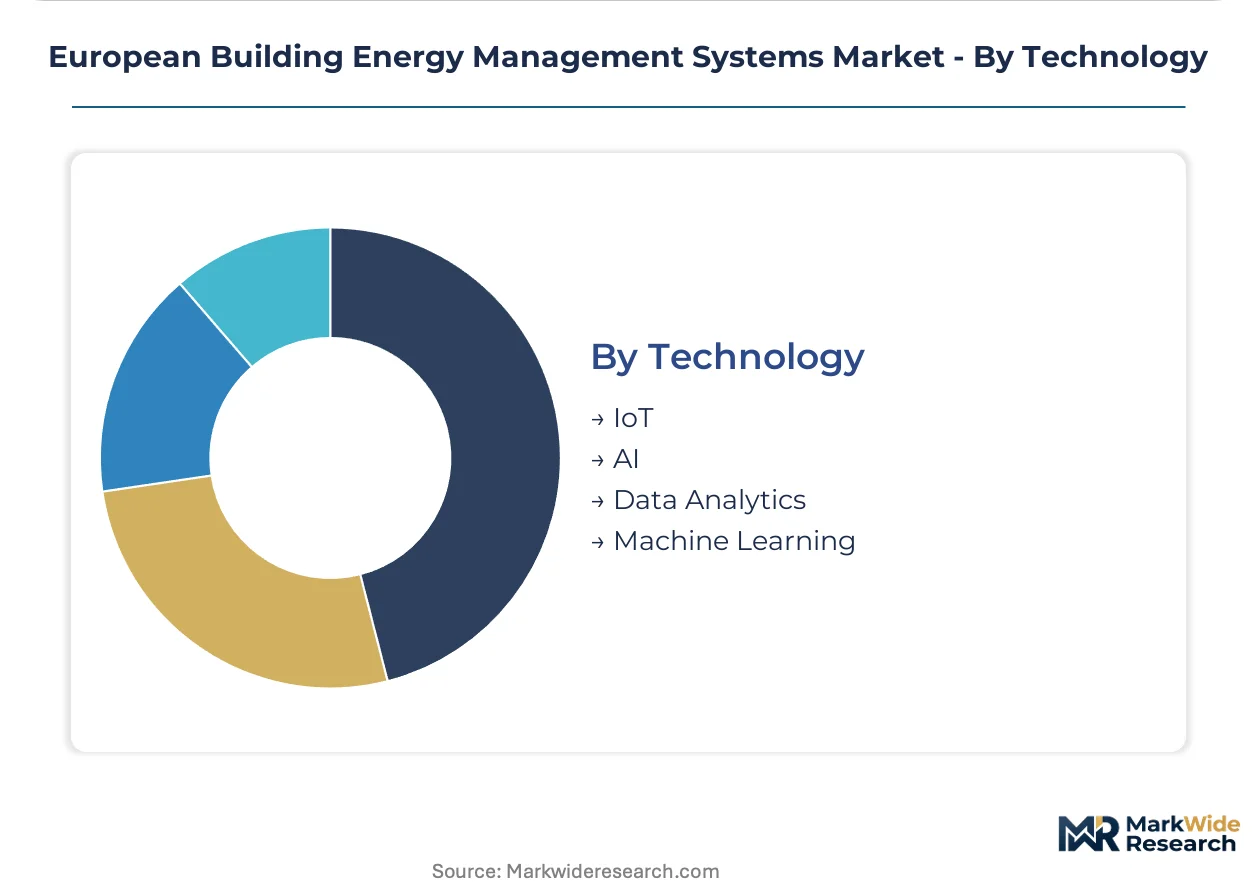
Technology:
Technology stack selection determines predictive capability and integration complexity.
- IoT:Wireless sensor networks using BACnet or Modbus protocols feed real-time data to central analytics platforms. Commoditization of temperature and occupancy sensors compresses hardware margins even as volume expands.
- AI:Autonomous control algorithms face new compliance categories under EU AI Act risk classification protocols. Documented algorithmic governance frameworks favor established vendors in procurement evaluations.
- Data Analytics:Granular energy consumption tracking exceeds legacy metering densities in older buildings. CSRD audit-ready data requirements compress implementation timelines for listed real estate operators.
- Machine Learning:Continuous model-predictive control adapts to occupancy pattern shifts without manual recalibration. Digital twin platforms integrate real-time sensor feeds with physics-based HVAC performance models.
IoT anchors installed base scale; machine learning drives technology refresh cycles as digital twin adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amsterdam's district heating retrofits anchor procurement concentration across the continent. Rotterdam's smart port logistics facilities and Copenhagen's Nordic office portfolios drive integrated energy management demand. Facility operators in Warsaw and Krakow accelerate deployments as commercial construction booms reshape Eastern European procurement patterns.
Germany
Industrial facility operators in North Rhine-Westphalia and Bavaria deploy model-predictive control for process cooling optimization. The ECHA F-Gas Regulation refrigerant phase-down mandates accelerate HVAC-linked BEMS retrofits across manufacturing complexes. Siemens AG leverages its building automation heritage to sustain dominance in integrated hardware-software bundles throughout German industrial zones.
Netherlands
Amsterdam's municipal retrofit programs generate concentrated procurement of integrated thermal management platforms with real-time load balancing. The EU Green Deal's building renovation targets enforce smart metering infrastructure mandates through national EPBD transpositions. Rotterdam's port logistics facilities unbundle BEMS analytics as standalone performance-guaranteed subscriptions under centralized procurement functions.
France
Commercial real estate investment trusts in Île-de-France face binding CSRD disclosure requirements driving sub-circuit metering specifications. The EU AI Act's risk classification protocols apply to autonomous building control algorithms, reshaping vendor competitive dynamics. Schneider Electric SE competes through specialized edge-computing controllers anchoring its position in French commercial retrofits.
Poland
Warsaw and Krakow office construction booms create first-mover advantages for BEMS vendors establishing localized service partnerships. National transpositions of the Energy Performance of Buildings Directive mandate smart metering infrastructure in large commercial structures. Polish facility managers prioritize cloud-native architectures to eliminate on-site server maintenance burdens across new commercial developments.
Denmark
Copenhagen's Nordic office portfolios unbundle energy optimization from traditional hard services through outsourced facility management contracts. The EU Green Deal efficiency targets compress deployment timelines for networked energy platforms across Danish commercial real estate. Danish property investors procure BEMS analytics as standalone performance-guaranteed subscriptions, concentrating vendor selection authority with centralized procurement functions.
European Building Energy Management Systems Market Competitive Landscape
Global majors compete with regional champions across integrated platform delivery and specialized controller manufacturing. The vendor base spans diversified industrial conglomerates with building automation heritage alongside focused specialists in edge-computing and thermal management. Three strategic archetypes dominate: integrated hardware-software bundlers, edge-computing controller specialists, and cloud-native analytics pure-plays. Competitive moves concentrate on strategic partnerships for localized service deployment and portfolio diversification into adjacent building automation segments.
Among diversified industrial conglomerates, Johnson Controls International Plc and Siemens AG exemplify integrated platform providers with established building automation heritage. Schneider Electric SE occupies a position within the edge-computing specialist tier, competing through localized controller manufacturing. Rockwell Automation represents the industrial automation crossover archetype, leveraging process control expertise to anchor positions in manufacturing facility deployments. These three companies illustrate how vendor selection authority concentrates with procurement functions seeking documented algorithmic governance frameworks under emerging EU AI Act compliance categories.
| Leading Market Players |
|---|
| Johnson Controls International Plc |
| Rockwell Automation |
| Siemens AG |
| Priva Holding BV |
| Kieback&Peter GmbH & Co. KG |
| Schneider Electric SE |
| ABB Ltd |
| Bosch |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
Centralized procurement functions at Dutch and Danish property investment trusts anchor pricing power for BEMS vendors, compressing margins through performance-guaranteed subscription structures that displace perpetual licensing models.
Pricing Analysis
Input-cost pass-through from wireless sensor commoditization intensifies margin pressure across hardware tiers. Three-tier pricing structure across premium, standard, and economy levels separates Siemens AG's integrated bundles from Schneider Electric SE's edge controllers and Asian sensor imports. Pricing pressure stems from Chinese manufacturers flooding European markets with low-cost BACnet-compatible devices. Mid-sized facility operators exhibit highest price sensitivity due to capital constraints, while industrial complexes in Germany absorb premium tiers for AI-driven predictive control.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for controller hardware across Northern Europe. Manufacturing concentrates in Germany, France, and China for edge-computing devices, with sensor assembly drawing from Taiwanese and South Korean component suppliers. Raw material dependencies span semiconductor wafers, rare earth magnets for actuators, and copper for HVAC integration. Single-source vulnerability in AI chip supply from NVIDIA and Intel creates procurement risk for autonomous control platforms. Distribution runs through authorized system integrators and direct OEM channels to large facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European BEMS market functions as a stable compounder, with EU Green Deal enforcement providing predictable regulatory tailwinds that sustain deployment velocity across member states.
For Market Incumbents: Lock in service partnerships with municipal retrofit programs in Amsterdam and Rotterdam to defend against cloud-native analytics pure-plays. Deepen backward integration into edge-computing controller manufacturing to capture margin pools escaping to Asian sensor suppliers. Prioritize algorithmic governance documentation to secure procurement preference under EU AI Act risk classification protocols. For New Entrants and Emerging Players: Cloud-native SaaS platforms offer the lowest customer acquisition cost route into Polish commercial real estate, where Warsaw and Krakow construction booms outpace established vendor coverage. Target mid-sized Dutch property investors with standalone performance-guaranteed subscriptions that bypass incumbent hardware bundling. Emphasize CSRD compliance automation to differentiate against legacy metering infrastructure. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking edge-computing capabilities to complement process control portfolios. Five-to-ten year viability rests on AI-enabled predictive maintenance expansion beyond HVAC into full building automation. Acquisition target archetype: regional specialists with documented EU AI Act compliance frameworks and municipal service contracts. Watch for F-Gas Regulation enforcement intensity as inflection indicator for HVAC-linked BEMS retrofit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combining digital twin capabilities with legacy BACnet infrastructure reduces commissioning cycles for German industrial retrofits. |
| Strategic Partnership | Collaborations with Amsterdam municipal authorities secure preferred vendor status for district heating network deployments. |
| Acquisition of Specialist Firm | Purchasing edge-computing controller manufacturers addresses AI Act algorithmic governance requirements for French commercial real estate. |
| Geographic Expansion | Establishing Polish service partnerships captures first-mover advantages in Warsaw and Krakow office construction booms. |
| Product Launch | Introducing CSRD-automated reporting modules meets French REIT audit-ready data requirements from fiscal year 2025. |
Research Methodology
Coverage spans Western Europe, Eastern Europe, and Nordic markets, with primary inputs from each. The research combines interviews with facility management directors, energy procurement officers, building automation engineers, and municipal retrofit program managers with secondary validation. Sources include EPBD national transposition documents, ECHA F-Gas Regulation filings, CSRD implementation guidance, and EU AI Act risk classification protocols. Bottom-up deployment tracking and top-down regulatory impact assessment enable triangulation across market sizing.
Rate-of-change decomposition separates volume expansion from value migration across software, hardware, and services segments over the projection horizon. Segmentation dimensions modeled include deployment architecture, end-use regulatory exposure, technology stack, and facility ownership structure. CAGRs derive from installed base evolution, replacement cycles, and new construction penetration. Forecast inputs incorporate EU Green Deal building renovation targets and CSRD disclosure timeline enforcement.
The model assumes a particular technology adoption path; alternative pathways for autonomous AI control would alter the outlook. Forecasts reflect assumptions around regulatory enforcement consistency, sensor cost trajectories, and cloud migration willingness among conservative facility operators. Cybersecurity certification delays, legacy integration cost overruns, or AI Act compliance burden revisions could materially revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Energy Security Market
Energy Management
Microgrid Control System Market
Energy Management
Energy Harvesting System Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Global Utility Asset Management Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Energy ESO Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Connected Energy Market
Energy Management
Germany Demand Response Management Systems Market