
 Industrial Energy Management System Market | 2026-2036
Industrial Energy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Energy Management System Market Outlook
Energy-intensive process manufacturers is reorganizing procurement priorities around real-time optimization platforms. Schneider Electric SE leverages its EcoStruxure architecture to anchor European heavy industry deployments. Siemens AG competes through its MindSphere ecosystem, sustaining deep integration with German automotive and chemical plant automation stacks. Honeywell International Inc differentiates via Forge platform specialization in refining and petrochemical verticals where thermal efficiency commands premium pricing.
An industrial energy management system comprises sensor networks, control hardware, analytics software, and cloud infrastructure that monitor, analyze, and optimize energy consumption across production facilities, typically integrating SCADA protocols with machine learning algorithms to reduce kilowatt-hour intensity per unit output. The hardware layer remains the largest revenue pool due to capital-intensive retrofit cycles in legacy plants, though cloud solutions represent the fastest-expanding segment as multi-site operators abandon on-premise server maintenance. Software anchored by AI and big data analytics captures disproportionate margin pools because subscription pricing models generate recurring revenue streams that hardware transactions cannot replicate.
The EPA enforces mandatory energy reporting for large U.S. industrial facilities under its Energy Star and GHGRP frameworks, while the EU Green Deal and REACH compliance timelines force European manufacturers to document Scope 1 and 2 emissions reductions or face carbon border adjustment penalties. China's MEE implements dual carbon goals through provincial emissions intensity targets that directly shape industrial procurement specifications. Stakeholders must decide whether to build in-house platform capabilities or partner with established vendors before regulatory disclosure requirements harden into technical standards that lock out non-compliant suppliers.
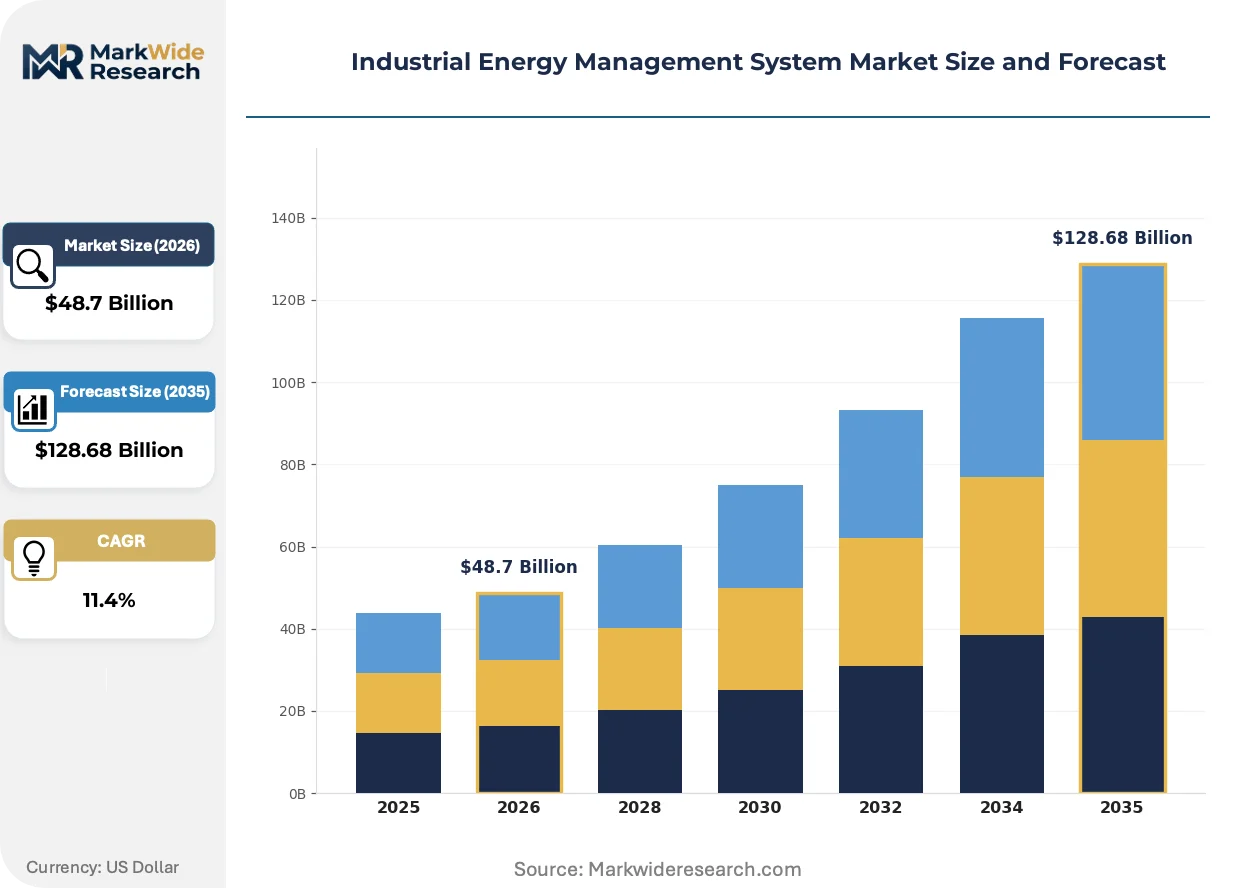
Market Dynamics
Carbon border adjustment mechanisms are forcing heavy manufacturers to install real-time emissions tracking infrastructure ahead of trade compliance deadlines. The EU Green Deal and China's dual carbon goals have synchronized procurement cycles across steel, cement, and chemical sectors toward integrated energy platforms.
Growth Catalysts
- EU F-Gas Regulation:Industrial refrigeration and cooling systems in Germany's chemical corridor face mandatory leakage monitoring, accelerating sensor network deployments.
- Steel decarbonization:Electric arc furnace operators in China's Jiangsu province require granular energy accounting to qualify for green steel export certifications.
- Digital twin convergence:Process simulation software now feeds directly into energy optimization algorithms, compressing payback periods for integrated platform investments.
Market Restraints
- Copper and rare earth price volatility:Sensor hardware and power electronics face input cost swings that destabilize project economics for brownfield retrofits.
- Legacy protocol fragmentation:Proprietary SCADA systems from 1990s-era installations resist seamless integration with cloud-native analytics layers.
- Substitution by on-site generation:Captive solar and battery microgrids in India's textile belt are diverting capital from demand-side management platforms.
Strategic Opportunities
- Small and mid-sized process manufacturers:Tier-two chemical and food processing plants in Brazil's São Paulo industrial zone remain unserved by enterprise-grade platforms.
- EU CSRD disclosure mandates:Scope 3 emissions tracking requirements are creating demand for supply chain energy visibility tools beyond facility boundaries.
- Edge-to-cloud architecture:Hybrid processing models combining on-premise inference with centralized analytics are opening mid-market segments previously priced out of full cloud deployments.
Industry Challenges
- OT-IT cybersecurity certification:IEC 62443 compliance timelines for industrial control systems are extending procurement cycles by six to twelve months.
- Interoperability engineering talent:Specialists capable of bridging legacy Modbus and modern MQTT protocols command premium compensation that strains system integrator margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Energy Management System Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Cloud Solutions Application: Manufacturing, Warehousing, Transportation, Utilities End User: Manufacturers, Energy Providers, Logistics Companies, Facility Managers Technology: IoT, AI, Big Data, Renewable Energy Integration |
| Companies Covered | Schneider Electric SE, Siemens AG, Honeywell International Inc, ABB Ltd, Johnson Controls International Plc, Emerson Electric Co, General Electric, Eaton Corporation PLC, Cisco Systems Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Energy Management System Market Strategic Shifts
Energy management architectures are pivoting from reactive monitoring toward predictive optimization driven by machine learning inference at the network edge. This shift is compressing hardware refresh cycles while elevating software subscription revenues.
Edge-deployed AI inference engines are supplanting centralized cloud analytics for latency-critical load balancing decisions. Steel mills and aluminum smelters in Germany's Ruhr region are deploying these systems to manage furnace cycling against real-time electricity pricing. The technology is compressing response times from minutes to milliseconds, enabling participation in ancillary services markets previously inaccessible to industrial loads.
The EU F-Gas Regulation and accompanying carbon border adjustment mechanism are mandating documented refrigerant leakage rates and embodied carbon calculations for imported industrial goods. Chemical and pharmaceutical manufacturers in the Netherlands and Belgium are retrofitting cold chain infrastructure with continuous monitoring systems to maintain export eligibility. The regulation is accelerating consolidation around integrated platforms that combine energy and emissions data into unified audit trails.
Buyers are unbundling long-term service contracts from initial platform procurement, opting instead for modular subscription tiers tied to verified savings outcomes. This pattern is most visible among multi-site food and beverage operators in the United States, where procurement teams now separate hardware acquisition from analytics licensing and ongoing optimization support. The shift is pressuring incumbent vendors to restructure pricing architectures and expand partner ecosystems for implementation services.
Industrial Energy Management System Market Segmentation
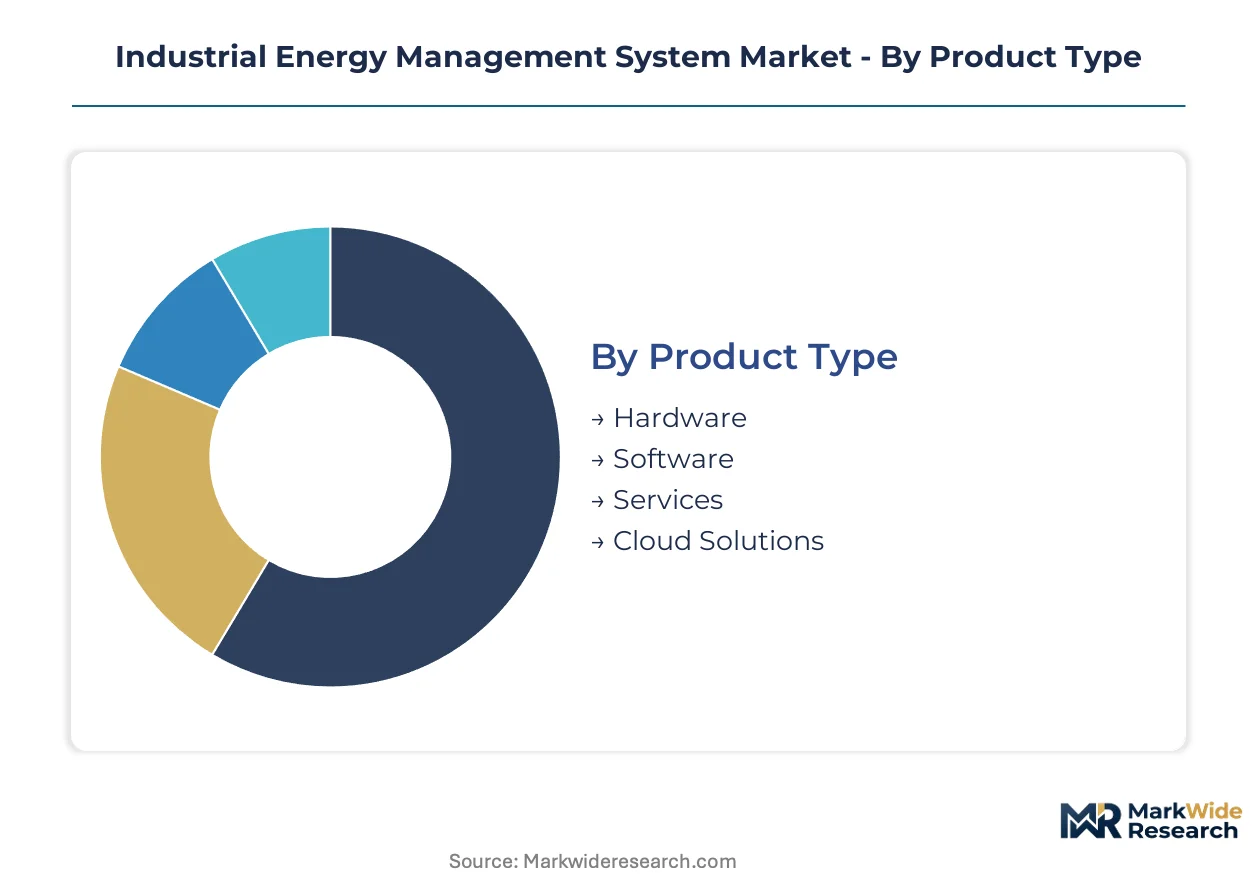
Industrial energy management platforms fragment across four distinct dimensions that determine procurement priorities and vendor positioning. Product type dictates capital intensity and margin structure, while application context shapes integration complexity and payback expectations. Technology choices increasingly determine competitive differentiation as edge computing displaces centralized architectures.
Product Type:
Cloud solutions and services face the strongest substitution pressure from captive microgrids and on-site generation investments that divert capital from demand-side platforms.
- Hardware:Sensor networks, control systems, and power electronics constitute the foundational infrastructure layer requiring physical retrofit of legacy plants. Demand concentrates in Germany's Ruhr industrial corridor where brownfield steel and chemical facilities face EU Green Deal compliance deadlines. Copper price volatility destabilizes project economics for multi-site rollouts.
- Software:Analytics platforms anchored by AI and machine learning algorithms capture disproportionate margins through subscription pricing models that hardware transactions cannot replicate. China's Yangtze River Delta manufacturing belt drives procurement as provincial emissions intensity targets harden into technical specifications.
- Services:Implementation, integration, and ongoing optimization support delivered through system integrator networks. Brazil's São Paulo industrial zone shows concentrated demand as tier-two manufacturers seek outcome-based contracting structures.
- Cloud Solutions:Centralized infrastructure for multi-site data aggregation and predictive analytics. India's textile belt exhibits substitution effects as captive solar and battery microgrids divert capital from demand-side management investments.
Hardware retains volume leadership; cloud solutions hold the steepest expansion curve.
Application:
Cost tier differentiation separates mission-critical process manufacturing from lower-intensity facility types where payback thresholds stretch deployment timelines.
- Manufacturing:Energy-intensive process industries including steel, cement, chemicals, and automotive assembly where kilowatt-hour intensity per unit output determines competitive positioning. Germany's automotive and chemical plant automation stacks sustain deep integration requirements.
- Warehousing:Cold chain infrastructure and distribution centers facing EU F-Gas Regulation mandates for refrigerant leakage monitoring. Netherlands and Belgium pharmaceutical manufacturers retrofit continuous monitoring systems to maintain export eligibility.
- Transportation:Fleet electrification depots and rail yard energy optimization where load balancing against real-time electricity pricing creates ancillary services revenue opportunities.
- Utilities:Grid-interactive industrial loads participating in demand response programs with millisecond-latency requirements enabled by edge-deployed AI inference engines.
Manufacturing dominates current procurement volumes; warehousing is expanding most quickly as cold chain regulations tighten.
End User:
Customer type determines platform complexity requirements and contracting sophistication, with energy providers commanding the most advanced integration specifications.
- Manufacturers:Heavy process industries and discrete assembly operations prioritizing Scope 1 and 2 emissions reductions for carbon border adjustment compliance. China's Jiangsu province electric arc furnace operators require granular energy accounting for green steel export certifications.
- Energy Providers:Utility and independent power producer customers seeking grid-interactive load management and virtual power plant aggregation capabilities.
- Logistics Companies:Multi-site warehouse and fleet operators unbundling long-term service contracts from initial platform procurement in favor of modular subscription tiers tied to verified savings outcomes.
- Facility Managers:Commercial and institutional building operators with lower technical sophistication driving demand for edge-to-cloud hybrid architectures that reduce upfront investment barriers.
Manufacturers retain volume leadership; energy providers hold the steepest expansion curve.
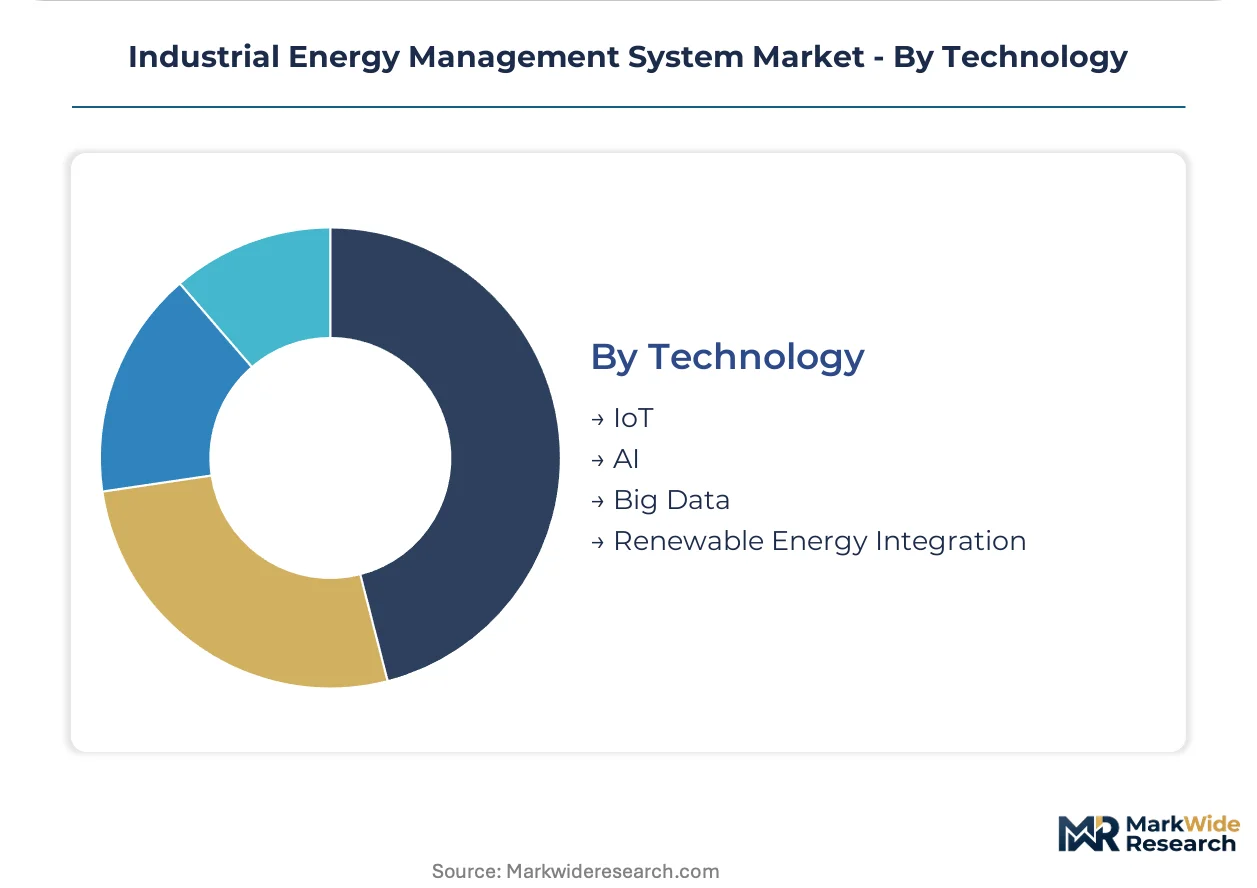
Technology:
Maturity gradients separate established connectivity protocols from emerging inference architectures that compress response times for latency-critical applications.
- IoT:Sensor networks and edge devices transmitting operational data through MQTT and legacy Modbus protocols. Germany's Ruhr region steel mills deploy these systems for furnace cycling optimization against real-time electricity pricing.
- AI:Machine learning inference engines for predictive optimization and automated load balancing. Edge deployment patterns are displacing centralized cloud analytics for applications requiring millisecond response times.
- Big Data:Historical consumption pattern analysis and benchmarking across multi-site portfolios. United States food and beverage operators leverage these capabilities for outcome-based contracting structures.
- Renewable Energy Integration:Solar, wind, and battery microgrid coordination with demand-side management platforms. Substitution effects from on-site generation divert capital in India's textile belt and other markets with high renewable resource availability.
IoT retains volume leadership; AI holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor underwrites Germany's central role in European industrial energy platform deployment. China's ultra-high-voltage grid interconnects power the Yangtze River Delta manufacturing belt. The US Gulf Coast petrochemical pipeline network anchors North American demand for thermal optimization systems.
Germany
Ruhr industrial corridor steel mills and chemical complexes drive hardware retrofit demand ahead of EU Green Deal deadlines. The F-Gas Regulation mandates refrigerant leakage monitoring for cold chain infrastructure. North Rhine-Westphalia's brownfield facilities concentrate procurement of edge-deployed AI systems for furnace cycling optimization.
China
Jiangsu province electric arc furnace operators require granular energy accounting for green steel export certifications. The MEE implements dual carbon goals through provincial emissions intensity targets that shape technical procurement specifications. The Yangtze River Delta manufacturing belt leads cloud solution adoption as multi-site operators abandon on-premise server maintenance.
United States
Gulf Coast refining and petrochemical complexes sustain demand for thermal efficiency platforms where kilowatt-hour intensity determines competitive positioning. EPA Energy Star and GHGRP frameworks enforce mandatory energy reporting for large industrial facilities. Texas and Louisiana process plants concentrate procurement of integrated platforms combining sensor networks with machine learning analytics.
India
Gujarat and Maharashtra textile belt manufacturers face substitution pressure as captive solar and battery microgrids divert capital from demand-side management investments. The Bureau of Energy Efficiency mandates consumption audits for designated consumers above threshold capacity. Tamil Nadu's automotive component clusters show emerging demand for edge-to-cloud hybrid architectures reducing upfront investment barriers.
Netherlands
Rotterdam port industrial complexes and pharmaceutical cold chain infrastructure face EU F-Gas Regulation compliance requirements. The CSRD disclosure mandates create demand for supply chain energy visibility tools beyond facility boundaries. Eindhoven region chemical and pharmaceutical manufacturers retrofit continuous monitoring systems to maintain export eligibility under carbon border adjustment mechanisms.
Industrial Energy Management System Market Competitive Environment
Listed leaders compete with private specialists across platform architecture and vertical integration depth. The vendor base clusters around three tiers: diversified industrial conglomerates with automation heritage, pure-play software vendors with cloud-native stacks, and regional system integrators with legacy protocol expertise. Strategic moves concentrate on M&A for AI capability acquisition and partnership structures for mid-market channel expansion.
Within the diversified industrial tier, Schneider Electric SE and Siemens AG exemplify European automation heritage positioning. Honeywell International Inc anchors North American presence in refining and petrochemical verticals. These three occupy positions reflecting distinct geographic and sectoral specialization patterns rather than direct product competition.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| Honeywell International Inc |
| ABB Ltd |
| Johnson Controls International Plc |
| Emerson Electric Co |
| General Electric |
| Eaton Corporation PLC |
| Cisco Systems Inc |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week sensor lead times from Southeast Asian contract manufacturers concentrate pricing power among integrated platform vendors with captive component inventories. Hardware procurement teams in Germany's Ruhr corridor absorb premium markups for expedited delivery against EU Green Deal compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-site deployments from mid-market single-facility installations. Three-tier pricing stratifies across premium certified integration, standard configurable packages, and economy sensor-only bundles. Cost compression in the economy tier intensifies because copper price volatility destabilizes brownfield retrofit project economics. Mid-sized process manufacturers in Brazil's São Paulo zone exhibit the highest price sensitivity, while energy providers with grid-interactive load specifications command the least.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose rare earth magnet shipments from China to logistics disruption risks. Sensor hardware production concentrates in China, South Korea, and Taiwan, drawing from copper cathode, silicon wafer, and neodymium magnet feedstocks. Single-source vulnerability in AI accelerator chip supply strains system integrator margins. Distribution runs through authorized system integrator networks rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
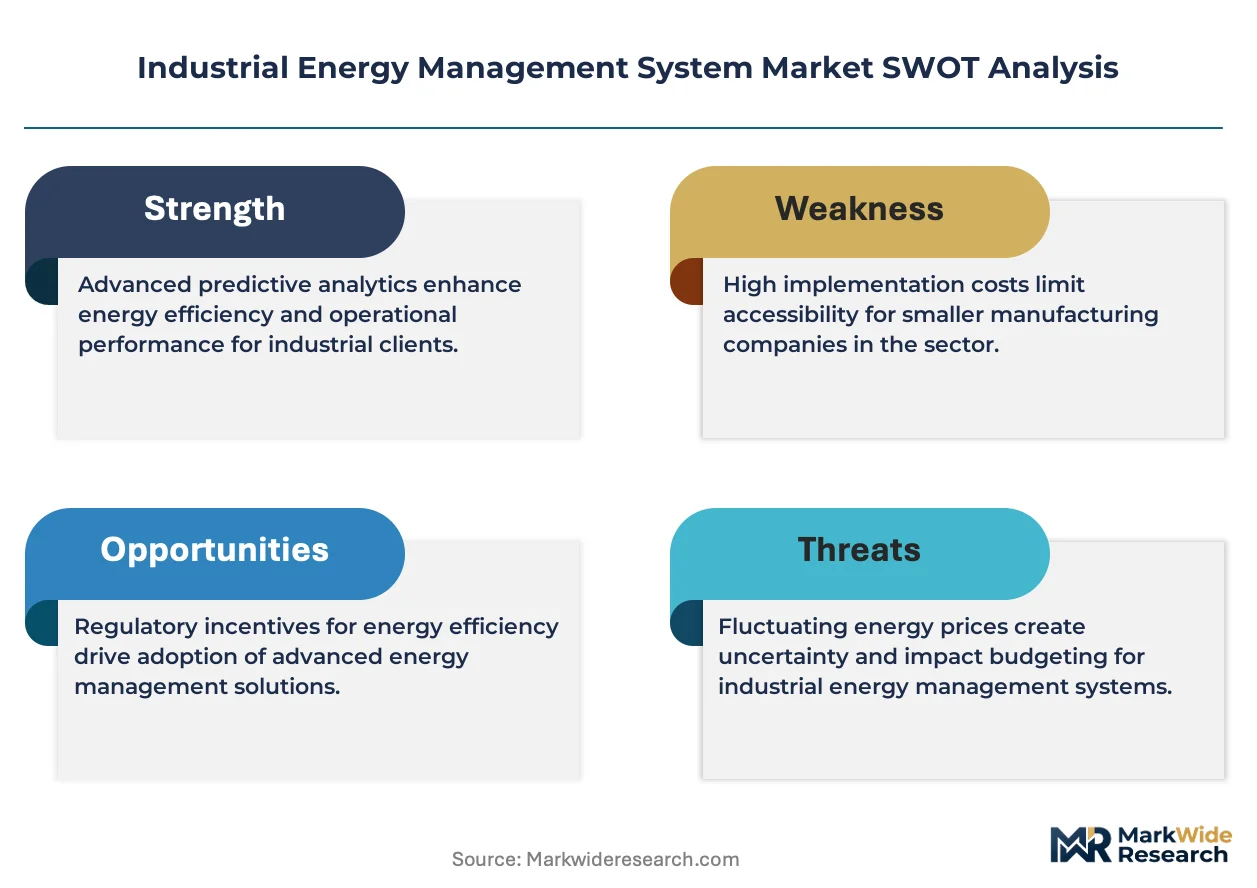
Analyst Recommendations
Industrial energy platform procurement is recovering from cyclical capital expenditure compression driven by steel and cement sector margin troughs.
For Market Incumbents: Compound platform stickiness through deeper embedded AI capability and outcome-based contracting structures. Defend against pure-play software entrants by securing IEC 62443 cybersecurity certification ahead of compliance hardening. Prioritize backward integration into edge hardware production to stabilize sensor cost exposure. For New Entrants and Emerging Players: Differentiate on rapid deployment architectures for tier-two food and chemical processors in underpenetrated Brazilian and Indian industrial zones. Target São Paulo and Gujarat manufacturing belts with edge-to-cloud hybrid offerings that reduce upfront investment barriers. Pursue system integrator partnership channels rather than direct enterprise sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core energy software divisions. Long-term viability hinges on recurring revenue share expansion versus hardware transaction dependency. Watch for inflection signals in carbon border adjustment mechanism enforcement timelines that synchronize procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified audit trails combining energy and emissions data satisfy EU F-Gas Regulation documentation requirements. |
| Acquisition of Specialist Firm | AI inference engine specialists compress response times for steel mill furnace cycling optimization. |
| Strategic Partnership | System integrator alliances extend reach into Brazil's tier-two chemical processing mid-market. |
| Geographic Expansion | Yangtze River Delta cloud infrastructure investments capture multi-site operator server abandonment. |
| Product Launch | Edge-deployed inference engines enable millisecond-latency ancillary services participation for aluminum smelters. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers, energy procurement directors, system integrator technical leads, and regulatory compliance officers and refined through secondary validation against SEC 10-K filings, EPA Energy Star databases, EU ETS transaction registries, and customs import records. Bottom-up facility deployment estimates were triangulated with top-down vendor revenue aggregation.
Variance-decomposition across product type, application vertical, end-user sophistication tier, and technology maturity gradient shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Edge computing adoption curves and carbon border adjustment mechanism implementation timelines served as industry-specific forecast inputs across the projection horizon.
Decision-makers should treat outputs as directional under stable copper pricing and regulatory enforcement continuity assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as dual carbon goal provincial allocation methodologies and F-Gas Regulation leakage threshold revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Connected Energy Market
Energy Management
Heat Meter Market
Energy Management
Smart Power Management Market
Energy Management
Europe Exhaust Heat Recovery System Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Energy ESO Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Demand Response Management System Market
Energy Management
Power SCADA Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Thermostat Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Germany Demand Response Management Systems Market