
 Solar Panel Monitoring System Market | 2026-2036
Solar Panel Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Monitoring System Market Analytics
The EU Green Deal is realigning procurement criteria for solar asset operators across European member states. Nextracker leverages its tracker-integrated electronics portfolio to capture utility-scale monitoring contracts in high-irradiance markets. Array Technologies anchors its competitive position through domestic manufacturing scale and North American supply chain density. Soltec specializes in bifacial-optimized monitoring algorithms that differentiate its offering in Latin American and Southern European deployments.
A solar panel monitoring system comprises sensor arrays, data loggers, and communication gateways that measure photovoltaic module voltage, current, temperature, and irradiance in real time, transmitting performance telemetry to centralized or edge-computing platforms for fault detection and yield optimization. These systems serve commercial and industrial asset managers seeking to minimize downtime and maximize power purchase agreement compliance. The technology dimension shows IoT-enabled architectures leading current deployments while cloud-based platforms represent the fastest-expanding segment due to lower capital intensity and remote accessibility. Within end-user categories, industrial and commercial installations command the deepest margin pools because operational scale justifies advanced predictive analytics subscriptions.
The Federal Energy Regulatory Commission in the United States mandates interconnection standards that implicitly require grid-visible generation telemetry, while the EU AI Act imposes algorithmic transparency requirements on automated fault-diagnosis systems deployed across European solar portfolios. India's Central Electricity Authority enforces renewable energy forecasting regulations that drive adoption of granular monitoring infrastructure. Stakeholders must evaluate how evolving cybersecurity standards for critical energy infrastructure will reshape hardware authentication and data-encryption specifications in procurement decisions.
Market Dynamics
Real-time performance telemetry mandates from grid operators and renewable portfolio standards are forcing asset owners to upgrade from basic fault detection to predictive analytics platforms. This regulatory compression is restructuring vendor competition around cloud-native architectures and edge-computing capabilities.
Growth Catalysts
- EU Green Deal sustainability reporting:Embedded disclosure requirements accelerate procurement of granular generation data infrastructure across European solar portfolios.
- Utility-scale solar developers:North American project sponsors are expanding contracts for tracker-integrated electronics that synchronize monitoring with automated solar tracking.
- India's renewable energy forecasting regulations:The Central Electricity Authority mandates granular monitoring infrastructure for grid stability, driving distributed generation compliance spending.
Market Restraints
- Silicon sensor cost volatility:Input price swings for photovoltaic-grade sensing components compress hardware margins and deter long-term procurement commitments.
- Supply concentration in East Asian electronics:Data logger and gateway manufacturing clusters create single-source vulnerability for non-integrated vendors.
- Cybersecurity certification delays:Evolving IEC 62443 standards for critical energy infrastructure extend hardware authentication timelines and freeze procurement cycles.
Strategic Opportunities
- Brazilian distributed generation expansion:Underpenetrated commercial rooftop markets offer white space for bifacial-optimized monitoring algorithms in high-irradiance zones.
- EU AI Act algorithmic transparency:Automated fault-diagnosis mandates create regulatory tailwind for explainable AI platforms in European solar asset management.
- Edge-to-cloud architecture convergence:Hybrid computing models enable real-time anomaly detection without full bandwidth dependency, opening rural and off-grid deployments.
Industry Challenges
- Embedded systems engineering scarcity:Shortage of firmware developers with photovoltaic domain expertise delays product roadmaps and integration timelines.
- Legacy SCADA protocol fragmentation:Incompatible communication standards across installed bases force costly middleware development and customer-specific customization.
- Multi-jurisdiction certification stacking:Separate cybersecurity, electrical safety, and environmental approvals for cross-border projects extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Monitoring System Market |
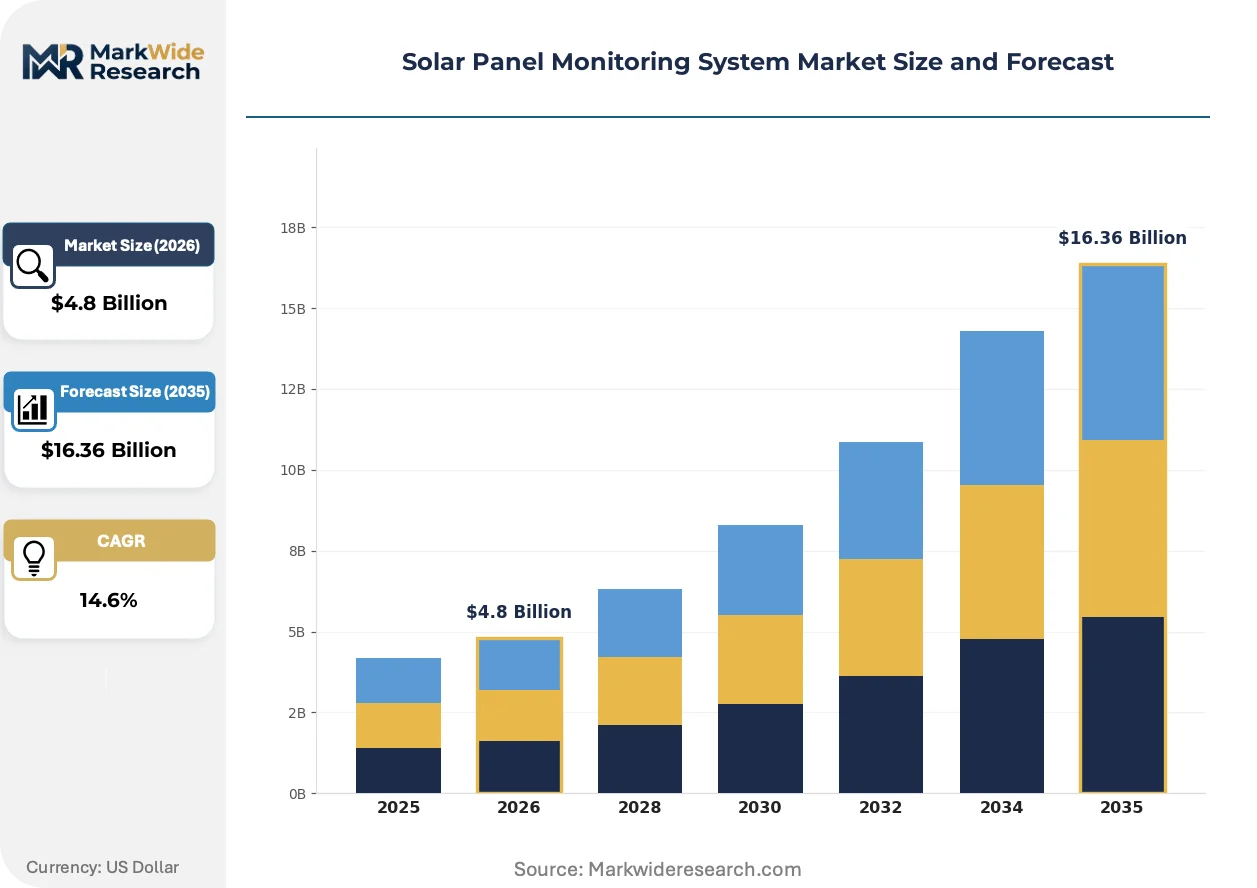
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized, Distributed, Hybrid, Standalone Technology: IoT, Cloud-based, Software, Data Analytics End User: Residential, Commercial, Industrial, Government Installation Type: Rooftop, Ground-mounted, Building-integrated, Portable |
| Companies Covered | Arctech Solar, FTC Solar, Nextracker, Ideematec, Soltec, Array Technologies, Trina Tracker, PV Hardware, GameChange Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Monitoring System Market Evolving Landscape
Digital twin architectures and machine learning inference at the edge are compressing fault-response cycles from hours to seconds. Vendors are racing to embed predictive capabilities directly into field hardware rather than centralized servers.
Machine learning inference engines are migrating from cloud servers to gateway devices positioned at solar array substations. Large utility-scale operators in Germany and the southwestern United States are piloting these architectures to reduce latency in soiling detection and inverter fault isolation. This edge intelligence is converging with low-earth-orbit satellite backhaul to enable monitoring in remote installations lacking terrestrial connectivity.
The EU AI Act imposes explainability requirements on automated diagnostic systems deployed across member state solar portfolios. Asset managers must now document algorithmic decision pathways for fault classification and energy yield forecasting. European commercial and industrial installations face the steepest compliance burden, driving substitution toward vendors with transparent model architectures.
Power purchase agreement sponsors are unbundling monitoring subscriptions from hardware procurement, treating analytics as separate operating expenditure line items. This shift compresses vendor switching costs and elevates software renewal rates as the primary revenue anchor. The pattern is most pronounced in California and Texas, where independent power producers rotate between specialized monitoring providers across project refinancing cycles.
Solar Panel Monitoring System Market Segmentation
Solar panel monitoring system procurement varies sharply by deployment scale and regulatory exposure. Asset managers select architectures based on grid interconnection mandates, cybersecurity certification requirements, and the granularity of yield optimization needed for power purchase agreement compliance.
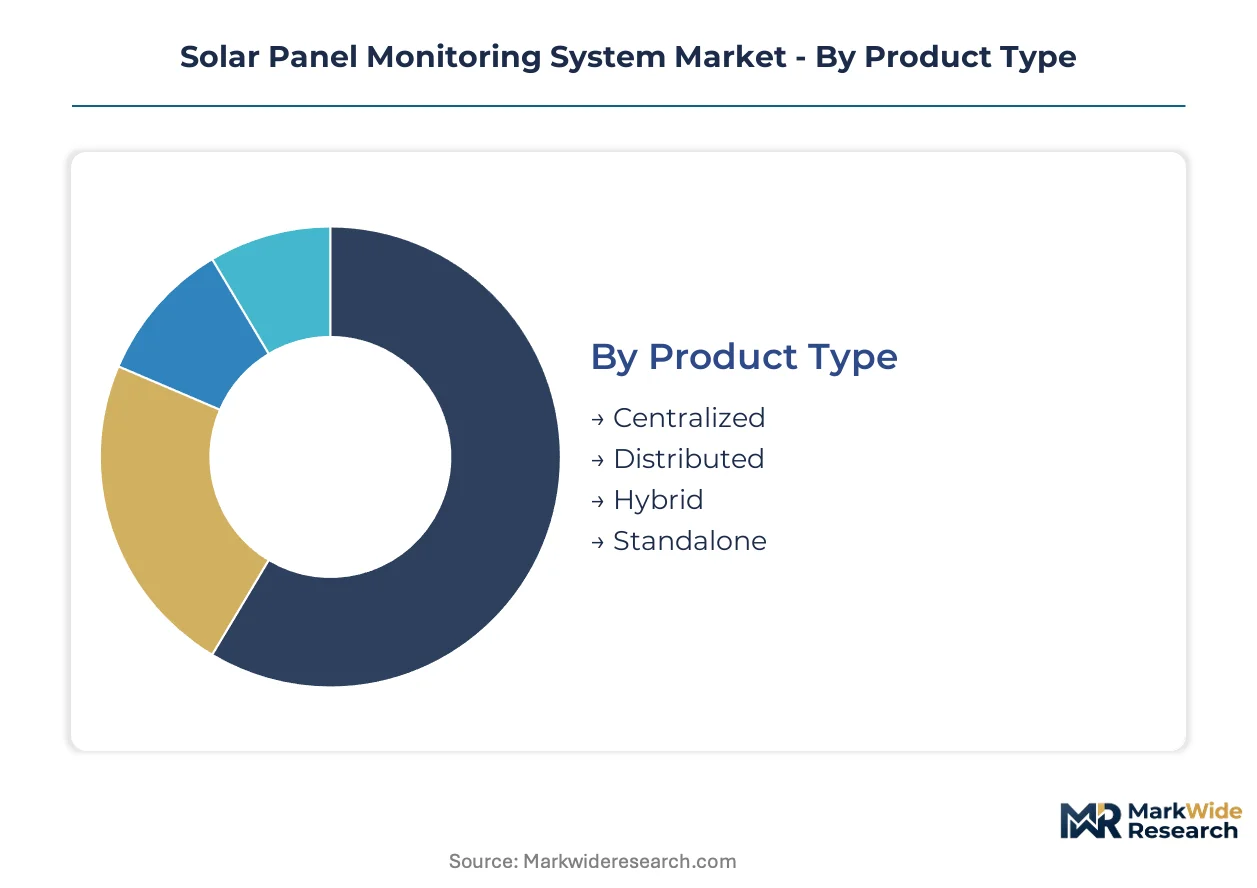
Product Type:
IEC 62443 cybersecurity certification applies differentially across product architectures, with centralized systems facing the heaviest compliance burden and standalone units navigating lighter approval pathways.
- Centralized:Hub-and-spoke architectures aggregate telemetry from multiple arrays through single data loggers. German utility-scale developers favor these systems for their compatibility with grid operator SCADA integration mandates and centralized fault diagnosis capabilities.
- Distributed:Edge-computing nodes process performance data locally at individual string or module level. India's commercial rooftop sector drives concentrated demand here, as CEA renewable energy forecasting regulations require granular generation visibility without single points of failure.
- Hybrid:Combines local processing with cloud synchronization for resilience. Brazil's distributed generation expansion favors this architecture for intermittent connectivity environments.
- Standalone:Self-contained units operating without network dependency. Remote off-grid installations in Australia and Saudi Arabia deploy these where terrestrial backhaul is unavailable.
Centralized systems sit at the top of the volume ranking, with distributed architectures climbing the fastest as grid operators mandate module-level visibility.
Technology:
Technology selection tracks operational expenditure preferences, with capital-intensive hardware deployments giving way to subscription-based analytics platforms among independent power producers.
- IoT:Sensor networks with embedded connectivity modules transmit real-time voltage, current, and temperature telemetry. Southwestern United States utility-scale operators deploy these extensively for soiling detection and automated cleaning trigger integration.
- Cloud-based:Remote server architectures eliminate on-premise infrastructure and enable portfolio-wide analytics dashboards. European commercial and industrial asset managers accelerate procurement here to meet EU Green Deal sustainability reporting timelines.
- Software:Licensed platforms for data visualization and performance benchmarking. Texas independent power producers treat these as separate operating expenditure line items during project refinancing cycles.
- Data Analytics:Machine learning inference engines for predictive maintenance and yield forecasting. Germany leads deployment as EU AI Act explainability requirements reshape vendor selection toward transparent model architectures.
IoT-enabled systems command the largest installed base, while cloud-based platforms gain share fastest among new procurement.
End User:
End-user categories separate by margin pool depth and analytics sophistication, with industrial operators justifying premium predictive subscriptions that residential deployments cannot support.
- Industrial:Large-scale manufacturing facilities and data centers with captive solar generation. These operators in India and the United States purchase advanced fault-diagnosis subscriptions to minimize downtime and maximize power purchase agreement compliance.
- Commercial:Office buildings, retail centers, and logistics facilities with rooftop or carport installations. California's commercial sector drives concentrated demand for unbundled monitoring subscriptions treated as operating expenditure.
- Residential:Single-family homes and small multi-unit dwellings with behind-the-meter solar. Simpler fault-alert systems dominate here due to price sensitivity and limited technical staffing.
- Government:Municipal buildings, military installations, and public infrastructure with resilience mandates. Federal procurement in the United States emphasizes FERC interconnection standards compliance and domestic supply chain requirements.
Industrial end users anchor revenue concentration, with commercial installations expanding most quickly as financing structures evolve.
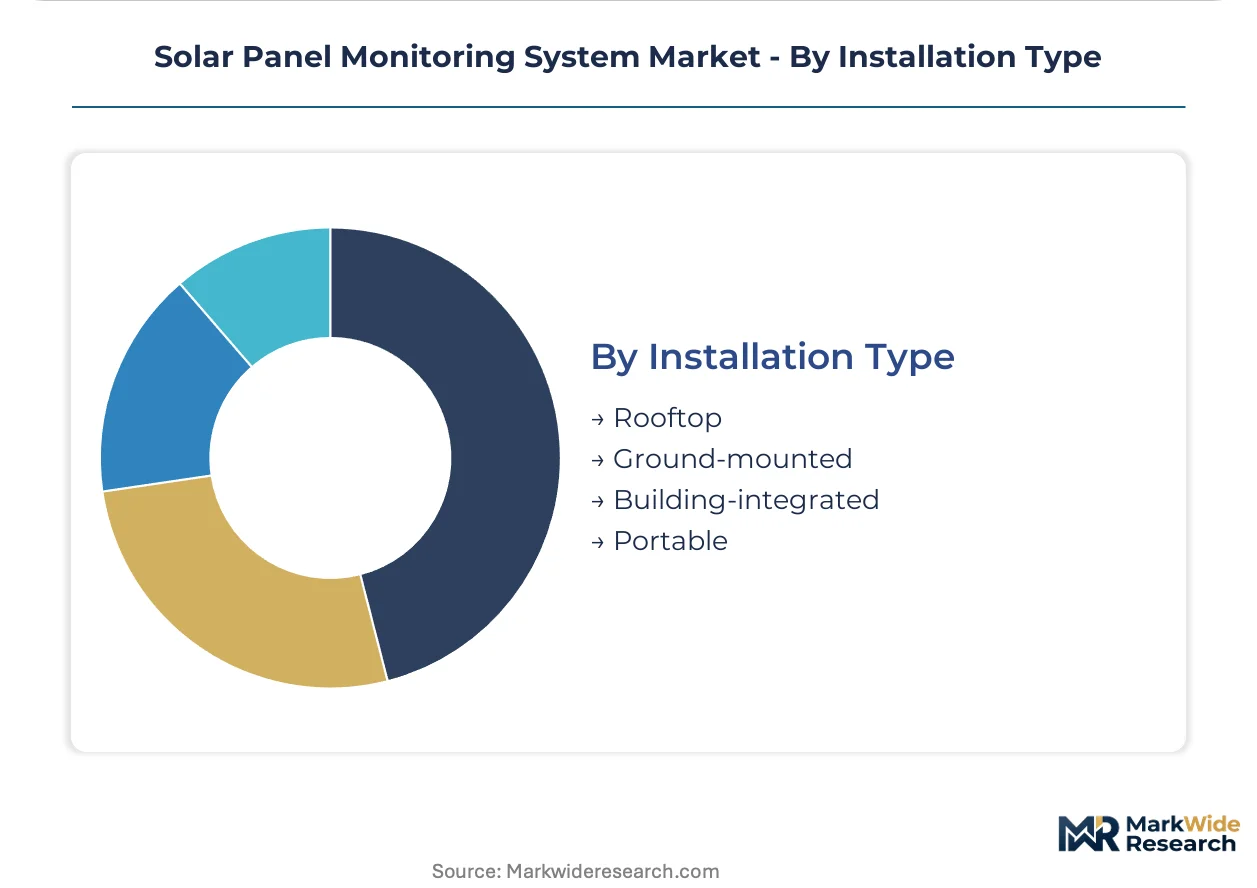
Installation Type:
Physical mounting configuration determines sensor placement, communication gateway positioning, and exposure to environmental stressors that shape hardware specification.
- Rooftop:Elevated arrays on commercial and residential structures with constrained access for maintenance. Brazil's distributed generation expansion targets this segment with bifacial-optimized monitoring algorithms for high-irradiance commercial zones.
- Ground-mounted:Utility-scale arrays on dedicated land with tracker integration potential. Nextracker and Array Technologies compete here for contracts synchronizing monitoring with automated solar tracking in the southwestern United States.
- Building-integrated:Photovoltaic elements embedded in facades, skylights, or roofing materials. European mandates for building energy performance drive niche demand with specialized irradiance modeling requirements.
- Portable:Temporary deployments for disaster relief, construction power, or mobile applications. Limited commercial scale but growing interest from humanitarian and defense procurement channels.
Ground-mounted installations dominate capacity deployment, with rooftop systems gaining share fastest under distributed generation incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers with photovoltaic domain expertise concentrate in Germany, India, and the southwestern United States, anchoring development centers for next-generation monitoring architectures. These talent clusters align with jurisdictions enforcing the strictest telemetry mandates for grid-connected solar assets.
United States
Utility-scale developers in Arizona and Texas procure tracker-integrated electronics that synchronize real-time performance data with automated solar tracking. FERC interconnection standards implicitly require grid-visible generation telemetry, compelling asset owners to upgrade from basic fault detection to predictive analytics platforms. Nextracker and Array Technologies anchor manufacturing and R&D operations in the Southwest, capturing contracts from independent power producers refinancing projects across California and Texas.
Germany
Commercial and industrial asset managers accelerate procurement of cloud-native monitoring architectures to meet EU Green Deal sustainability reporting timelines. The EU AI Act imposes algorithmic transparency requirements on automated fault-diagnosis systems, reshaping vendor selection toward explainable AI platforms. Munich and Stuttgart host concentrated development activity for digital twin architectures that compress fault-response cycles from hours to seconds.
India
The Central Electricity Authority enforces renewable energy forecasting regulations that mandate granular monitoring infrastructure for grid stability. Maharashtra and Gujarat drive distributed generation compliance spending, with commercial rooftop operators favoring edge-computing nodes that process performance data locally. Firmware developers with photovoltaic expertise cluster in Bengaluru and Hyderabad, supporting indigenous platform development.
Brazil
Underpenetrated commercial rooftop markets in São Paulo and Minas Gerais offer white space for bifacial-optimized monitoring algorithms in high-irradiance zones. Distributed generation expansion favors hybrid architectures that combine local processing with cloud synchronization for intermittent connectivity environments. ANVISA and national electrical safety regulators impose certification requirements that extend hardware approval timelines.
Australia
Remote off-grid installations in Western Australia and the Northern Territory deploy standalone monitoring units where terrestrial backhaul is unavailable. Low-earth-orbit satellite backhaul convergence enables monitoring in mining and agricultural applications lacking terrestrial connectivity. Perth anchors regional engineering support for edge-intelligence pilot programs.
Solar Panel Monitoring System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the solar panel monitoring system landscape. Integrated tracker manufacturers with captive electronics capabilities face competition from specialized software vendors unbundling analytics subscriptions from hardware procurement. Three archetypes dominate: tracker-integrated electronics suppliers, standalone monitoring platform developers, and hybrid architecture specialists. Consolidation pressure intensifies through strategic partnerships bridging hardware manufacturing with cloud-native software stacks, while geographic expansion into underpenetrated distributed generation markets accelerates.
Within the tracker-integrated tier, Nextracker, Array Technologies, and Soltec exemplify capital-intensive positioning. Nextracker represents the electronics-forward archetype with embedded sensing capabilities. Array Technologies anchors domestic manufacturing scale within North American supply chains. Soltec occupies a specialization position in bifacial-optimized algorithm development. These three firms illustrate how hardware integration depth separates competitive positioning in utility-scale procurement cycles.
| Leading Market Players |
|---|
| Arctech Solar |
| FTC Solar |
| Nextracker |
| Ideematec |
| Soltec |
| Array Technologies |
| Trina Tracker |
| PV Hardware |
| GameChange Solar |
| Others |
Value Network & Pricing Analysis
Photovoltaic-grade silicon wafer spot indices cascade through sensor component costs into three distinct procurement tiers that separate utility-scale bundled contracts from unbundled SaaS subscriptions for commercial operators. Hardware margins compress when East Asian electronics manufacturing clusters face input volatility, while software-heavy pricing models in European markets absorb these shocks through recurring revenue structures.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-intensive hardware procurement from operating expenditure treatment of analytics subscriptions. Three-tier pricing structure across premium, standard, and economy levels tracks IEC 62443 cybersecurity certification grade and volume scale. Pricing pressure stems from silicon sensor cost volatility compressing hardware margins. Residential end users exhibit highest price sensitivity, while industrial asset managers justify premium predictive analytics subscriptions through power purchase agreement compliance value.
Supply Chain Analysis
Reverse-logistics flows for data logger refurbishment and gateway remanufacturing concentrate in Shenzhen, Dongguan, and Taipei electronics corridors. Manufacturing draws from photovoltaic-grade silicon wafers, embedded microcontroller units, and low-earth-orbit satellite communication modules. Single-source vulnerability in East Asian sensor fabrication creates structural risk exposure. Distribution runs through tracker-integrated electronics suppliers and specialized monitoring platform vendors serving distinct deployment scales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as grid interconnection telemetry mandates force recurring upgrade cycles across installed solar capacity. Regulatory compression ensures sustained procurement velocity regardless of headline solar deployment fluctuations.
For Market Incumbents: Anticipate margin erosion from specialized software vendors unbundling analytics subscriptions by deepening backward integration into sensor manufacturing and securing IEC 62443 certification ahead of evolving cybersecurity standards. Prioritize cloud-native architecture investments that accommodate EU AI Act explainability requirements. For New Entrants and Emerging Players: Capture white space in Brazilian commercial rooftop distributed generation and Australian remote off-grid standalone deployments where terrestrial connectivity gaps favor hybrid edge-to-cloud architectures. Enter through bifacial-optimized algorithm specialization or low-earth-orbit satellite backhaul integration partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light software vendors possessing transparent machine learning architectures that satisfy European regulatory requirements. Long-term viability favors platforms demonstrating portfolio-wide analytics retention across project refinancing cycles. Monitor FERC interconnection standard enforcement intensity and EU AI Act implementation timelines as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables EU Green Deal sustainability reporting compliance across member state solar portfolios. |
| Edge Computing Hardware Development | Supports India's CEA renewable energy forecasting regulations through local processing capabilities. |
| Cybersecurity Certification Investment | Accelerates IEC 62443 approval timelines for critical energy infrastructure procurement cycles. |
| Tracker-Electronics Integration | Synchronizes real-time monitoring with automated solar tracking for utility-scale developers. |
| Explainable AI Architecture Deployment | Satisfies EU AI Act algorithmic transparency mandates for automated fault-diagnosis systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators alongside secondary validation through EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation forecasts and top-down regulatory impact assessments triangulated segment-level outputs.
Segment-weighting across product architecture, technology deployment model, end-user operational scale, and installation type dimensions anchored the analytical framework. CAGRs derived from historical procurement velocity and regulatory mandate enforcement timelines incorporated solar capacity addition pipelines and grid interconnection queue depths as industry-specific inputs.
Commodity price volatility, cybersecurity certification delays, and renewable portfolio standard enforcement gaps are the dominant revision risks that could compress or extend forecast trajectories. Practitioners should monitor silicon wafer spot indices, IEC 62443 implementation timelines, and FERC interconnection rulemakings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Europe Energy Management Systems Market
Energy Management
Energy ESO Market
Energy Management
Heat Meter Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Thermostat Market
Energy Management
Brazil Energy Sector Market
Energy Management
Smart Power Technologies Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market